
 Global Motorcycle Supercharger Market | 2026-2036
Global Motorcycle Supercharger Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motorcycle Supercharger Market Outlook
Aftermarket distribution is fragmenting as online performance parts platforms and specialty dealer networks compete for rider loyalty. Kawasaki Heavy Industries dominates factory-installed supercharger systems through its Ninja H2 platform. Rotrex leverages its patented traction-drive technology to anchor the centrifugal segment. ProCharger competes aggressively in the V-twin cruiser aftermarket with bolt-on conversion kits.
A motorcycle supercharger is a forced-induction device that compresses intake air above atmospheric pressure, typically generating boost pressures between 0.5 and 2.0 bar to increase engine power density without proportional displacement growth. Centrifugal designs occupy the premium tier due to thermal efficiency and packaging advantages at high RPM, while electric superchargers represent the fastest-growing category as 48V architectures enable lag-free boost delivery. Racing applications sustain the highest margin pools, though touring and custom segments are expanding as reliability improves.
EPA tailpipe regulations in the United States, Euro 5 emission standards administered by ECHA-aligned bodies in Europe, and Japan's METI energy-efficiency directives collectively constrain aftermarket modifications while incentivizing OEM-integrated solutions. OEMs must navigate divergent homologation pathways across these jurisdictions, complicating platform standardization. Stakeholders should monitor evolving particulate-matter thresholds and electrification timelines that could redefine forced-induction relevance in motorcycle powertrains.
Market Dynamics
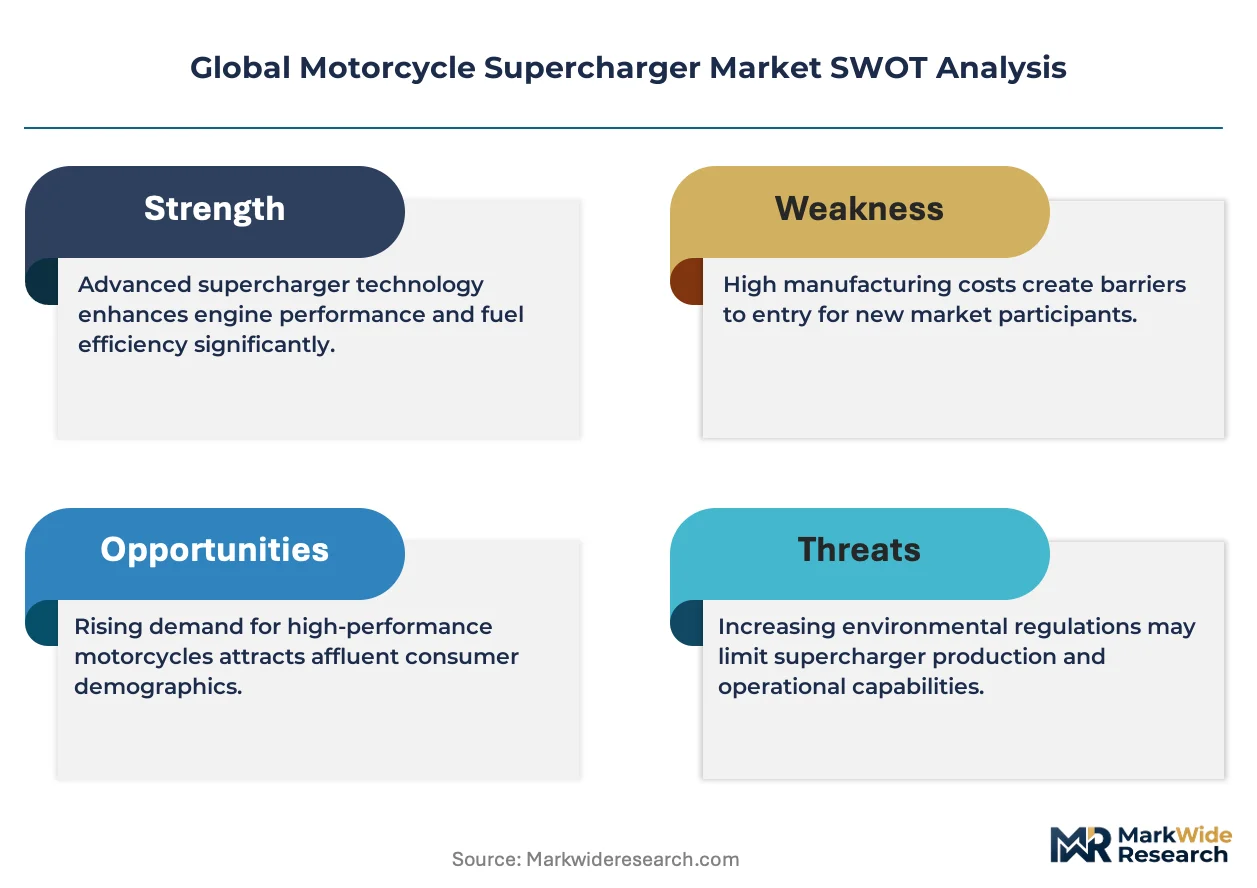
The motorcycle supercharger market pivots on the tension between EPA emissions mandates and rider demand for power density gains without displacement expansion. OEMs must engineer factory-integrated forced induction systems that satisfy tailpipe regulations while preserving aftermarket upgrade pathways.
Growth Catalysts
- Japan's METI energy-efficiency directives:Japanese regulators incentivize powertrain downsizing with forced induction, accelerating domestic OEM investment in compact supercharger architectures for sportbike platforms.
- 48V electrical architectures:Electric supercharger technology eliminates turbo lag through instant torque delivery, opening adoption in touring motorcycles where throttle response precision commands premium pricing.
- Track-day participation:Amateur racing circuits in Germany and the United States sustain demand for bolt-on centrifugal kits as riders seek competitive lap times without engine swaps.
Market Restraints
- Euro 5 particulate thresholds:ECHA-aligned enforcement constrains aftermarket ECU remapping and exhaust modifications, limiting supercharger kit compatibility with newer motorcycle generations.
- Titanium impeller supply:Aerospace-grade titanium sourcing concentrates with Japanese and Russian primary producers, exposing supercharger manufacturers to input cost volatility and export license uncertainty.
- Mechanical complexity trade-offs:Roots-type positive displacement systems impose packaging penalties and thermal management burdens that deter adoption in middleweight motorcycle segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced powertrain parts attract contract manufacturing investment, creating export hub capacity for centrifugal supercharger assemblies.
- Electrification convergence:Hybrid motorcycle architectures combining electric motors with forced-induction internal combustion engines enable torque-fill strategies that pure ICE or pure electric platforms cannot replicate.
- Direct-to-rider digital platforms:Specialized e-commerce marketplaces for performance parts bypass traditional dealer networks, capturing margin pools previously allocated to brick-and-mortar distribution.
Industry Challenges
- Thermofluid simulation expertise:Compressor map development and intercooler integration require specialized computational fluid dynamics talent scarce outside motorsport engineering consultancies.
- Homologation timeline compression:Divergent EPA, KBA, and Japan MLIT certification pathways force redundant testing cycles that delay product launches across North American, European, and Japanese markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motorcycle Supercharger Market |
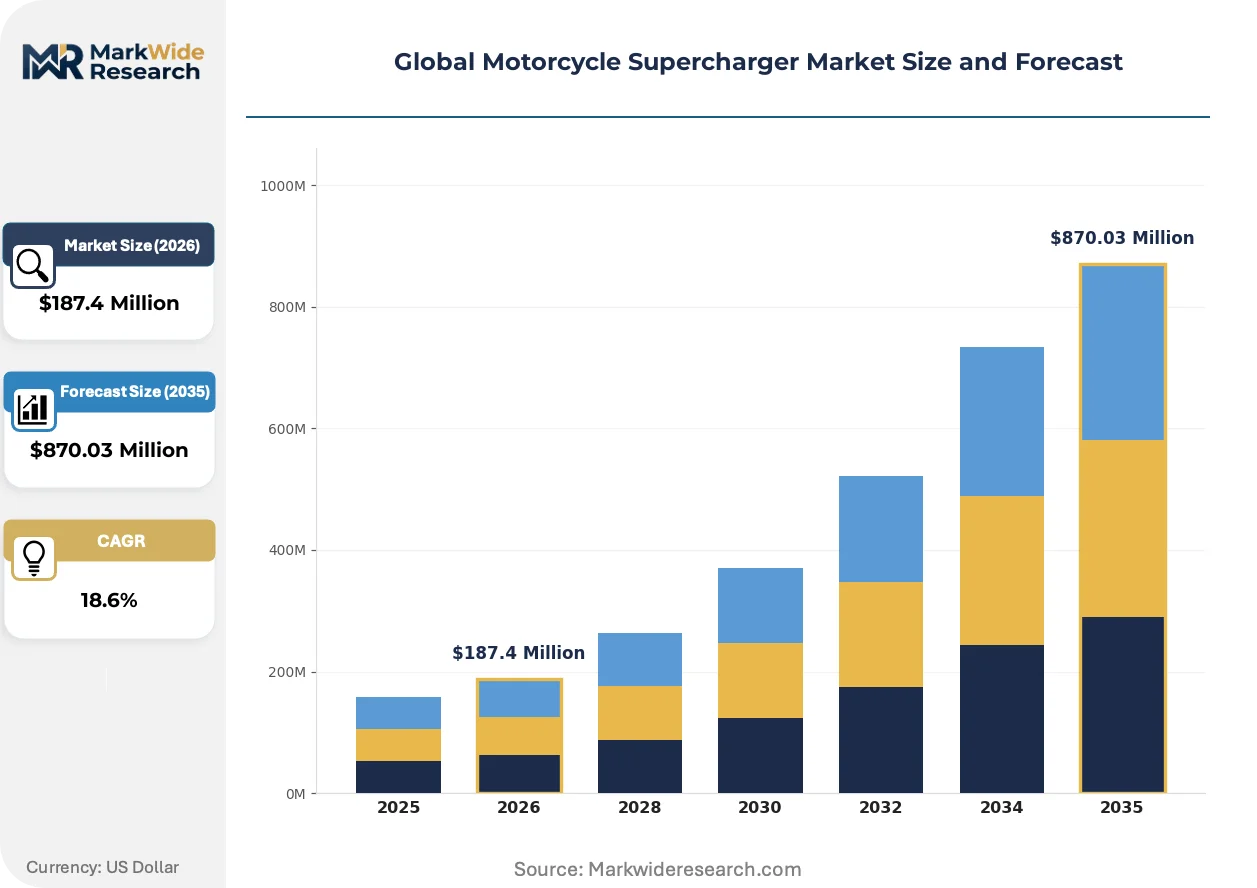
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Roots, Centrifugal, Twin-screw, Electric Application: Racing, Touring, Off-road, Custom End User: OEMs, Aftermarket, Recreational Riders, Commercial Users Installation: Factory-installed, Aftermarket Conversion, DIY Kits, Performance Upgrades |
| Companies Covered | Kawasaki Heavy Industries, Rotrex, ProCharger, Vortech Superchargers, TTS Performance, Kraftstoff, Whipple Superchargers, BorgWarner, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motorcycle Supercharger Market Strategic Shifts
Forced induction technology is fragmenting across three vectors: electric compressor architectures, regulatory-driven OEM integration, and direct-to-consumer distribution disruption. These shifts compress traditional aftermarket upgrade cycles while elevating factory-installed system sophistication.
Electric superchargers leveraging 48V electrical subsystems are rendering obsolete mechanical belt-driven designs in premium touring motorcycles. Kawasaki and Ducati engineering teams have accelerated development timelines for lag-free boost delivery systems. This transition compresses the addressable market for traditional centrifugal aftermarket kits in displacement segments above 1000cc.
EPA tailpipe regulations and Euro 5 standards administered by ECHA-aligned bodies are forcing OEMs toward factory-integrated supercharger solutions rather than aftermarket bolt-on pathways. Compliance costs for standalone kit manufacturers have risen substantially. The sportbike segment in Germany and California faces the strictest enforcement, driving Kawasaki Heavy Industries to expand Ninja H2 platform derivatives.
Chinese MIIT dual carbon goals and domestic NEV mandates are redirecting motorcycle R&D investment toward pure electric platforms, constraining forced induction development resources at indigenous manufacturers. Procurement patterns among Chinese OEMs now favor electric motor and battery suppliers over compressor technology licensors. This pivot is most visible in Chongqing and Zhejiang manufacturing clusters, where supercharger engineering headcount has stagnated.
Global Motorcycle Supercharger Market Segmentation
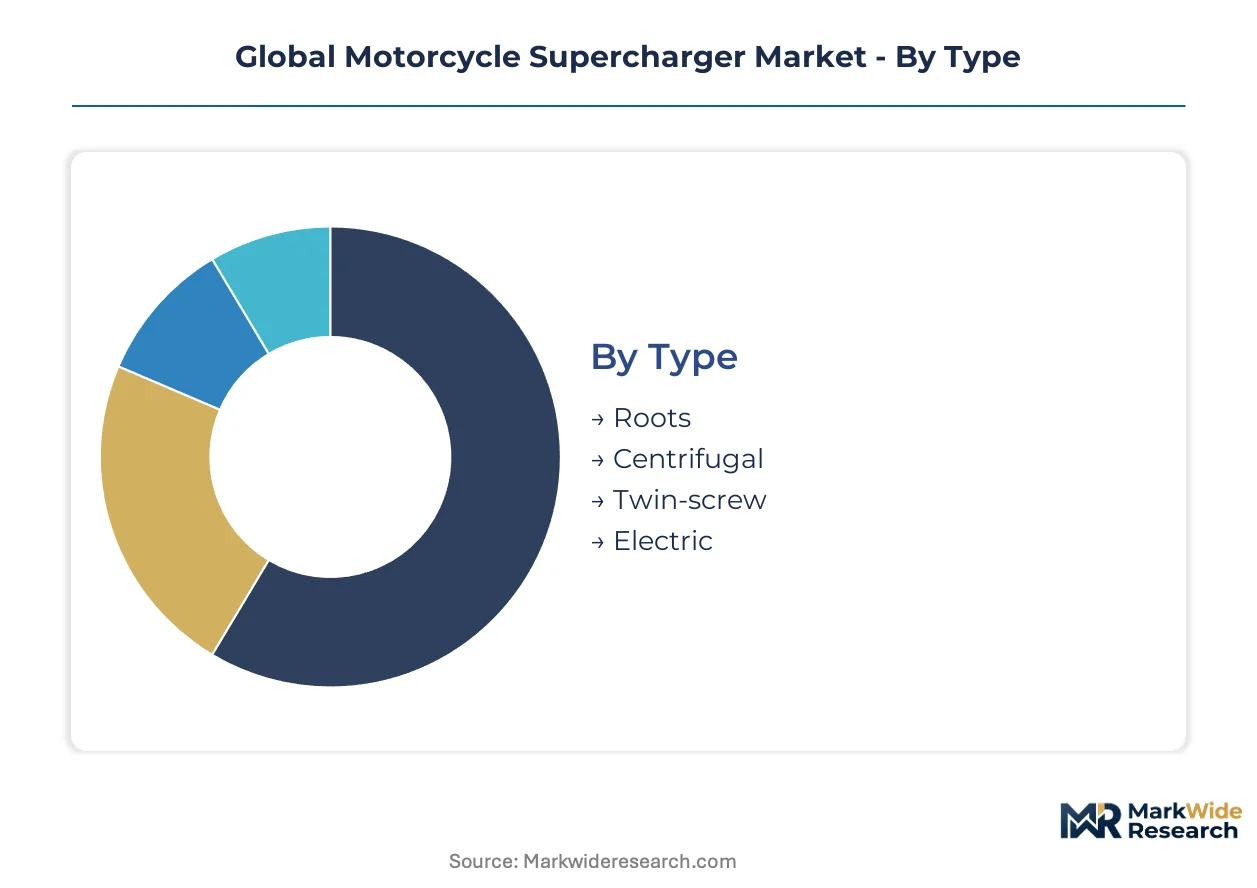
Forced induction architectures fragment across compressor technologies, rider use cases, and supply chain channels. Each dimension carries distinct margin profiles and regulatory exposure that shape investment prioritization for component suppliers and motorcycle OEMs.
Type:
Centrifugal designs command the longest development cycles due to precision impeller manufacturing, while electric superchargers iterate fastest as 48V subsystem suppliers proliferate.
- Centrifugal:Compressor wheels spun by engine-driven belts or gears achieve thermal efficiencies above 75% at high RPM. Kawasaki Heavy Industries deploys these exclusively on Ninja H2 platforms for track-day riders in Japan and Germany. EPA and Euro 5 compliance costs concentrate development resources at the OEM tier, squeezing aftermarket kit margins.
- Electric:Motor-driven compressors eliminate mechanical lag through instant torque delivery from 48V architectures. Ducati engineering teams target touring motorcycles where throttle response precision sustains premium pricing. METI efficiency directives in Japan accelerate domestic patent filings for compact electric blower designs.
- Roots:Positive displacement pumps deliver immediate low-RPM boost but impose packaging penalties in middleweight frames.
- Twin-screw:Intermeshing rotors balance efficiency and response for custom V-twin builds in the United States.
Centrifugal systems anchor the volume base while electric superchargers gain share at the steepest rate.
Application:
Margin concentration follows risk tolerance, with racing applications commanding the highest per-unit pricing and touring segments scaling through fleet partnerships.
- Racing:Amateur circuits in Germany and the United States sustain demand for bolt-on forced induction kits. Riders seeking competitive lap times without engine swaps drive recurring purchases of intercooler upgrades and pulley modifications. KBA technical inspections in Germany enforce strict homologation compliance that filters out low-quality suppliers.
- Touring:Long-distance motorcycles prioritize reliability and thermal management over peak output. Electric supercharger architectures eliminate belt maintenance concerns for rental fleets and police motorcycle procurement programs in Japan and California.
- Off-road:Dust sealing and vibration tolerance constrain supercharger durability in desert racing and enduro applications.
- Custom:Harley-Davidson and Indian Motorcycle owners in the United States commission bespoke forced induction builds through specialty shops.
Touring applications generate the most stable revenue streams while racing commands the highest per-unit margins.
End User:
Procurement authority separates factory-integrated decisions from rider-initiated modifications, with distinct regulatory gateways governing each pathway.
- OEMs:Kawasaki Heavy Industries, Ducati, and BMW Motorrad integrate superchargers at the design stage to satisfy Euro 5 and EPA tailpipe mandates. Factory calibration preserves warranty coverage and emissions compliance. Homologation investments by Japan MLIT, KBA, and EPA create barriers that exclude aftermarket kit competitors from new-vehicle supply chains.
- Aftermarket:Specialty distributors and online performance platforms serve riders seeking power upgrades outside dealer networks. ProCharger and Rotrex compete for V-twin cruiser conversions in the United States through dealer-trained installation programs.
- Recreational Riders:Track-day participants and club racers form price-sensitive demand concentrated in Germany and California.
- Commercial Users:Police and rental fleets in Japan evaluate total cost of ownership including maintenance intervals.
OEMs dominate value capture while aftermarket channels expand fastest through direct-to-rider digital platforms.
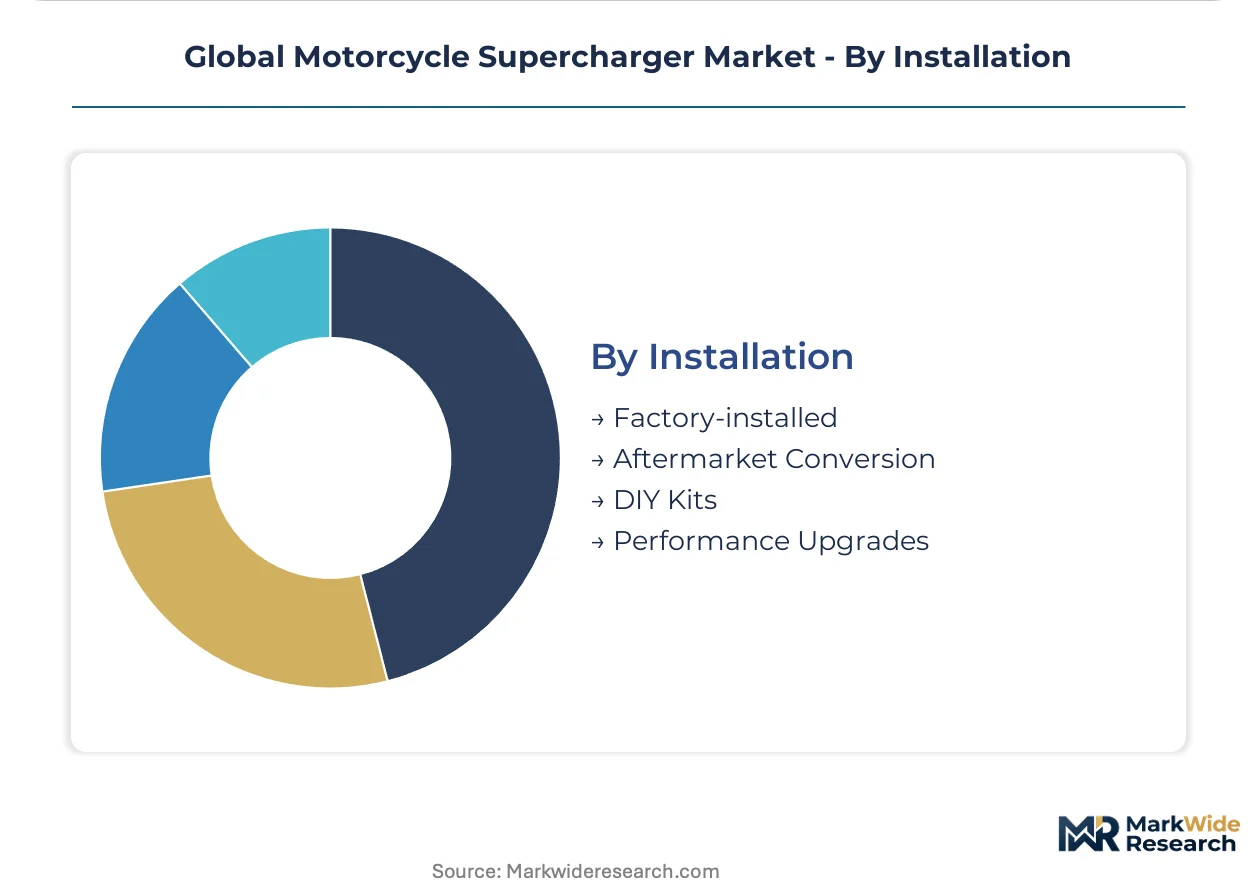
Installation:
Technical complexity and liability exposure stratify the installation landscape from factory automation to owner-operated garage builds.
- Factory-installed:Assembly line integration enables precision intercooler packaging and ECU calibration. Kawasaki's Ninja H2 production in Japan leverages aerospace-grade titanium impeller sourcing through domestic supply chains. EPA certification and Japan MLIT homologation lock in design specifications years before production.
- Aftermarket Conversion:Dealer-installed kits preserve some warranty coverage through manufacturer-approved programs. Rotrex traction-drive systems dominate this tier in European markets with KBA inspection compliance.
- DIY Kits:Enthusiast-installed packages require mechanical expertise and custom tuning. Online forums and video tutorials reduce support burdens for suppliers.
- Performance Upgrades:Staged enhancement programs allow incremental investment in pulley swaps, intercoolers, and fuel system modifications.
Factory-installed systems capture the premium tier while aftermarket conversions scale fastest through certified dealer networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama's automotive logistics infrastructure underwrites Japan's dominance in high-performance motorcycle engineering, while Germany's KBA homologation network and the United States' EPA regional enforcement offices shape compliance pathways across three continents.
Japan
Kawasaki Heavy Industries anchors factory-installed supercharger production through its Ninja H2 platform, serving track-day riders and domestic tuning houses. METI energy-efficiency directives incentivize powertrain downsizing with forced induction, accelerating patent filings for compact blower architectures. Tokyo and Osaka metropolitan clusters concentrate aerospace-grade titanium impeller sourcing through domestic supply chains.
Germany
Amateur racing circuits sustain demand for bolt-on centrifugal kits as riders seek competitive lap times without engine swaps. KBA technical inspections enforce strict homologation compliance that filters out low-quality aftermarket suppliers. Bavaria's automotive engineering corridor hosts specialized motorsport consultancies developing thermofluid simulation capabilities for compressor map development.
United States
V-twin cruiser owners commission bespoke forced induction builds through specialty shops in California and the Midwest. EPA tailpipe regulations constrain aftermarket ECU remapping and exhaust modifications, limiting supercharger kit compatibility with newer motorcycle generations. California's Air Resources Board maintains the strictest regional enforcement, driving OEMs toward factory-integrated solutions.
India
Production-linked incentives for advanced powertrain components attract contract manufacturing investment in centrifugal supercharger assemblies. The country's national automotive regulator aligns component certification with export market requirements. Maharashtra and Gujarat manufacturing clusters develop export hub capacity for compressor wheel production serving European and North American aftermarket channels.
China
MIIT dual carbon goals and domestic NEV mandates redirect motorcycle R&D investment toward pure electric platforms, constraining forced induction development resources. The national standardization administration favors electric motor and battery suppliers over compressor technology licensors. Chongqing and Zhejiang manufacturing clusters have stagnated supercharger engineering headcount as procurement patterns shift.
Global Motorcycle Supercharger Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in impeller manufacturing and traction-drive technology. The vendor base organizes around three archetypes: Japanese heavy industrial conglomerates with factory-installed capabilities, Danish and American centrifugal specialists serving aftermarket conversions, and diversified automotive suppliers with transferable forced-induction expertise. Strategic moves concentrate on technology licensing agreements and geographic expansion into Indian contract manufacturing.
Within the platform-integrator tier, Kawasaki Heavy Industries exemplifies the factory-installed archetype through its Ninja H2 production lineage. Among centrifugal specialists, Rotrex and ProCharger occupy positions in European and American aftermarket channels respectively, with Rotrex representing traction-drive technology and ProCharger anchoring V-twin cruiser conversions. BorgWarner sits within the diversified automotive supplier category, leveraging transferable forced-induction expertise from passenger car applications.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries |
| Rotrex |
| ProCharger |
| Vortech Superchargers |
| TTS Performance |
| Kraftstoff |
| Whipple Superchargers |
| BorgWarner |
| Eaton Corporation |
| Others |
Value Chain & Pricing Dynamics
Aerospace-grade titanium impeller sourcing concentrates with Japanese and Russian primary producers, anchoring margin capture at the precision-manufacturing tier while downstream pricing power fragments across OEM factory installations and aftermarket kit distributors. This upstream concentration forces centrifugal supercharger manufacturers to absorb input cost volatility or pass through to buyers in segmented tiers.
Pricing Analysis
Volume-discount tiering structures separate factory-integrated OEM contracts from small-batch aftermarket conversions and individual DIY kit purchases. Price differentiation rests on certification grade—EPA and KBA homologation tiers command substantial premiums over uncertified racing-only configurations—and vertical integration depth, with in-house impeller production insulating Kawasaki from supplier margin extraction. Cost compression in the DIY segment is intensifying because online performance platforms bypass traditional dealer markups. Recreational riders and club racers exhibit the highest price sensitivity, while police and rental fleets prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from Japanese and German OEMs strain working capital for smaller centrifugal kit manufacturers, forcing reliance on supply-chain finance facilities. Component manufacturing draws from Japan, Germany, and India, with precision impeller machining concentrated in Osaka and Tokyo metropolitan clusters, traction-drive assembly in Denmark, and contract production of compressor housings scaling in Maharashtra and Gujarat. Single-source vulnerability persists in aerospace-grade titanium feedstock, where export license uncertainty from Russian suppliers creates input disruption risk. Distribution runs through certified dealer networks for factory-installed systems, direct-to-rider digital platforms for aftermarket kits, and specialty performance shops for custom V-twin builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forced induction penetration in middleweight motorcycle segments remains below ten percent, creating substantial runway as 48V architectures mature and METI efficiency directives accelerate OEM investment cycles.
For Market Incumbents: Build regulatory-certification moats by expanding EPA and KBA homologation coverage ahead of Euro 6 particulate thresholds, which will filter out aftermarket competitors unable to fund redundant testing cycles. Deepen backward integration into titanium impeller production to neutralize Russian supply disruption risk. Secure channel control through exclusive dealer-trained installation programs that lock out Rotrex and ProCharger from OEM service networks. For New Entrants and Emerging Players: India's underpenetrated aftermarket offers the most accessible white-space target, where PLI scheme benefits reduce capital barriers for centrifugal assembly operations and domestic sportbike ownership is accelerating. Target touring motorcycle electric supercharger retrofits as the most penetrable application, where 48V subsystem availability lags rider demand for lag-free boost delivery. Pursue direct-to-rider digital platforms as the primary go-to-market angle, capturing margin pools previously allocated to brick-and-mortar distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component specialists possessing transferable forced-induction expertise from passenger car turbocharger operations. Long-term viability hinges on electrification convergence strategies that position hybrid architectures as bridge technologies through the next decade. Monitor patent filing velocity for compact electric blower designs at Japan METI as the signal for OEM platform commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Electric Supercharger Platform Development | Ducati and Kawasaki engineering teams target touring segments where instant torque delivery commands premium pricing. |
| Indian Contract Manufacturing Scale-Up | Maharashtra and Gujarat clusters build export hub capacity serving European and North American aftermarket channels. |
| Direct-to-Rider Digital Platform Launch | Specialized e-commerce marketplaces bypass dealer networks to capture margin pools in bolt-on centrifugal kit sales. |
| Titanium Impeller Backward Integration | In-house aerospace-grade machining neutralizes Russian supply disruption risk and export license uncertainty. |
| Hybrid Architecture Torque-Fill Integration | Electric motor and forced-induction ICE combinations enable performance strategies pure platforms cannot replicate. |
Study Parameters
A spread of perspectives from OEM platform engineers, aftermarket distributor procurement leads, racing team technical directors, and titanium alloy suppliers converged on the working assumptions driving compressor map development and intercooler integration specifications. Primary interviews with these stakeholders combined with secondary validation against EPA certification filings, KBA technical inspection protocols, Japan MLIT homologation records, and METI patent databases. Bottom-up triangulation across component supplier revenue disclosures and top-down demand modeling from motorcycle registration data established volume and value estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning compressor technology type, rider application, procurement authority, and installation complexity. CAGRs derived from fitted growth curves incorporating 48V electrical architecture adoption rates, track-day participation trends in Germany and California, and PLI scheme manufacturing capacity buildout in India. Industry-specific forecast inputs included thermofluid simulation talent scarcity and divergent homologation timeline compression effects.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese pure-electric motorcycle OEMs or accelerated Euro 6 particulate threshold advancement would shift outcomes substantially. Macroeconomic deviation in titanium commodity markets, regulatory harmonization failures across EPA-KBA-MLIT jurisdictions, or breakthroughs in solid-state battery energy density would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market