
 Motorbike Carburetor Market | 2026-2036
Motorbike Carburetor Market Size, Share, and Industry Trends Forecast 2026-2036
Motorbike Carburetor Market Insights
Aftermarket rebuilders and rural independent mechanics are redrawing demand patterns away from OEM-first procurement in emerging economies. Keihin Corporation leverages its Japanese manufacturing pedigree to dominate premium racing carburetor supply. Mikuni Corporation sustains strong positions in Southeast Asian OEM channels through localized production partnerships. Dell'Orto anchors European heritage motorcycle restoration demand with specialized slide-carburetor configurations.
A motorbike carburetor is a mechanical fuel-air mixing device that meters gasoline via a venturi throat, float chamber, and calibrated jets to match engine load conditions across throttle positions. Its primary commercial purpose is delivering combustible mixtures to internal combustion engines where electronic fuel injection remains cost-prohibitive. The 125cc engine capacity segment leads unit volume across South Asian commuter markets where aluminum-bodied carburetors balance thermal conductivity against manufacturing cost. Aftermarket application channels capture expanding margin pools as fleet aging outpaces new motorcycle sales in price-sensitive regions. Racing application demand concentrates in composite-material carburetors where weight reduction justifies premium positioning.
India's CEA and BIS enforce BS-VI emission thresholds that restrict new carburetor-equipped motorcycle registrations above 125cc, while EPA and NHTSA standards in the United States preserve vintage vehicle exemptions sustaining restoration demand. Japan's METI coordinates JIS standards that govern carburetor precision tolerances for domestic OEM supply. Stakeholders must monitor regulatory phase-out timelines against aftermarket inventory cycles to calibrate production commitments between declining OEM fitment and sustained replacement demand.
Market Dynamics
The motorbike carburetor market faces structural compression from India's BS-VI emission norms, which restrict new carburetor fitment on motorcycles above 125cc while simultaneously expanding aftermarket replacement demand across aging Southeast Asian fleets.
Growth Catalysts
- Aftermarket channel expansion:Indonesia's urban commuter corridors and India's tier-2 manufacturing clusters sustain robust replacement volumes as two-wheeler fleet aging outpaces new sales in cost-sensitive regions.
- BS-VI regulatory carve-out:India's CEA and BIS emission thresholds preserve niche demand for carburetors in sub-125cc commuter motorcycles where fuel injection remains economically prohibitive for OEMs.
- Heritage restoration demand:European and North American collector markets sustain premium slide-carburetor procurement for vintage motorcycle refurbishment, insulating specialized suppliers from volume decline.
Market Restraints
- Aluminum input cost volatility:Primary aluminum price fluctuations squeeze margin structures for aluminum-bodied carburetor manufacturers serving price-sensitive OEM procurement in South Asia.
- Fuel injection substitution:Electronic fuel injection systems displace mechanical carburetors in mid-capacity motorcycles above 150cc, compressing addressable market scope in premium segments.
- Production concentration risk:Carburetor manufacturing clusters in Thailand and Vietnam face logistics disruption exposure from concentrated Southeast Asian supply base dependencies.
Strategic Opportunities
- Racing application premiumization:Composite-material carburetor demand concentrates in competitive motorsport segments where weight reduction justifies three-tier pricing stratification across performance tiers.
- Indonesian aftermarket penetration:Rural independent mechanics and rebuilders in Java and Sumatra absorb rising replacement volumes through informal distribution networks bypassing OEM channels.
- Japan METI precision standards:JIS tolerance compliance creates certification-driven preference shifts among domestic OEMs seeking supply base differentiation against lower-cost regional competitors.
Industry Challenges
- Venturi machining skill scarcity:Precision casting and flow-bench calibration expertise concentrates among aging technician cohorts in Japanese and Italian manufacturing bases, constraining capacity expansion.
- BS-VI compliance timeline compression:India's rapid regulatory phase-out forces inventory cycle recalibration between declining OEM fitment and sustained aftermarket replacement demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorbike Carburetor Market |
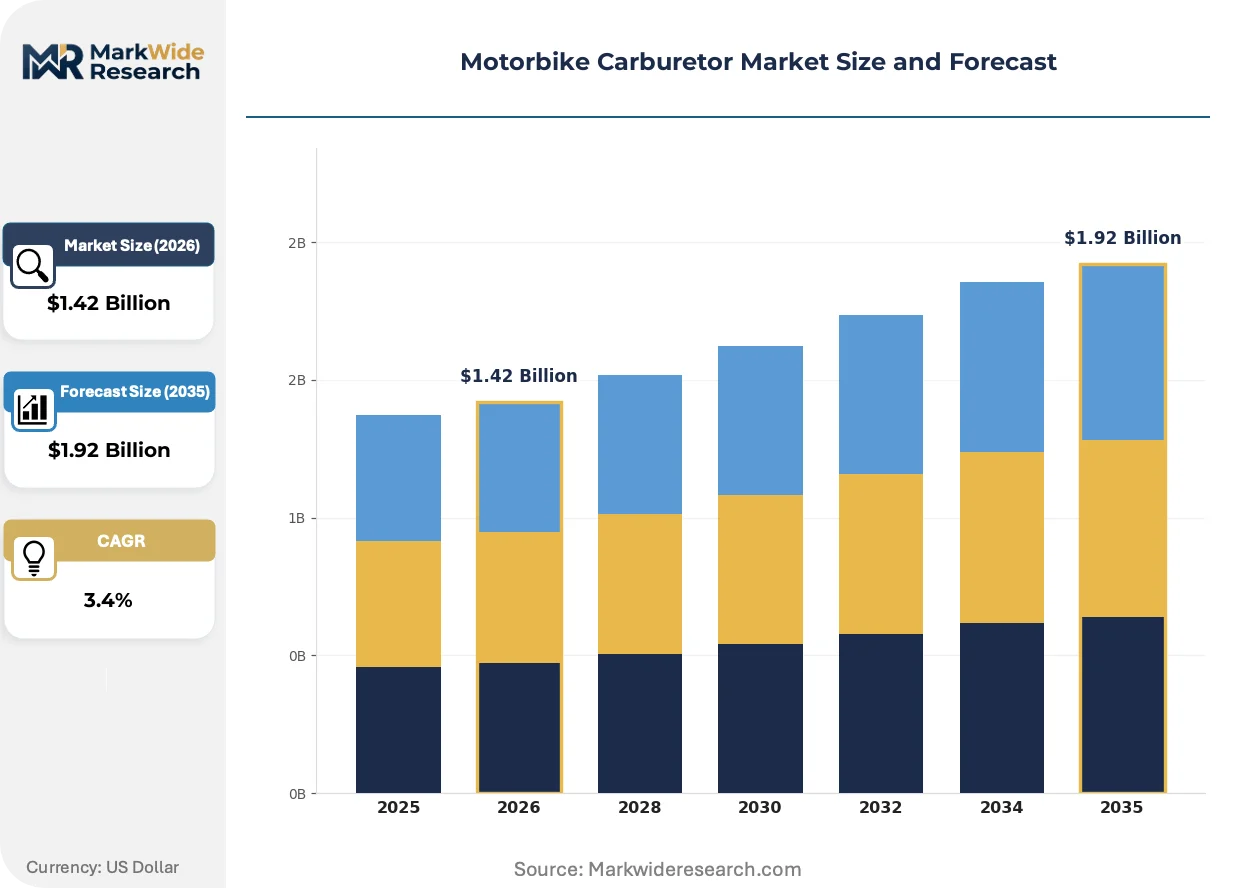
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cruiser, Sportbike, Touring, Dirt Bike Engine Capacity: 125cc, 250cc, 500cc, 1000cc Material: Aluminum, Plastic, Cast Iron, Composite Application: OEM, Aftermarket, Racing, Maintenance |
| Companies Covered | Dell'Orto, Holley Performance Products, Keihin Corporation, Ruixing, Edelbrock Corporation, Mikuni Corporation, Zama Group, Fuding Huayi, Walbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorbike Carburetor Market Trends and Innovations
Active innovation in the motorbike carburetor market centers on material substitution for weight reduction, regulatory compliance architectures, and channel restructuring that redistributes margin capture away from traditional OEM supply hierarchies.
Composite-material carburetor construction is fragmenting competitive positioning in racing and high-performance segments. Carbon-fiber reinforced polymer venturi housings reduce unit weight by substantial margins compared to aluminum castings. Professional racing teams and premium aftermarket buyers in Italy and Japan absorb these components despite manufacturing cost premiums. The technology is fragmenting supplier tiers into precision composite specialists versus legacy aluminum foundries.
India's CEA enforcement of BS-VI emission thresholds is reshaping product development priorities for domestic market participants. The regulation mandates evaporative emission controls and precise air-fuel ratio management that challenge conventional float-chamber designs. Sub-125cc commuter motorcycle OEMs respond with calibrated jetting modifications and sealed fuel systems that delay fuel injection adoption in lowest-cost segments.
Mechanics and rebuilders across Southeast Asia are consolidating procurement influence through informal parts networks that bypass authorized distribution. Indonesia's independent repair ecosystem sources replacement carburetors through cross-border traders and remanufacturing shops in Malaysia and Thailand. This channel disintermediation compresses OEM margin retention while expanding addressable volume for non-branded aftermarket suppliers.
Motorbike Carburetor Market Segmentation
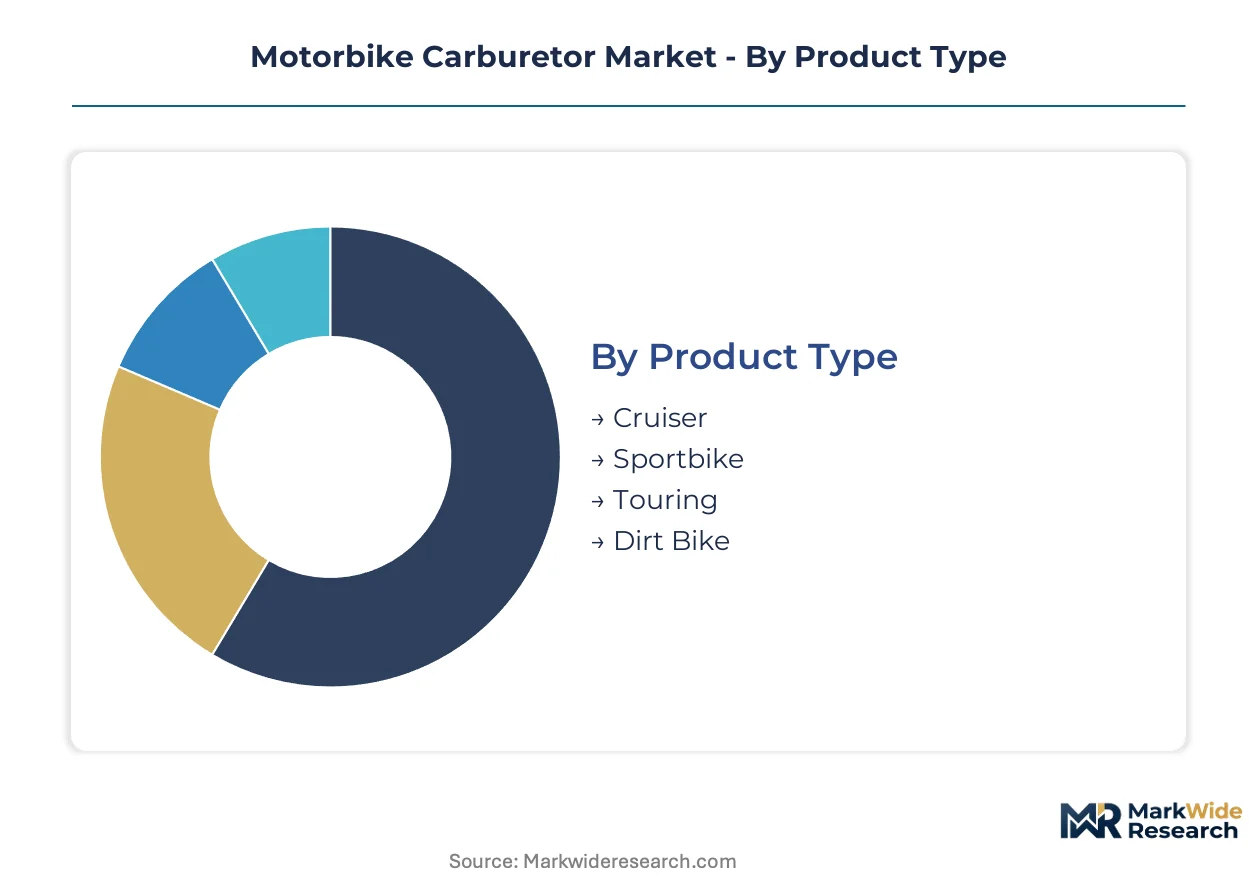
Carburetor market segmentation reveals divergent margin architectures across motorcycle categories and supply channels. Product type and engine capacity determine manufacturing complexity, while material selection and application channel dictate pricing power and customer loyalty patterns.
Product Type:
Margin pools concentrate in sportbike and dirt bike segments where performance-tuned carburetion commands technical premiums over utilitarian commuter applications.
- Sportbike:Slide-type carburetors with accelerator pumps and multiple venturi stages deliver precise fuel metering under rapid throttle transitions. Keihin and Mikuni capture premium positioning in Japanese and Italian sportbike OEM channels where 600cc-1000cc displacement brackets sustain mechanical carburetor demand despite fuel injection encroachment.
- Dirt Bike:Off-road motorcycles employ gravity-fed float chambers with enhanced vibration resistance and debris-tolerant air filtration. Thailand's manufacturing clusters supply Southeast Asian trail and enduro markets where carburetors persist due to field-repairability advantages over electronic systems in remote terrain.
- Cruiser:Large-bore venturi designs accommodate V-twin torque characteristics with simplified maintenance access.
- Touring:Dual-carburetor configurations for multi-cylinder highway motorcycles face accelerating displacement by fuel injection in premium touring segments.
The dominant share belongs to Sportbike, while Dirt Bike is closing the gap fastest.
Engine Capacity:
Volume-weighted returns favor smaller displacement brackets where unit economics sustain carburetor manufacturing against fuel injection cost curves.
- 125cc:Single-barrel float carburetors with fixed main jets dominate Indian and Indonesian commuter production. BS-VI emission thresholds restrict this segment to sub-125cc fitment, concentrating India's OEM procurement in Hero MotoCorp and Bajaj Auto supply chains where cost-per-unit targets resist electronic fuel injection adoption.
- 250cc:Mid-capacity motorcycles employ CV (constant velocity) carburetors with vacuum-operated slides for smoother power delivery. Vietnam's export-oriented assembly plants source these components for regional distribution across ASEAN markets where 200cc-250cc represents the practical ceiling for carburetor-equipped new motorcycles.
- 500cc:Twin-cylinder applications increasingly transition to fuel injection, compressing addressable scope to heritage models and price-sensitive markets.
- 1000cc:Large-displacement sport and touring motorcycles retain carburetors only in vintage restoration and racing exemption categories.
The dominant share belongs to 125cc, though 250cc is expanding most quickly in Vietnam and Thailand export channels.
Material:
Raw input cost structures and thermal management requirements fragment competitive positioning across foundry-dependent and precision-machining supply bases.
- Aluminum:Die-cast aluminum bodies balance thermal conductivity with weight reduction for mass-market OEM supply. Primary aluminum price volatility in the London Metal Exchange squeezes margin structures for Indian and Thai manufacturers serving price-sensitive procurement.
- Composite:Carbon-fiber reinforced polymer venturi housings reduce unit weight substantially for racing applications. Italian and Japanese motorsport specialists absorb manufacturing cost premiums where FIM competition rules permit carburetor configurations.
- Plastic:Injection-molded polymer components serve float chambers and air horns in lowest-cost commuter segments.
- Cast Iron:Obsolete for new production, cast iron bodies persist in vintage restoration supply chains for pre-1980s motorcycle refurbishment.
Aluminum retains the dominant position, while Composite is gaining share fastest in premium racing procurement.
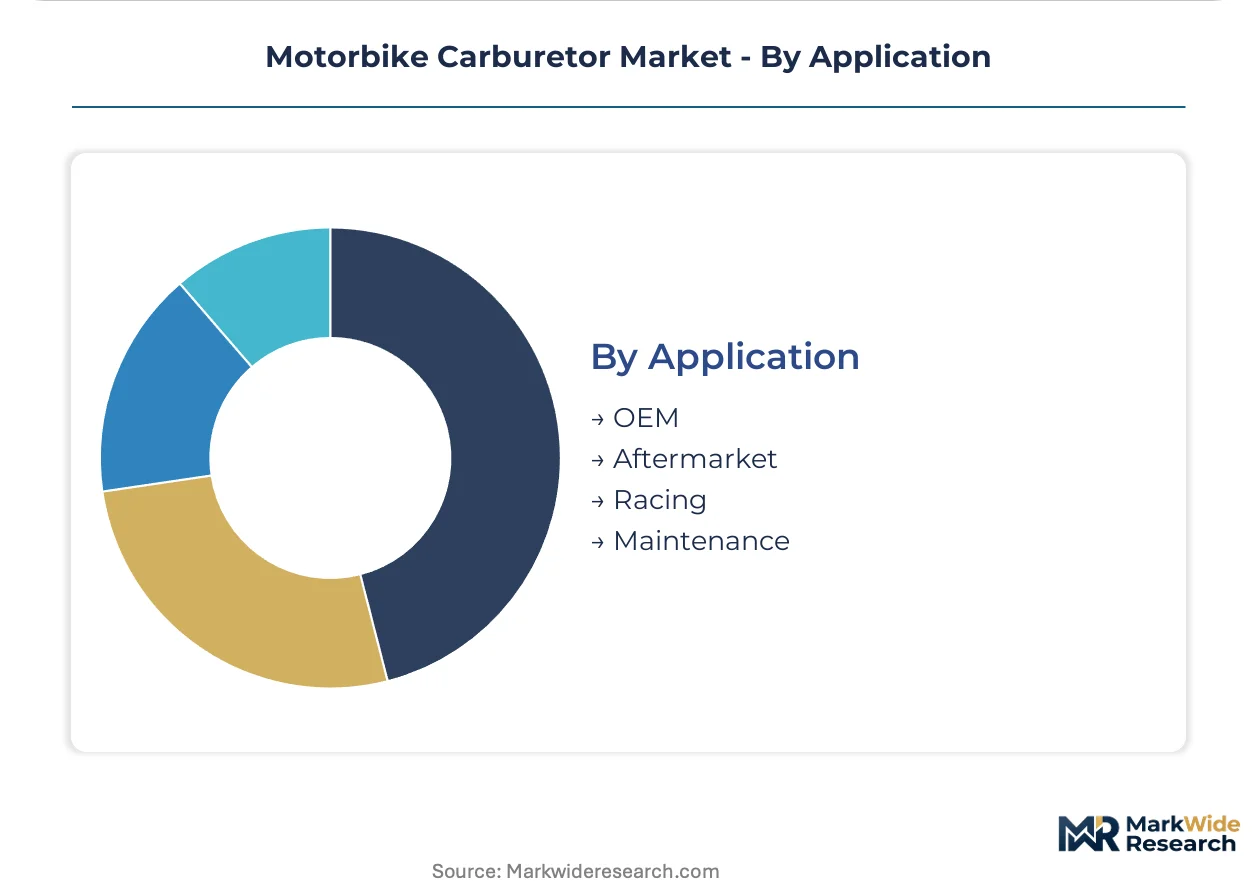
Application:
Channel control and inventory velocity determine working capital intensity, with aftermarket rebuilders capturing expanding margin pools as fleet aging accelerates replacement cycles.
- Aftermarket:Independent mechanics and rural rebuilders across Java and Sumatra source replacement carburetors through informal cross-border networks. Indonesian distributors bypass authorized channels to supply aging Honda and Yamaha fleets where OEM parts pricing exceeds mechanic labor economics.
- Racing:FIM-sanctioned competition categories sustain demand for precision-tuned slide carburetors with tunable needle profiles and interchangeable venturi inserts. Japanese Superbike and Moto2 feeder series maintain technical partnerships with Keihin for homologated racing specifications.
- OEM:Original equipment fitment faces structural compression from India's BS-VI emission norms above 125cc displacement thresholds.
- Maintenance:Service-channel replacement concentrates in Southeast Asian urban corridors where fleet density supports dedicated carburetor rebuilding shops.
The dominant share belongs to Aftermarket, while Racing is climbing the fastest in absolute margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tanjung Priok port complex in Jakarta underwrites Indonesia's dominance in Southeast Asian two-wheeler distribution, channeling replacement carburetor volumes through Java's dense independent mechanic networks. India's JNPT and Chennai port corridors handle aluminum casting imports that feed Tamil Nadu and Maharashtra manufacturing clusters. Thailand's Laem Chabang deep-water terminal anchors ASEAN export assembly for Vietnamese and Indonesian re-export markets.
Indonesia
Urban commuter corridors in Jakarta and Surabaya sustain robust aftermarket carburetor demand as Honda and Yamaha fleet aging accelerates replacement cycles. The country's Ministry of Industry oversees domestic content requirements that protect local assembly operations. Java's independent mechanic ecosystems in Bandung and Yogyakarta source cross-border remanufactured units through informal Malaysian trader networks.
India
BS-VI emission thresholds enforced by CEA and BIS restrict new carburetor fitment above 125cc while preserving sub-125cc commuter procurement for Hero MotoCorp and Bajaj Auto supply chains. Tamil Nadu's Coimbatore and Tiruppur clusters concentrate aluminum die-casting capacity serving cost-sensitive OEM targets. Tier-2 manufacturing hubs in Pune and Ahmedabad absorb rising aftermarket volumes as rural fleet extension outpaces new motorcycle sales.
Thailand
Bangkok's manufacturing belt supplies ASEAN trail and enduro markets where carburetors persist due to field-repairability advantages in remote terrain. The country's Industrial Estate Authority of Thailand coordinates bonded-zone incentives for export-oriented motorcycle component fabrication. Rayong and Chonburi industrial zones host precision machining operations serving Vietnamese assembly re-export demand.
Vietnam
Hanoi and Ho Chi Minh City assembly plants source 200cc-250cc CV carburetors for regional ASEAN distribution where this displacement bracket represents the practical ceiling for mechanical fuel metering. The Ministry of Industry and Trade administers import tariff structures that favor regional supply base integration. Binh Duong and Dong Nai provinces concentrate export-oriented motorcycle manufacturing clusters absorbing Thai and Chinese component inflows.
Japan
METI-coordinated JIS precision tolerance standards govern domestic OEM supply preferences, creating certification-driven differentiation against lower-cost regional competitors. Kanto and Chubu manufacturing corridors retain specialized venturi machining expertise among aging technician cohorts. Osaka-based racing carburetor specialists maintain technical partnerships with FIM-sanctioned competition categories.
Motorbike Carburetor Market Competitive Landscape
Listed leaders compete with private specialists across precision tolerance certification and aftermarket channel control. The vendor base stratifies into three tiers: Japanese precision manufacturers commanding premium OEM supply, Southeast Asian volume fabricators serving cost-sensitive procurement, and European heritage specialists capturing restoration margin pools. Consolidation pressures concentrate among aluminum foundries facing input cost volatility, while composite specialists fragment racing segment positioning. Dominant competitive moves include backward integration into precision casting operations and geographic expansion through localized production partnerships.
Within the precision-tier segment, Keihin Corporation and Mikuni Corporation occupy positions defined by JIS certification compliance and domestic OEM supply relationships. Dell'Orto anchors European heritage restoration demand through specialized slide-carburetor configurations. Among volume-oriented fabricators, Ruixing and Fuding Huayi represent Chinese manufacturing archetypes serving price-sensitive ASEAN aftermarket channels.
| Leading Market Players |
|---|
| Dell'Orto |
| Holley Performance Products |
| Keihin Corporation |
| Ruixing |
| Edelbrock Corporation |
| Mikuni Corporation |
| Zama Group |
| Fuding Huayi |
| Walbro |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Thai aluminum foundries directly shapes price floors across Southeast Asian carburetor supply, compressing margins for Indian OEM procurement while sustaining premium tiers in Japanese precision manufacturing. Scale advantages in die-casting operations concentrate bargaining power among volume fabricators serving Indonesian aftermarket channels, forcing tier-2 suppliers into cost-absorbing positions.
Pricing Analysis
Volume-discount tiering structures separate Keihin and Mikuni premium racing specifications from standard aluminum commuter units and economy-grade plastic-bodied alternatives for Indonesian rebuilders. Price differentiation rests on JIS certification compliance and composite-material weight reduction rather than brand premium alone. Cost compression in aluminum foundry tiers is intensifying because London Metal Exchange volatility feeds directly into Hero MotoCorp and Bajaj Auto procurement negotiations. Aftermarket rebuilders across Java exhibit highest price sensitivity, while FIM-sanctioned racing teams absorb three-tier pricing premiums for homologated specifications.
Supply Chain Analysis
Thailand and Vietnam anchor precision machining and aluminum die-casting for ASEAN carburetor assembly, while India concentrates casting capacity in Tamil Nadu and Maharashtra for domestic OEM supply. Raw material flows draw from primary aluminum smelters, carbon-fiber composite feedstock, and injection-molded polymer resins. Single-source vulnerability concentrates in Japanese venturi machining expertise where aging technician cohorts constrain capacity expansion. Distribution runs through Tanjung Priok port corridors for Indonesian aftermarket absorption and Laem Chabang bonded zones for Vietnamese re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is fragmenting traditional OEM supply hierarchies as Indonesian independent mechanic networks consolidate procurement influence through cross-border digital coordination. Interoperability between remanufacturing shops and informal traders is redrawing margin capture away from authorized distribution channels.
For Market Incumbents: Consolidate backward integration into precision casting operations in Thailand and Vietnam to defend against aluminum input cost volatility. Secure JIS certification renewal timelines ahead of METI compliance reviews. Channel control through exclusive distributor agreements in Java and Sumatra remains essential as informal networks erode OEM margin retention.
For New Entrants and Emerging Players: Lead with composite-material specialization for racing and heritage restoration segments where technical premiums sustain independent positioning. Target Indonesian aftermarket penetration through direct mechanic network relationships bypassing established distributor tiers. Go-to-market execution should emphasize field-repairability advantages and cross-border logistics partnerships with Malaysian traders.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-tolerance specialists with captive venturi machining expertise as fuel injection substitution compresses volume-scope manufacturers. Long-term viability hinges on aftermarket replacement cycle duration against fleet aging trajectories. Acquisition targets should demonstrate JIS certification compliance or established Indonesian channel relationships. The signal to watch is BS-VI regulatory enforcement intensity and sub-125cc commuter motorcycle production commitments by Hero MotoCorp and Bajaj Auto.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive aluminum die-casting capacity insulates Thai manufacturers from London Metal Exchange volatility. |
| JIS Certification Investment | METI tolerance compliance creates preference differentiation against lower-cost ASEAN competitors. |
| Indonesian Aftermarket Channel Expansion | Direct mechanic network relationships in Java bypass authorized distribution margin compression. |
| Composite-Material Product Line Development | Carbon-fiber reinforced polymer housings capture FIM racing segment premium positioning. |
| Cross-Border Logistics Partnership | Malaysian trader network integration accelerates Indonesian replacement cycle absorption. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association publications. Primary interviews engaged carburetor manufacturing executives, OEM procurement managers at Hero MotoCorp and Bajaj Auto, Indonesian independent mechanic network operators, and FIM technical partnership coordinators. Secondary validation drew from BIS and CEA emission standard documentation, METI JIS specification databases, and ASEAN automotive production statistics. Bottom-up unit volume estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include product type, engine capacity bracket, material composition, and application channel across the projection horizon. Analytical frameworks incorporated displacement-tier substitution curves, aftermarket replacement velocity by fleet age cohort, and regional regulatory phase-out timelines. CAGRs derived from regression analysis of historical production data against emission norm implementation schedules and aluminum price elasticity coefficients for cost-sensitive procurement tiers.
The analysis sits within stated boundaries; outcomes outside sustained BS-VI enforcement intensity, aluminum price stability, or Indonesian fleet aging trajectories would require recalibration. Forecasts reflect documented assumptions regarding fuel injection cost curve convergence and mechanic network consolidation patterns. Recalibration cycles align with material shifts in Indian emission regulatory enforcement and Southeast Asian logistics infrastructure development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market