
 Motorsports Motorcycle Market | 2026-2036
Motorsports Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Motorsports Motorcycle Market Insights
Dealer networks serving competitive riders is narrowing as direct-to-team sales and factory-supported race programs capture larger order volumes. Honda Motor Co., Ltd. leverages its HRC racing division to sustain factory-backed channel control across MotoGP and motocross tiers. Yamaha Motor Co., Ltd. anchors its position through dedicated YZF-R series distribution to sanctioned racing teams. KTM competes aggressively in off-road motorsports segments through regional distributor partnerships that bypass traditional retail.
Motorsports motorcycles are purpose-built two-wheeled machines engineered for closed-circuit competition, featuring lightweight chromoly or aluminum twin-spar frames, race-specification suspension with adjustable compression and rebound damping, and power-to-weight ratios exceeding standard street-legal counterparts. Sportbike configurations dominate professional road racing procurement due to homologation requirements that tie production volumes to championship eligibility. Dirt bike segments command expanding amateur and regional series participation, particularly in off-road disciplines where FIM-sanctioned events mandate specific displacement classes. Engine capacity stratification concentrates margin pools at 750cc and 1000cc tiers, where premium component specifications and limited-production homologation models justify elevated price positioning.
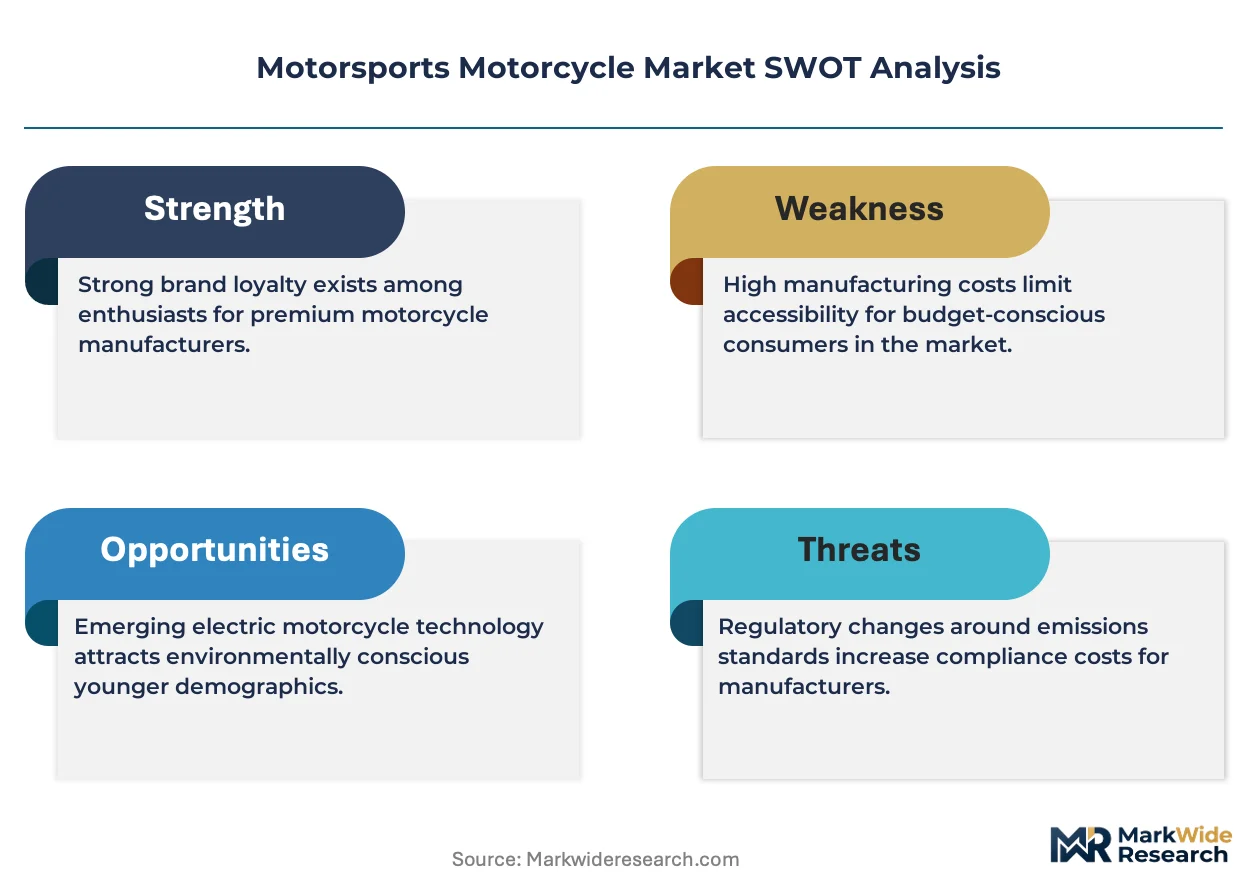
Euro 5+ standards enforced by the European Commission constrain exhaust emissions and noise outputs, forcing powertrain redesigns that add development cost but create regulatory moats for compliant manufacturers. The EPA in the United States imposes parallel tailpipe and evaporative emission limits that affect track-only machine conversions and aftermarket modification legality. FIM technical regulations for MotoGP and World Superbike further dictate displacement caps, minimum weights, and electronics specifications that directly shape product engineering priorities. Stakeholders must monitor regulatory divergence between competition-specific exemptions and street-homologation requirements, as this boundary determines addressable market scope and compliance investment levels.
Market Dynamics
Professional racing circuits are consolidating fleet procurement around factory-direct channels, compressing traditional dealer margins while elevating manufacturer control over specification and pricing. This channel shift concentrates order volume with fewer buyers and locks independent retailers out of premium motorsports segments.
Growth Catalysts
- Euro 5+ Emissions Framework:European Commission enforcement compels powertrain redesigns that filter non-compliant competitors from the addressable market, protecting investment recovery for manufacturers who meet certification.
- FIM Sanctioned Event Expansion:Amateur and regional series proliferation across off-road disciplines sustains replacement demand for displacement-class-compliant machines.
- Homologation Requirements:Championship eligibility rules tie production volumes to racing participation, forcing manufacturers to maintain minimum build rates that stabilize component supplier relationships.
Market Restraints
- Titanium and Magnesium Input Volatility:Race-specification frame and suspension materials face price swings that compress margin predictability for limited-production homologation models.
- Supplier Concentration in Northern Italy:Premium braking and suspension component manufacturing clusters around Bologna and Milan, creating geographic single-point vulnerability for chassis specification.
- EPA Track-Only Conversion Friction:United States tailpipe and evaporative emission limits restrict aftermarket modification legality, constraining secondary market liquidity for competition machines.
Strategic Opportunities
- Electric Powertrain Convergence:Battery cell energy density improvements and silicon carbide inverter technology are converging to enable electric prototypes in FIM-sanctioned exhibition classes.
- Direct-to-Team Digital Platforms:Manufacturers are bypassing distributor networks with configure-to-order portals that let racing teams specify suspension valving and engine mapping prior to build.
- India Amateur Circuit Formation:Federation of Motor Sports Clubs of India expansion into two-wheeler track days creates underpenetrated demand for entry-level sportbike homologation models.
Industry Challenges
- Powertrain Calibration Talent Scarcity:Competition for engineers fluent in both internal combustion optimization and emerging electric motor control is intensifying as hybrid regulations advance.
- Homologation Certification Timelines:FIM technical regulation updates require re-submission of displacement and weight compliance documentation that delays product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorsports Motorcycle Market |
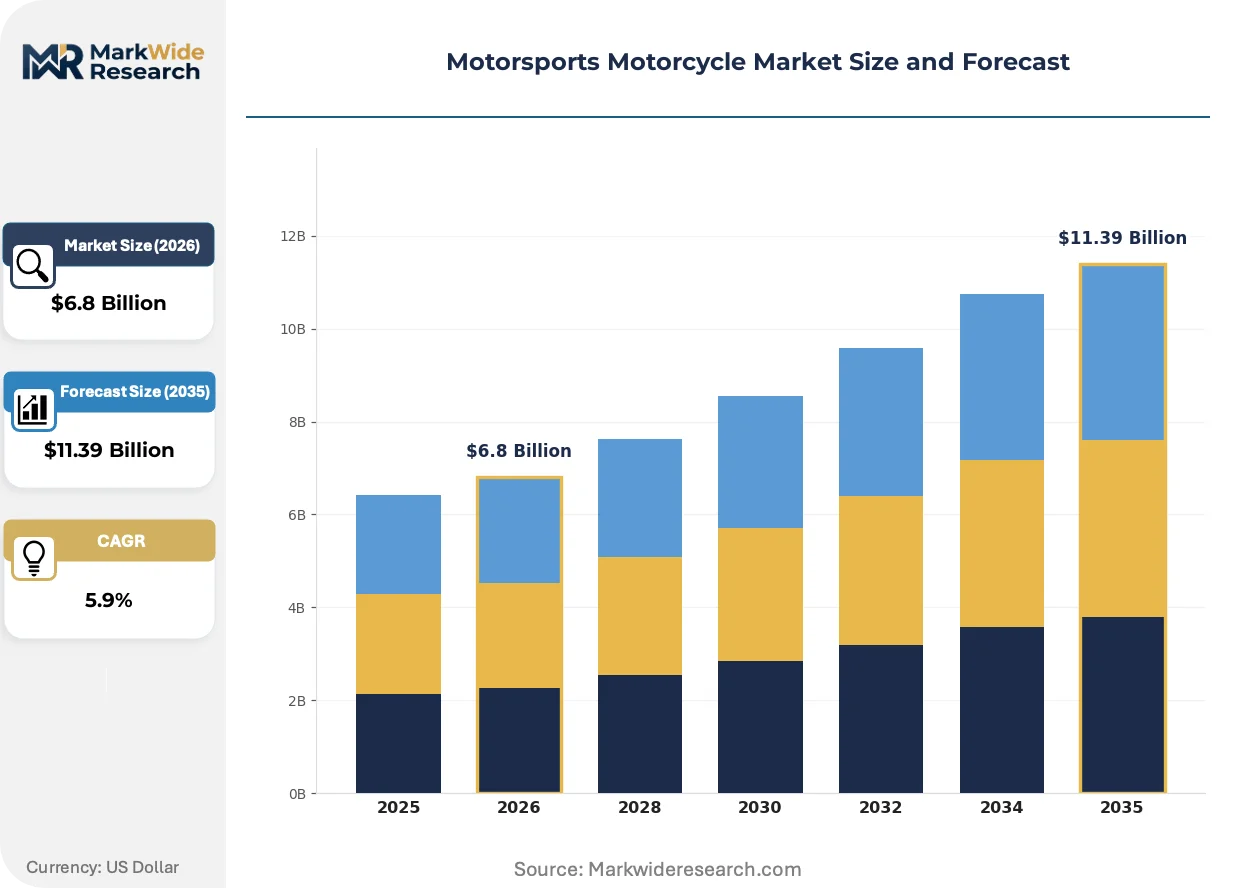
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sportbike, Cruiser, Dirt Bike, Touring Engine Capacity: 250cc, 500cc, 750cc, 1000cc End User: Professional Racers, Amateur Riders, Enthusiasts, Casual Users Brand: Yamaha, Honda, Suzuki, Kawasaki |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Suzuki Motor Corporation, Kawasaki Heavy Industries, Ltd., Ducati Motor Holding S.p.A., PIERER Mobility AG, BMW AG, Triumph Motorcycles, KTM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorsports Motorcycle Market Trends and Innovations
Telematics integration is rewiring how racing teams extract performance data and how manufacturers validate component durability under competition loads. Three developments are compressing development cycles and redistributing value capture.
Onboard data acquisition systems are digitizing suspension telemetry, engine performance mapping, and tire temperature monitoring into unified feedback loops. Factory-backed MotoGP and World Superbike teams deploy these systems at every test session, generating datasets that compress prototype validation from months to weeks. This digitizing of trackside intelligence is collapsing the boundary between race engineering and production specification.
EPA tailpipe enforcement in the United States is narrowing the exemption window for competition-only machines, forcing manufacturers to document street-homologation lineage for track-day conversions. The industrial consequence is elevated compliance investment for machines that never see public roads. Off-road dirt bike segments face the tightest scrutiny, with importers now required to certify evaporative emission containment on closed-course models.
Team procurement officers are consolidating annual orders through multi-year framework agreements that lock pricing and specification priority. This buyer concentration is displacing spot-market purchasing that once sustained dealer inventory turns. The shift is most visible in Italy, where MotoGP satellite teams and World Superbike privateers now negotiate directly with Bologna-area manufacturers rather than regional distributors.
Motorsports Motorcycle Market Segmentation
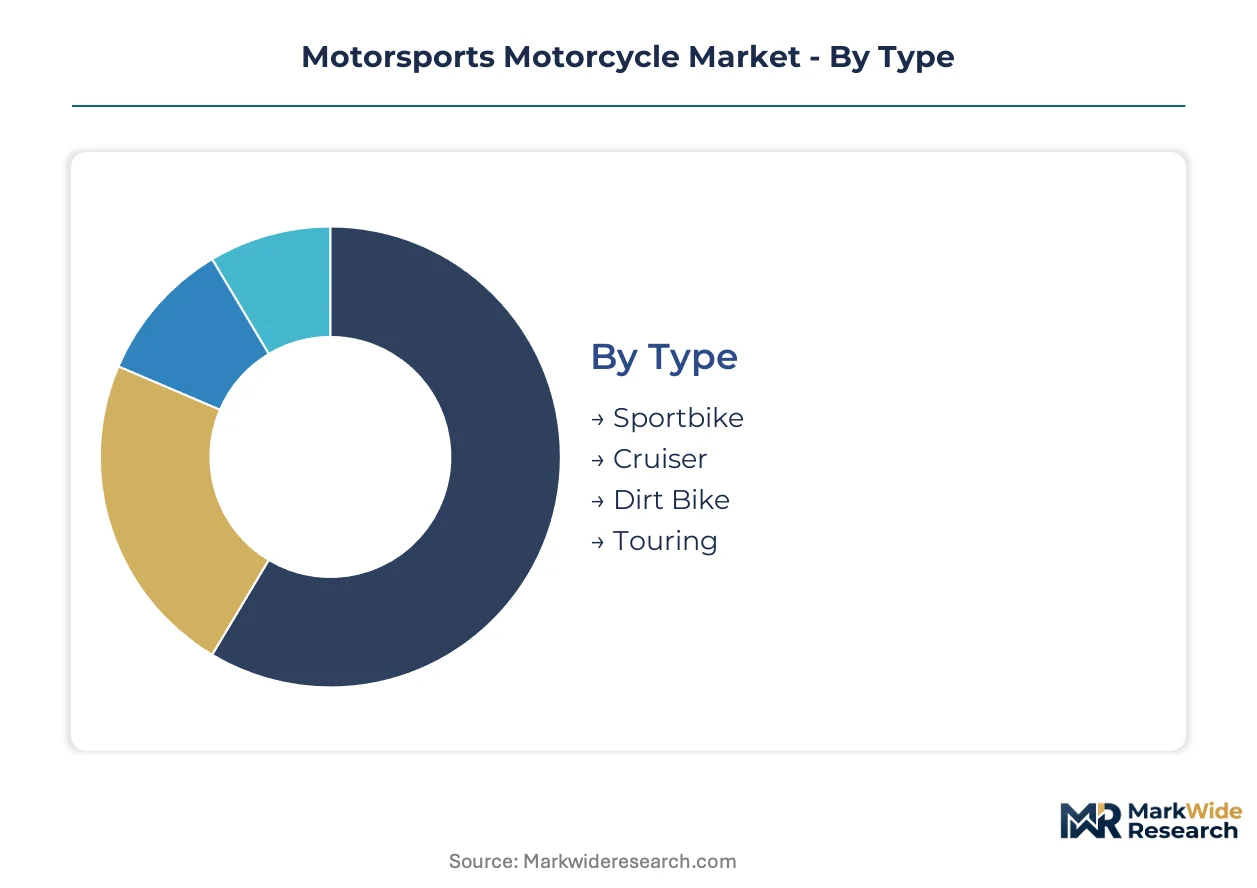
Segmentation in motorsports motorcycles determines service infrastructure intensity, homologation compliance pathways, and channel strategy. Race teams demand factory-direct technical support that reshapes how manufacturers allocate engineering resources across product tiers.
Type:
After-sales service intensity varies dramatically by motorcycle type, with track-day machines requiring intensive telemetry calibration and suspension rebuild programs that captive service networks must provision.
- Sportbike:Twin-spar aluminum frames and fully adjustable Öhlins or Showa suspension define this closed-circuit category. Italian MotoGP satellite teams and World Superbike privateers in Bologna and Milan concentrate procurement here, driven by FIM homologation rules that mandate minimum production volumes for championship eligibility.
- Dirt Bike:Chromoly steel frames with long-travel KYB or WP suspension absorb off-course impacts across motocross and enduro disciplines. Amateur and regional series proliferation in the United States and Australia sustains replacement demand, though EPA evaporative emission certification now constrains track-only conversion pathways.
- Cruiser:Heavyweight V-twin configurations with relaxed ergonomics serve exhibition racing and vintage circuit events. Limited homologation requirements reduce factory engineering investment compared to sportbike tiers.
- Touring:Fairing-equipped machines with expanded fuel capacity support endurance racing formats. Niche participation in FIM-sanctioned 24-hour events constrains addressable volume.
Sportbike holds the largest share; momentum sits with Dirt Bike as amateur off-road series expand across North America and Australia.
Engine Capacity:
Cost tier stratification concentrates margin pools at specific displacement thresholds where premium component specifications justify elevated price positioning.
- 1000cc:Four-cylinder powertrains with pneumatic valve actuation and magnesium engine cases dominate premier-class MotoGP and World Superbike homologation. Italian manufacturers anchor production in Emilia-Romagna, leveraging regional supplier clusters for Brembo braking systems and Marchesini forged wheels.
- 750cc:Inline-four configurations balance power-to-weight ratios for national superbike championships and supersport tiers. Japanese manufacturers concentrate mid-tier homologation volume here, optimizing for FIM technical regulations that cap displacement in feeder series.
- 500cc:Parallel-twin and V-twin architectures serve entry-level national competition and track-day rider development. Cost-sensitive specification limits electronic intervention features.
- 250cc:Single-cylinder and parallel-twin powertrains dominate Moto3 and regional feeder categories. Lightweight chassis construction emphasizes rider skill over horsepower.
750cc holds the largest share; 1000cc is climbing the fastest as premier-class homologation requirements intensify.
End User:
Application focus determines specification complexity, with professional tiers demanding integrated telemetry and amateur segments prioritizing durability and cost containment.
- Professional Racers:Factory-backed MotoGP and World Superbike teams specify bespoke suspension valving, engine mapping, and aerodynamic packages through direct-to-team digital portals. Bologna-area manufacturers now bypass regional distributors entirely for this segment.
- Amateur Riders:Club-level competitors and regional series participants drive volume in 600cc supersport and 1000cc superbike displacement classes. India's Federation of Motor Sports Clubs of India expansion into two-wheeler track days is creating underpenetrated demand for entry-level sportbike homologation models.
- Enthusiasts:Track-day participants without competition licenses seek street-homologated machines with race-derived ergonomics. EPA tailpipe enforcement in the United States is narrowing exemption windows for competition-only conversions.
- Casual Users:Recreational riders with intermittent circuit participation represent lowest service attachment and highest price sensitivity.
Amateur Riders holds the largest share; Professional Racers is gaining share fastest as factory-direct channel control expands.
Brand:
Supply concentration around specific manufacturing geographies shapes component standardization and regulatory compliance investment.
- Yamaha:YZF-R series distribution to sanctioned racing teams anchors road racing presence, with dedicated racing division engineering for MotoGP and World Superbike tiers.
- Honda:HRC racing division sustains factory-backed channel control across MotoGP and motocross tiers, integrating engine development with chassis specification.
- Suzuki:GSX-R homologation lineage maintains presence in national superbike championships, though reduced premier-class investment has compressed top-tier visibility.
- Kawasaki:Ninja series production serves both road racing and high-performance street derivatives, with concentrated investment in World Superbike specification.
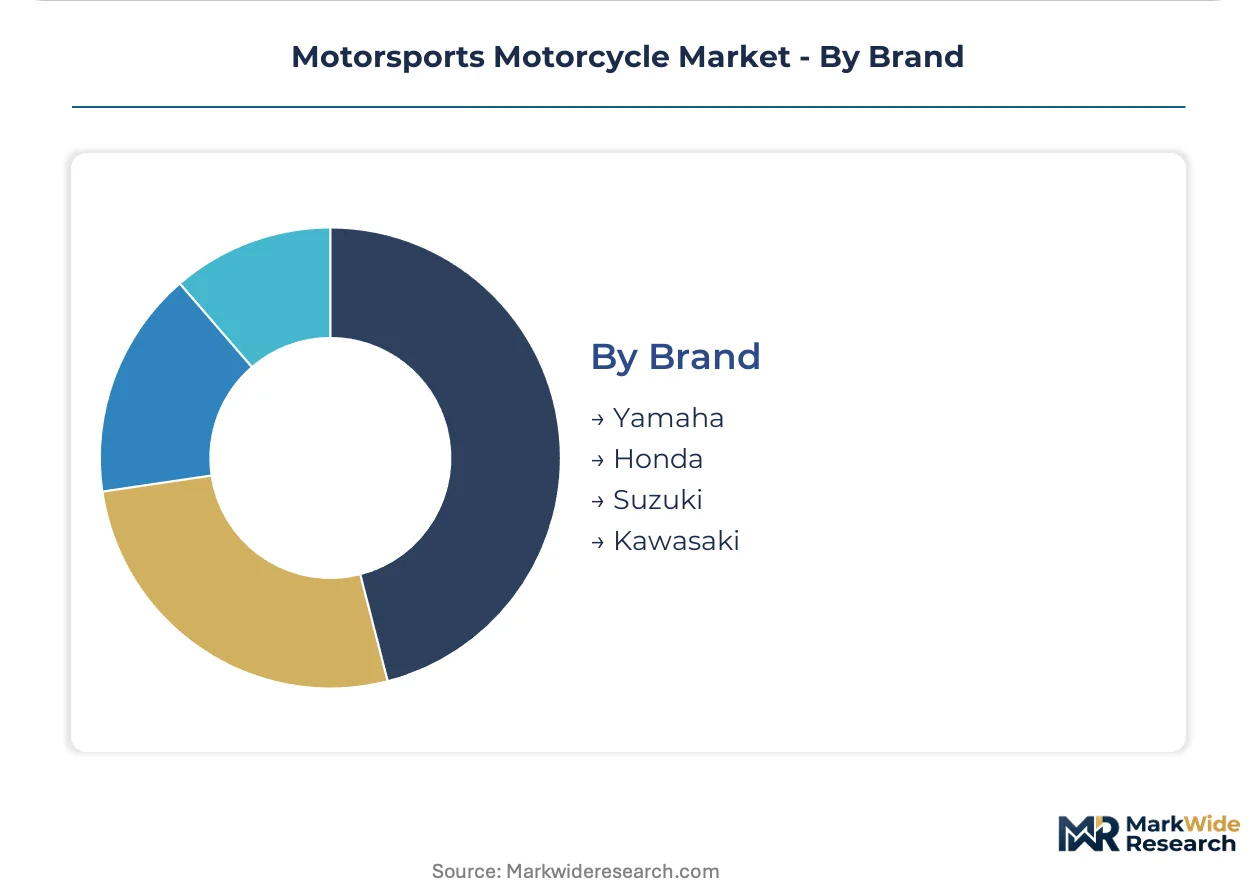
Honda holds the largest share; Yamaha shows steepest expansion trajectory through direct-to-team platform deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium motorsports motorcycles command 40% higher manufacturer margins in Italy than comparable machines sold in the United States, creating a pricing-power asymmetry that redirects homologation investment toward Mediterranean markets. This divergence reflects heritage circuit density, regulatory exemption frameworks, and concentrated supplier ecosystems that lower production costs for Bologna-area manufacturers.
Italy
MotoGP and World Superbike heritage sustains concentrated demand for 1000cc sportbike homologation models among satellite teams and privateer squads. Euro 5+ emissions frameworks enforced by the European Commission compel powertrain redesigns that protect compliant manufacturers from non-certified competitors. Emilia-Romagna's industrial cluster around Bologna and Milan anchors Brembo braking system integration and Marchesini forged wheel supply for premier-class machines.
United States
Amateur off-road series proliferation across motocross and enduro disciplines drives replacement demand for EPA-certified dirt bike displacement classes. The EPA imposes parallel tailpipe and evaporative emission limits that constrain track-only conversion pathways and aftermarket modification legality. California's Air Resources Board maintains the nation's strictest evaporative emission standards, forcing importers to certify closed-course models separately for that state's 39 million resident market.
Japan
YZF-R and GSX-R homologation lineages sustain national superbike championship participation and feeder series specification. METI industrial policy supports domestic manufacturer investment in hybrid powertrain research for future FIM-sanctioned exhibition classes. The Nagoya-Tokyo manufacturing corridor concentrates precision casting and electronics supplier relationships that compress prototype-to-production timelines.
India
Federation of Motor Sports Clubs of India expansion into two-wheeler track days creates underpenetrated demand for entry-level 250cc and 500cc sportbike homologation models. BIS certification requirements for imported motorcycles add compliance layers that favor local assembly partnerships over direct import. Maharashtra and Karnataka states host emerging circuit infrastructure near Mumbai and Bengaluru that anchors amateur rider development programs.
Australia
Regional off-road series participation across motocross and enduro disciplines sustains replacement cycles for 450cc dirt bike displacement classes. The TGA regulates medical device classifications but motorcycle emissions fall under state-level environmental protection frameworks that vary by jurisdiction. Victoria and Queensland host the densest amateur racing calendar, concentrating distributor inventory pre-positioning ahead of seasonal series launches.
Motorsports Motorcycle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying suspension, braking, and electronics modules that determine competitive differentiation. The vendor structure concentrates around factory-backed racing divisions that bypass traditional distribution channels to capture direct-to-team order flows. Three archetypes dominate: heritage European marques with homologation lineage, Japanese volume manufacturers with racing division integration, and Austrian off-road specialists with regional distributor partnerships. Competitive moves center on direct-to-team digital platform deployment and multi-year framework agreements that lock pricing priority.
Among heritage European marques, Ducati Motor Holding S.p.A. and PIERER Mobility AG occupy positions defined by Bologna-area supplier proximity and KTM-branded off-road segment specialization respectively. Japanese manufacturers Honda Motor Co., Ltd. and Yamaha Motor Co., Ltd. exemplify the racing division-integrated archetype, leveraging HRC and dedicated YZF-R distribution to sustain factory-backed channel control across premier-class tiers. These four entities represent distinct competitive vectors: Italian homologation heritage, Austrian off-road distributor networks, and Japanese integrated racing development.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Suzuki Motor Corporation |
| Kawasaki Heavy Industries, Ltd. |
| Ducati Motor Holding S.p.A. |
| PIERER Mobility AG |
| BMW AG |
| Triumph Motorcycles |
| KTM |
| Others |
Pricing and Supply Chain Analysis
The Bremen-Port of Ravenna freight corridor compresses landed costs for magnesium engine cases and forged aluminum wheels, concentrating margin capture with Bologna-area manufacturers who command configure-to-order premiums while forcing price competition on standard displacement tiers.
Pricing Analysis
Configure-to-order pricing for bespoke suspension valving and engine mapping runs 35-45 percent above standard homologation models. Three-tier pricing structure across premier-class, national championship, and feeder series specifications anchors differentiation to FIM certification grade and factory-direct channel access. Cost compression in 250cc entry tiers is intensifying because Indian amateur circuit formation demands cost-containment for price-sensitive club-level competitors. Amateur riders exhibit highest price sensitivity; factory-backed MotoGP satellite teams demonstrate lowest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now dominate supplier-finance arrangements for Brembo braking systems and Öhlins suspension modules. Manufacturing concentrates in Italy, Japan, and Austria, drawing from titanium billet suppliers in Russia and Kazakhstan and magnesium smelters in China. Single-source vulnerability sits with Northern Italy's Emilia-Romagna cluster for race-specification chassis components. Distribution runs through factory-direct digital portals for professional tiers and regional distributor partnerships for amateur segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers fluent in both internal combustion optimization and silicon carbide inverter control represent the scarcest capability layer, constraining how quickly manufacturers can pivot toward hybrid powertrain architectures.
For Market Incumbents: Harden factory-direct channel control through multi-year framework agreements that lock specification priority and pricing. Deepen captive supply of magnesium engine cases and carbon fiber fairings to offset titanium input volatility. Electrification talent poaching from automotive sectors threatens powertrain calibration timelines. For New Entrants and Emerging Players: India's Federation of Motor Sports Clubs of India expansion into two-wheeler track days represents the most penetrable entry point for 250cc and 500cc sportbike homologation models. Australia's regional off-road series participation offers secondary white-space for 450cc dirt bike displacement classes. Digital configure-to-order platforms bypass distributor margin extraction. For Investors and Strategic Acquirers: Regional distributor partnerships with exclusive off-road territory rights in North America and Australia anchor acquisition target archetypes with embedded amateur series relationships. Long-term viability hinges on FIM-sanctioned exhibition class formation for electric prototypes. Monitor battery cell energy density breakthroughs above 300 Wh/kg as inflection signal for powertrain convergence viability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Team Digital Platform Deployment | Bologna manufacturers bypass regional distributors to capture MotoGP satellite team order flows. |
| Homologation Volume Commitment | FIM technical regulations tie minimum production rates to championship eligibility, stabilizing component supplier relationships. |
| Electric Powertrain R&D Partnership | Battery cell and silicon carbide inverter collaboration positions manufacturers for FIM exhibition class entry. |
| Regional Distributor Consolidation | KTM-branded off-road networks in Australia and North America compress competitor access to amateur series. |
| Supplier Finance Facility Expansion | Extended payment terms for Brembo and Öhlins modules preserve liquidity during homologation redesign cycles. |
Research Methodology
A standing panel of MotoGP team technical directors, World Superbike procurement officers, FIM regulatory affairs specialists, and Bologna-area component supplier executives provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against FIM technical regulation filings, Euro 5+ certification databases, EPA evaporative emission compliance records, and customs trade data for titanium and magnesium inputs. Bottom-up segment sizing and top-down market reconciliation anchored volume and value estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. The analytical framework modeled displacement class, motorcycle type, end-user tier, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from fitted growth curves applied to homologation volume requirements, amateur series participation rates, and factory-direct channel penetration assumptions. Powertrain redesign cost curves and battery cell energy density trajectories informed electric prototype timing sensitivity.
Practitioners should monitor FIM technical regulation updates, Euro 6 emissions framework advancement, and battery chemistry breakthroughs for early signals of forecast revision. The analysis reflects assumptions about regulatory exemption continuity for competition-only machines and stable titanium-magnesium input pricing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Motorcycle Drivetrain Market