
 E-Cargo Bike Market | 2026-2036
E-Cargo Bike Market Size, Share, and Industry Trends Forecast 2026-2036
E-Cargo Bike Market Analysis
Aftermarket service revenue is reshaping margin capture in the e-cargo bike sector, pulling profitability from hardware sales toward battery refurbishment and fleet maintenance contracts. Rad Power Bikes leverages direct-to-consumer channel control to sustain pricing power across North American urban markets. Riese & Müller anchors premium positioning through German engineering credibility and Bosch drivetrain integration. Urban Arrow dominates the front-loading family and commercial segment in Benelux cycling infrastructure corridors.
An e-cargo bike is a pedal-assisted electric bicycle engineered to haul payloads exceeding 100 kilograms through reinforced frames, extended wheelbases, and mid-drive or hub motors rated at 250–750 watts, purpose-built for commercial freight movement and family transport in dense urban environments. Electric cargo bikes occupy the highest-margin tier among product types, as commercial fleet operators prioritize load capacity and durability over upfront cost. Lithium-ion battery configurations lead the battery type landscape due to energy density advantages, though solid-state chemistry represents the fastest-advancing alternative for extended-range logistics applications. Delivery services command the dominant end user position, with e-commerce retailers representing the most rapidly scaling procurement segment as same-day fulfillment networks expand.
The European Union's F-Gas Regulation and Machinery Directive (MDR) shape motor and refrigerant standards for cargo bike manufacturing, while Germany's KBA enforces type-approval requirements for speed-pedelec variants exceeding 25 km/h. The EPA in the United States and Health Canada both influence battery disposal protocols and motor efficiency benchmarks for North American market entry. Stakeholders must monitor evolving subsidy qualification criteria and infrastructure investment commitments across municipal governments to anticipate procurement cycle timing and fleet deployment scale.
Market Dynamics
Last-mile logistics operators are accelerating fleet electrification mandates as urban congestion pricing schemes expand across European metropolitan centers, compressing total cost of ownership calculations for van-to-cargo-bike substitution decisions.
Growth Catalysts
- Germany's KBA type-approval streamlining:The federal motor transport authority has reduced homologation timelines for speed-pedelec variants, cutting fleet procurement lead times by several months for commercial operators.
- Lithium-ion energy density gains:Cell chemistry improvements now enable 150-kilometer range configurations on single charges, eliminating range anxiety for urban delivery circuits.
- Dutch municipal procurement frameworks:Rotterdam and Amsterdam have embedded cargo bike quotas into public service contracts, creating guaranteed demand anchors for fleet manufacturers.
Market Restraints
- Mid-drive motor supply concentration:Bosch and Shimano dominate torque-sensing motor production, creating single-source vulnerability for frame assemblers.
- Battery raw material volatility:Lithium carbonate and nickel price swings transmit directly to pack costs, destabilizing OEM margin forecasts.
- Speed-pedelec insurance classification:German liability frameworks classify 45 km/h variants as motor vehicles, triggering commercial premium spikes that erode operating cost advantages.
Strategic Opportunities
- French cargo bike purchase incentives:The FMD (Fonds Mobilités Durable) subsidy covers 40 percent of acquisition costs for professional fleets, opening price-sensitive SME segments.
- Battery-as-a-service models:Subscription-based pack leasing decouples upfront hardware costs from energy infrastructure, lowering barrier-to-entry for micro-delivery entrepreneurs.
- Solid-state chemistry convergence:Next-generation cell architectures promise 400 Wh/kg density, enabling refrigerated cargo applications in pharmaceutical logistics.
Industry Challenges
- Frame welding certification backlog:EN 15194 testing capacity constraints at notified bodies delay product launches by 4-6 months.
- Software-hardware integration complexity:CAN bus protocol fragmentation between motor controllers and fleet telematics platforms forces redundant engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Cargo Bike Market |
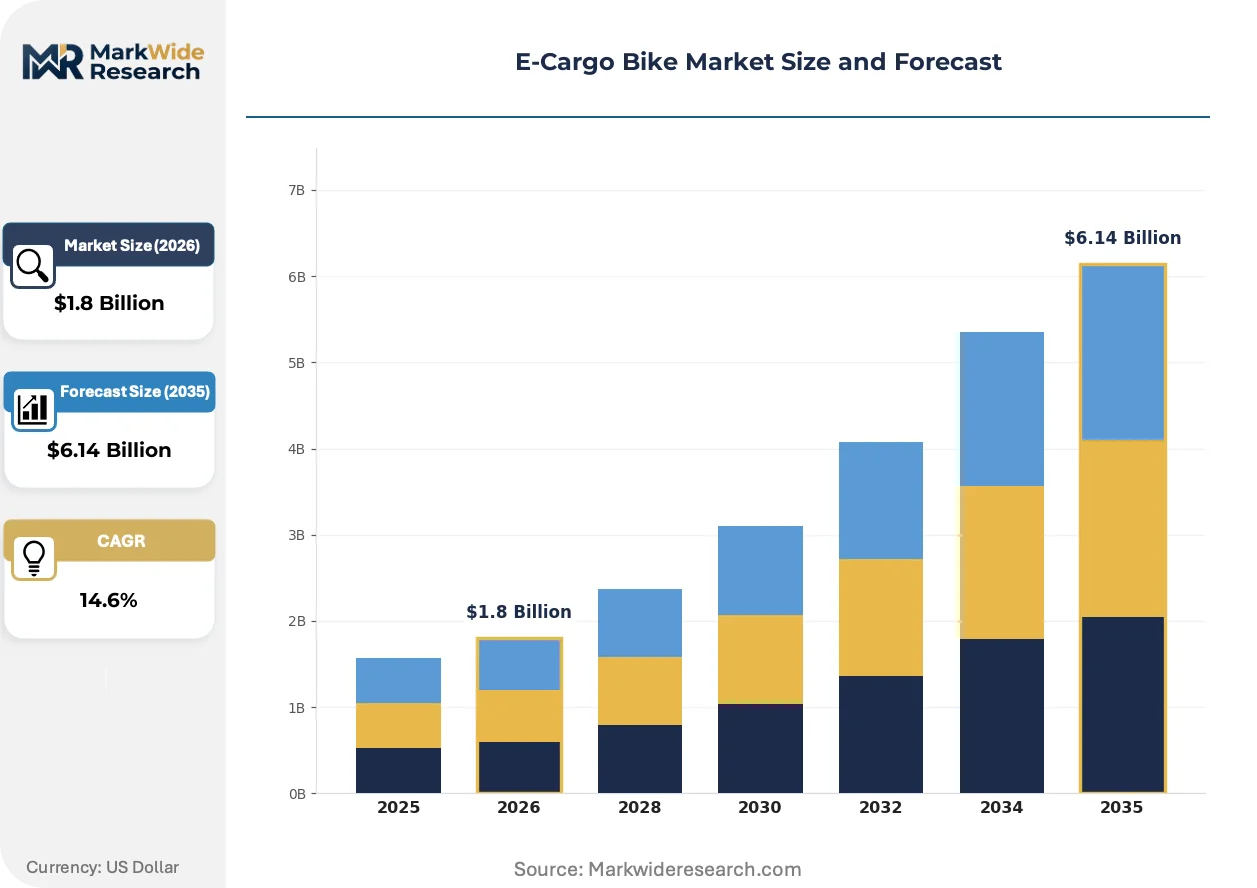
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Cargo Bikes, Electric Trailer Bikes, Modular Cargo Bikes, Utility E-Bikes End User: Delivery Services, Logistics Companies, E-Commerce Retailers, Urban Transport Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Price Tier: Economical, Mid-Range, Premium, Luxury |
| Companies Covered | Rad Power Bikes, Riese & Müller, Urban Arrow, Tern Bicycles, Giant Manufacturing, Accell Group, Douze Cycles, Yuba Bicycles, Butchers & Bicycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Cargo Bike Market Emerging Trajectories
Modular cargo platform architectures are redefining product lifecycle economics, allowing frame manufacturers to swap motor mounts and battery housings across multiple use cases without complete retooling.
Mid-drive torque sensors with automatic load compensation are rendering obsolete hub-motor configurations that lack real-time traction adjustment. Parcel carriers in Copenhagen and Utrecht are specifying these systems for 200-kilogram payload routes. The technology is compressing warranty claim rates and extending fleet replacement cycles beyond five years.
REACH substance restrictions on flame retardants in battery enclosures are forcing enclosure manufacturers toward ceramic fiber alternatives. German frame builders report 12-week material qualification delays. The F-Gas Regulation's refrigerant phase-down is simultaneously pressuring thermal management suppliers in cold-chain cargo segments.
Subscription-based fleet management is displacing outright purchase models among urban delivery cooperatives. Dutch logistics platforms now bundle insurance, maintenance, and battery swaps into per-kilometer pricing. This shift is most pronounced in Belgian e-grocery networks where seasonal demand volatility makes fixed asset ownership uneconomical.
E-Cargo Bike Market Segmentation
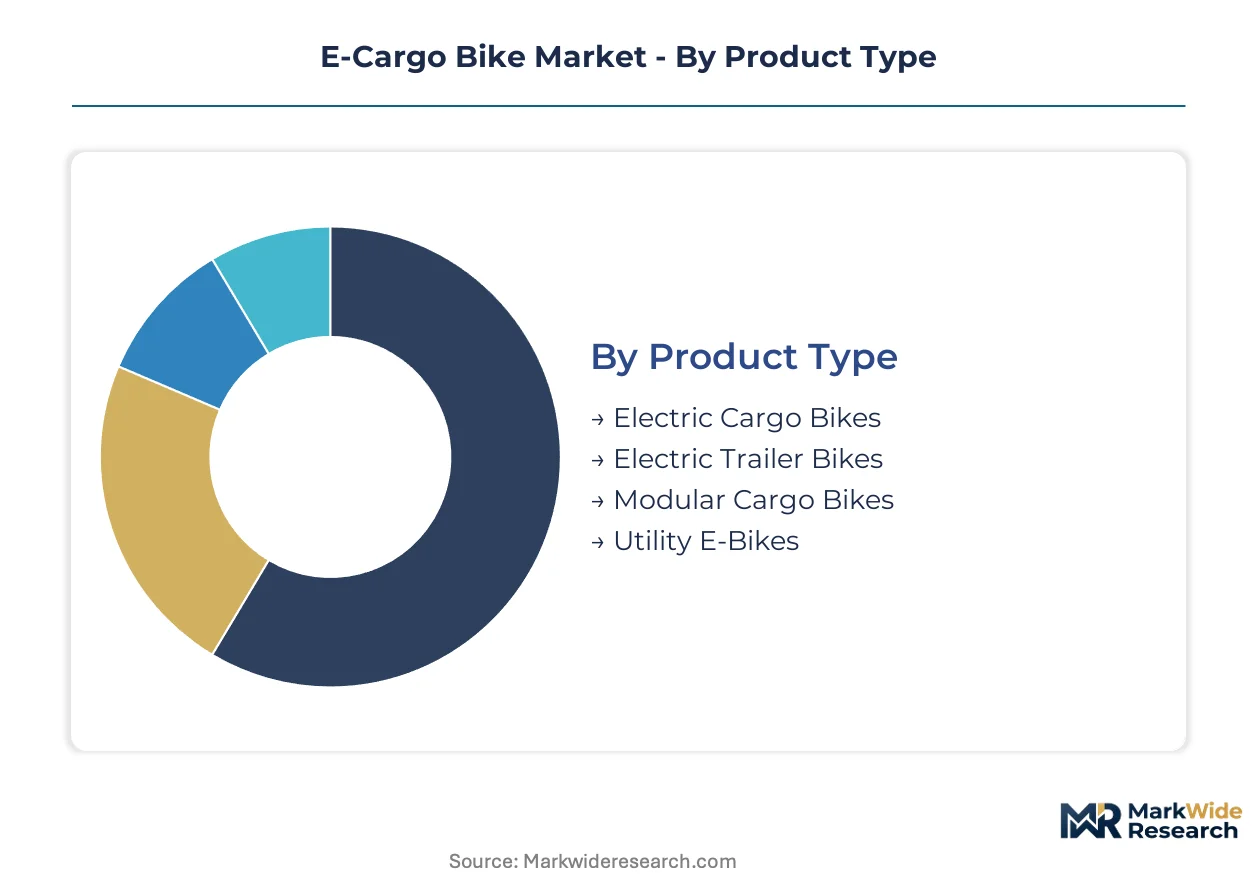
Segmentation in the E-Cargo Bike Market reveals divergent equipment lifecycles and margin profiles across use cases. Fleet operators prioritize durability and payload specifications over consumer segments that emphasize purchase subsidies and multi-purpose flexibility. Understanding these structural differences enables targeted product positioning and service revenue capture.
Product Type:
Replacement cycles vary dramatically across product architectures, with commercial-grade frames engineered for 5-7 year service lives while lighter consumer variants turn over every 3-4 years.
- Electric Cargo Bikes:Purpose-built frames with reinforced head tubes and extended wheelbases accommodate 150-200 kilogram payloads through mid-drive motor configurations. Dutch municipal procurement programs in Rotterdam and Amsterdam specify these units for postal and waste collection contracts, creating stable demand anchors with standardized replacement schedules.
- Modular Cargo Bikes:Interchangeable front and rear mounting systems allow rapid reconfiguration between passenger, parcel, and refrigerated cargo applications. Danish logistics cooperatives in Copenhagen favor these platforms for seasonal demand fluctuations, swapping modules rather than acquiring dedicated fleets.
- Electric Trailer Bikes:Hitch-mounted cargo extensions convert standard e-bikes into freight carriers without dedicated frame investment. German last-mile operators deploy these for peak season capacity augmentation.
- Utility E-Bikes:Light-duty frames with rear rack expansion support sub-50 kilogram loads for personal shopping and family transport. French FMD subsidy qualification drives household adoption in urban cores.
Electric Cargo Bikes dominate installed base. Modular Cargo Bikes is where expansion concentrates.
End User:
Procurement scale and decision velocity separate enterprise fleet operators from fragmented consumer demand, with contract terms and service bundling becoming the primary competitive battleground.
- Delivery Services:Parcel carriers negotiate multi-year fleet leases with embedded maintenance and battery swap provisions. Subscription-based per-kilometer pricing has displaced outright purchase models in Belgian e-grocery networks where demand volatility makes fixed asset ownership uneconomical.
- E-Commerce Retailers:Same-day fulfillment networks require 12-16 hour daily utilization rates, driving specification toward dual-battery configurations and rapid-swap charging infrastructure. These operators represent the steepest expansion trajectory as urban congestion charges compress van-to-cargo-bike substitution economics.
- Logistics Companies:Third-party freight operators balance asset utilization across multiple client contracts, prioritizing standardized service protocols over customized specifications.
- Urban Transport:Municipal bike-share schemes and public service fleets emphasize vandal-resistant hardware and centralized depot maintenance.
Delivery Services command current fleet volume. E-Commerce Retailers is where procurement velocity is climbing the fastest.
Battery Type:
Energy density and cycle life specifications determine total cost of ownership calculations, with chemistry selection locking operators into specific charging infrastructure and thermal management investments.
- Lithium-Ion:NMC and LFP cell configurations deliver 400-600 Wh energy density with 1,000+ charge cycles, establishing the dominant chemistry for commercial routes. Energy density gains now enable 150-kilometer range configurations on single charges, eliminating range anxiety for urban delivery circuits.
- Solid-State:Ceramic electrolyte architectures promise 400 Wh/kg density with reduced thermal runaway risk, enabling refrigerated cargo applications in pharmaceutical logistics where temperature integrity is non-negotiable.
- Nickel-Metal Hydride:Mature chemistry with lower energy density but simplified recycling protocols appeals to municipal fleets with extended replacement timelines.
- Lead-Acid:Lowest acquisition cost chemistry remains confined to emerging market price-sensitive segments with limited daily range requirements.
Lithium-Ion dominates installed base. Solid-State is where technology investment concentrates.
Price Tier:
Margin capture and customer lifetime value diverge sharply across price bands, with premium segments generating disproportionate aftermarket service revenue relative to hardware margins.
- Premium:German-engineered frames with Bosch drivetrain integration and EN 15194 certification command price positions that sustain dealer network viability. These specifications anchor fleet procurement decisions where downtime costs exceed acquisition premiums.
- Mid-Range:Asian-manufactured frames with qualified component sourcing balance upfront cost against 3-year service life expectations. Direct-to-consumer channel control sustains pricing power across North American urban markets.
- Economical:Simplified hub-motor configurations and reduced battery capacity target micro-delivery entrepreneurs with constrained capital access.
- Luxury:Custom fabrication and design-house collaborations serve brand-conscious consumers with limited commercial relevance.
Premium dominates commercial fleet specification. Mid-Range is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German fleet operators absorb premium hardware costs through subsidy offset mechanisms, while French micro-delivery entrepreneurs depend on FMD coverage thresholds to justify acquisition decisions.
Germany
Fleet procurement concentrates around speed-pedelec variants for suburban logistics corridors. The KBA type-approval streamlining has compressed homologation timelines, accelerating commercial deployment decisions. Manufacturing clusters in Baden-Württemberg and Bavaria anchor frame fabrication and Bosch drivetrain integration.
Netherlands
Municipal procurement quotas in Rotterdam and Amsterdam generate guaranteed demand anchors for postal and waste collection fleets. The country's cycling infrastructure density eliminates range anxiety as a purchasing constraint. Eindhoven-Brabant manufacturing corridors specialize in modular cargo platform production.
France
FMD subsidies covering 40 percent of professional fleet acquisition costs unlock price-sensitive SME segments. The national regulator enforces machinery safety standards through MDR-aligned certification requirements. Paris and Lyon logistics cooperatives are migrating toward subscription-based fleet management models.
Denmark
Copenhagen's congestion pricing scheme compresses van-to-cargo-bike substitution economics for last-mile operators. National cycling infrastructure investment prioritizes freight corridor separation from passenger lanes. Odense and Aarhus harbor manufacturing clusters for mid-drive torque sensor integration.
United States
Direct-to-consumer channel penetration sustains mid-range volume expansion across dense urban markets. The EPA influences battery disposal protocols and motor efficiency benchmarks for market entry compliance. Seattle and Portland metro areas exhibit concentrated fleet pilot programs for e-grocery delivery networks.
E-Cargo Bike Market Vendor Landscape
Capability concentration sits with premium-tier German engineering specialists; scale advantage sits with Asian manufacturing platforms and North American direct-to-consumer operators. The market structures around three archetypes: integrated drivetrain-frame assemblers, modular platform specialists, and volume-focused consumer brands. Competitive moves center on backward integration into battery pack assembly and geographic licensing partnerships for fleet telematics integration.
Among European premium fabricators, Riese & Müller GmbH and Urban Arrow occupy positions defined by EN 15194 certification anchoring and municipal fleet specification capture. Rad Power Bikes exemplifies the direct-to-consumer archetype with channel-controlled pricing power across North American urban markets. These three entities represent distinct competitive vectors: engineering credibility, infrastructure-native design, and scale-driven consumer access.
| Leading Market Players |
|---|
| Rad Power Bikes |
| Riese & Müller |
| Urban Arrow |
| Tern Bicycles |
| Giant Manufacturing |
| Accell Group |
| Douze Cycles |
| Yuba Bicycles |
| Butchers & Bicycles |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Amsterdam freight corridors compress delivery economics through congestion pricing, concentrating pricing power with frame assemblers who control Bosch drivetrain allocation while forcing downstream price stratification between fleet operators and micro-entrepreneurs.
Pricing Analysis
Long-term fleet lease contracts with embedded battery swap provisions dominate commercial procurement, anchoring price differentiation around EN 15194 certification tier and dual-battery configuration scale. Premium-mid-economy pricing differentiation separates municipal fleet specifications from consumer subsidy-driven purchases. Cost compression in the economical tier intensifies because Asian frame imports erode hardware margins. Micro-delivery entrepreneurs exhibit highest price sensitivity, while German postal operators absorb premiums through KBA type-approval reliability requirements.
Supply Chain Analysis
Extended payment terms from Bosch and Shimano torque-sensor suppliers strain frame assembler working capital, forcing supply-chain finance facility dependence. Manufacturing concentrates in Germany, the Netherlands, and Taiwan for frame fabrication, motor integration, and battery pack assembly respectively. Lithium carbonate, nickel cathode materials, and 6061 aluminum tubing constitute critical input dependencies. Single-source vulnerability around mid-drive motor controllers creates procurement risk. Distribution runs through direct-to-consumer platforms in North America and dealer networks anchored by municipal procurement frameworks in Benelux corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frame welding certification capacity and mid-drive motor controller firmware expertise constitute binding constraints, limiting fleet-scale expansion regardless of subsidy availability or infrastructure investment.
For Market Incumbents: Build switching-cost moats through battery-as-a-service subscription lock-in and embedded fleet telematics integration. Deepen backward integration into battery pack assembly to offset raw material volatility. Anchor dealer network viability through EN 15194 certification exclusivity that emerging Asian competitors cannot rapidly replicate. For New Entrants and Emerging Players: Establish a beachhead in French FMD-subsidized SME segments where incumbent coverage remains thin. Target modular cargo platform niches serving Danish seasonal logistics cooperatives. Pursue white-label manufacturing partnerships with Eindhoven-Brabant fabrication clusters to bypass Bosch supply allocation queues. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cycling conglomerates with undermonetized cargo bike divisions lacking fleet telematics capabilities. Five-to-ten year viability hinges on software-hardware integration competence rather than frame fabrication scale. Monitor solid-state battery chemistry convergence as inflection signal for refrigerated logistics segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Launch | Subscription models decouple upfront costs for FMD-qualifying French micro-fleets. |
| Backward Integration into Pack Assembly | In-house lithium-ion production hedges nickel price volatility for German OEMs. |
| Fleet Telematics Platform Partnership | CAN bus protocol standardization reduces redundant engineering cycles across Rotterdam operators. |
| Modular Platform Architecture Investment | Swappable motor mounts extend product lifecycles for Copenhagen seasonal cooperatives. |
| Solid-State Chemistry R&D Alliance | Ceramic electrolyte development unlocks pharmaceutical cold-chain cargo applications. |
Methodological Framework
A spread of perspectives from fleet procurement managers at Dutch postal operators, Bosch drivetrain integration engineers, French FMD subsidy administrators, and Belgian e-grocery logistics coordinators converged on the working assumptions underlying segment sizing. Primary interview insights were cross-referenced against secondary sources including KBA type-approval registration databases, municipal procurement contract disclosures from Rotterdam and Amsterdam, and EU F-Gas Regulation implementation tracking. Bottom-up unit economics from fleet operator TCO models were triangulated against top-down market value reconstruction from frame manufacturer revenue disclosures.
Demand-supply balance dynamics across the analysis window were modeled through fleet replacement cycle timing, subsidy qualification threshold adjustments, and infrastructure deployment commitments. Segmentation dimensions included product architecture, end-user procurement scale, battery chemistry configuration, and price tier positioning. CAGRs were derived from installed base growth trajectories and average selling price evolution across premium and mid-range tiers. Motor controller firmware development timelines and EN 15194 testing capacity constraints were incorporated as industry-specific forecast inputs.
Stress conditions across lithium carbonate price bands, KBA homologation timeline variability, and FMD subsidy renewal political cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification mandate expansion and congestion pricing scheme adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Motorcycle Lighting Market