
 Motorcycle Transmission Control Unit Market | 2026-2036
Motorcycle Transmission Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Transmission Control Unit Market Insights
Over-the-air calibration services is realigning how transmission control value gets captured in the motorcycle sector. Continental AG leverages its embedded software stack to extend recurring revenue beyond hardware shipments. Robert Bosch GmbH anchors its position through R&D intensity in mechatronic integration for automated manual transmissions. ZF Friedrichshafen AG competes on manufacturing scale across European and Asian OEM supply chains.
A motorcycle transmission control unit governs gear selection, clutch engagement, and torque delivery through sensor fusion, actuator commands, and real-time powertrain algorithms operating at millisecond cycle times; its primary purpose is to optimize shift quality, reduce rider workload, and improve fuel economy across varying load conditions. Electronic Control Unit hardware dominates current value pools due to semiconductor content and firmware complexity, while Dual Clutch Transmission technology is capturing the fastest growth trajectory as premium OEMs phase out pure manual gearboxes. The OEM channel sustains higher margin concentration than aftermarket retailers because of bundled programming and warranty obligations.
The EPA enforces emission compliance thresholds that directly mandate precision transmission timing for fuel consumption targets, while EMA oversees European type-approval standards affecting control unit calibration protocols. NHTSA safety regulations in the United States are expanding to include electronic powertrain controls within defect investigation scopes. Stakeholders must monitor how cybersecurity mandates from ISO and regional transport agencies reshape firmware architecture requirements and supplier qualification timelines.
Market Dynamics
Dual clutch transmission systems are forcing a fundamental rearchitecture of motorcycle powertrain electronics as premium OEMs abandon mechanical linkages for fully electronic shift-by-wire architectures.
Growth Catalysts
- Euro 5 emission mandates:European type-approval standards now require precision transmission timing for fuel consumption optimization, compelling electronic control unit integration across mid-displacement platforms.
- Sensor fusion advances:Millisecond-cycle torque management algorithms now integrate IMU data, wheel-speed sensors, and throttle position for predictive shift scheduling.
- India:Domestic OEM electrification roadmaps are accelerating demand for integrated transmission-motor control units in hybrid motorcycle prototypes.
Market Restraints
- Semiconductor supply concentration:Foundry capacity constraints in Taiwan and South Korea create 16-24 week lead times for automotive-grade microcontrollers.
- Technical limitation:Current clutch actuator designs struggle to deliver consistent engagement feel across temperature extremes, limiting adoption in adventure-touring segments.
- Substitution threat:Direct-drive electric motorcycles eliminate multi-speed transmissions entirely, compressing addressable market for control units in urban commuter classes.
Strategic Opportunities
- Japan:Kei-class motorcycle electrification programs create demand for compact, cost-optimized transmission control units with integrated motor inverters.
- Over-the-air calibration:Cloud-connected firmware updates enable recurring revenue streams and reduce warranty claim costs for OEMs.
- Technology convergence:Integration of transmission control with vehicle dynamics control and cornering ABS is creating consolidated ECU architectures.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for clutch actuation systems extends development timelines by 8-14 months.
- Mechatronics talent scarcity:Shortage of engineers with combined firmware, hydraulics, and mechanical design expertise constrains supplier scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Transmission Control Unit Market |
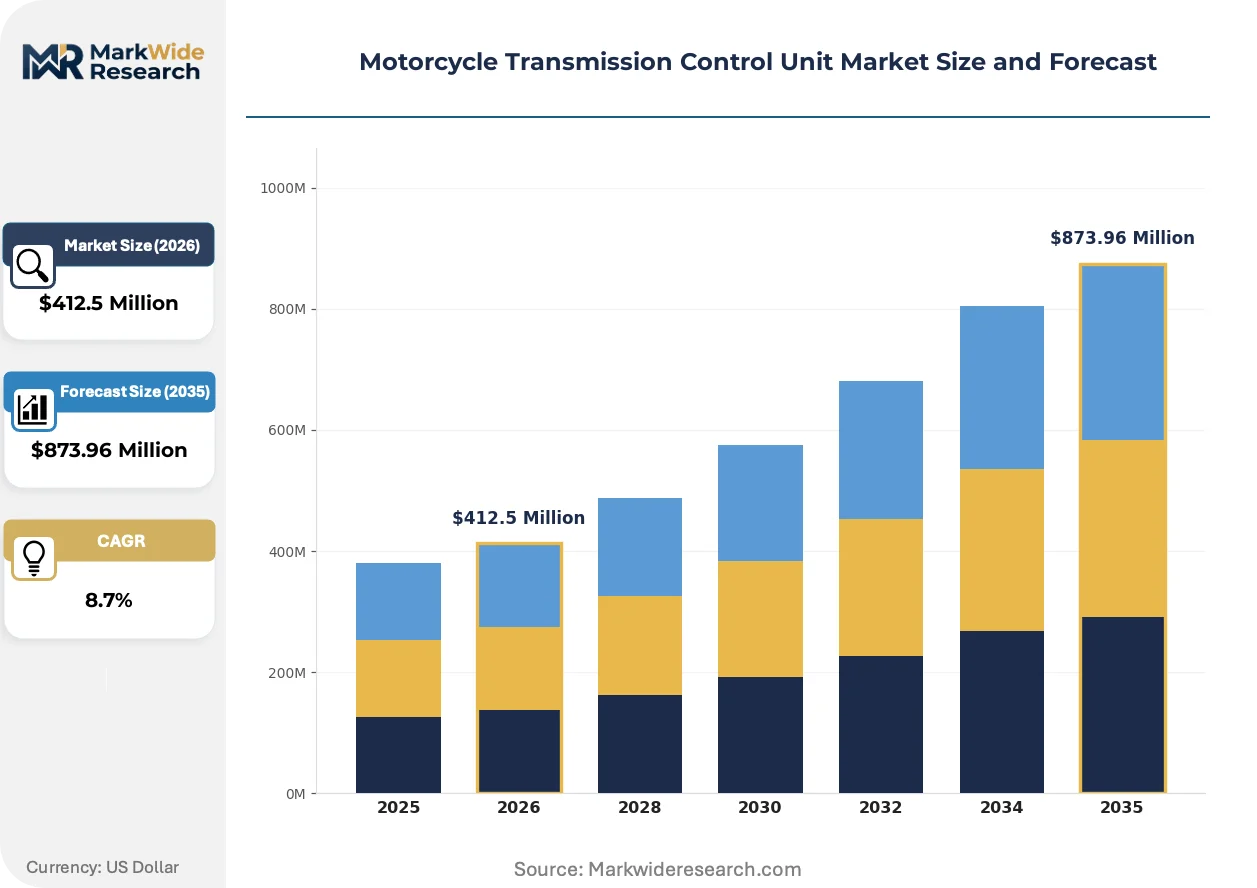
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Control Unit, Hydraulic Control Module, Hybrid Control System, Digital Controller End User: OEMs, Aftermarket Retailers, Service Centers, Fleet Operators Technology: Continuous Variable Transmission, Dual Clutch Transmission, Automated Manual Transmission, Semi-Automated Transmission Application: Recreational Riding, Racing, Commuting, Touring |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Biperformance Development Corp., SEDEMAC Mechatronics Pvt. Ltd., Ricardo Plc, Endurance Technologies Ltd., NXP Semiconductors NV, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Transmission Control Unit Market Trends and Innovations
Software-defined transmission architectures are decoupling hardware from control logic, enabling feature upgrades through firmware rather than physical redesign cycles.
Shift-by-wire actuation is overtaking cable-operated systems in 600cc-plus sportbike segments. Japanese and German OEMs are phasing out mechanical linkages entirely for 2027 model year platforms. The technology is compressing supplier margins on mechanical components while expanding value capture in embedded software and calibration services.
EPA Tier 3 emission regulations now mandate closed-loop fuel trim integration with transmission shift maps. Powertrain engineers must recalibrate every gear change point for particulate matter compliance. The heaviest compliance burden falls on US-market cruiser and touring motorcycles with large-displacement V-twin engines.
Subscription-based feature unlocking is disrupting traditional equipment packaging. Buyers in Germany and Japan now purchase base hardware with dormant capabilities activated through dealer-enabled software licenses. This model is concentrating margin in OEM captive finance and service operations while fragmenting aftermarket accessory demand.
Motorcycle Transmission Control Unit Market Segmentation
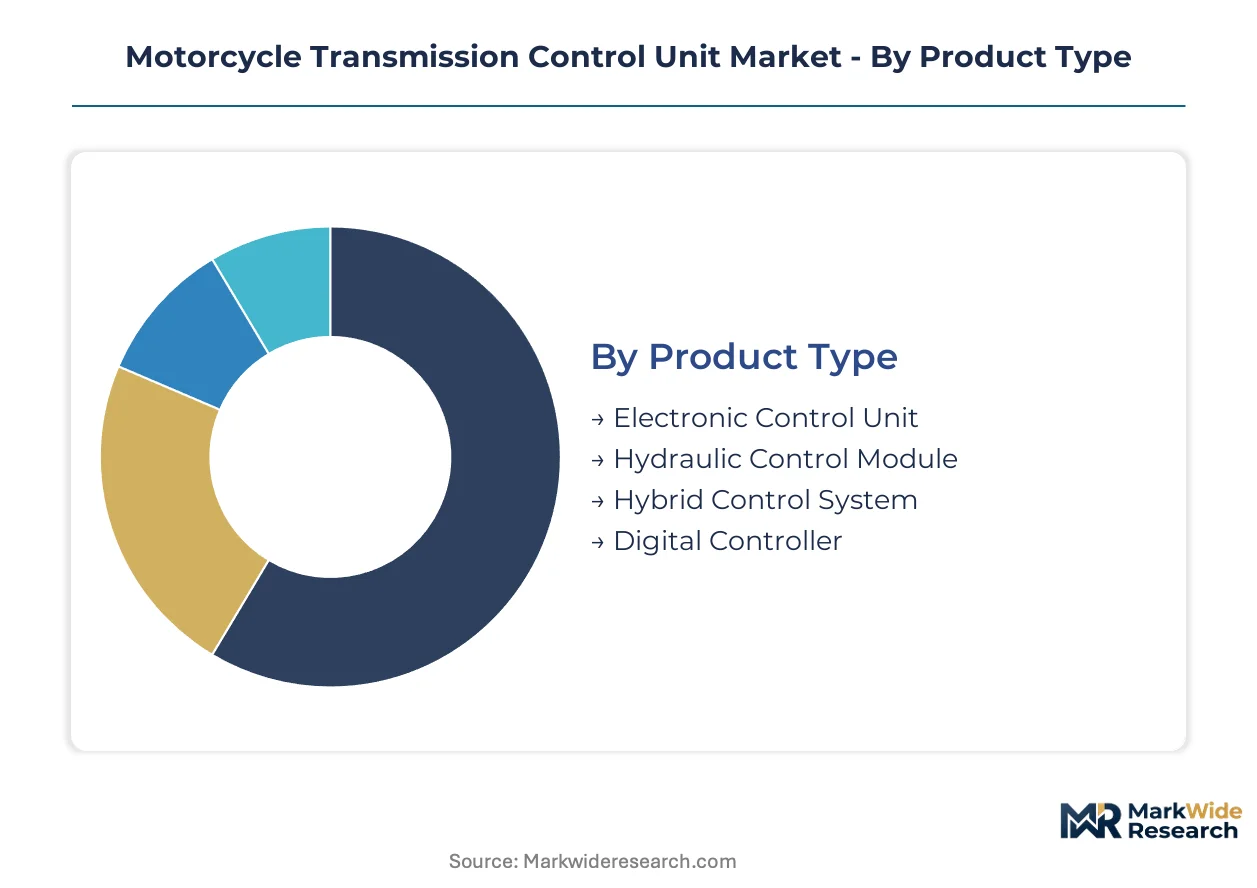
Segmentation in the motorcycle transmission control unit market reveals how powertrain complexity fragments across hardware architectures, customer channels, and riding applications. Each dimension exposes distinct margin structures and supplier qualification barriers that shape competitive positioning.
Product Type:
Cost tier dictates procurement patterns as semiconductor content and firmware licensing fees separate premium from commodity hardware.
- Electronic Control Unit:Embedded microcontroller platforms execute real-time gear selection algorithms with millisecond cycle precision. Demand concentrates in German and Japanese OEM platforms where Euro 5 compliance mandates closed-loop fuel trim integration with transmission shift maps.
- Hybrid Control System:Integrated motor-inverter architectures consolidate transmission and electric powertrain management into unified ECU housings. Indian OEM electrification roadmaps are accelerating prototype procurement for mid-displacement hybrid motorcycles.
- Hydraulic Control Module:Proportional valve assemblies manage clutch engagement pressure through mechatronic actuation.
- Digital Controller:Software-defined architectures decouple control logic from physical hardware for over-the-air feature activation.
Electronic Control Unit leads on scale; Hybrid Control System leads on momentum.
End User:
Margin concentration varies sharply between bundled OEM supply contracts and fragmented service channel economics.
- OEMs:Captive programming and warranty obligations sustain higher margin pools through multi-year supply agreements. German and Japanese manufacturers dominate volume procurement as premium platform adoption accelerates.
- Aftermarket Retailers:Hardware-only sales face margin compression from subscription-based feature unlocking models. German buyers increasingly purchase base hardware with dormant capabilities activated through dealer-enabled software licenses.
- Service Centers:Calibration and firmware update services capture recurring revenue from cloud-connected architectures.
- Fleet Operators:Standardized maintenance protocols drive demand for interchangeable control module platforms.
OEMs anchor volume concentration; Service Centers capture expanding share from connected vehicle services.
Technology:
Application requirements determine actuator complexity and sensor fusion demands across riding disciplines.
- Dual Clutch Transmission:Twin-clutch architectures enable seamless torque delivery through predictive shift scheduling without rider clutch operation. Premium sportbike segments in Japan and Germany are phasing out mechanical linkages entirely for shift-by-wire implementations.
- Automated Manual Transmission:Single-clutch automated systems preserve mechanical efficiency while reducing rider workload in urban commuting.
- Continuous Variable Transmission:Pulley-based ratio systems optimize engine speed for fuel economy in small-displacement platforms.
- Semi-Automated Transmission:Rider-initiated shifts with automated clutch actuation bridge manual and fully automatic experiences.
Dual Clutch Transmission commands premium positioning; Automated Manual Transmission expands most quickly in cost-sensitive commuter classes.
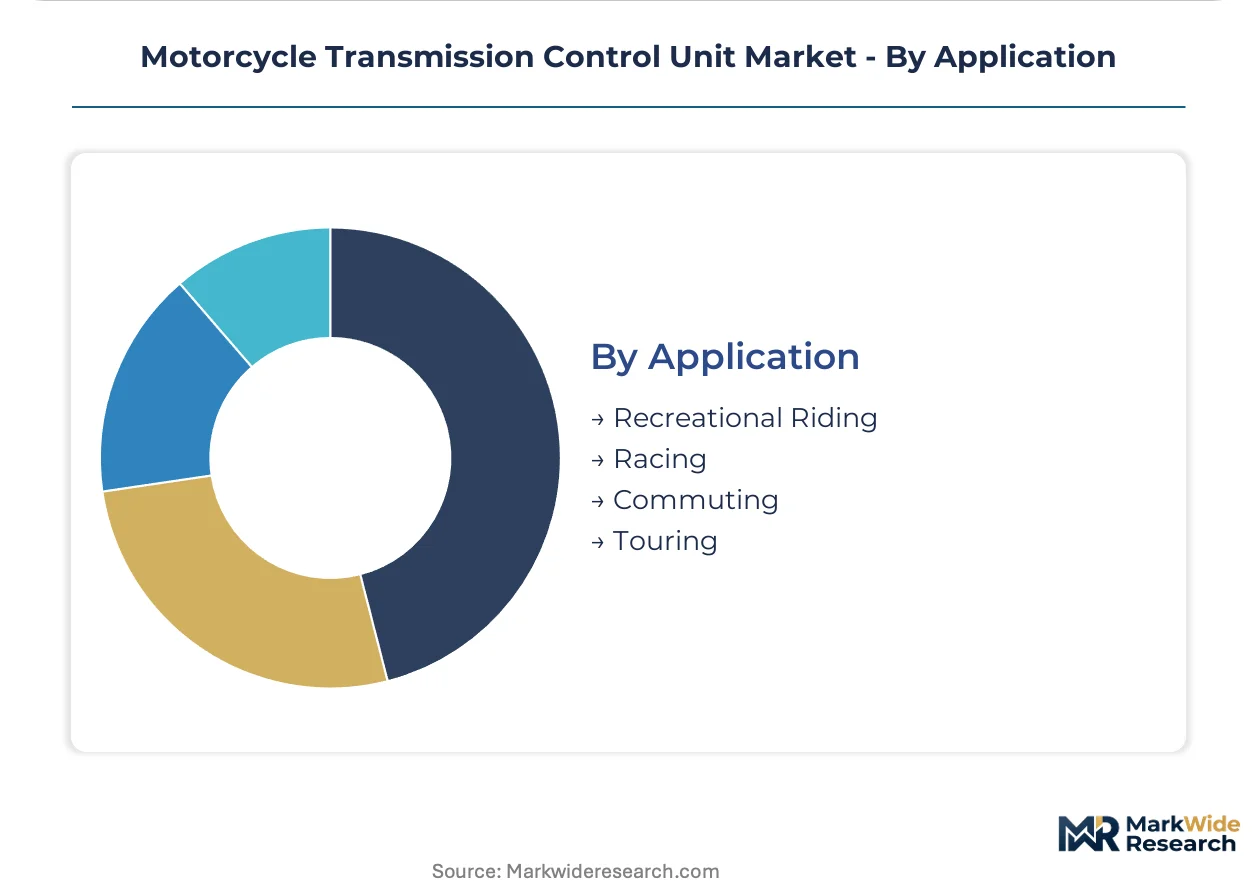
Application:
Riding intensity and duty cycle variation determine control algorithm sophistication and thermal management requirements.
- Racing:Millisecond-cycle torque management with IMU integration enables predictive shift scheduling under extreme load conditions. Professional competition platforms demand ASIL-D functional safety certification extending supplier development timelines.
- Touring:Long-distance thermal stability and consistent clutch engagement feel across temperature extremes constrain adventure-touring segment adoption.
- Recreational Riding:Weekend-use duty cycles prioritize shift quality refinement over absolute durability metrics.
- Commuting:Stop-start traffic patterns favor automated clutch actuation to reduce rider fatigue.
Racing drives technology specification; Commuting offers the steepest expansion trajectory as urban congestion intensifies automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
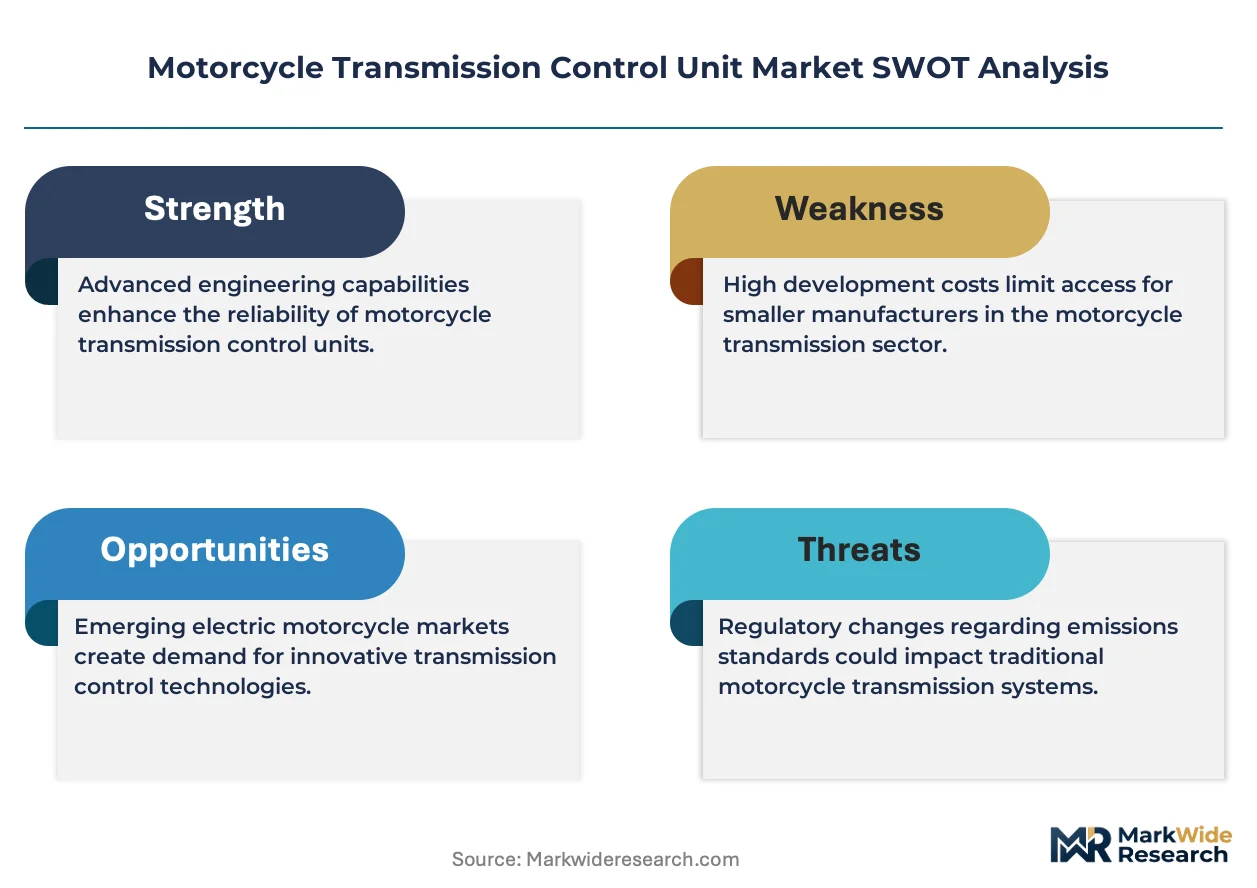
Germany and Japan demonstrate contrasting transmission control strategies, with German OEMs prioritizing shift-by-wire premiumization while Japanese manufacturers accelerate kei-class electrification programs. India bridges both approaches through hybrid motorcycle prototypes that merge cost optimization with regulatory compliance.
Germany
BMW Motorrad and KTM drive dual clutch transmission adoption across 800cc-plus sport touring platforms. KBA enforces Euro 5 emission type-approval standards that mandate closed-loop fuel trim integration with transmission shift maps. Stuttgart-based supplier clusters concentrate mechatronics R&D for automated manual transmission architectures.
Japan
Honda and Yamaha prototype integrated motor-inverter transmission control units for 125cc hybrid commuter motorcycles. METI subsidizes kei-class electrification roadmaps through Green Innovation Fund allocations. Nagoya industrial corridors host precision actuator manufacturing for millisecond-cycle clutch engagement systems.
India
Hero MotoCorp and TVS Motor Company develop hybrid transmission-motor control units for mid-displacement platforms targeting ASEAN export markets. BIS certification requirements for electronic powertrain components extend supplier qualification timelines. Pune and Chennai manufacturing clusters scale domestic ECU assembly to reduce semiconductor import dependency.
United States
Harley-Davidson and Indian Motorcycle recalibrate large-displacement V-twin shift maps for EPA Tier 3 particulate matter compliance. NHTSA defect investigation scopes now encompass electronic powertrain controls. Milwaukee and Spirit Lake engineering centers integrate over-the-air calibration infrastructure for touring motorcycle fleets.
South Korea
Hyosung and Daelim Motor prioritize compact dual clutch systems for 250-400cc urban commuter segments. MFDS automotive-grade semiconductor sourcing requirements intersect with transmission control unit procurement protocols. Seoul Capital Area foundry partnerships secure automotive microcontroller supply for 2027 model year platforms.
Motorcycle Transmission Control Unit Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one automotive suppliers commanding OEM bundled programming contracts while domestic fabricators capture aftermarket calibration services. The vendor base concentrates among mechatronics integrators with ISO 26262 functional safety certification and semiconductor vendors with automotive-grade microcontroller portfolios. Three archetypes dominate: European full-system suppliers, Asian component specialists, and semiconductor platform providers. Competitive moves center on firmware licensing partnerships and captive foundry capacity allocation.
Within the European full-system tier, Continental AG and Robert Bosch GmbH anchor premium OEM supply relationships through embedded software stacks and mechatronic integration capabilities. ZF Friedrichshafen AG occupies a scale-driven position across European and Asian manufacturing footprints. Among semiconductor platform providers, NXP Semiconductors NV and Infineon Technologies AG exemplify automotive-grade microcontroller suppliers whose silicon content underpins transmission control unit hardware value pools.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Biperformance Development Corp. |
| SEDEMAC Mechatronics Pvt. Ltd. |
| Ricardo Plc |
| Endurance Technologies Ltd. |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
German and Japanese premium OEM procurement concentration sustains contract-based long-term offtake pricing with embedded firmware licensing fees, while Indian domestic manufacturers compress hardware margins through volume-scale negotiations and localized assembly incentives.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for automotive-grade microcontrollers that dominate ECU hardware value pools. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified dual-clutch systems from basic automated manual transmissions and commodity hydraulic modules. Cost compression in the economy tier is intensifying because foundry capacity constraints force allocation prioritization toward higher-margin silicon. Fleet operators and Indian domestic OEMs exhibit the highest price sensitivity, while German premium sportbike manufacturers absorb firmware licensing premiums with minimal negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BMW Motorrad, Honda, and Hero MotoCorp through multi-year supply agreements with embedded calibration services. Semiconductor fabrication concentrates in Taiwan, South Korea, and Germany, while precision actuator manufacturing clusters in Japan and Stuttgart. The supply chain draws from automotive-grade microcontroller wafers, rare-earth magnet materials for clutch actuators, and specialized hydraulic valve alloys. Single-source vulnerability around Taiwan foundry capacity represents the dominant structural risk. Distribution runs through captive Tier 1 supplier networks with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margins are expanding through software-defined transmission architectures that decouple hardware from control logic, enabling recurring revenue from over-the-air calibration while reducing physical redesign costs.
For Market Incumbents: Anchor defensive positioning through captive foundry capacity allocation in Taiwan and South Korea to secure automotive-grade microcontroller supply against emerging fabless competitors. Deepen backward integration into clutch actuator mechatronics to preserve margin pools as shift-by-wire architectures displace mechanical component suppliers. ISO 26262 ASIL-D certification investment extends development timelines but creates qualification barriers that protect long-term OEM relationships.
For New Entrants and Emerging Players: Euro 5 emission mandates in Germany open a window for specialized calibration service providers targeting mid-displacement platform compliance. White-space concentration exists in Indian hybrid motorcycle transmission-motor control units and Japanese kei-class electrification programs where domestic OEMs seek cost-optimized integrated architectures. A firmware-first go-to-market angle bypasses capital-intensive hardware manufacturing while capturing recurring revenue from cloud-connected update services.
For Investors and Strategic Acquirers: Tier 1 automotive electronics suppliers are the most active acquirer in this space, consolidating embedded software stacks and mechatronics capabilities to serve converging powertrain control architectures. The 5-10 year viability window favors targets with ISO 26262 certification and existing OEM supply relationships over pure-play semiconductor distributors. Watch direct-drive electric motorcycle penetration in urban commuter segments as the critical inflection indicator for transmission control unit addressable market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Transmission Architecture | Decouples control logic from hardware to enable over-the-air feature activation and recurring revenue streams. |
| Captive Foundry Capacity Allocation | Secures automotive-grade microcontroller supply from Taiwan and South Korea against allocation competition. |
| ISO 26262 ASIL-D Certification Investment | Extends development timelines but creates qualification barriers protecting premium OEM supply relationships. |
| Backward Integration into Clutch Actuator Mechatronics | Preserves margin pools as shift-by-wire architectures displace mechanical component suppliers. |
| Hybrid Powertrain Control Unit Convergence | Integrates transmission and motor inverter management to capture Indian and Japanese electrification procurement. |
Research Methodology
Multiple input streams — OEM platform engineering directors, Tier 1 supplier procurement leads, semiconductor foundry account managers, and aftermarket calibration service operators — were reconciled against vehicle production databases, IHS Markit registration data, EPA emission certification filings, and KBA type-approval records. Bottom-up unit demand estimates across dual-clutch, automated manual, and hybrid control architectures were cross-validated through top-down value-chain analysis. Primary fieldwork with transmission control firmware developers and mechatronics R&D directors in Stuttgart and Nagoya informed technology adoption trajectory assumptions.
Historical shipment patterns were cross-referenced against panel input from OEM platform planners to construct the analytical framework across the analysis window. Segmentation dimensions modeled include transmission technology type, displacement class, OEM tier positioning, and regional regulatory compliance cluster. CAGRs were derived through iterative reconciliation of unit volume projections with semiconductor content value per unit. Forecast inputs incorporated Euro 5 and EPA Tier 3 compliance timelines, kei-class electrification subsidy programs, and direct-drive electric motorcycle substitution curves.
Revisions become necessary when foundry capacity allocation priorities shift, cybersecurity mandates from ISO reshape firmware architecture requirements, or direct-drive electric motorcycle penetration accelerates beyond baseline assumptions. Forecasts reflect documented assumptions regarding OEM platform electrification roadmaps and regulatory compliance phase-in schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market