
 Hybrid EV Conversion Kit Market | 2026-2036
Hybrid EV Conversion Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid EV Conversion Kit Market Analysis
Shortage of certified high-voltage technicians is redrawing competitive boundaries across the conversion ecosystem. XL Fleet Corp. leverages fleet-scale installation protocols to anchor recurring commercial contracts, while A123 Systems LLC sustains cell supply relationships that dominate aftermarket battery sourcing. Zelectric Motors, Inc. specializes in air-cooled motor integrations that occupy a defensible niche within vintage vehicle electrification.
A hybrid EV conversion kit retrofits internal-combustion vehicles with electric drivetrain components including lithium-ion battery packs rated between 10 kWh and 40 kWh, power controllers managing 400V architectures, and AC induction or permanent-magnet synchronous motors coupled through custom adapter plates. Its primary purpose extends vehicle service life while reducing tailpipe emissions and fuel expenditure for operators unable to purchase new electric platforms. Batteries command the dominant margin pool within product type segmentation due to cell procurement scale requirements, while plug-in hybrid technology leads technology adoption because it preserves range flexibility for commercial operators with variable route lengths. Professional installation channels capture premium pricing over DIY kits, reflecting liability exposure and warranty underwriting costs.
Federal EPA tailpipe standards and NHTSA conversion compliance protocols govern road-legal retrofit specifications in the United States, while EU REACH chemical restrictions and CE marking requirements shape battery import and component sourcing across European markets. These frameworks elevate engineering validation costs but simultaneously filter low-quality entrants, consolidating demand toward suppliers with documented homologation capabilities. Stakeholders must weigh certification investment timelines against the window for capturing fleet retrofit contracts before OEM new-vehicle pricing compresses conversion economics.
Market Dynamics
Solid-state battery chemistry is compressing pack costs and extending range for converted vehicles, redrawing competitive boundaries as suppliers race to secure cell supply relationships and certified installation capacity.
Growth Catalysts
- Federal tax incentives:Brazil's federal retrofit subsidies have created dense conversion clusters around São Paulo and Curitiba, accelerating municipal fleet electrification timelines.
- REACH chemical restrictions:EU battery import protocols are filtering low-quality entrants and consolidating demand toward suppliers with documented homologation capabilities.
- Legacy diesel fleet mandates:Latin American municipal bus operators are electrifying existing vehicles rather than purchasing new platforms, preserving capital expenditure flexibility.
Market Restraints
- Lithium cell procurement volatility:Battery chemistry improvements require scale commitments that strain working capital for mid-tier conversion specialists.
- EPA tailpipe compliance:Federal validation protocols elevate engineering costs and extend homologation timelines for road-legal retrofit specifications.
- OEM new-vehicle pricing compression:Falling electric platform costs threaten conversion economics as fleet buyers compare retrofit investment against factory-built alternatives.
Strategic Opportunities
- Vintage vehicle electrification:Air-cooled motor integrations occupy a defensible niche for classic car collectors seeking emission compliance without platform replacement.
- Professional installation channels:Liability exposure and warranty underwriting costs are pushing fleet operators toward certified service networks over DIY kit procurement.
- Plug-in hybrid flexibility:Commercial operators with variable route lengths are prioritizing range-preserving architectures over full battery-electric conversions.
Industry Challenges
- Certified high-voltage technician scarcity:The shortage of qualified installers is constraining installation throughput and extending project backlogs for fleet-scale contracts.
- 400V architecture integration complexity:Custom adapter plate fabrication and power controller calibration require specialized tooling that fragments supplier capabilities.
- NHTSA conversion compliance timelines:Documentation requirements for road-legal status create execution risk for retrofit projects with fixed fleet renewal deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid EV Conversion Kit Market |
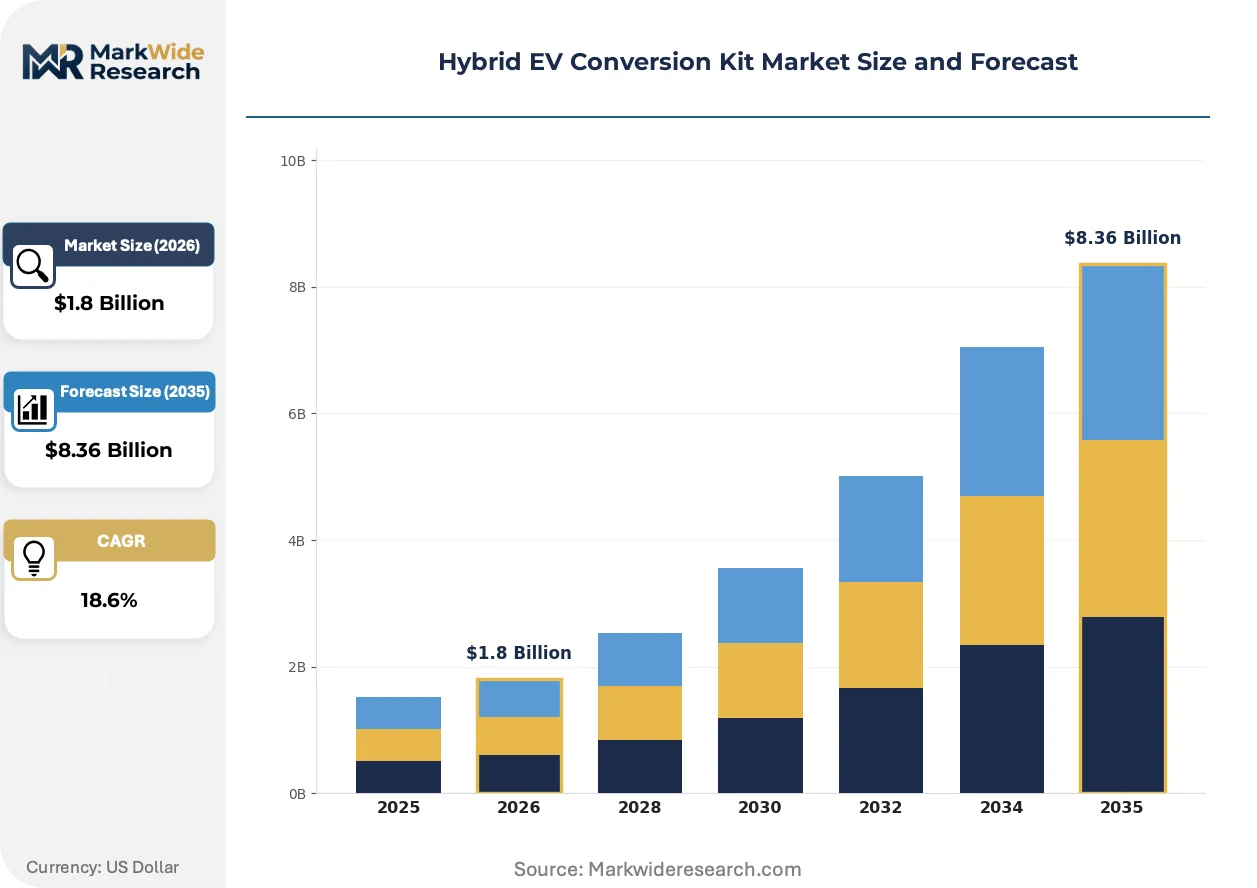
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Controllers, Motors, Adapters End User: Commercial Fleets, Individual Owners, OEMs, Retrofit Shops Technology: Plug-in Hybrid, Series Hybrid, Parallel Hybrid, Mild Hybrid Installation Type: DIY Kits, Professional Installation, Mobile Services, Fixed Facilities |
| Companies Covered | XL Fleet Corp., Electro Automotive, EV West, Electric GT Ltd., A123 Systems LLC, Stealth EV, EVDrive, Zelectric Motors, Inc., Zero EV Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid EV Conversion Kit Market Emerging Trajectories
Conversion kit architectures are pivoting toward modular battery configurations that accommodate diverse vehicle platforms without complete drivetrain redesign, compressing development cycles for specialist suppliers.
Permanent-magnet synchronous motors paired with silicon carbide inverters are displacing AC induction alternatives in commercial retrofit specifications. Municipal bus operators across Brazil and Mexico are specifying these architectures for their superior torque density and thermal efficiency. The shift is compressing maintenance intervals and enabling longer service routes for electrified legacy fleets.
EU REACH chemical restrictions and CE marking requirements are reshaping battery import and component sourcing across European markets. These frameworks elevate engineering validation costs but simultaneously filter low-quality entrants. Suppliers with documented homologation capabilities are capturing consolidated demand from fleet operators seeking compliance certainty.
Buying patterns among commercial operators are pivoting from component procurement toward turnkey installation contracts. Fleet managers are unbundling hardware acquisition from certified service provision, prioritizing warranty coverage and liability transfer over unit cost minimization. This shift is most visible in Brazil, where federal incentive programs require professional installation for tax credit eligibility.
Hybrid EV Conversion Kit Market Segmentation
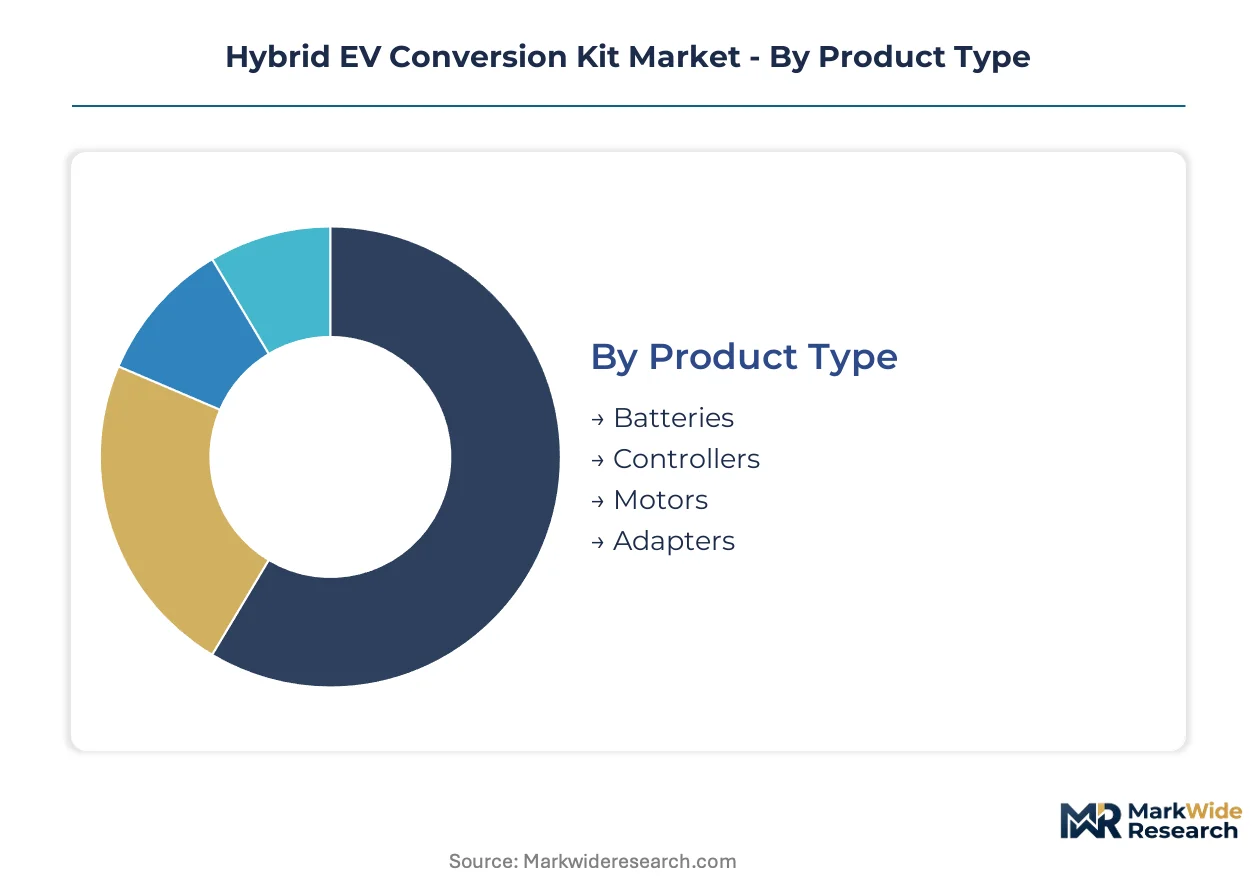
Segmentation in the Hybrid EV Conversion Kit Market reveals how margin pools concentrate around battery procurement scale and certified installation capacity. Fleet operators prioritize technology architectures that preserve range flexibility while minimizing downtime during retrofit execution.
Product Type:
Margin pools concentrate heaviest in cell procurement and pack integration, where scale commitments separate viable suppliers from assembly-only operations.
- Batteries:Lithium-ion packs rated between 10 kWh and 40 kWh dominate material cost structures. Brazilian municipal bus operators around São Paulo and Curitiba are specifying these configurations to qualify for federal retrofit subsidies while extending diesel fleet service life.
- Controllers:Power management units governing 400V architectures require specialized firmware calibration. Demand clusters among commercial fleets seeking warranty-backed performance guarantees rather than component-only procurement.
- Motors:AC induction and permanent-magnet synchronous variants couple through custom adapter plates.
- Adapters:Custom fabrication components bridge legacy drivetrain mounting points to electric motor geometries.
Batteries hold installed capacity. Controllers are rotating up the share rankings.
End User:
Volume concentrates in fleet-scale contracts where installation throughput and liability transfer override unit cost minimization.
- Commercial Fleets:Municipal bus operators and logistics companies electrify legacy platforms to preserve capital expenditure flexibility. Latin American cities are accelerating these programs as diesel phase-out mandates tighten compliance timelines.
- Individual Owners:Classic car collectors pursue vintage vehicle electrification for emission compliance without platform replacement. Zelectric Motors has carved defensible positioning through air-cooled motor integrations suited to collector vehicle constraints.
- OEMs:Factory-authorized retrofit programs extend brand service revenue from aging vehicle populations.
- Retrofit Shops:Independent installers capture demand from price-sensitive operators seeking non-dealer service options.
Commercial Fleets anchor current volume. Individual Owners are climbing the fastest as regulatory compliance deadlines approach.
Technology:
Application requirements dictate architecture selection, with route predictability determining the optimal hybrid configuration.
- Plug-in Hybrid:Range-preserving systems combining electric drive with combustion backup dominate commercial specifications. Variable route lengths across Brazilian and Mexican municipal networks favor this flexibility over full battery-electric commitment.
- Series Hybrid:Engine-generator configurations decouple combustion RPM from wheel speed for optimized efficiency. Fixed-route delivery fleets in urban density corridors are specifying these architectures for stop-start operational profiles.
- Parallel Hybrid:Mechanical coupling allows direct engine-to-wheel power flow alongside electric assist.
- Mild Hybrid:Belt-integrated starter-generator systems provide limited electric boost without full drivetrain redesign.
Plug-in Hybrid maintains production scale. Series Hybrid is gaining share fastest among route-optimized deployments.
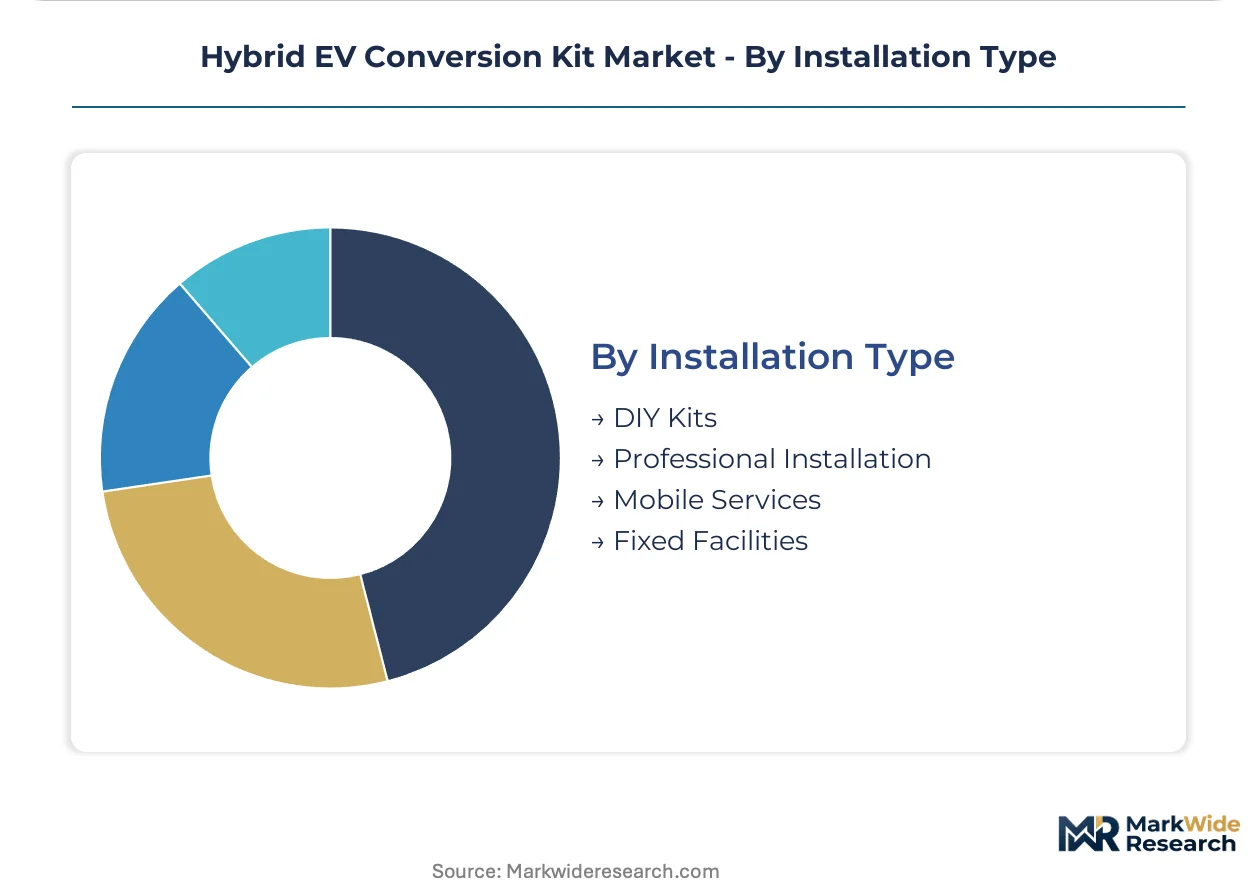
Installation Type:
Channel economics fragment between liability-conscious fleet procurement and cost-driven individual conversions.
- Professional Installation:Certified service networks command premium pricing reflecting warranty underwriting and NHTSA compliance documentation. Brazil's federal incentive programs mandate this channel for tax credit eligibility, consolidating demand toward homologation-capable suppliers.
- DIY Kits:Component-only procurement appeals to technically proficient individual owners with access to high-voltage safety training. Scarcity of certified technicians constrains this channel's expansion despite lower upfront cost positioning.
- Mobile Services:Deployable installation units reduce vehicle downtime for fleet operators with constrained depot access.
- Fixed Facilities:Dedicated conversion centers concentrate specialized tooling and technician expertise for complex platform adaptations.
Professional Installation holds certified capacity. Mobile Services are rotating up the share rankings as fleet operators prioritize uptime minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's ANVISA and federal transport regulators anchor the dominant geography through retrofit subsidy frameworks that compress payback periods for municipal fleet operators. Conversion demand clusters around São Paulo and Curitiba where dense service networks support high-volume electrification programs.
United States
Fleet-scale operators and vintage vehicle collectors drive retrofit demand across California and the Pacific Northwest. NHTSA conversion compliance protocols and EPA tailpipe standards govern road-legal specifications, elevating engineering validation costs. Installation capacity concentrates in Greater Los Angeles and Detroit metro areas where certified high-voltage technicians cluster around legacy automotive infrastructure.
Germany
Industrial fleet operators and classic car enthusiasts sustain conversion activity amid stringent emission zone expansions in Berlin and Hamburg. KBA homologation requirements and EU REACH chemical restrictions shape battery import protocols. Conversion specialists cluster in Baden-Württemberg and Bavaria where automotive supplier density supports adapter plate fabrication and power controller calibration.
China
Municipal bus operators and logistics fleets electrify legacy diesel platforms under MIIT industrial policy directives and dual carbon goals. GB standards govern high-voltage system safety and battery pack integration. Yangtze River Delta manufacturing hubs around Shanghai and Suzhou concentrate cell procurement scale and motor controller production capacity.
United Kingdom
London's ultra-low emission zone penalties and corporate fleet sustainability mandates accelerate commercial retrofit adoption. DVSA type approval requirements and CE marking obligations filter supplier entry. Conversion activity clusters in the Midlands and Southeast England where automotive engineering heritage supports custom adapter fabrication and 400V architecture integration.
Japan
Kei car owners and commercial delivery fleets pursue mild-hybrid conversions amid METI energy efficiency targets and urban emission restrictions. JIS standards and PMDA-adjacent safety protocols influence component sourcing. Industrial concentration in Aichi Prefecture and Osaka-Kobe corridors provides precision machining capacity for motor mounting adaptations.
Hybrid EV Conversion Kit Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with cell chemistry specialists commanding premium positioning while assembly-focused operators compete on installation throughput. The vendor base separates into three strategic tiers: integrated battery-pack suppliers with captive cell relationships, modular kit assemblers sourcing components from tier-two vendors, and certified installation networks underwriting warranty liability. Dominant competitive moves include backward integration into cell procurement and geographic expansion of homologation-capable service footprints.
Among North American fleet-scale specialists, XL Fleet Corp. and Zelectric Motors, Inc. occupy differentiated archetype positions, with the former anchoring commercial retrofit contracts and the latter exemplifying vintage vehicle electrification positioning. A123 Systems LLC represents the cell supply tier that underpins aftermarket battery sourcing relationships across multiple kit assemblers.
| Leading Market Players |
|---|
| XL Fleet Corp. |
| Electro Automotive |
| EV West |
| Electric GT Ltd. |
| A123 Systems LLC |
| Stealth EV |
| EVDrive |
| Zelectric Motors, Inc. |
| Zero EV Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Brazilian municipal fleet operators and battery pack integrators lock in lithium cell supply access while compressing price visibility across the conversion ecosystem. These arrangements concentrate procurement leverage among operators qualifying for ANVISA-compliant federal retrofit subsidies, fragmenting pricing power toward assembly specialists with documented homologation capabilities.
Pricing Analysis
Brazilian conversion clusters command premium pricing over Mexican and Argentine counterparts due to ANVISA certification requirements and warranty underwriting costs. Three-tier pricing structure across certified professional installation, homologation-capable kit supply, and unverified component sourcing separates margin pools. Cost compression in economy-tier DIY kits is intensifying because lithium cell procurement volatility strains working capital for mid-tier specialists. Individual owners exhibit highest price sensitivity, while municipal bus operators prioritize liability transfer over unit cost minimization.
Supply Chain Analysis
Port congestion across Yangtze River Delta corridors elevates inbound logistics costs for power controllers and silicon carbide inverters destined for Latin American assembly facilities. Cell manufacturing concentrates in China, South Korea, and Japan, while custom adapter plate fabrication clusters in Germany and Brazil. The supply chain draws from lithium carbonate, nickel sulfate, and rare-earth magnet inputs. Single-source vulnerability around solid-state electrolyte precursors threatens throughput for next-generation pack integrators. Distribution runs through OEM-authorized retrofit networks and independent certified installation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the conversion kit ecosystem creates niche opportunities as fleet procurement patterns pivot from component sourcing toward turnkey installation contracts. This demand-side shift rewards specialists combining homologation capabilities with certified technician networks.
For Market Incumbents: Fortify cell supply relationships through backward integration into lithium procurement or captive offtake agreements with South Korean and Chinese cathode producers. Expand certified installation capacity in São Paulo and Curitiba to capture Brazilian federal subsidy flows before OEM new-vehicle pricing compresses conversion economics. Prioritize NHTSA compliance documentation investments to filter low-quality competitors from road-legal retrofit specifications. For New Entrants and Emerging Players: Differentiate on air-cooled motor architectures for vintage vehicle electrification, where Zelectric Motors has validated collector willingness to pay emission-compliance premiums. Target individual owners in California and Germany's classic car corridors as the most penetrable segment underserved by fleet-scale specialists. Pursue mobile installation service models to minimize fleet operator downtime and secure recurring maintenance contracts. For Investors and Strategic Acquirers: Homologation-capable mid-tier assemblers with documented REACH compliance and Brazilian ANVISA certification represent the highest-conviction acquisition archetype for portfolio exposure to fleet electrification tailwinds. Long-term viability hinges on conversion economics persisting against falling OEM battery-electric platform pricing across the next decade. Watch NHTSA and EPA regulatory relaxation timelines as the critical inflection signal for DIY kit channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium cell access for Brazilian municipal fleet contracts under ANVISA subsidy frameworks. |
| Certification Investment | Accelerates NHTSA homologation timelines to capture road-legal retrofit demand from US commercial operators. |
| Geographic Manufacturing Footprint | Establishes adapter plate fabrication capacity in Baden-Württemberg to serve EU REACH-compliant battery imports. |
| Charging Infrastructure Partnership | Integrates plug-in hybrid architectures with depot charging networks across São Paulo municipal bus routes. |
| Platform Standardization | Reduces custom engineering costs through modular battery configurations spanning diverse legacy vehicle platforms. |
Methodological Framework
A standing panel of fleet procurement directors, certified high-voltage technicians, battery pack integration engineers, and ANVISA compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA tailpipe standard filings, NHTSA conversion compliance documentation, EU REACH chemical restriction registries, and Brazilian federal transport subsidy records. Bottom-up unit economics modeling triangulated against top-down fleet electrification expenditure projections from municipal budget disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented demand by propulsion architecture, installation channel, vehicle platform vintage, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating battery chemistry cost trajectories and certified technician supply constraints. Solid-state cell development timelines and OEM battery-electric platform pricing curves served as industry-specific forecast inputs.
Material uncertainties — lithium cell procurement volatility, NHTSA compliance timeline extensions, and OEM new-vehicle pricing compression — sit outside the modeled envelope. Forecasts reflect assumptions about federal subsidy continuity and homologation capability scarcity persisting across the analysis window. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market