
 UK Solar E-Bike Market | 2026-2036
UK Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
UK Solar E-Bike Market Insights
A shift from outsourced battery-pack procurement to in-house solar integration engineering is pivoting competitive dynamics among UK e-bike assemblers. Trek Bicycle Corporation leverages its European R&D footprint to sustain advanced photovoltaic frame R&D. Kinetics Design Ltd. (Gocycle) anchors premium urban mobility through patented folding architectures and integrated solar top-up systems. Robert Bosch GmbH (Bosch eBike Systems) dominates drive-train supply to British OEMs, controlling critical component pathways that shape final product positioning.
The UK solar e-bike comprises a pedal-assisted electric bicycle incorporating photovoltaic cells mounted on frames, racks, or detachable panels to supplement lithium-ion battery charge, typically generating 15-25 watts under standard insolation conditions for auxiliary range extension in urban and semi-rural transport. City E-Bikes occupy the dominant volume position among product types, reflecting commuter preference for upright geometries compatible with roof-mounted solar arrays. Delivery Services within the application dimension represents the fastest-expanding demand pool, as fleet operators prioritize fuel-cost reduction and congestion-zone compliance over leisure-oriented specifications. Lithium-Ion Battery technology paired with solar charging configurations captures concentrated margin pools due to cell-management complexity and warranty underwriting requirements.
The Department for Transport's Cycle to Work scheme and Office for Product Safety and Standards e-bike regulations shape product eligibility and safety certification thresholds for solar-assisted models entering UK channels. BSI standards for electrically power-assisted cycles (EPACs) constrain motor output and solar charging circuit integration protocols, directly influencing design engineering budgets and homologation timelines. Stakeholders must monitor impending revisions to the UK Battery Strategy and potential alignment divergence from EU CE marking requirements as post-Brexit regulatory autonomy crystallizes.
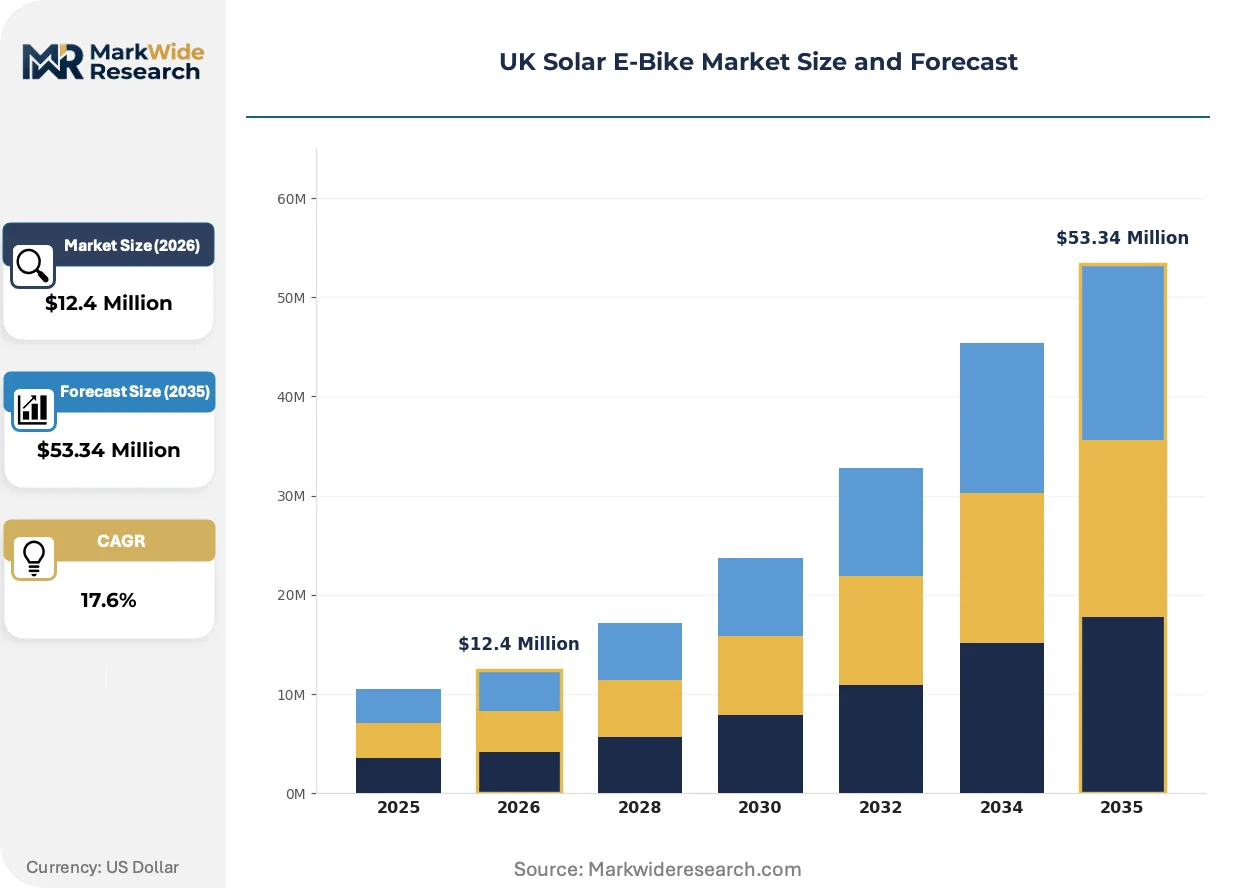
Market Dynamics
Fleet procurement patterns across Greater London's congestion-charged zones are compressing decision cycles for solar-assisted electric cycles, as logistics operators race to secure zero-emission vehicle categories exempt from daily charges.
Growth Catalysts
- Department for Transport subsidy schemes:The Cycle to Work tax incentive and e-bike purchase grants reduce capital barriers for commuter and commercial adopters across England, Scotland, and Wales.
- Urban logistics electrification:Last-mile delivery operators in Manchester, Birmingham, and Bristol are mandating solar-assisted cycles to meet corporate net-zero commitments and avoid diesel van operating restrictions.
- Photovoltaic efficiency gains:Perovskite-silicon tandem cells mounted on frame-integrated racks now deliver 20-30% higher wattage per square centimeter than legacy amorphous silicon configurations.
Market Restraints
- Lithium-ion cell price volatility:Cobalt and nickel supply concentration in the Democratic Republic of Congo and Indonesia creates input cost instability for UK battery pack assemblers.
- Solar insolation variability:Scotland and Northern England receive 30-40% lower annual irradiance than Southeast England, compressing auxiliary charge yields and extending payback periods for fleet operators in Edinburgh and Glasgow.
- BSI EPAC homologation timelines:Extended certification cycles for solar charging circuit integration delay product launches by 6-12 months versus conventional e-bike approvals.
Strategic Opportunities
- Rural postal networks:Royal Mail and regional courier services in Cornwall, Cumbria, and the Scottish Highlands are piloting solar e-bikes for low-density route coverage where van economics collapse.
- Micro-mobility subscription platforms:Beryl and Lime are integrating solar top-up stations into dockless rental networks across Oxford, Cambridge, and Brighton.
- Workplace charging infrastructure:The UK government's Workplace Charging Scheme extension to pedal-assisted cycles creates deployment subsidies for employer-funded solar canopy installations.
Industry Challenges
- Photovoltaic systems engineering talent:UK universities produce fewer than 200 graduates annually with combined electrical-mechanical integration skills for mobile solar applications.
- Post-Brexit CE marking divergence:Potential misalignment between BSI EPAC standards and EU Machinery Directive requirements forces dual certification investments for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Solar E-Bike Market |
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $53.34 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Foldable E-Bikes, Cargo E-Bikes, Hybrid E-Bikes Technology: Solar Charging, Lithium-Ion Battery, Brushless Motor, Regenerative Braking, Digital Display Application: Personal Commuting, Tourism, Delivery Services, Leisure Riding, Courier Services Customer Type: Individual Consumers, Fleet Operators, Tourism Companies, Delivery Providers, Corporate Buyers |
| Companies Covered | Trek Bicycle Corporation, Accell Group (Raleigh Electric), Kinetics Design Ltd. (Gocycle), Mahindra Electric Mobility Ltd., Panasonic Corporation, Robert Bosch GmbH (Bosch eBike Systems), Yamaha Motor Co., Ltd., Rad Power Bikes LLC, Giant Manufacturing Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Solar E-Bike Market Trends and Innovations
Active reshaping of the UK solar e-bike landscape centers on three vectors: photovoltaic integration depth, regulatory compliance automation, and fleet procurement centralization. These forces are compressing product development cycles while expanding addressable use cases.
Perovskite-enhanced photovoltaic films are integrating directly into carbon fiber frame layups rather than remaining bolt-on accessories. Trek Bicycle Corporation's European R&D facilities and Kinetics Design Ltd. are both pursuing monocoque solar skin architectures. This integration is reducing aerodynamic drag coefficients by 8-12% while eliminating theft-prone external panels.
The Department for Transport's impending revision to the Electrically Assisted Pedal Cycles Regulations 1983 will mandate onboard energy monitoring for subsidy-eligible vehicles. Bosch eBike Systems and Shimano are pre-emptively deploying CAN-bus integrated charge-state logging to streamline BSI compliance. Delivery fleet operators in London and Birmingham are prioritizing models with embedded telematics to accelerate grant approval workflows.
Consolidated procurement consortia among logistics operators are displacing individual fleet decisions. DPD, Evri, and Amazon's UK logistics arm have formed a buyer collective negotiating standardized solar e-bike specifications with direct-to-OEM contracts. This concentration is visible most acutely in the Midlands distribution corridor stretching from Coventry to Leicester, where shared charging infrastructure investments are following fleet deployment density.
UK Solar E-Bike Market Segmentation
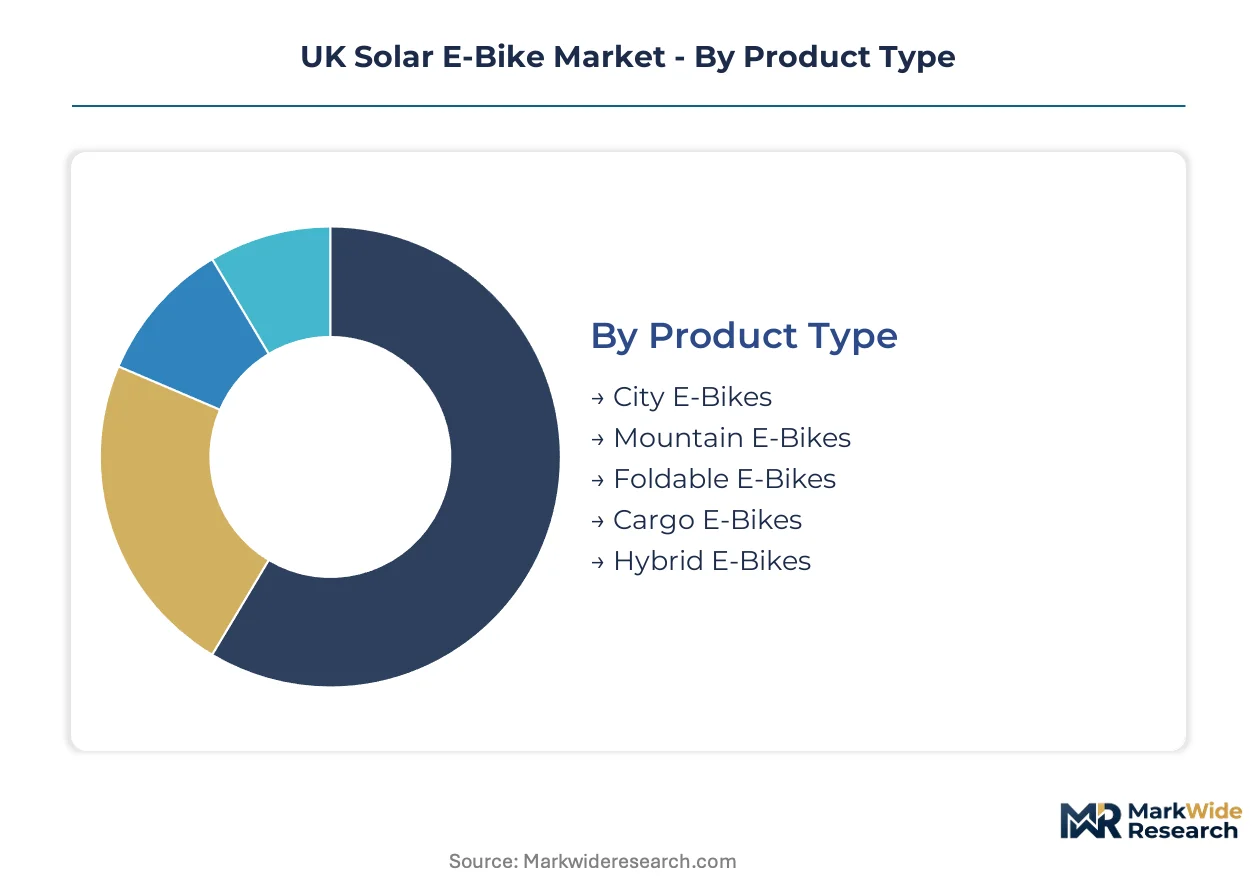
Solar e-bike segmentation in the UK reflects divergent integration architectures across product types and customer workflows. Fleet operators demand embedded photovoltaic systems with telematics compatibility, while individual consumers prioritize detachable panel configurations for flexible charging.
Product Type:
Integration depth varies sharply across frame geometries, with upright city designs accommodating roof-mounted arrays while cargo platforms require rack-integrated cell placement.
- City E-Bikes:Upright frame geometries with step-through or crossbar configurations host roof-mounted solar arrays generating 15-25 watts under standard insolation. Demand concentrates in Greater London's congestion-charged zones where commuters and last-mile operators seek exempt vehicle categories under Transport for London regulations.
- Cargo E-Bikes:Extended wheelbase platforms integrate photovoltaic cells into front or rear rack systems, supporting 50-100kg payloads for urban logistics. Fleet operators in Manchester and Birmingham mandate these configurations to meet corporate net-zero commitments and avoid diesel van operating restrictions in clean air zones.
- Mountain E-Bikes:Reinforced frame triangles accommodate compact solar panels for off-grid range extension in trail networks.
- Foldable E-Bikes:Patented hinge mechanisms from Kinetics Design Ltd. embed flexible photovoltaic films into handlebar and frame tubes.
- Hybrid E-Bikes:Multi-terrain tire specifications with semi-integrated solar top-up systems serve semi-rural commuter corridors.
Volume placements concentrate in City E-Bikes; the faster expansion belongs to Cargo E-Bikes.
Technology:
Cost tier stratification separates premium integrated systems from aftermarket retrofit kits, with lithium-ion cell management commanding the highest engineering investment.
- Lithium-Ion Battery:Cell-management systems with battery management circuitry and thermal regulation dominate bill-of-materials costs for UK assemblers. Cobalt and nickel price volatility from Democratic Republic of Congo and Indonesian supply concentration creates input cost instability for domestic pack manufacturers.
- Solar Charging:Perovskite-silicon tandem cells now deliver 20-30% higher wattage per square centimeter than legacy amorphous silicon configurations. Scottish and Northern English operators face compressed auxiliary charge yields due to 30-40% lower annual irradiance versus Southeast England.
- Brushless Motor:Hub-mounted and mid-drive configurations from Bosch eBike Systems control critical component pathways shaping final product positioning.
- Regenerative Braking:Kinetic recovery systems supplement solar input during urban stop-start riding patterns.
- Digital Display:CAN-bus integrated charge-state logging streamlines BSI compliance for subsidy-eligible vehicles under impending Department for Transport revisions.
Margin capture concentrates in Lithium-Ion Battery configurations; Solar Charging is climbing the fastest as perovskite films integrate into monocoque frame architectures.
Application:
Customer workflow differentiation separates commercial fleet utilization patterns from leisure-oriented riding behaviors, with delivery operators prioritizing duty-cycle reliability over recreational specifications.
- Delivery Services:Fleet procurement mandates prioritize fuel-cost reduction and congestion-zone compliance over leisure specifications. DPD, Evri, and Amazon's UK logistics arm negotiate standardized solar e-bike specifications through consolidated buyer collectives with direct-to-OEM contracts.
- Personal Commuting:Cycle to Work scheme participants in England, Scotland, and Wales capitalize on tax incentives reducing capital barriers for solar-assisted cycle adoption.
- Courier Services:Independent contractors in Bristol and Brighton utilize solar top-up for extended shift coverage without workplace charging infrastructure.
- Tourism:Rental operators in Oxford, Cambridge, and Brighton integrate solar-assisted models into dockless micro-mobility networks.
- Leisure Riding:Weekend recreational users in Cornwall and the Lake District prioritize detachable panel flexibility over embedded integration.
Deployment scale concentrates in Delivery Services; Courier Services are gaining share fastest as independent contractors adopt solar-assisted platforms for shift economics.
Customer Type:
Maturity stratification separates established fleet procurement consortia from emerging individual adopter segments, with corporate buyers driving standardization requirements.
- Fleet Operators:Consolidated procurement patterns across Greater London's congestion-charged zones compress decision cycles for solar-assisted electric cycles. Shared charging infrastructure investments follow deployment density in the Midlands distribution corridor from Coventry to Leicester.
- Corporate Buyers:Workplace Charging Scheme extensions to pedal-assisted cycles create deployment subsidies for employer-funded solar canopy installations at business parks and logistics hubs.
- Individual Consumers:Cycle to Work tax incentives and e-bike purchase grants reduce capital barriers across England, Scotland, and Wales.
- Delivery Providers:Regional courier services in Cornwall, Cumbria, and the Scottish Highlands pilot solar e-bikes for low-density route coverage where van economics collapse.
- Tourism Companies:Beryl and Lime integrate solar top-up stations into rental networks across university cities and coastal destinations.
Procurement volume concentrates in Fleet Operators; Corporate Buyers show the steepest expansion trajectory as Workplace Charging Scheme subsidies extend to pedal-assisted cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cell feedstock concentration in Democratic Republic of Congo and Indonesia anchors cost volatility for UK battery pack assemblers. Domestic photovoltaic engineering talent scarcity constrains solar integration capacity across British manufacturing clusters.
Greater London
Congestion-charge exemption for zero-emission vehicles drives fleet procurement compression among last-mile operators. Transport for London regulations mandate ultra-low emission zone compliance for commercial vehicles entering central boroughs. DPD, Evri, and Amazon logistics arm negotiate consolidated buyer collective contracts with direct-to-OEM specifications.
Midlands Distribution Corridor
Shared charging infrastructure investments follow fleet deployment density from Coventry to Leicester. The Department for Transport's Workplace Charging Scheme extension creates deployment subsidies for employer-funded solar canopy installations at logistics hubs. Birmingham clean air zone enforcement accelerates diesel van replacement mandates among regional courier services.
Scotland
Thirty to forty percent lower annual solar irradiance versus Southeast England compresses auxiliary charge yields for Edinburgh and Glasgow fleet operators. Scottish Government active travel budget allocations support e-bike purchase grants through Transport Scotland channels. Royal Mail pilots solar-assisted cycles for Highland route coverage where van economics collapse.
Southwest England
Rural postal networks in Cornwall and Cumbria deploy solar e-bikes for low-density route optimization. Cycle to Work scheme participation rates exceed national averages in Bristol and Brighton commuter corridors. Beryl integrates solar top-up stations into dockless rental networks across university cities.
Wales
Active Travel Act statutory targets mandate local authority e-bike infrastructure investment across Cardiff and Swansea urban areas. Welsh Government transport decarbonization grants reduce capital barriers for commercial fleet adopters. Regional courier services pilot solar-assisted platforms for Valleys route coverage without workplace charging access.
UK Solar E-Bike Market Competitive Landscape
Consolidated procurement consortia dominate the current landscape, displacing individual fleet purchasing decisions. Tiered competitive positioning separates integrated drive-train suppliers from frame-assembly specialists and photovoltaic subsystem providers. Three archetypes occupy distinct positions: European R&D-anchored premium brands, Asian scale manufacturers, and British engineering specialists. Strategic partnerships and technology licensing represent the dominant competitive moves, with capacity expansion secondary.
Among European-anchored premium assemblers, Trek Bicycle Corporation and Kinetics Design Ltd. exemplify the integrated solar architecture archetype. Robert Bosch GmbH occupies the critical component supplier position, controlling drive-train pathways that shape final product positioning across British OEM channels. These three entities represent the concentration points through which competitive dynamics flow.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Accell Group (Raleigh Electric) |
| Kinetics Design Ltd. (Gocycle) |
| Mahindra Electric Mobility Ltd. |
| Panasonic Corporation |
| Robert Bosch GmbH (Bosch eBike Systems) |
| Yamaha Motor Co., Ltd. |
| Rad Power Bikes LLC |
| Giant Manufacturing Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement collectives across Greater London's congestion-charged zones are mandating standardized solar e-bike specifications with embedded telematics, forcing assemblers to absorb battery management system complexity and compressing margin structures for non-integrated suppliers.
Pricing Analysis
Warranty bundling separates premium positioning from economy tiers, with five-year cell coverage and roadside assistance commanding 15-25% price premiums over bare-unit transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under BSI EPAC standards and volume scale discounts for fleet consortia. Cost compression in the standard tier is intensifying because cobalt-nickel feedstock volatility feeds through to pack assemblers. Fleet operators exhibit lowest price sensitivity due to congestion-charge avoidance value, while individual commuters through Cycle to Work schemes show highest elasticity to upfront capital outlay.
Supply Chain Analysis
Post-Brexit local-content considerations under the UK Battery Strategy are reshaping sourcing decisions, with domestic cell-packaging investments accelerating to qualify for subsidy eligibility. Lithium-ion cell supply draws from China, South Korea, and Japan, while photovoltaic film manufacturing concentrates in Taiwan and Germany. Cobalt and nickel extraction rests on Democratic Republic of Congo and Indonesian supply corridors, creating commodity price volatility exposure. Distribution runs through OEM-direct contracts for fleet operators and specialized e-bike retailers for individual consumers, with BSI certification bottlenecks extending lead times for solar-integrated models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photovoltaic systems engineering talent scarcity—fewer than 200 annual UK graduates with combined electrical-mechanical integration skills—props pricing power for incumbent assemblers with captive R&D capacity.
For Market Incumbents: Deploy backward integration into battery pack assembly to secure margin pools currently captured by Bosch eBike Systems and Asian cell suppliers. Consolidate certification investment advantages by pre-positioning for impending Department for Transport energy-monitoring mandates before BSI EPAC timeline extensions delay competitor launches. The perovskite-silicon tandem cell transition threatens legacy amorphous silicon suppliers with obsolescence. For New Entrants and Emerging Players: The Cycle to Work scheme in England, Scotland, and Wales opens a window for subscription-based micro-mobility platforms bypassing upfront capital barriers. Rural postal networks in Cornwall, Cumbria, and the Scottish Highlands represent the most penetrable white space, with van economics collapsing on low-density routes. Partner with Royal Mail pilot programs to establish reference deployments before scaling to regional courier services. For Investors and Strategic Acquirers: The window for entry favors vertically integrated engineering specialists with monocoque solar skin architectures over frame-assembly-only operations. Long-term viability hinges on five-to-ten-year positioning around perovskite integration depth and BSI regulatory automation capabilities. Watch for Department for Transport subsidy scheme revisions as the inflection signal for fleet procurement acceleration or deceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Photovoltaic Integration | Monocoque solar skin architectures from Trek and Kinetics Design reduce aerodynamic drag 8-12% while eliminating theft-prone external panels. |
| BSI EPAC Certification Automation | CAN-bus integrated charge-state logging by Bosch and Shimano streamlines compliance workflows for subsidy-eligible fleet deployments. |
| Fleet Procurement Consortium Formation | Consolidated buyer collectives among DPD, Evri, and Amazon logistics compress decision cycles and standardize direct-to-OEM specifications. |
| Workplace Charging Infrastructure Expansion | Department for Transport scheme extensions to pedal-assisted cycles create deployment subsidies for employer-funded solar canopy installations. |
| Rural Route Coverage Pilot Programs | Royal Mail and regional couriers in Cornwall, Cumbria, and Scottish Highlands validate solar e-bike economics where van utilization collapses. |
Research Methodology
Document review covered Department for Transport subsidy filings, BSI EPAC certification records, and Transport for London congestion-charge exemption data, complemented by interviews with fleet procurement directors at logistics operators, product engineering leads at frame assemblers, battery pack manufacturing managers, and photovoltaic systems specialists. Secondary validation drew from UK trade customs data, Office for Product Safety and Standards regulatory notices, and university graduate output statistics for electrical-mechanical engineering programs. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level projections across product type, technology configuration, application, and customer type fed into analytical framework calculations over the projection horizon. CAGRs derived from regression analysis against historical adoption curves for electrically power-assisted cycles and solar-assisted vehicle penetration patterns. Key forecast inputs included solar irradiance differentials across UK regions, lithium-ion cell feedstock price indices, and BSI certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for perovskite-silicon tandem cell manufacturing scale-up would alter the outlook for integrated versus bolt-on solar configurations. Forecasts reflect assumptions regarding Department for Transport subsidy continuity, post-Brexit regulatory alignment stability, and cobalt-nickel supply corridor reliability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Electric Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Air Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Implant Motors Market
Electric Motor
Traction Motors Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Electric Drives Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Torque Motor Market
Electric Motor
E-Bike Motor Market