
 Spain E-Bike Market | 2026-2036
Spain E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Spain E-Bike Market Analytics
Spain's national cycling infrastructure plan is shifting subsidy eligibility toward pedelecs with integrated battery systems above 250W nominal output. BH Bikes Europe SL leverages its Basque manufacturing heritage to dominate domestic production capacity. Orbea S.Coop. sustains competitive positioning through worker-owned cooperative governance and premium mountain bike specialization. Trek Bicycle Spain navigates import tariff complexities while extending its specialty store network across Madrid and Barcelona metropolitan zones.
An e-bike integrates an electric motor with pedal-assist or throttle-controlled propulsion, typically powered by rechargeable lithium-ion cells mounted on the frame or rear rack, designed to augment human power for urban mobility, cargo transport, and recreational trail riding. City commuter models occupy the largest volume tier due to last-mile delivery expansion and municipal bike-lane investments, while cargo configurations represent the fastest-growing margin pool as commercial fleet operators replace diesel vans. Lithium-ion battery chemistry leads the power source landscape, with nickel-metal hydride retaining niche presence in entry-level folding units sold through supermarket channels.
Spain's Directorate General for Traffic enforces EU harmonized type-approval standards for speed pedelecs, while the Ministry for the Ecological Transition channels NextGenerationEU funds into cycling infrastructure. BIS-equivalent conformity assessment for battery safety shapes import compliance costs for Asian manufacturers. Stakeholders must monitor how Madrid's low-emission zone expansion and Basque Country e-mobility incentives recalibrate fleet procurement criteria for delivery services.
Market Dynamics
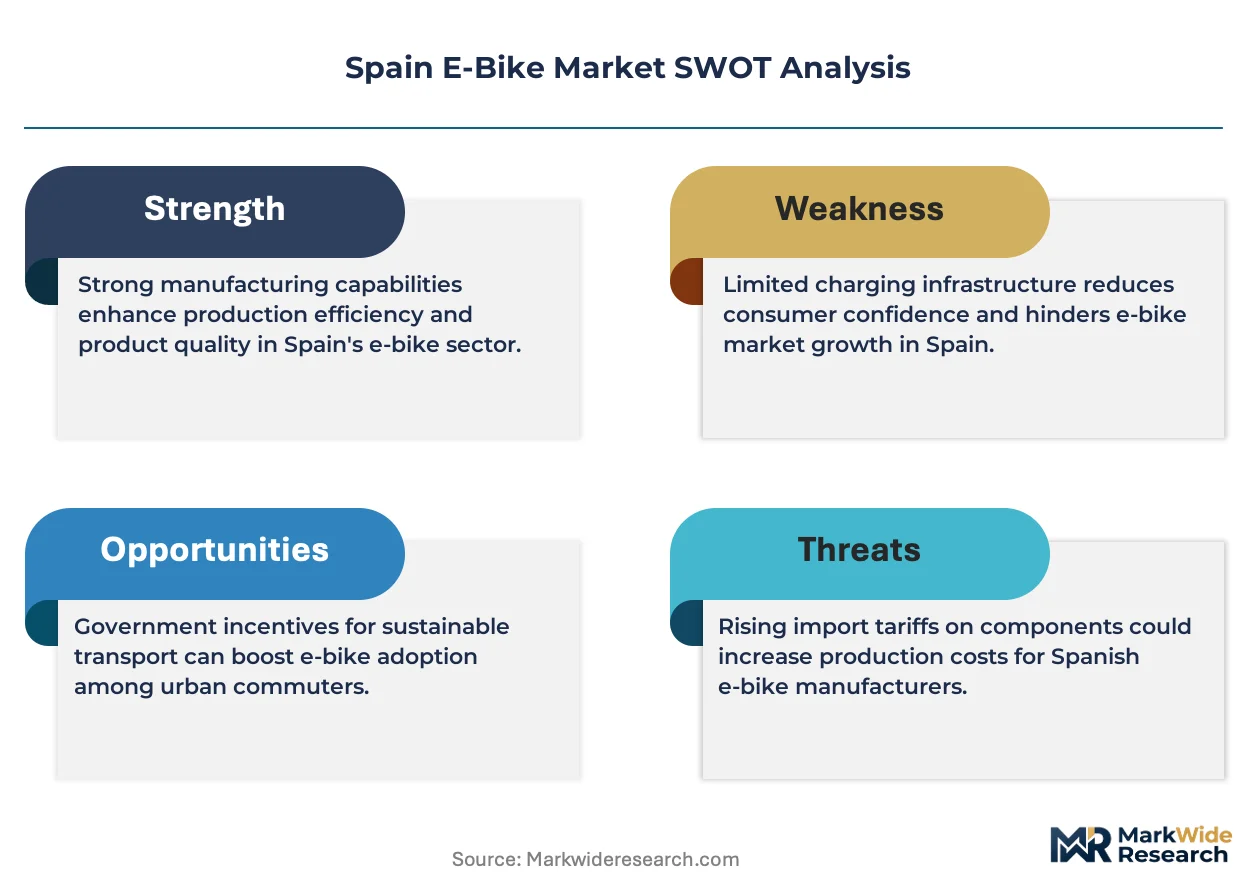
Spain's e-bike market pivots on subsidy recalibration under the EU Green Deal, which redirects public funds toward integrated battery systems and away from retrofit conversion kits, compressing margins for low-tier assemblers while advantaging domestic manufacturers with captive cell sourcing.
Growth Catalysts
- NextGenerationEU infrastructure allocation:Madrid and Barcelona metropolitan councils deploy dedicated cycle highways, reducing collision risk and expanding addressable commuter base beyond recreational cyclists.
- Last-mile delivery electrification:Food and parcel logistics operators in Catalonia replace thermal mopeds with cargo e-bikes to comply with expanding low-emission zones.
- Lithium-ion cell cost curve:Declining pack prices enable 500Wh+ configurations at mid-market price points, extending range utility for Basque Country hill-climbing routes.
Market Restraints
- Import compliance friction:Asian manufacturers face BIS-equivalent battery safety certification costs that add 8-12 weeks to first-market entry.
- Cell supply concentration:Cylindrical 21700 format dependency on East Asian cell producers exposes Spanish assemblers to shipping rate volatility and customs delays.
- Speed pedelec type-approval:EU harmonized standards enforced by Spain's Directorate General for Traffic impose homologation costs that exclude sub-€2,000 retail price points.
Strategic Opportunities
- Galicia and Andalusia penetration:Cycling infrastructure investment lags behind northern regions, creating first-mover advantage for fleet operators establishing commercial bike-share networks.
- Battery leasing unbundling:Subscription models separate asset ownership from usage, reducing upfront consumer outlay and extending manufacturer revenue streams through recurring service contracts.
- EU Green Deal alignment:Extended producer responsibility mandates for battery recycling create closed-loop material recovery partnerships between domestic manufacturers and Spanish waste management consortia.
Industry Challenges
- Power electronics engineering scarcity:Motor controller firmware development and thermal management design talent concentrates in automotive hubs, forcing e-bike firms to compete for embedded systems specialists.
- Service network standardization:Diagnostic protocol fragmentation across Bosch, Shimano, and Bafang drive systems complicates technician training and aftermarket parts inventory management for independent retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain E-Bike Market |
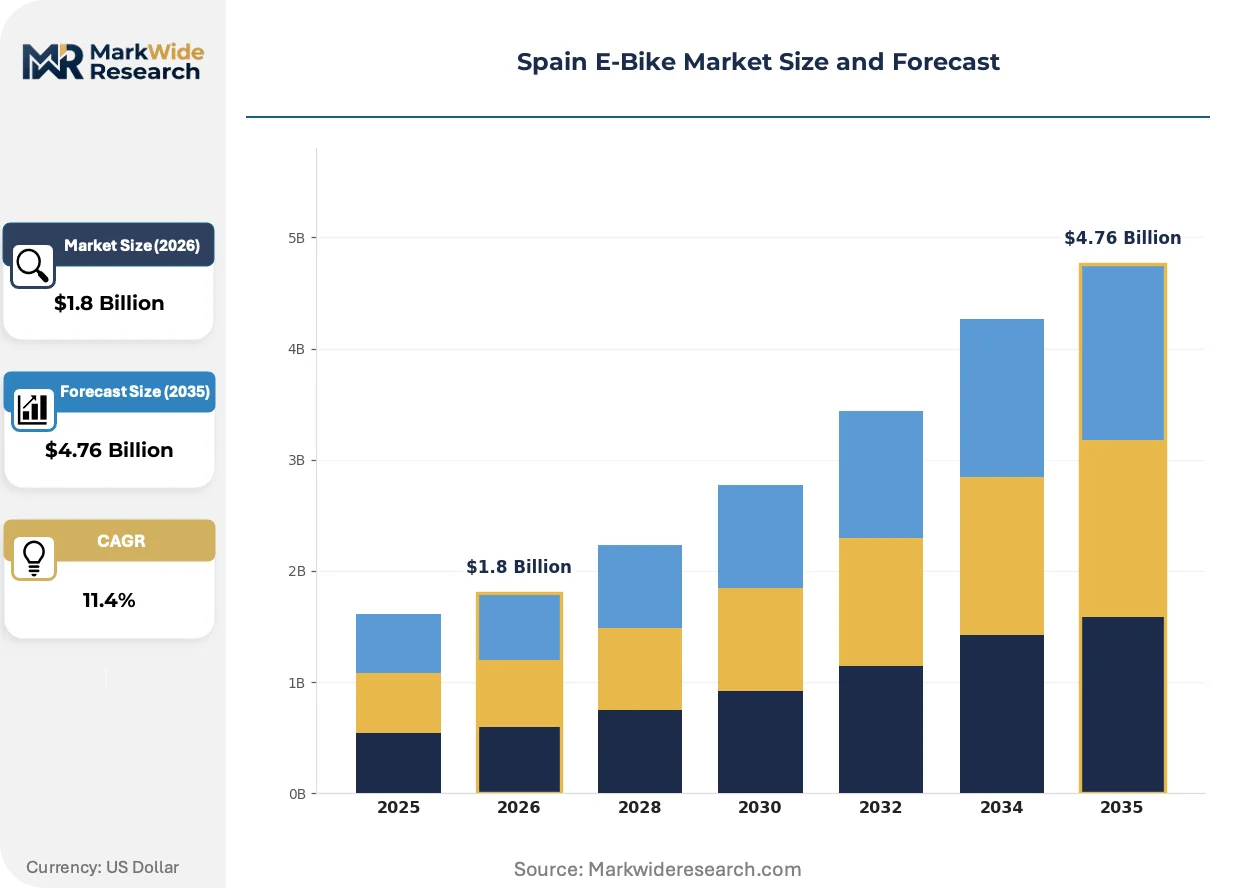
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Commuter, Mountain, Folding, Cargo Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Others End User: Environmentally-Conscious Consumers, Urban Commuters, Fitness Enthusiasts, Delivery Services Sales Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Orbea S.Coop., BH Bikes Europe SL, Mondraker, Urbanbiker, Trek Bicycle Spain, CUBE Bikes, Giant Manufacturing Co. Ltd., Merida Industry Co. Ltd., Scott Sports, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain E-Bike Market Evolving Landscape
Spain's e-bike sector is experiencing a hardware-software convergence that redefines product value from mechanical durability to connected fleet manageability, with implications for how manufacturers organize R&D and channel relationships.
Mid-drive torque sensor technology is expanding into urban commuter segments previously dominated by hub-motor cost leaders. Delivery fleet operators in Madrid now specify pedal-assist responsiveness metrics for rider efficiency optimization. This specification compression is forcing hub-motor suppliers to develop proprietary sensor integration or retreat to recreational price tiers.
Spain's Ministry for the Ecological Transition channels NextGenerationEU funds through municipal tenders requiring ISO 4210 frame testing and UN 38.3 battery transport certification. These procurement pre-qualifications exclude catalog importers lacking in-house engineering documentation. Basque Country manufacturers with captive testing facilities capture disproportionate public contract share.
Subscription-based ownership models are displacing outright purchase in Barcelona's B2B fleet segment. Logistics operators now procure kilometers-per-rider rather than asset depreciation, transferring residual value risk to manufacturer-financing arms. This shift concentrates purchasing authority with procurement departments and away from store-floor retail influence.
Spain E-Bike Market Segmentation
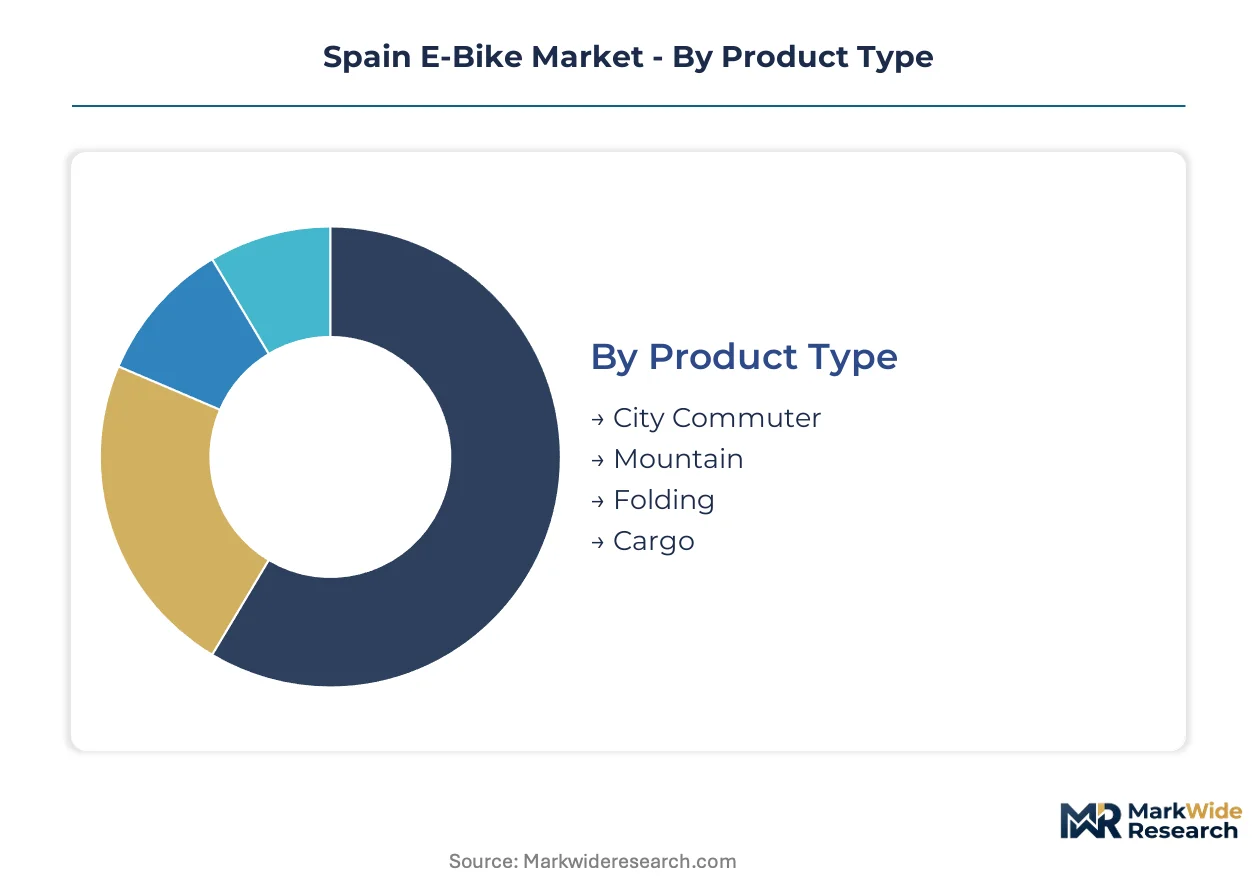
Segmentation in Spain's e-bike market reveals how subsidy structures, terrain demands, and fleet procurement criteria fragment purchasing behavior across distinct buyer profiles. Manufacturers must align product development with these divergent specifications to capture public tender opportunities and retail channel placement.
Product Type:
Urban topography and commercial fleet requirements differentiate buyer priorities more sharply than recreational preference alone.
- City Commuter:Step-through frames with integrated lighting and fenders dominate Barcelona and Madrid municipal procurement. Last-mile delivery operators in Catalonia specify these models for low-emission zone compliance, driving volume concentration in metropolitan corridors with dedicated cycle infrastructure.
- Cargo:Dual-battery configurations with 200kg+ payload capacity serve parcel and food logistics fleets replacing diesel vans. Basque Country manufacturers capture disproportionate share through captive frame testing facilities required for NextGenerationEU tender pre-qualification.
- Mountain:Full-suspension systems with torque-sensor integration address Basque Country and Pyrenean recreational demand.
- Folding:Compact hub-motor designs target multimodal commuters in Barcelona's metro-train interchanges.
City Commuter leads volumes today; Cargo is gaining share fastest.
Battery Type:
Cell chemistry selection tracks subsidy eligibility thresholds and total cost of ownership calculations across consumer and commercial segments.
- Lithium-ion:21700 cylindrical cells with 500Wh+ configurations power premium commuter and cargo fleets. Declining pack prices enable mid-market penetration, though Spanish assemblers remain exposed to East Asian cell supply concentration and shipping volatility.
- Nickel-Metal Hydride:Retains presence in entry-level folding units distributed through supermarket channels where upfront cost sensitivity outweighs energy density requirements.
- Lead Acid:Sealed lead-acid chemistry persists in price-driven retrofit conversion kits now excluded from EU Green Deal subsidy eligibility.
- Others:Solid-state and sodium-ion prototypes circulate in Basque Country manufacturer R&D pipelines without commercial scale.
Lithium-ion dominates installed base; Nickel-Metal Hydride retains niche defensibility in discount retail.
End User:
Procurement authority and residual risk allocation separate individual consumers from institutional fleet operators.
- Delivery Services:Fleet operators in Madrid and Barcelona now procure through subscription models transferring asset depreciation risk to manufacturer financing arms. These buyers specify pedal-assist responsiveness metrics and ISO 4210 frame certification for rider efficiency and tender compliance.
- Urban Commuters:Individual purchasers in Catalonia and the Basque Country prioritize integrated battery systems above 250W nominal output to capture national cycling infrastructure plan subsidies.
- Environmentally-Conscious Consumers:Sustainability-motivated buyers respond to EU Green Deal alignment and extended producer responsibility mandates for battery recycling.
- Fitness Enthusiasts:Recreational riders in northern Spain's hill regions demand mid-drive torque sensors for trail performance.
Urban Commuters anchor retail volumes; Delivery Services is climbing the fastest.
Sales Channel:
Service capability and diagnostic standardization determine channel viability for different product tiers.
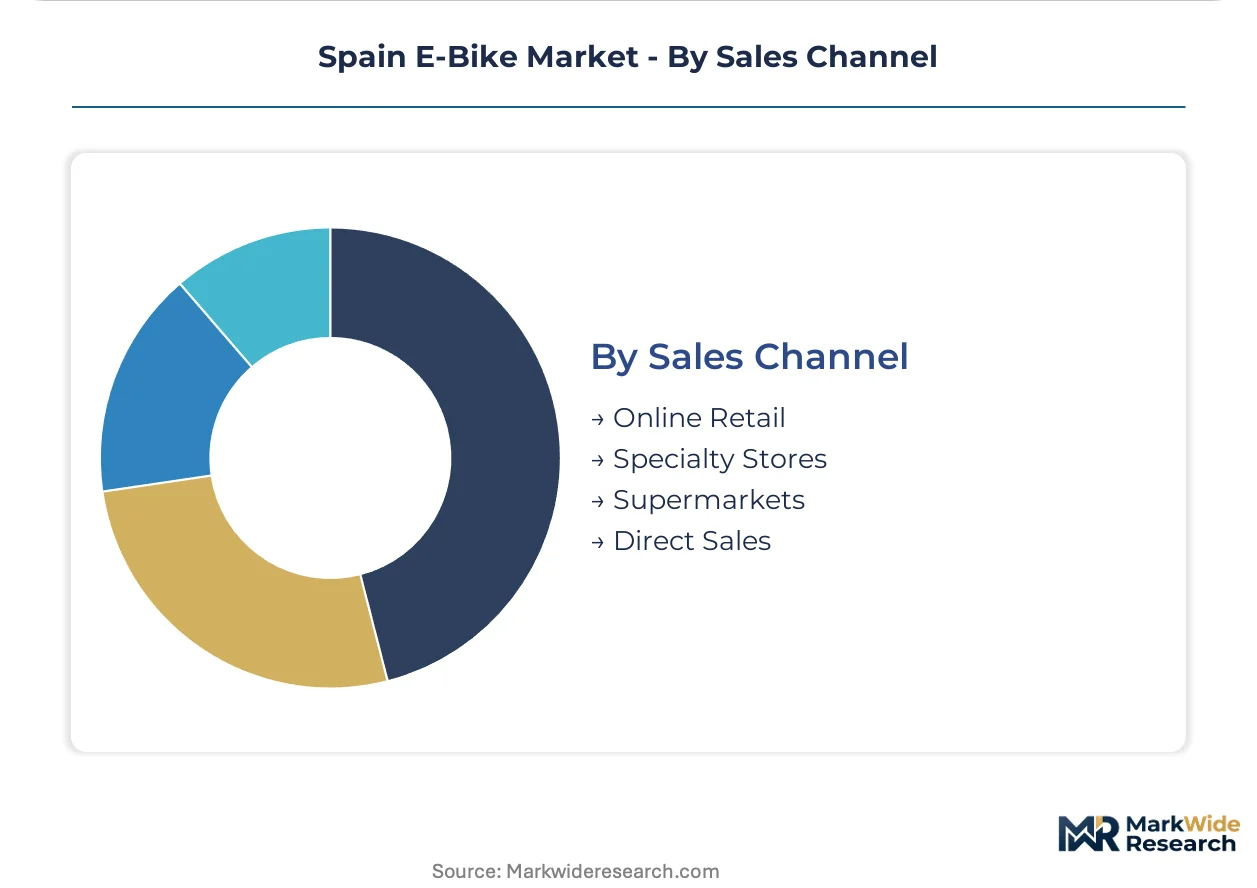
- Specialty Stores:Independent retailers with Bosch, Shimano, and Bafang certification handle premium mid-drive systems requiring firmware diagnostics and thermal management expertise. These outlets concentrate in Madrid and Barcelona metropolitan zones.
- Online Retail:Direct-to-consumer platforms serve price-sensitive segments with hub-motor commuter models where remote assembly support suffices.
- Supermarkets:Mass-market channels distribute entry-level folding e-bikes with Nickel-Metal Hydride batteries and minimal service requirements.
- Direct Sales:Manufacturer-owned outlets in Basque Country production clusters emphasize worker-owned cooperative governance models and local manufacturing heritage.
Specialty Stores lead premium placement; Online Retail is expanding most quickly in mid-market commuter segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's e-bike industry traces its manufacturing heritage to Basque Country cooperative workshops that scaled bicycle production through the twentieth century. Madrid and Barcelona now anchor metropolitan demand corridors. Sub-regional specialization concentrates engineering talent and procurement authority across distinct autonomous communities.
Madrid
Last-mile delivery electrification dominates fleet procurement in the capital metropolitan zone. The city's expanding low-emission zone mandates thermal moped replacement with cargo e-bikes for logistics operators. Madrid City Council deploys NextGenerationEU cycle highway investments, concentrating tender awards among manufacturers with ISO 4210 frame certification and captive testing documentation.
Catalonia
Barcelona anchors Spain's highest urban commuter density, with dedicated bike-lane networks driving step-through frame volumes. The Generalitat de Catalunya channels EU Green Deal alignment funds toward integrated battery systems above 250W nominal output. Local manufacturing presence remains limited, concentrating import distribution and specialty retail networks across the metropolitan corridor.
Basque Country
Worker-owned cooperative governance structures sustain premium mountain bike and urban commuter production in Vitoria-Gasteiz and Mallabia clusters. The Eusko Jaurlaritza e-mobility incentive program subsidizes domestic assembly with captive cell sourcing. Steep urban topography in Bilbao and San Sebastián amplifies torque-sensor specification requirements for daily transport segments.
Andalusia
Cycling infrastructure investment lags northern regions, creating penetration gaps for commercial bike-share network establishment. The Junta de Andalucía transportation planning documents prioritize highway expansion over metropolitan cycle connectivity. Seville and Málaga municipal governments represent emerging procurement opportunities as EU cohesion funds redirect toward sustainable mobility.
Valencia
Port logistics and ceramics industry freight corridors generate emerging cargo e-bike demand for short-haul container and material transport. The Generalitat Valenciana climate action plan allocates limited cycling infrastructure budgets relative to rail electrification priorities. Alicante and Castellón coastal tourism zones sustain seasonal recreational rental volumes with lower specification hub-motor configurations.
Spain E-Bike Market Competitive Landscape
The competitive structure tilts toward domestic cooperative manufacturers with captive engineering documentation and Basque production heritage. Tiered positioning separates premium mid-drive specialists from hub-motor cost leaders serving supermarket channels. Three archetypes dominate: worker-owned cooperatives with vertical production control, Asian scale manufacturers navigating import compliance friction, and European brand licensors operating through Spanish distribution subsidiaries. Consolidation pressure concentrates among catalog importers lacking in-house testing facilities, while capacity expansion favors domestic assemblers with NextGenerationEU tender pre-qualification.
Among domestic cooperative fabricators, Orbea S.Coop. and BH Bikes Europe SL occupy positions exemplifying worker-governance and Basque manufacturing heritage. Trek Bicycle Spain represents the European brand licensor archetype, navigating import tariff structures while extending specialty store networks. These three anchors illustrate how procurement authority shifts from retail floors to fleet procurement departments and municipal tender boards.
| Leading Market Players |
|---|
| Orbea S.Coop. |
| BH Bikes Europe SL |
| Mondraker |
| Urbanbiker |
| Trek Bicycle Spain |
| CUBE Bikes |
| Giant Manufacturing Co. Ltd. |
| Merida Industry Co. Ltd. |
| Scott Sports |
| Others |
Value Network & Pricing Analysis
Delivery fleet procurement departments in Madrid and Barcelona metropolitan zones command pricing leverage through subscription-based kilometer contracts that transfer residual value risk to manufacturer financing arms. This buyer concentration forces pricing stratification across premium mid-drive configurations, standard hub-motor commuters, and economy folding units distributed through supermarket channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 4210-certified cargo fleets from uncertified catalog imports. Price differentiation hinges on battery certification tier and captive cell sourcing from Basque Country manufacturers. Margins are tightening due to BIS-equivalent compliance costs for Asian entrants. Supermarket channels exhibit highest price sensitivity; fleet procurement departments prioritize total cost of ownership over upfront outlay.
Supply Chain Analysis
Dual-sourcing requirements from Madrid and Barcelona fleet operators mandate multi-supplier qualification for 21700 cylindrical cells. Cell supply concentrates in China, South Korea, and Japan, with Spanish assemblers drawing from East Asian producers for lithium-ion chemistry. Raw material dependencies span cobalt, nickel, and electrolyte formulations. Single-source vulnerability in semiconductor motor controllers threatens production continuity. Distribution runs through specialty retailers with Bosch and Shimano certification in metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's e-bike market operates as a regulatory compounder where EU Green Deal subsidy recalibration and NextGenerationEU infrastructure allocation continuously reshape demand curves.
For Market Incumbents: Anticipate margin compression from retrofit conversion kit exclusion by accelerating captive battery system development. Deepen backward integration into cell testing facilities to defend NextGenerationEU tender eligibility against Asian scale manufacturers. Prioritize firmware diagnostics certification to lock specialty retail channel placement. For New Entrants and Emerging Players: The mid-market price-point gap between Orbea premium mountain bikes and supermarket folding units offers white-space entry. Andalusia and Galicia cycling infrastructure underinvestment presents first-mover advantage for commercial bike-share network establishment. Pursue battery leasing unbundling as the primary go-to-market angle to reduce fleet operator capital barriers. For Investors and Strategic Acquirers: European automotive component suppliers are the most active acquirer in this space, seeking embedded systems capabilities. Five-to-ten year viability rests on extended producer responsibility mandate execution for battery recycling infrastructure. Acquisition target archetypes include Basque Country manufacturers with captive testing documentation. Monitor Madrid low-emission zone expansion velocity as the inflection indicator for cargo fleet procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Leasing Unbundling | Subscription models transfer residual value risk to manufacturer financing arms in Barcelona fleet procurement. |
| ISO 4210 Certification Investment | Frame testing documentation secures NextGenerationEU tender pre-qualification for Basque Country manufacturers. |
| Cell Supply Diversification | Dual-sourcing mandates from Madrid fleet operators reduce dependency on East Asian 21700 producers. |
| Regional Infrastructure Partnership | Andalusia municipal contracts offer first-mover positioning as EU cohesion funds redirect toward cycling. |
| Extended Producer Responsibility Compliance | Battery recycling mandates create closed-loop partnerships with Spanish waste management consortia. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed e-bike manufacturer product directors, fleet procurement managers at Madrid and Barcelona logistics operators, specialty retailer service technicians, and Ministry for the Ecological Transition policy officers. Secondary validation drew from EU TARIC customs data, NextGenerationEU tender documentation, Directorate General for Traffic type-approval registers, and Basque Country industrial cluster reports. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Segment-weighting approaches distributed volume and value estimates across product type, battery chemistry, end-user archetype, and sales channel dimensions. The analytical framework applied penetration modeling for urban commuter adoption against cycling infrastructure deployment timelines. CAGRs were derived from logistic diffusion curves fitted to fleet electrification mandates and consumer subsidy uptake patterns. Key inputs included lithium-ion cell cost trajectories and low-emission zone expansion schedules.
Caveats apply where subsidy recalibration under EU Green Deal alignment or Basque Country e-mobility incentive modification could materially shift the outlook. Forecasts reflect assumptions on cell supply chain normalization and municipal tender award continuity. Deviation in Madrid low-emission zone enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market