
 Motorcycle Instrument Cluster Market | 2026-2036
Motorcycle Instrument Cluster Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Instrument Cluster Market Outlook
Glass-reinforced polycarbonate is shifting away from traditional ABS in motorcycle instrument cluster housings as OEMs pursue weight reduction and improved vibration resistance. Bosch leverages its automotive display expertise to anchor European premium cluster supply chains. Denso Corporation sustains R&D intensity in thin-film transistor integration for motorcycle-specific form factors. Yamaha Motor Co., Ltd. dominates captive cluster production for its own sportbike and touring platforms, controlling vertical supply from design to final assembly.
A motorcycle instrument cluster constitutes the rider-facing information display assembly, typically integrating speedometers, tachometers, fuel gauges, warning indicators, and optional navigation interfaces within an IP-rated enclosure designed to withstand sustained vibration, UV exposure, and temperature cycling from minus twenty to plus eighty-five degrees Celsius. Its primary commercial purpose is to deliver real-time vehicle telemetry while enabling brand differentiation through interface design and connected-feature integration. Digital clusters and TFT clusters are capturing margin pools as OEMs bundle smartphone mirroring and turn-by-turn navigation, while analog clusters retain volume dominance in emerging-market commuter segments where cost sensitivity limits electronic content. Hybrid clusters occupy a transitional position, appealing to heritage-focused brands that must balance classic dial aesthetics with regulatory demands for digital odometer accuracy and diagnostic readability.
FCC certification governs wireless connectivity modules embedded in North American-sourced clusters, while ECE R10 from the United Nations Economic Commission for Europe shapes electromagnetic compatibility standards for units sold across EU member states. Japan's METI enforces energy-efficiency benchmarks that push suppliers toward low-power OLED and transflective LCD technologies. Stakeholders must monitor how India's BIS certification timelines for automotive electronics will reshape sourcing decisions for clusters destined for one of the world's largest two-wheeler production bases.
Market Dynamics
Digital display migration is compressing analog gauge supply chains as EU F-Gas Regulation and REACH compliance deadlines force mercury-containing component phase-outs, while India's two-wheeler manufacturing belt concentrates TFT cluster procurement around Chennai and Pune.
Growth Catalysts
- EU F-Gas Regulation:The phase-out mandate for mercury-containing components accelerates solid-state digital display adoption across European premium motorcycle lineups.
- Glass-reinforced polycarbonate:This material substitution from ABS housings enables weight reduction and vibration resistance improvements that OEM specifications increasingly demand.
- Chennai-Pune corridor:Domestic OEMs and tier-1 suppliers are localizing TFT cluster production within India's two-wheeler manufacturing belt, reducing import dependency.
Market Restraints
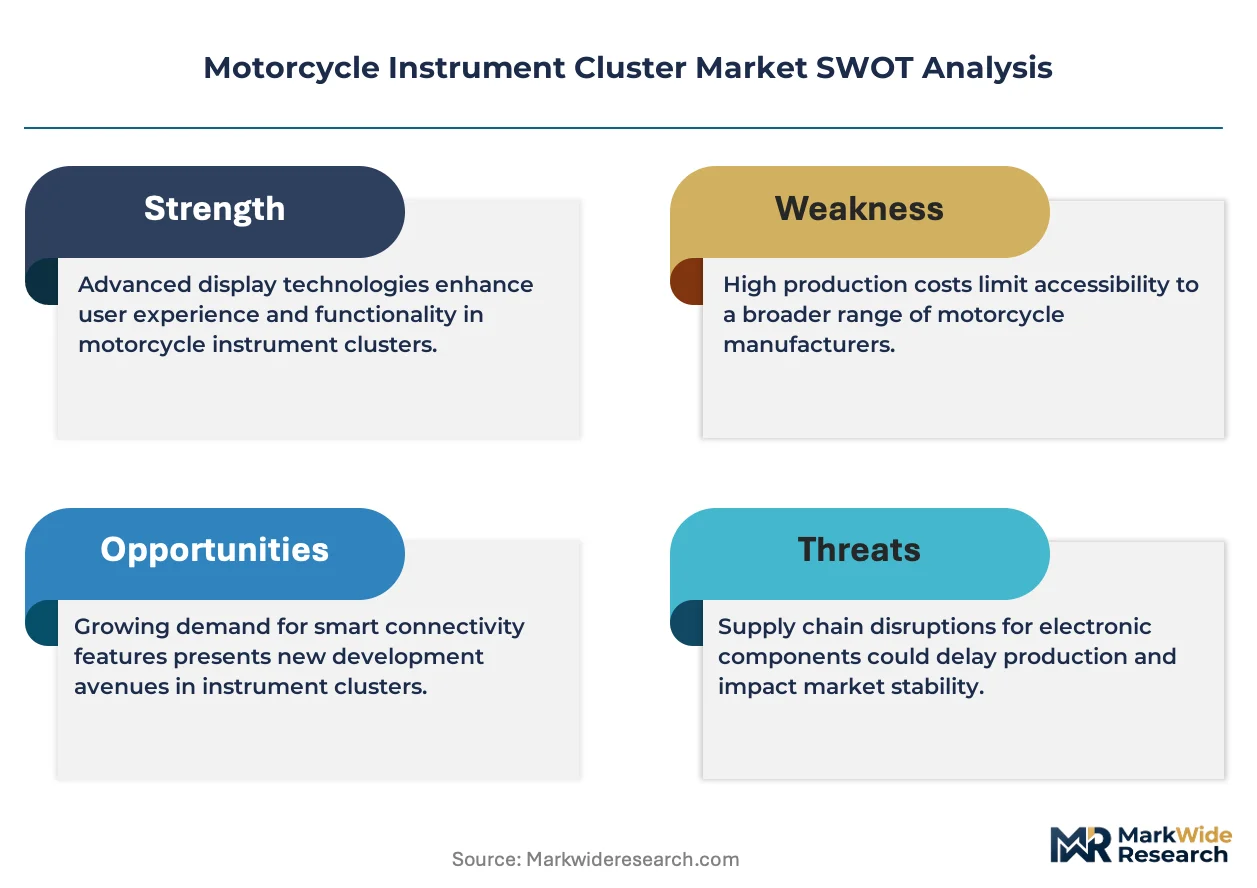
- OLED input cost volatility:Display panel price fluctuations constrain margin expansion for suppliers targeting mid-tier motorcycle segments.
- Japan captive production:Yamaha Motor's vertical control from design through final assembly limits third-party supplier access to sportbike and touring platforms.
- ECE R10 certification friction:Electromagnetic compatibility testing timelines delay cluster introductions for EU-bound motorcycle models.
Strategic Opportunities
- Smartphone mirroring integration:Bundling navigation and telemetry interfaces creates margin pools in premium segments previously served by standalone GPS units.
- Heritage hybrid clusters:Classic dial aesthetics combined with digital odometer accuracy address regulatory compliance without alienating traditionalist buyer segments.
- India BIS certification readiness:Early alignment with automotive electronics timelines positions suppliers for sourcing decisions at one of the world's largest two-wheeler production bases.
Industry Challenges
- TFT integration complexity:Motorcycle-specific form factors require specialized thin-film transistor engineering that strains available embedded systems talent pools.
- IP-rated enclosure capex:Tooling for enclosures rated to withstand sustained vibration, UV exposure, and temperature cycling from minus twenty to plus eighty-five degrees Celsius demands significant upfront investment.
- Legacy analog obsolescence:Supply chain reconfiguration for digital-first production creates stranded capacity at established gauge manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Instrument Cluster Market |
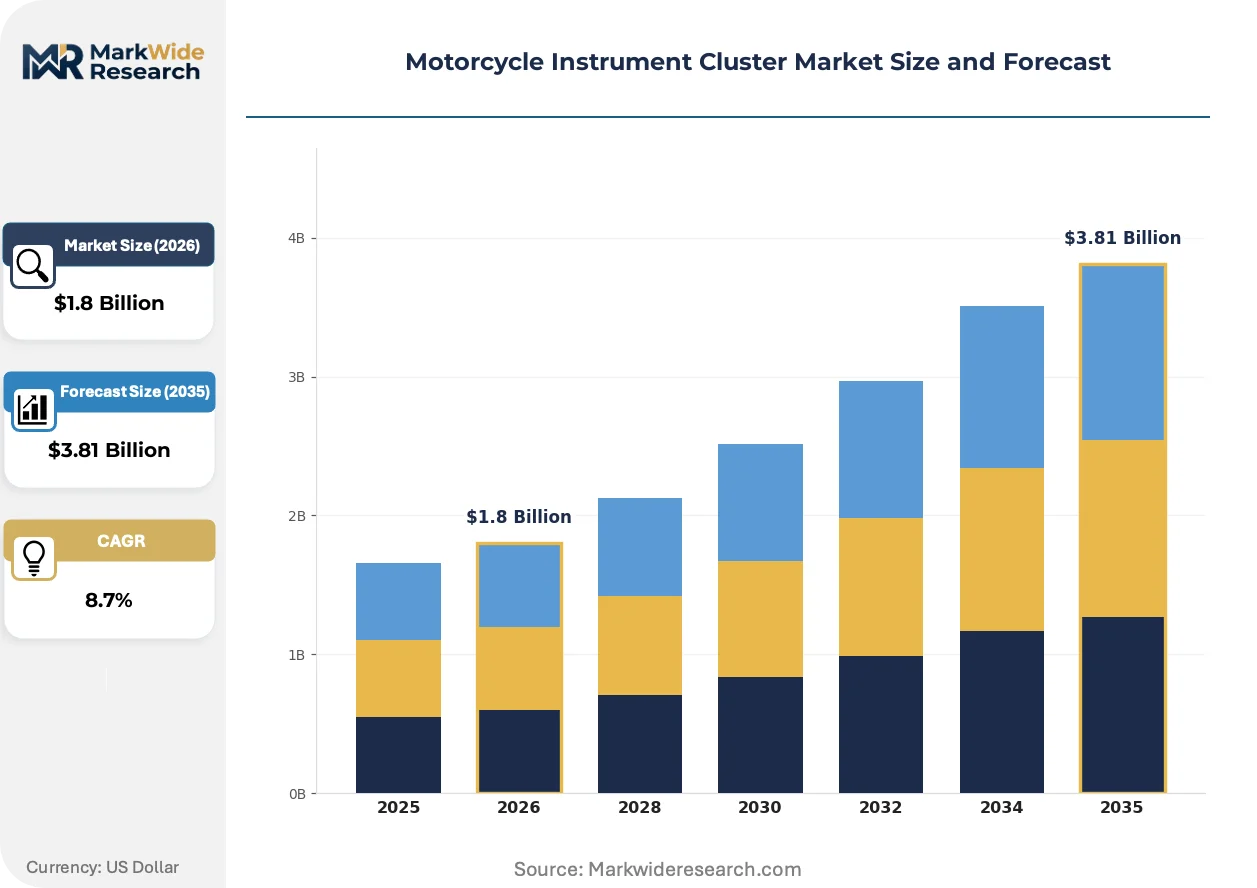
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Clusters, Digital Clusters, Hybrid Clusters, TFT Clusters Technology: GPS Integration, Bluetooth Connectivity, Speed Sensors, Fuel Monitoring End User: OEMs, Aftermarket Retailers, Service Providers, Individual Consumers Installation Type: Integrated, Standalone, Custom Mounts, Plug-and-Play |
| Companies Covered | Yamaha Motor Co., Ltd., Denso Corporation, Bosch, Yazaki Corporation, Magneti Marelli S.p.A., Continental AG, Nippon Seiki Co., Ltd., Honda Motor Co., Ltd., Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Instrument Cluster Market Strategic Shifts
Connected feature bundling is redefining cluster value propositions as riders expect seamless smartphone integration, while regulatory pressure and material science advances reshape hardware specifications across all price tiers.
Transflective LCD technology is automating visibility optimization across varying ambient light conditions without backlight power drain. Premium touring and adventure motorcycle buyers specify these displays for all-weather readability. The technology is automating the displacement of traditional transflective passive-matrix alternatives in mid-tier segments.
REACH substance restrictions are forcing reformulation of display backlights and housing materials to eliminate restricted phthalates and heavy metals. Suppliers must requalify component streams through ECHA-registered alternatives. Heritage-focused manufacturers face compressed redesign timelines for models with multi-year production cycles.
Direct OEM procurement of complete cluster modules is consolidating previously fragmented tier-2 and tier-3 supply relationships. Electronics integrators now capture value previously distributed across gauge specialists, cable harness suppliers, and separate navigation providers. This pattern concentrates most visibly in Germany and Japan where flagship sportbike programs specify turnkey digital cockpit solutions.
Motorcycle Instrument Cluster Market Segmentation
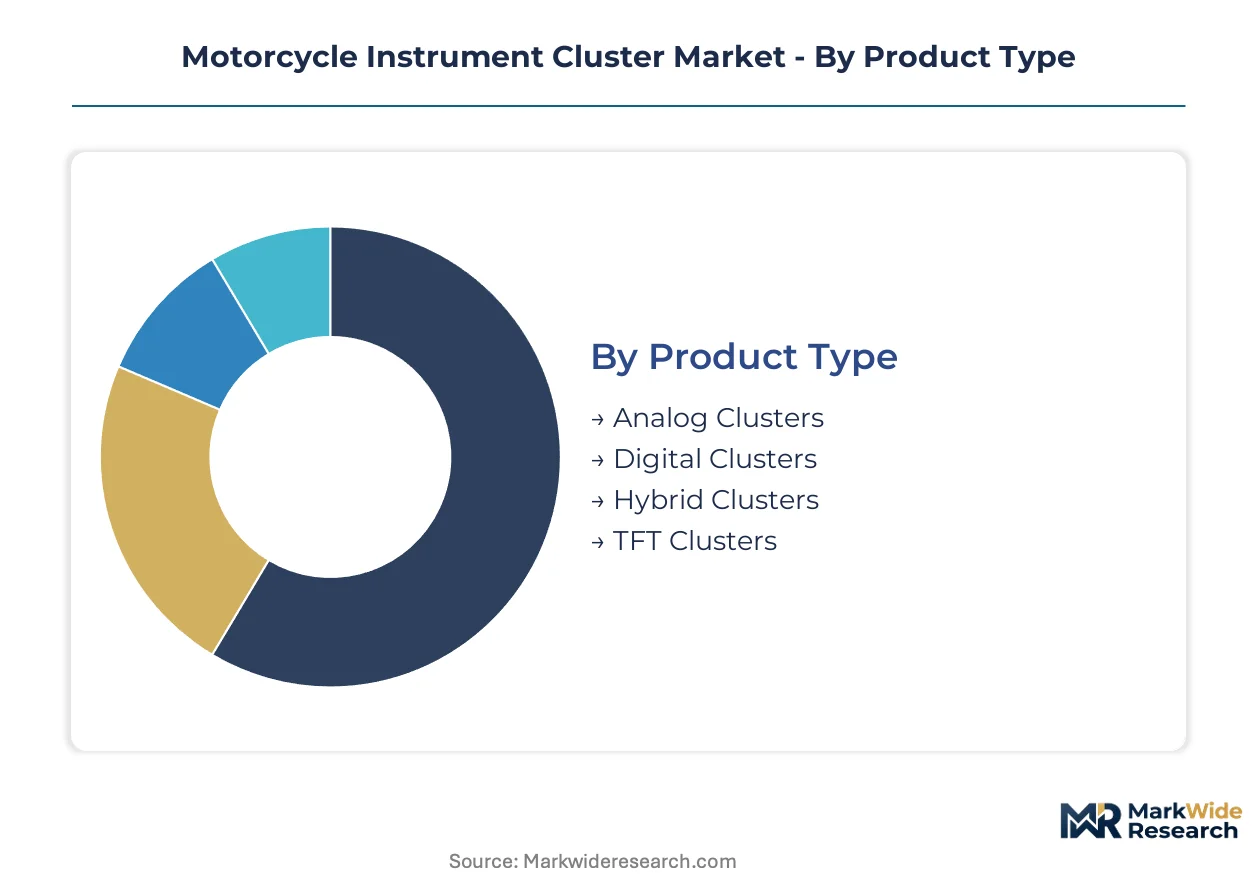
Motorcycle instrument cluster segmentation reveals a market bifurcated between cost-driven commuter volumes and feature-rich premium platforms. Product type and technology choices determine margin architecture, while end-user channels and installation methods shape go-to-market economics for suppliers.
Product Type:
Analog clusters dominate unit volumes in emerging-market commuter segments, while TFT clusters command premium positioning through smartphone integration capabilities.
- Analog Clusters:Mechanical gauge assemblies with needle-based speedometers and tachometers retain cost advantages for price-sensitive motorcycle buyers. Demand concentrates in India's sub-125cc commuter belt around Pune, where domestic OEMs prioritize unit economics over electronic content.
- TFT Clusters:Thin-film transistor displays enable full-color navigation, smartphone mirroring, and configurable rider interfaces. Procurement from Germany's premium sportbike OEMs is accelerating as EU F-Gas Regulation deadlines force mercury-free solid-state alternatives.
- Digital Clusters:Segment LCD or LED displays without full TFT capabilities occupy mid-tier positioning between analog simplicity and premium connectivity.
- Hybrid Clusters:Classic dial aesthetics combined with digital odometer modules address heritage brand requirements for regulatory compliance without alienating traditionalist buyers.
Today's leader: Analog Clusters. Tomorrow's challenger: TFT Clusters.
Technology:
Connectivity modules and sensor integration are redefining cluster functionality beyond basic telemetry display.
- Bluetooth Connectivity:Wireless pairing with smartphones enables call alerts, music control, and navigation prompts on cluster displays. FCC certification requirements for North American-bound modules add compliance complexity and cost.
- GPS Integration:Embedded or mirrored turn-by-turn navigation displaces standalone handlebar-mounted units. Demand from adventure touring segments in Germany and Japan specifies all-weather readability through transflective optimization.
- Speed Sensors:Hall-effect and inductive pickup technologies feed real-time velocity data to digital processing units.
- Fuel Monitoring:Resistive or ultrasonic level sensing integrates with range calculation algorithms for range-anxiety reduction.
Bluetooth Connectivity claims installed base dominance. GPS Integration shows the steepest expansion trajectory as navigation bundling becomes standard in premium segments.
End User:
Channel structure determines pricing power and technical support requirements across the value chain.
- OEMs:Factory-fit procurement by motorcycle manufacturers demands full validation to ECE R10 electromagnetic compatibility standards. Direct relationships with Germany's KBA-registered type-approval holders streamline homologation for EU-bound models.
- Aftermarket Retailers:Distributor and dealer networks serve replacement and upgrade demand outside factory warranty channels.
- Service Providers:Independent repair shops handle cluster replacement for crash damage or electrical failure.
- Individual Consumers:Direct-to-rider sales through e-commerce platforms target customization enthusiasts seeking plug-in upgrades.
OEMs control specification-setting power. Aftermarket Retailers capture margin expansion as digital retrofit demand grows among existing fleet owners.
Installation Type:
Mounting methodology reflects the tension between design integration and field serviceability.
- Integrated:Cluster modules designed into motorcycle cockpit architecture from initial styling clay. Yamaha Motor's captive production for sportbike platforms exemplifies this approach, with housing geometry matched to fairing contours.
- Standalone:Self-contained units with independent mounting brackets enable cross-platform compatibility.
- Plug-and-Play:Pre-wired harness connections reduce installation time for aftermarket technicians.
- Custom Mounts:Fabricated or 3D-printed brackets address non-standard handlebar configurations in custom builds.
Integrated solutions define new-model development. Plug-and-Play formats are gaining fastest in aftermarket channels where labor cost minimization drives purchasing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chennai-Pune corridor anchors production localization as India's two-wheeler belt concentrates TFT cluster manufacturing. Germany's premium sportbike OEMs drive digital display procurement. Japanese vertical integration controls captive supply chains. Regulatory deadlines reshape European sourcing.
India
Domestic OEMs and tier-1 suppliers localize TFT cluster production within the Chennai-Pune manufacturing belt, reducing import dependency for display modules. BIS certification timelines for automotive electronics reshape sourcing decisions at one of the world's largest two-wheeler production bases. Domestic procurement concentrates around Pune's commuter belt for sub-125cc analog clusters.
Germany
Premium motorcycle OEMs expand digital cluster procurement for flagship sportbike lineups as KBA-registered type-approval holders streamline EU homologation. EU F-Gas Regulation and REACH compliance deadlines force mercury-free solid-state alternatives across European premium segments. Stuttgart and Munich anchor turnkey digital cockpit specification-setting for factory-fit programs.
Japan
Yamaha Motor Co., Ltd. dominates captive cluster production for sportbike and touring platforms through vertical control from design to final assembly. METI enforces energy-efficiency benchmarks that push suppliers toward low-power OLED and transflective LCD technologies. Nagoya and Hamamatsu concentrate thin-film transistor R&D for motorcycle-specific form factors.
United States
FCC certification governs wireless connectivity modules embedded in North American-sourced clusters, adding compliance complexity for Bluetooth-enabled displays. Aftermarket retrofit demand grows among existing fleet owners seeking plug-in digital upgrades. California and Michigan anchor electronics integrator relationships with adventure touring distributors.
China
Display panel suppliers serve mid-tier motorcycle segments through cost-optimized TFT alternatives, though OLED input cost volatility constrains margin expansion. MIIT standards shape electromagnetic compatibility for units targeting export markets. Yangtze River Delta clusters concentrate glass-reinforced polycarbonate housing fabrication for vibration-resistant enclosures.
Motorcycle Instrument Cluster Market Competitive Environment
Global majors compete with regional champions across certification and localization capabilities, creating a tiered structure where captive production coexists with independent electronics integrators. The vendor base separates into automotive display specialists, motorcycle-captive manufacturers, and tier-1 electronics suppliers. Three archetypes dominate: vertically integrated OEMs controlling design-to-assembly pipelines; diversified automotive suppliers leveraging cross-platform display expertise; and regional electronics houses capturing aftermarket retrofit volumes. Competitive moves center on strategic partnerships for certification bundling and capacity expansion in India's manufacturing belt.
Within the diversified automotive supplier tier, Bosch leverages cross-platform display expertise to anchor European premium cluster supply chains, while Denso Corporation sustains R&D positioning in thin-film transistor integration. Yamaha Motor Co., Ltd. exemplifies the vertically integrated archetype through captive production control. These three entities represent distinct strategic postures: technology licensing breadth, component specialization depth, and end-to-end supply chain ownership.
| Leading Market Players |
|---|
| Yamaha Motor Co., Ltd. |
| Denso Corporation |
| Bosch |
| Yazaki Corporation |
| Magneti Marelli S.p.A. |
| Continental AG |
| Nippon Seiki Co., Ltd. |
| Honda Motor Co., Ltd. |
| Visteon Corporation |
| Others |
Value Chain & Pricing Dynamics
OLED panel price indices cascade through motorcycle instrument cluster supply chains into three distinct procurement tiers, compressing margins for mid-tier suppliers while premium TFT integrators capture connectivity bundling premiums. Glass-reinforced polycarbonate resin costs and thin-film transistor wafer pricing determine whether suppliers can absorb REACH compliance expenses or must pass them downstream to OEMs.
Pricing Analysis
Input-cost pass-through from display panel volatility stratifies pricing across premium, standard, and economy tiers. Premium-mid-economy pricing differentiation reflects certification grade divergence between ECE R10-validated modules and BIS-registered alternatives for the Indian market. Pricing pressure stems from OLED input cost volatility constraining margin expansion for suppliers targeting mid-tier segments. Aftermarket retrofit buyers exhibit highest price sensitivity, while Germany's premium sportbike OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
India's PLI scheme for automotive electronics and domestic-content thresholds for government procurement are reshaping sourcing patterns toward Chennai-Pune corridor localization. Display panel supply concentrates in China, South Korea, and Japan, while glass-reinforced polycarbonate housing fabrication clusters in the Yangtze River Delta and Germany. Raw material dependencies on TFT substrates, Hall-effect sensors, and UV-stabilized polymers create single-source vulnerability for specialized motorcycle form factors. Distribution runs through direct OEM procurement channels consolidating previously fragmented tier-2 relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as rider demand shifts toward smartphone mirroring and turn-by-turn navigation specifications that command premium positioning. OEM procurement consolidation favors suppliers with bundled certification capabilities and localized production footprints.
For Market Incumbents: Deploy certification bundling as the primary defensive lever against emerging electronics integrators from China's Yangtze River Delta. Secure ECE R10 and FCC validation pipelines simultaneously to streamline homologation for EU and North American-bound motorcycle models. Add captive TFT assembly capacity within India's Chennai-Pune belt before BIS automotive electronics deadlines reshape sourcing decisions. For New Entrants and Emerging Players: Begin with aftermarket plug-and-play retrofit clusters targeting existing fleet owners in the United States and Germany where labor cost minimization drives purchasing decisions. Heritage hybrid cluster white space offers penetrable entry points as classic dial aesthetics combined with digital odometer modules address regulatory compliance without alienating traditionalist buyer segments. Pursue direct-to-rider e-commerce channels bypassing established distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-1 electronics suppliers possessing India BIS certification readiness and thin-film transistor integration capabilities for motorcycle-specific form factors. Long-term viability over a multi-year horizon hinges on positioning for connected-feature bundling as navigation and telemetry interfaces displace standalone GPS units. Monitor EU F-Gas Regulation enforcement intensity as the inflection signal for accelerated analog gauge obsolescence and stranded capacity risk.| Strategic Initiative | Industry Significance |
|---|---|
| TFT Cluster Localization | Chennai-Pune capacity expansion reduces import dependency for India's domestic OEM procurement. |
| Certification Bundling | Combined ECE R10 and FCC validation streamlines homologation for multi-region motorcycle programs. |
| Smartphone Mirroring Integration | Navigation bundling captures margin pools previously served by standalone handlebar-mounted GPS units. |
| Heritage Hybrid Cluster Development | Classic dial aesthetics with digital odometer accuracy address REACH compliance without alienating traditionalist segments. |
| Glass-Reinforced Polycarbonate Adoption | Material substitution from ABS enables weight reduction and vibration resistance improvements OEM specifications demand. |
Study Parameters
Direct dialogue with motorcycle OEM platform engineers, tier-1 supplier procurement leads, TFT display integrators, and aftermarket distribution channel heads grounded the qualitative foundation. Secondary validation drew from vehicle production databases, BIS automotive electronics certification timelines, ECHA REACH substance restriction updates, and customs records for glass-reinforced polycarbonate trade flows. Bottom-up cluster shipment estimates triangulated against top-down two-wheeler production forecasts across the analysis window.
Segmented outputs across product type, technology architecture, end-user channel, and installation methodology informed the analytical framework throughout the projection horizon. CAGRs derived from regression analysis against historical TFT penetration curves and analog gauge phase-out trajectories. Forecast inputs incorporated EU F-Gas Regulation enforcement schedules, India PLI scheme uptake rates, and OLED panel price elasticity assumptions for mid-tier motorcycle segments.
Several conditions sit outside the modeled scope, including potential delays in India BIS certification implementation, unanticipated raw material substitutions for REACH-restricted substances, and disruptive consolidation among China's display panel suppliers. Forecasts reflect documented assumptions regarding regulatory deadline adherence and technology cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Bicycle Saddles Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market