
 Two Wheeler Fenders Market | 2026-2036
Two Wheeler Fenders Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Fenders Market Outlook
Polymer composite molding is narrowing cost gaps between thermoplastic fenders and conventional steel alternatives across high-volume scooter platforms. SKS-Germany leverages its European tooling expertise to supply premium OEM fitments for adventure-touring motorcycles. Topeak sustains a dominant position in clip-on aftermarket mudguards through bicycle-to-motorcycle technology transfer. Omax Auto anchors India's replacement-fender segment with steel stamping capacity serving Hero and Bajaj service networks.
Two wheeler fenders are protective body panels mounted above wheels to deflect road debris, water spray, and contaminants from the rider and engine bay, typically manufactured through injection molding of ABS or polypropylene blends or through press-forming of cold-rolled steel with surface phosphate treatment and e-coat finishing. Plastic front fenders now lead OEM specifications across commuter motorcycles under 150cc displacement due to weight-reduction targets and corrosion immunity in monsoon climates. Aftermarket replacement channels for steel rear fenders retain margin concentration in rural Indian and Indonesian markets where collision damage and rust drive frequent swap-outs. Full plastic fender assemblies compete with split mudguard designs in European electric scooter platforms where integrated LED housing and cable routing demand unitary construction.
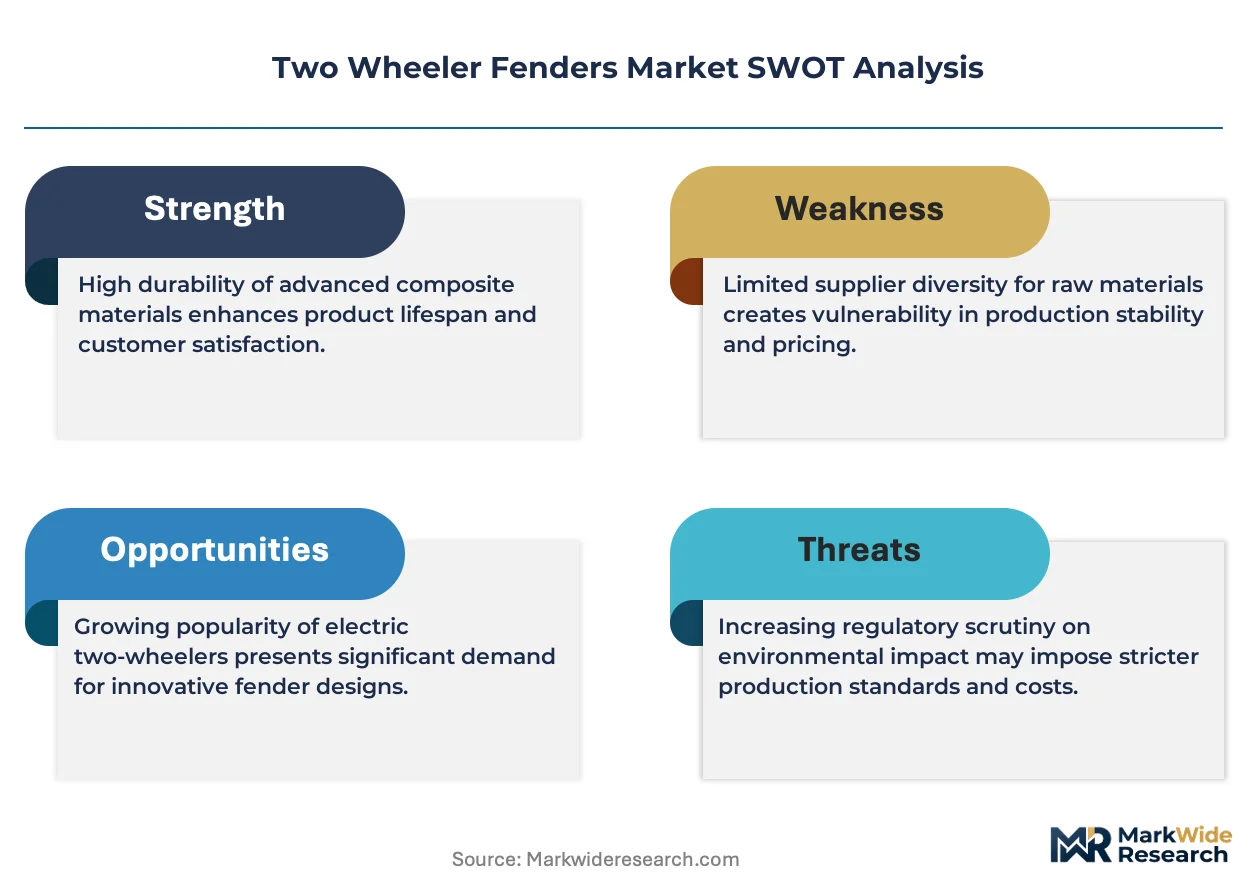
India's BIS and ARAI enforce impact-resistance and material-flammability standards that shape fender substrate selection for domestic-market two-wheelers. REACH and RoHS compliance in Europe restricts certain plasticizers and heavy-metal pigments in colored fender compounds, elevating formulation costs for exporters. Stakeholders must monitor how India's PLI scheme for auto components and Vietnam's evolving industrial-zone environmental rules reshape regional sourcing decisions for stamped and molded fender supply.
Market Dynamics
Polymer composite molding is compressing cost differentials between thermoplastic fenders and steel alternatives, while India's BIS certification mandates force substrate upgrades across Southeast Asian supplier networks serving Honda and Yamaha assembly plants.
Growth Catalysts
- India's PLI scheme for auto components:Production-linked incentives are accelerating domestic fender stamping capacity expansion for Hero and Bajaj supply chains.
- ABS and polypropylene blend adoption:Injection molding of polymer composites is displacing steel in commuter motorcycles under 150cc displacement across Vietnam's northern industrial corridor.
- Monsoon climate corrosion immunity:Plastic front fenders are capturing OEM specifications across Southeast Asian markets where water exposure degrades metal alternatives.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings compress margins for stamped rear fender producers serving rural Indian replacement channels.
- Vietnam supplier concentration:Dense component ecosystems around Honda and Yamaha facilities create single-source vulnerability for regional OEM procurement.
- REACH and RoHS compliance costs:European restrictions on plasticizers and heavy-metal pigments elevate formulation expenses for colored fender compound exporters.
Strategic Opportunities
- European electric scooter platforms:Integrated LED housing and cable routing requirements favor unitary plastic fender construction over split mudguard designs.
- ARAI impact-resistance mandates:Tightening material-flammability standards create certification barriers that favor established compound formulators over new entrants.
- Aftermarket unbundling:Direct-to-workshop digital channels are bypassing traditional distributor tiers in Indonesian collision-repair networks.
Industry Challenges
- Tooling capex intensity:Precision injection molds for complex fender geometries require capital outlays that strain mid-tier suppliers.
- BIS certification timelines:Extended approval cycles for new material grades delay product launches in India's replacement market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Fenders Market |
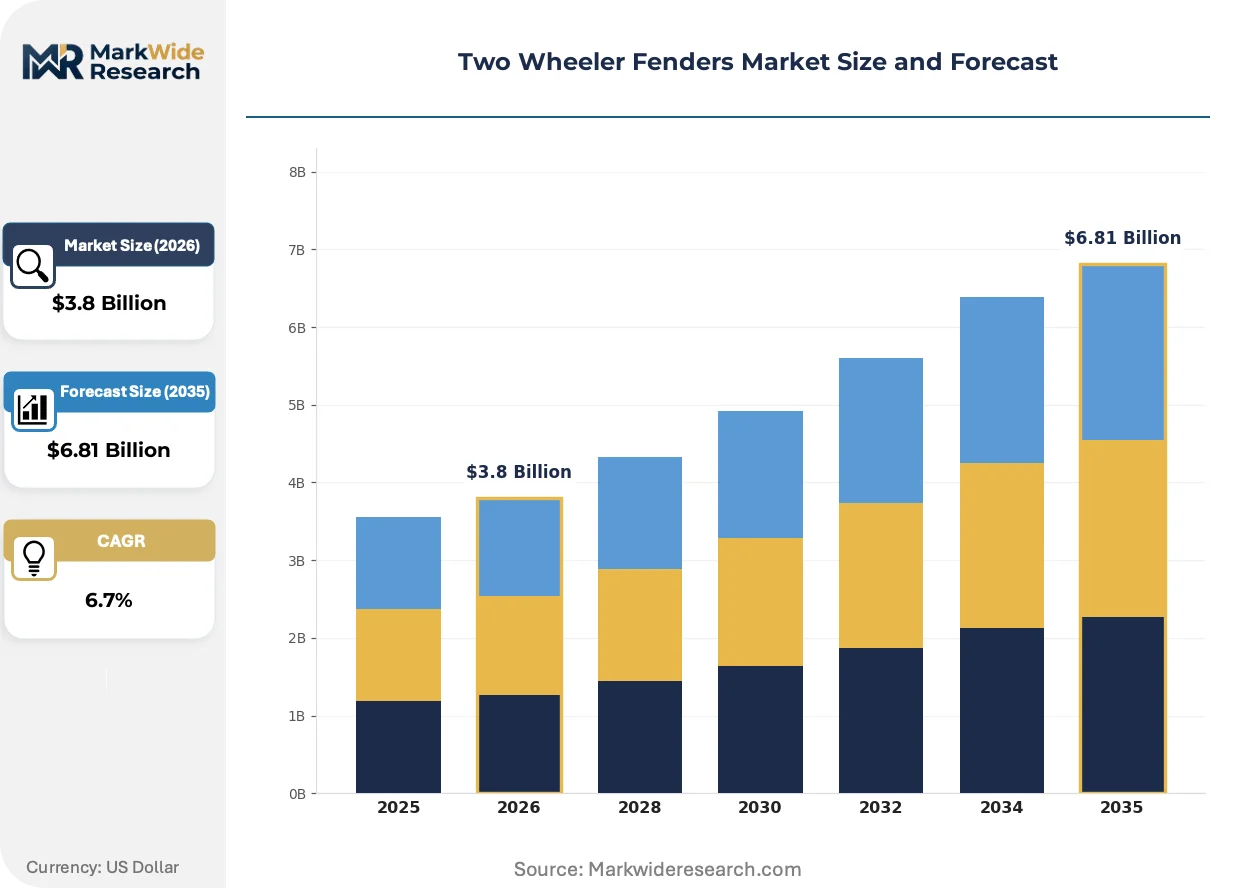
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Fender, Rear Fender, Mudguard, Full Plastic Fender Material: Plastic, Steel, Aluminum, Fiber Installation Type: OEM, Aftermarket, Custom, Replacement End User: Manufacturers, Dealerships, DIY Consumers, Workshops |
| Companies Covered | SKS-Germany, Crud Products, Zefal, Ass Savers, PDW, Axiom, RapidRacerProducts, Topeak, Omax Auto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Fenders Market Strategic Shifts
Digital twin simulation is compressing fender design-to-production cycles, while regulatory fragmentation across ASEAN and European markets forces parallel certification tracks for shared tooling investments.
Generative design software paired with topology optimization is virtualizing traditional stamping die development for steel rear fenders. Tier-1 suppliers serving Bajaj and Hero are adopting these tools to reduce prototype iteration counts. The technology is virtualizing physical trial-and-error workflows that previously consumed months in Indian toolrooms.
India's BIS and ARAI are tightening impact-resistance testing protocols for two-wheeler safety components. Domestic-market OEMs must now validate fender substrates against revised material-flammability benchmarks. Scooter manufacturers in Pune and Chennai are restructuring supply agreements to transfer certification liability upstream to compound suppliers.
Fleet operators and ride-hailing platforms are consolidating aftermarket procurement through centralized maintenance contracts. Traditional parts distributors in Jakarta and Ho Chi Minh City are losing volume to direct-supply arrangements with workshop chains. This concentration is most visible in Vietnamese urban corridors where Grab and Be dominate two-wheeler utilization rates.
Two Wheeler Fenders Market Segmentation
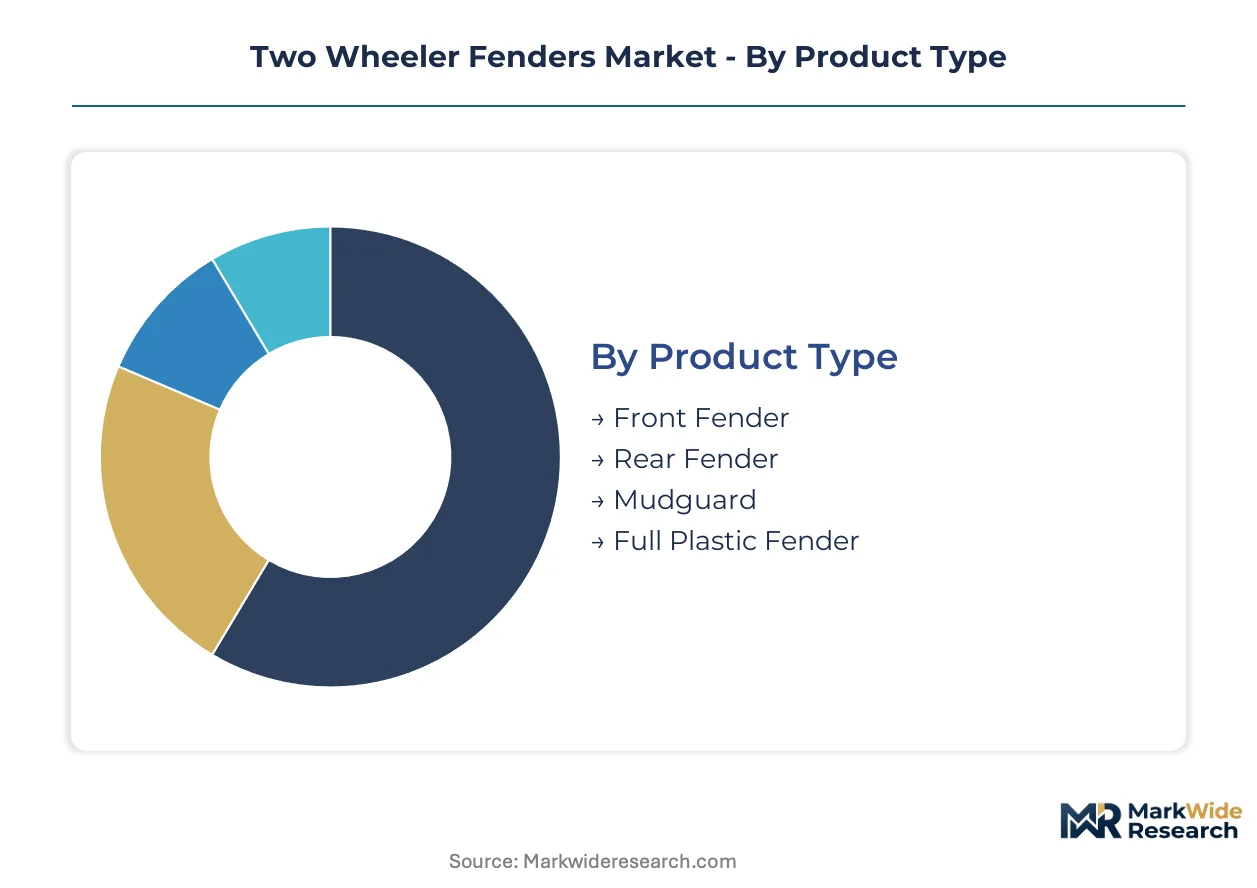
Fender segmentation in two-wheeler markets tracks divergent material specifications across OEM assembly lines versus aftermarket collision-repair channels. Procurement patterns split sharply between volume-driven commuter platforms and premium adventure-touring fitments with integrated LED routing.
Product Type:
The use-case spectrum spans protective debris deflection on unpaved rural routes through aerodynamic integration on urban electric scooters.
- Front Fender:Injection-molded ABS dominates commuter motorcycles under 150cc displacement where weight targets and monsoon corrosion resistance override metal alternatives. Vietnam's northern industrial corridor concentrates Honda and Yamaha supplier procurement of these assemblies.
- Rear Fender:Press-formed cold-rolled steel retains margin concentration in rural Indian replacement channels where collision damage and rust drive frequent swap-outs. BIS certification timelines delay new material grade launches in this segment.
- Mudguard:Clip-on aftermarket designs serve bicycle-to-motorcycle technology transfer applications in European adventure-touring platforms.
- Full Plastic Fender:Unitary construction competes with split designs where integrated LED housing and cable routing demand seamless geometries on electric scooter platforms.
The dominant share belongs to Front Fender, while Full Plastic Fender is closing the gap fastest.
Material:
Cost tier stratification separates premium compound formulations from commodity-grade substrates in regional supplier networks.
- Plastic:Polypropylene blends and ABS compounds displace steel across Southeast Asian OEM specifications due to REACH and RoHS compliance requirements elevating European export formulation costs. India's PLI scheme accelerates domestic injection molding capacity for Hero and Bajaj supply chains.
- Steel:Cold-rolled stamping with phosphate treatment and e-coat finishing anchors India's replacement-fender segment serving rural collision-repair networks. Input price volatility compresses margins for independent stampers.
- Aluminum:Premium adventure-touring motorcycles specify die-cast or sheet-formed alloys where weight reduction justifies material cost premiums.
- Fiber:Carbon and glass-reinforced composites occupy niche performance applications with limited volume scaling.
Plastic commands volume leadership, though Aluminum is expanding most quickly in premium displacement categories.
Installation Type:
Customer type determines channel structure, with fleet consolidation reshaping traditional distributor tiers in urban maintenance networks.
- OEM:Front and rear fender assemblies procured directly by motorcycle manufacturers in Vietnam's dense component ecosystems around Honda and Yamaha facilities.
- Aftermarket:Traditional parts distributors in Jakarta and Ho Chi Minh City face volume erosion from direct-supply arrangements with workshop chains serving Grab and Be fleet operators.
- Custom:Specialty fabricators serve adventure-touring modification markets with non-standard fitments.
- Replacement:Collision-damage swap-outs concentrate in rural Indian and Indonesian markets where steel rear fenders dominate.
OEM captures the largest value pool, while Aftermarket is gaining share fastest through digital channel unbundling.
End User:
Supply concentration varies across centralized fleet procurement versus fragmented individual consumer transactions.
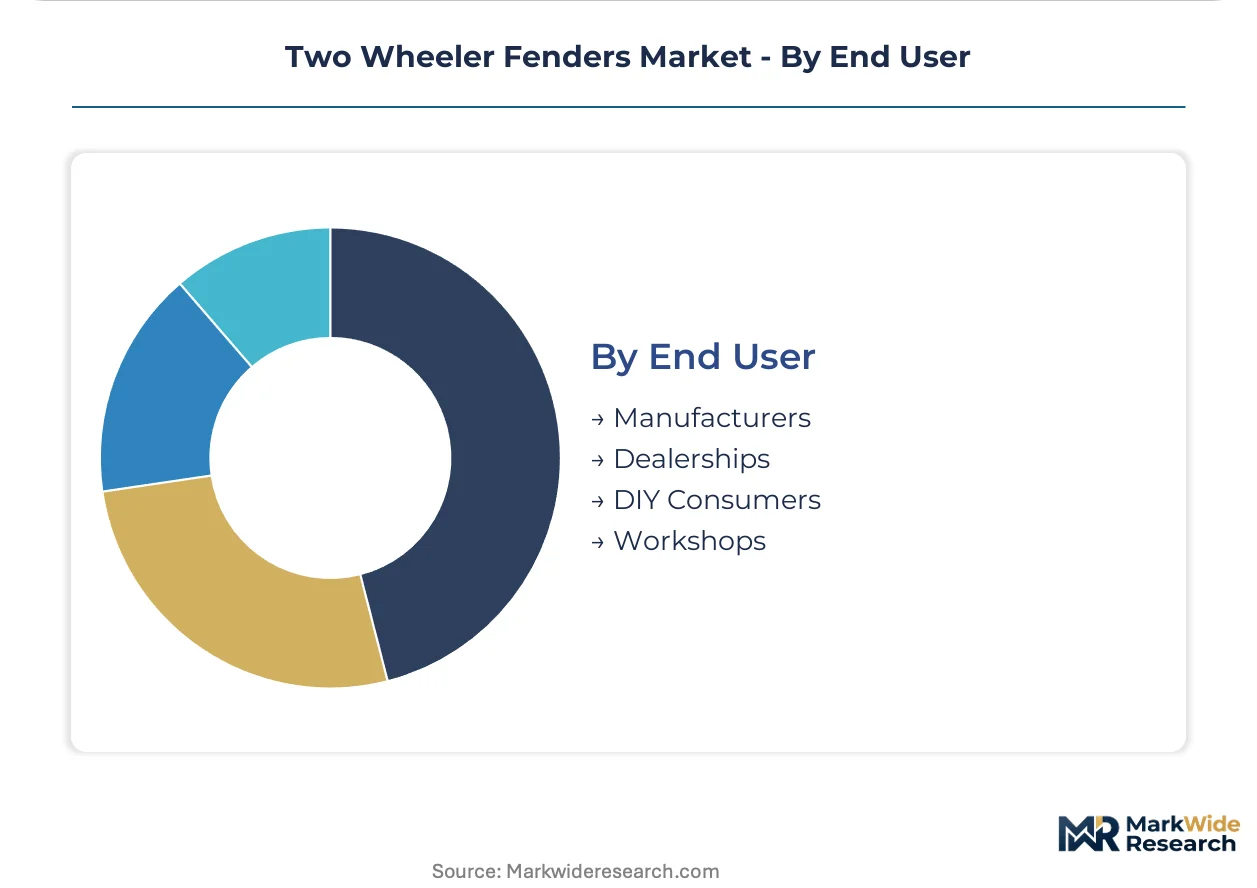
- Manufacturers:Tier-1 suppliers serving Bajaj and Hero adopt generative design software to compress stamping die development cycles in Indian toolrooms.
- Dealerships:Authorized service networks handle warranty-related fender replacements with OEM-specified substrates.
- DIY Consumers:Individual purchasers access clip-on mudguards through bicycle-to-motorcycle technology transfer channels.
- Workshops:Independent repair facilities in Indonesian collision-repair networks bypass traditional distributor tiers through direct-to-workshop digital procurement.
Manufacturers absorb the dominant procurement volume, while Workshops are climbing the fastest through fleet-operator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement teams concentrate in Vietnam's northern industrial corridor, while replacement demand clusters in rural Indian and Indonesian markets where collision damage drives frequent steel fender swap-outs. Fleet operators in Jakarta and Ho Chi Minh City are consolidating aftermarket procurement through centralized maintenance contracts with Grab and Be.
India
Hero and Bajaj anchor domestic fender demand through their extensive service networks across Maharashtra and Gujarat. BIS certification mandates for impact-resistance and material-flammability standards tighten substrate selection for commuter motorcycles under 150cc displacement. The PLI scheme for auto components accelerates stamping capacity expansion in Pune and Chennai manufacturing clusters.
Vietnam
Honda and Yamaha suppliers operate dense component ecosystems in the northern industrial corridor around Hanoi and Hai Phong. Domestic environmental regulations in industrial zones reshape sourcing decisions for molded fender supply. Injection molding of ABS and polypropylene blends displaces steel across OEM specifications in this manufacturing concentration.
Indonesia
Traditional parts distributors in Jakarta face volume erosion from direct-supply arrangements with workshop chains serving ride-hailing fleet operators. Rural collision-repair networks retain margin concentration for steel rear fenders where rust and road damage drive frequent replacements. Aftermarket unbundling through digital channels bypasses traditional distributor tiers in urban maintenance networks.
Germany
SKS-Germany leverages European tooling expertise to supply premium OEM fitments for adventure-touring motorcycles. REACH and RoHS compliance restricts certain plasticizers and heavy-metal pigments in colored fender compounds, elevating formulation costs for exporters serving German manufacturers. Die-cast and sheet-formed aluminum alloys occupy premium displacement categories where weight reduction justifies material cost premiums.
Japan
METI standards and JIS certification requirements shape fender substrate selection for domestic-market two-wheelers and regional export platforms. Motorcycle OEMs source front and rear fender assemblies through established supplier networks in the Kanto and Kansai industrial belts. Topology optimization software virtualizes traditional stamping die development for steel rear fenders in tier-1 supplier toolrooms.
Two Wheeler Fenders Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply structures. OEM procurement concentrates around established tier-1 suppliers with certified stamping and molding capacity, while aftermarket channels fragment across independent distributors and emerging direct-to-workshop digital platforms. Three archetypes dominate: European premium-fitment specialists, Asian volume manufacturers serving commuter platforms, and regional replacement-part distributors with dense service network coverage. Competitive moves center on backward integration into compound formulation and tooling capacity expansion in Vietnam's northern industrial corridor.
Among European premium-fitment specialists, SKS-Germany exemplifies the tooling-expertise archetype serving adventure-touring motorcycle OEMs. Topeak occupies a position within the technology-transfer segment, applying bicycle component expertise to motorcycle clip-on aftermarket mudguards. Omax Auto anchors the India-focused replacement-fender segment with steel stamping capacity. These three represent distinct competitive vectors: premium OEM supply, cross-category technology adaptation, and domestic aftermarket scale.
| Leading Market Players |
|---|
| SKS-Germany |
| Crud Products |
| Zefal |
| Ass Savers |
| PDW |
| Axiom |
| RapidRacerProducts |
| Topeak |
| Omax Auto |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Vietnam's northern industrial corridor for Honda and Yamaha supplier procurement compresses both pricing tier spreads and supply chain resilience across Southeast Asian two-wheeler fender markets. BIS certification timelines in India and REACH compliance costs in Europe amplify cost differentials between certified compound formulators and uncertified competitors.
Pricing Analysis
Cost-plus contracts with cold-rolled steel indexation dominate stamped rear fender procurement serving rural Indian replacement channels. Three-tier pricing structure across premium OEM fitments, standard commuter assemblies, and economy-grade aftermarket swaps reflects certification grade and volume scale differentiation. Pricing pressure stems from commodity volatility in steel inputs and polymer resin feedstocks. Fleet operators through Grab and Be maintenance contracts exhibit lowest price sensitivity; independent rural workshops face acute margin compression.
Supply Chain Analysis
Tariff exposure between Vietnam and European destination markets elevates landed costs for ABS and polypropylene blend exporters. Manufacturing concentrates in Vietnam, India, and China with raw material dependencies on Saudi-sourced polymer resins, Australian iron ore for steel, and Japanese injection molding equipment. Single-source vulnerability pervades Honda and Yamaha supplier ecosystems around Hanoi. Distribution runs through tier-1 OEM direct procurement, traditional aftermarket distributors, and emerging direct-to-workshop digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision tooling expertise for complex fender geometries represents the scarcest capability layer, separating viable tier-1 suppliers from margin-challenged stampers. This scarcity concentrates competitive advantage among compound formulators with BIS pre-certification and mold-makers with generative design software deployment.
For Market Incumbents: Harden supply positions by acquiring captive injection molding capacity in Vietnam's Hai Phong industrial zone and pre-certifying polymer grades against tightening ARAI material-flammability benchmarks. Defensive consolidation must neutralize digital channel unbundling threats from direct-to-workshop procurement platforms eroding traditional distributor margins. For New Entrants and Emerging Players: Rural Indonesian collision-repair networks offer the most penetrable white-space for steel rear fender supply, with rust-driven replacement cycles outpacing OEM plastic conversion. Entry should anchor on BIS certification arbitrage—supplying uncertified grades to informal channels while building approval timelines for formal market access. Digital-first procurement partnerships with Grab-affiliated workshop chains provide the cleanest go-to-market vector. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compound formulators with pre-certified substrate libraries and toolrooms with topology optimization capabilities. Long-term viability over a five-to-ten year window rests on backward integration into polymer formulation rather than pure stamping or molding operations. The signal to watch is BIS approval velocity for new material grades, which gates product launch cadence and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Tooling Capacity Expansion | Generative design software deployment in Indian toolrooms compresses die development cycles for Bajaj and Hero supply chains. |
| Backward Integration into Compounding | In-house ABS and polypropylene blend formulation captures margin from certified substrate supply to Vietnam-based OEM assembly. |
| Digital Channel Development | Direct-to-workshop platforms bypass Jakarta and Ho Chi Minh City distributor tiers serving Grab fleet maintenance contracts. |
| Certification Pre-Investment | Early BIS and ARAI validation for impact-resistant compounds accelerates product launch timelines in India's replacement market. |
| Geographic Manufacturing Footprint | Hai Phong industrial zone presence secures proximity to Honda and Yamaha supplier ecosystems in Vietnam's northern corridor. |
Study Parameters
A standing panel of tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and compound formulation specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from BIS certification registries, ARAI test protocols, Vietnam industrial zone investment disclosures, and customs trade data for polymer resin and cold-rolled steel flows. Bottom-up production capacity assessments triangulated against top-down OEM assembly volume estimates.
Scenario-bracketing around steel price volatility bands and PLI scheme uptake rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, material substrate, installation channel, and end-user category with regional production cluster overlays. CAGRs derived from unit volume trajectories indexed to OEM platform launch schedules and fleet operator procurement consolidation patterns. Industry-specific forecast inputs incorporated monsoon corrosion damage frequency and electric scooter platform adoption curves.
Practitioners should monitor BIS certification backlog durations, REACH amendment proposals, and Vietnam environmental rule enforcement intensity for early signals of supply constraint or cost acceleration. Forecasts reflect assumptions about regulatory stability, commodity input trends, and fleet operator market share consolidation that may shift with policy or competitive dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Italy E-Bike Market