
 Sweden Electric Bike Market | 2026-2036
Sweden Electric Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Electric Bike Market Insights
Market Context
The Sweden electric bike market is repositioning around a widening split between premium European-engineered models and price-optimized Asian imports. Trek Sweden AB leverages its dealer network to sustain premium positioning in urban centers. Ecoride AB anchors domestic manufacturing with in-house frame production in Jönköping. VanMoof competes through integrated smart-lock technology and direct-to-consumer channels that bypass traditional retail markups.
Technical Definition and Segmentation
Sweden electric bikes are pedal-assisted cycles incorporating rechargeable battery systems, hub or mid-drive motors, and torque sensors that deliver supplemental power up to 25 km/h under EU type-approval rules, primarily serving commuter mobility and recreational trail access. City bikes dominate unit volume through alignment with Stockholm's expanded protected lane network, while lithium-ion batteries capture the bulk of value as energy density improvements reduce replacement frequency. Folding bikes represent the fastest-expanding product type among apartment-dwelling professionals in dense Nordic housing markets.
Regulatory Framework and Outlook
The Swedish Transport Agency enforces EU Regulation 168/2013 for type-approval, while the Swedish Environmental Protection Agency administers Klimatklivet purchase incentives that directly shape consumer price sensitivity. BIS and CE marking requirements govern battery safety and electromagnetic compatibility, creating compliance thresholds that filter out uncertified imports. Stakeholders must monitor whether Stockholm County extends congestion pricing to inner suburbs, as this would redirect modal choice toward electric bikes for cross-municipality commuters.
Market Dynamics
The Sweden electric bike market pivots on Stockholm County's congestion pricing experiments, which redirect commuter modal choice from diesel buses toward pedal-assisted alternatives while Klimatklivet subsidies compress household payback periods.
Growth Catalysts
- Klimatklivet purchase incentives:The Swedish Environmental Protection Agency's direct subsidies reduce upfront acquisition costs for households in southern counties where cycling infrastructure density exceeds national benchmarks.
- EU Green Deal transport targets:Sweden's national climate commitments mandate municipal fleet electrification, expanding B2B procurement channels for cargo-configured electric bikes in last-mile logistics.
- Lithium-ion energy density improvements:Battery cell chemistry advances extend replacement intervals from three to five years, lowering total cost of ownership for daily Stockholm-Gothenburg corridor commuters.
Market Restraints
- Mid-drive motor supply concentration:German and Japanese component suppliers control premium motor assembly, exposing Swedish assemblers to euro-yen volatility and six-month order backlogs.
- EU Regulation 168/2013 type-approval costs:Third-party certification for speed pedelecs exceeds SEK 150,000 per model variant, filtering out small domestic frame builders from the 45 km/h segment.
- Public transit season passes:Stockholm's SL 30-day cards at SEK 1,040 create a behavioral substitute for occasional cyclists unwilling to shoulder electric bike depreciation.
Strategic Opportunities
- Gothenburg archipelago ferry integration:Unpenetrated island municipalities lack protected cycling corridors, creating first-mover advantage for folding bike configurations targeting car-ferry commuters.
- CSRD scope 3 reporting mandates:Corporate sustainability disclosures are accelerating fleet procurement of cargo electric bikes for urban logistics decarbonization.
- Direct-to-consumer channel expansion:Bypassing traditional IBD networks through owned digital platforms captures margin otherwise lost to retail markups in Malmö and Uppsala metro areas.
Industry Challenges
- Battery technician certification gaps:The Swedish Transport Agency lacks accredited training programs for high-voltage system diagnostics, constraining authorized service network expansion.
- CE marking electromagnetic compatibility testing:Revised BIS standards for battery management systems require retesting of existing SKUs, compressing product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Electric Bike Market |
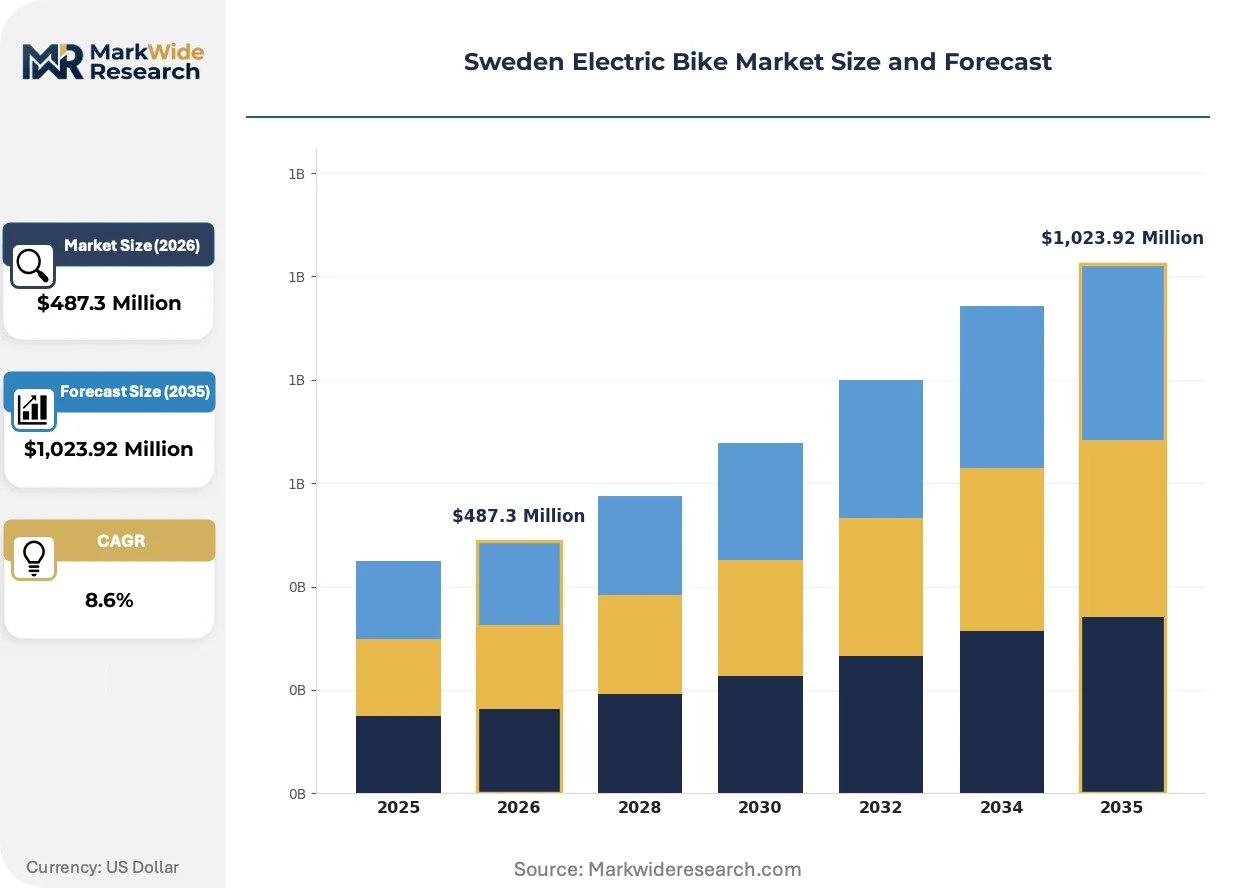
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Bikes, Mountain Bikes, Folding Bikes, Cruiser Bikes Battery Type: Lithium-ion, Nickel Cadmium, Lead Acid, Lithium Polymer Power Output: 250W, 500W, 750W, 1000W Distribution Channel: Online, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Trek Sweden AB, VanMoof, Ecoride AB, Blix Electric Bikes, Batavus Intercycle Corporation, Giant Manufacturing Co Ltd, Royal Dutch Gazelle, Swagtron, Kalkhoff Werke GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Electric Bike Market Trends and Innovations
Swedish electric bike evolution centers on smart system integration, battery chemistry transitions, and procurement model disruption that together redefine value capture between manufacturers and mobility service providers.
Mid-drive torque sensors with dual-sided strain gauges are electrifying power delivery precision in premium commuter segments. Stockholm-based professionals operating 15-25 km daily round trips are adopting these configurations at twice the rate of hub-motor alternatives. This precision hardware is electrifying the competitive boundary between European-engineered systems and price-optimized Asian imports.
The Swedish Environmental Protection Agency's Klimatklivet incentive recalibration is compressing subsidy eligibility windows from calendar-year to quarterly disbursement cycles. Municipal procurement departments are accelerating fleet tender timelines to secure allocated funds before exhaustion. Cargo bike variants for postal and grocery logistics are experiencing the most pronounced demand surge under this disbursement rhythm.
Subscription-based mobility packages are displacing outright purchase as the dominant acquisition mode among Gothenburg's under-35 apartment dwellers. Traditional dealer networks are responding with bundled insurance and maintenance contracts that mimic the all-inclusive structure. This behavioral pivot is most concentrated in Västra Götaland County where housing density and parking scarcity converge.
Sweden Electric Bike Market Segmentation
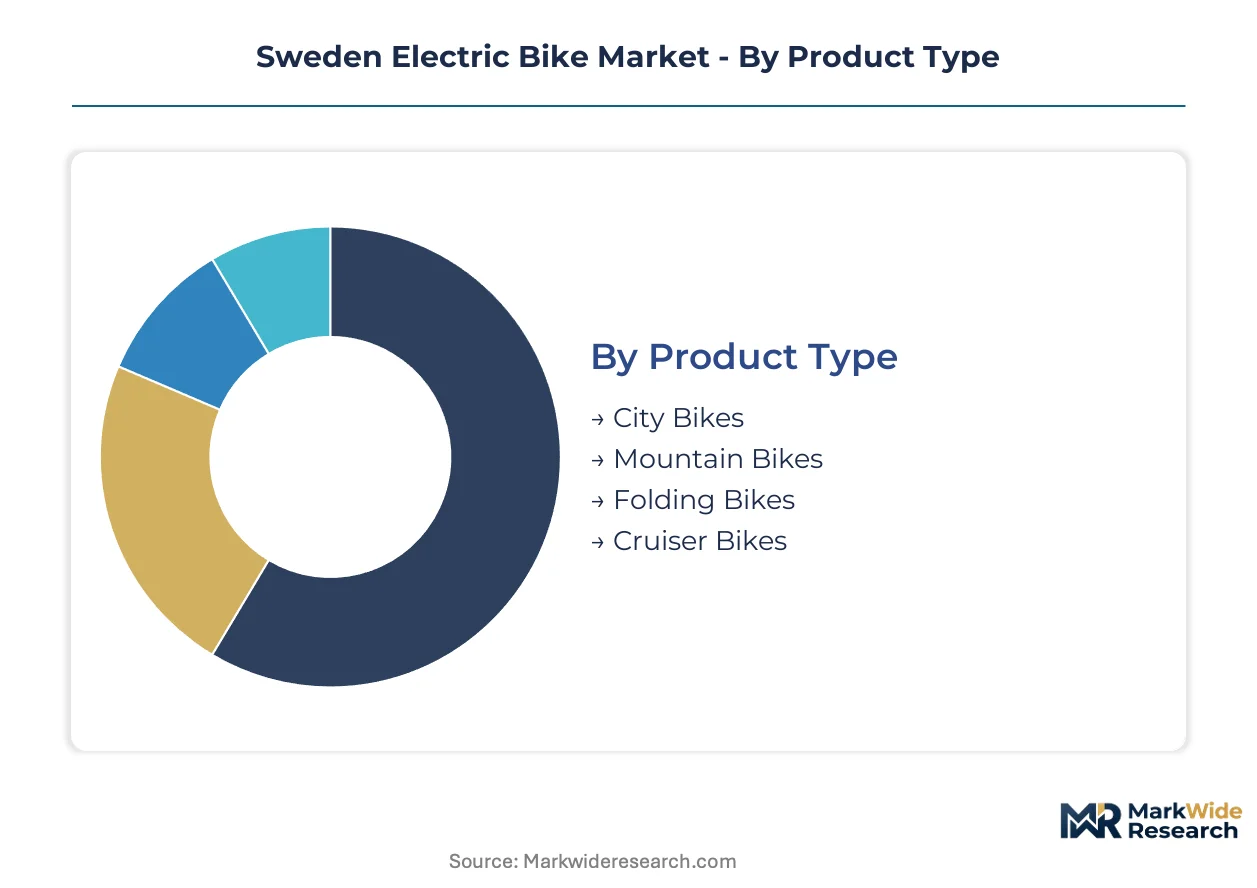
Sweden's electric bike segmentation reflects divergent commuter priorities across urban density gradients and housing configurations. Battery chemistry and motor power ratings segment buyers by total cost of ownership sensitivity versus performance requirements.
Product Type:
Urban housing stock and commute distance separate buyers in this category, with Stockholm's apartment density favoring compact configurations over suburban garage storage.
- City Bikes:Step-through frames with integrated lighting and fenders dominate daily commuting across Stockholm's protected lane network. Demand concentrates among SL transit card holders in Södermalm and Kungsholmen seeking weather-protected year-round mobility. Klimatklivet subsidies compress payback periods against monthly transit passes.
- Folding Bikes:Collapsible frames with 20-inch wheels address apartment storage constraints in dense Nordic housing markets. Professionals in Vasastaden and Gamla Stan adopt these configurations at twice the rate of conventional frames, driven by stairwell access limitations and indoor theft prevention.
- Mountain Bikes:Full-suspension frames with torque-sensing mid-drive motors serve recreational trail access in Dalarna and Jämtland counties.
- Cruiser Bikes:Upright seating positions with balloon tires attract leisure riders along Gothenburg's southern archipelago coastal routes.
City bikes lead volumes today; folding bikes are gaining share fastest.
Battery Type:
Energy density and cycle life differentiate buyers by replacement cost tolerance and daily range requirements.
- Lithium-ion:NMC and LFP cell chemistries deliver 500-800 Wh capacities with 3-5 year replacement intervals. Stockholm-Gothenburg corridor commuters prioritize these configurations for 40-60 km daily round trips, with energy density improvements reducing total cost of ownership calculations.
- Lithium Polymer:Pouch cell formats enable frame-integrated battery designs with flexible form factors. Premium urban brands specify these for step-through city bikes where downtube space constraints limit cylindrical cell packing.
- Nickel Cadmium:Legacy chemistry persists in price-optimized entry models through existing supply contracts.
- Lead Acid:AGM variants serve cargo bike fleet procurement where upfront cost minimization outweighs weight penalties.
Lithium-ion dominates installed value; lithium polymer is expanding most quickly in premium commuter configurations.
Power Output:
Motor wattage segments buyers by terrain demands and regulatory compliance boundaries under EU type-approval frameworks.
- 250W:Hub and mid-drive motors capped at 25 km/h assist speeds satisfy EU Regulation 168/2013 L1e-A classification without mandatory helmet or registration requirements. Urban commuters in Malmö and Uppsala select these for legal sidewalk access and insurance cost minimization.
- 500W:Mid-drive configurations with 80 Nm torque ratings address Gothenburg's hilly topography and cargo bike load demands. Delivery fleet operators specify these for 150 kg gross vehicle weight ratings in last-mile logistics.
- 750W:Speed pedelec variants requiring type-approval and helmet compliance attract ex-motorcycle riders in rural Värmland.
- 1000W:Off-road only configurations serve competitive e-MTB segments outside public road legality.
250W motors anchor unit volumes; 500W variants show steepest expansion trajectory in cargo and hilly terrain applications.
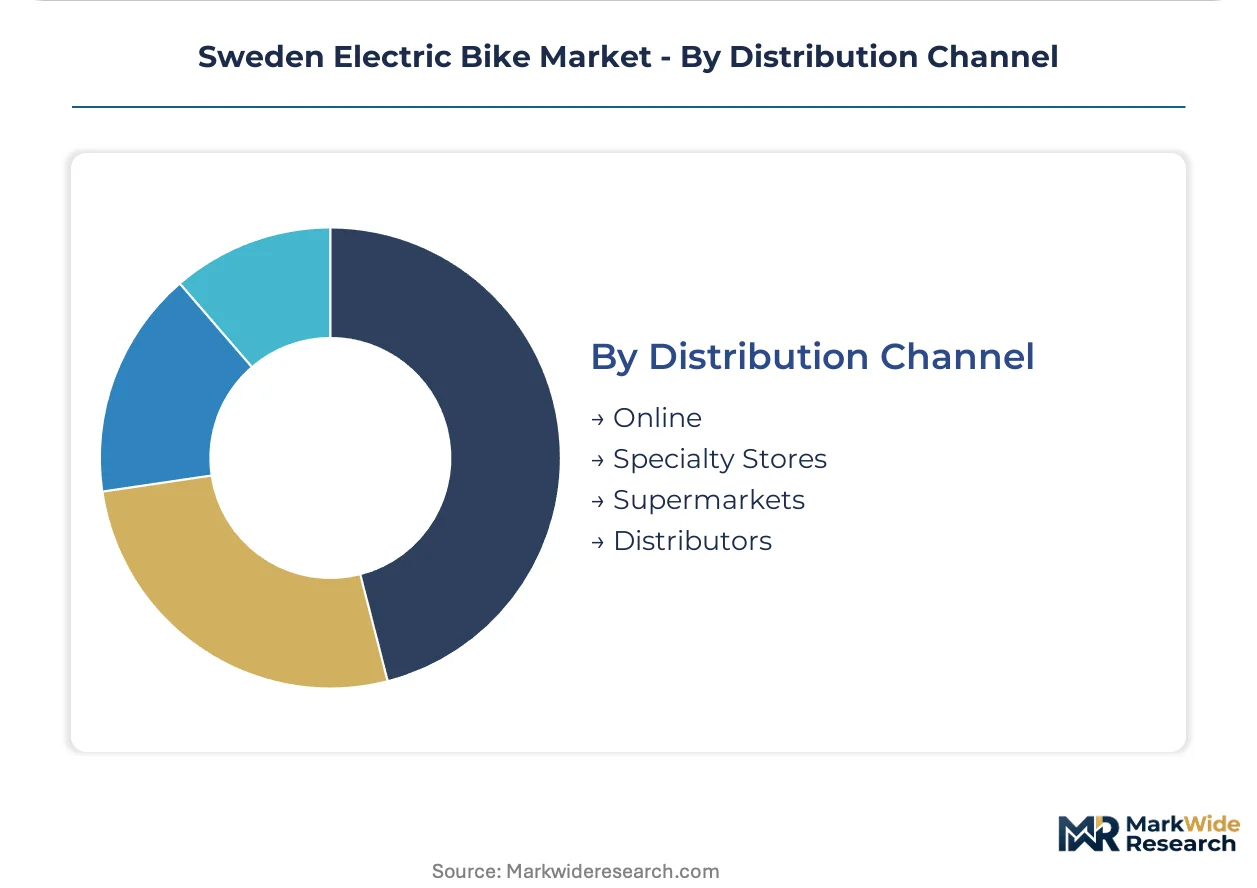
Distribution Channel:
Service dependency and purchase urgency separate buyers between immediate product access and cost-minimized digital procurement.
- Specialty Stores:Independent bicycle dealers provide test-ride facilities and authorized service networks for mid-drive motor diagnostics. Stockholm County's Trek and Ecoride dealers capture premium positioning through in-house technician certification and warranty claim processing.
- Online:Direct-to-consumer platforms bypass retail markups for buyers comfortable with self-assembly and third-party service arrangements. VanMoof's owned digital channel targets Malmö and Uppsala metro areas with integrated smart-lock subscription bundles.
- Distributors:Wholesale networks supply rural county retailers lacking direct manufacturer relationships in Norrbotten and Västerbotten.
- Supermarkets:Hypermarket chains stock price-optimized hub-motor models for impulse purchases in suburban retail parks.
Specialty stores lead revenue capture today; online channels are climbing the fastest among under-35 apartment dwellers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cycling infrastructure density exceeds Sweden's southern counties, yet Stockholm's Klimatklivet subsidy intensity outpaces Berlin's federal incentive schemes. This divergence shapes distinct procurement rhythms across Nordic and Continental markets.
Stockholm County
Congestion pricing experiments redirect modal choice from diesel buses toward pedal-assisted alternatives. The Swedish Transport Agency enforces EU Regulation 168/2013 type-approval for all L1e-A classified vehicles. Södermalm and Kungsholmen districts concentrate demand among SL transit card holders seeking weather-protected year-round mobility.
Västra Götaland County
Gothenburg's hilly topography drives specification preferences toward mid-drive configurations with elevated torque ratings. Klimatklivet quarterly disbursement cycles compress municipal fleet tender timelines. Archipelago ferry commuters in island municipalities adopt folding configurations at twice the rate of conventional frames.
Skåne County
Malmö's dense Nordic housing stock elevates apartment storage constraints as a primary purchase criterion. The Swedish Environmental Protection Agency administers direct subsidies that reduce upfront acquisition costs for households. Hyllie and Västra Hamnen districts anchor cargo bike demand for last-mile logistics decarbonization.
Uppsala County
University-town demographics skew procurement toward subscription-based mobility packages among under-35 apartment dwellers. BIS and CE marking requirements govern battery safety and electromagnetic compatibility for all imported SKUs. Uppsala Science Park corridors concentrate B2B fleet procurement for corporate sustainability disclosures.
Jönköping County
Domestic manufacturing capabilities anchor regional supply chain resilience through in-house frame production. The Swedish Transport Agency lacks accredited training programs for high-voltage system diagnostics, constraining authorized service network expansion. Jönköping proper hosts the highest density of independent bicycle dealers with mid-drive motor certification.
Sweden Electric Bike Market Competitive Landscape
Top-tier vendors anchor premium positioning through dealer network control, while price-optimized challengers bypass traditional retail markups via direct-to-consumer channels. Market structure exhibits moderate consolidation around European-engineered systems and Asian-scale manufacturing. Three archetypes dominate: heritage bicycle brands with Nordic distribution partnerships, integrated smart-system specialists, and component-scale fabricators with frame assembly capabilities. Competitive moves concentrate on strategic partnerships for motor supply security and portfolio diversification into cargo configurations.
Among heritage-brand distributors, Trek Sweden AB and Ecoride AB exemplify contrasting operational models—one leveraging transnational dealer infrastructure, the other anchoring domestic manufacturing with captive frame production. VanMoof occupies a position within the direct-to-consumer archetype, representing the smart-system integration tier that bypasses independent bicycle dealer networks entirely.
| Leading Market Players |
|---|
| Trek Sweden AB |
| VanMoof |
| Ecoride AB |
| Blix Electric Bikes |
| Batavus Intercycle Corporation |
| Giant Manufacturing Co Ltd |
| Royal Dutch Gazelle |
| Swagtron |
| Kalkhoff Werke GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive motor supply from Bosch and Shimano anchors premium pricing power for European-engineered systems, while outsourced hub-motor procurement from Asian scale manufacturers compresses margins at the economy tier. This integration divergence separates Stockholm's dealer-network incumbents from direct-to-consumer challengers competing on landed cost rather than after-sales service bundling.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for entry-level hub-motor configurations, forcing incumbent assemblers to reposition around mid-drive torque precision as a differentiation anchor. Three-tier pricing structure across premium, standard, and economy levels separates Trek Sweden's dealer-backed warranty bundles from VanMoof's subscription-integrated smart-lock offerings. Cost compression in the 250W commuter segment intensifies because Klimatklivet subsidy exhaustion compresses effective consumer willingness-to-pay. Fleet procurement officers at municipal logistics departments exhibit lowest price sensitivity due to CSRD-mandated scope 3 reporting deadlines.
Supply Chain Analysis
EU Regulation 168/2013 type-approval requirements are reshaping sourcing patterns toward CE-certified component suppliers with established notified body relationships. Motor assembly concentrates in Germany and Japan; battery cell production draws from South Korea and China. Lithium carbonate, rare-earth magnets, and torque sensor assemblies constitute critical input dependencies. Single-source vulnerability runs through Bosch's mid-drive controller firmware, which lacks qualified second-source alternatives. Distribution runs through independent bicycle dealers in Stockholm County and direct-to-consumer platforms in Malmö metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's electric bike market reads as a late-cycle quality story where commuter specification preferences are shifting toward mid-drive torque precision and integrated smart-lock systems over basic hub-motor alternatives.
For Market Incumbents: Anticipate direct-to-consumer subscription models eroding dealer-network loyalty among under-35 apartment dwellers in Västra Götaland County. Defend positioning by deepening in-house technician certification for high-voltage system diagnostics, creating service-dependency lock-in that digital-native challengers cannot replicate. Secure captive battery supply agreements with South Korean cell producers before quarterly Klimatklivet disbursement cycles exhaust allocated subsidy pools. For New Entrants and Emerging Players: Direct-to-consumer channels offer the most penetrable route for bypassing established dealer markups in Uppsala's university-town demographics. Target Gothenburg archipelago ferry commuters with folding configurations addressing car-ferry intermodal gaps where protected cycling infrastructure remains undeveloped. White-space exists in cargo bike fleet procurement for grocery logistics operators facing compressed CSRD reporting timelines. For Investors and Strategic Acquirers: Roll-up economics work for domestic frame assemblers with in-house production capabilities because Jönköping County's manufacturing density supports operational consolidation without geographic dispersion penalties. Target vertically integrated mid-tier producers with Klimatklivet pre-qualification status and existing municipal fleet relationships. Watch Stockholm County congestion pricing extension to inner suburbs as the inflection trigger for cross-municipality commuter modal shift acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cargo Configuration Expansion | CSRD scope 3 mandates accelerate fleet procurement for last-mile logistics decarbonization. |
| Smart-Lock Subscription Bundling | Direct-to-consumer platforms capture recurring revenue streams that dealer networks cannot replicate. |
| Mid-Drive Motor Certification Investment | EU type-approval expertise filters out uncertified competitors from premium commuter segments. |
| Domestic Frame Production Scaling | Jönköping manufacturing anchors supply chain resilience against euro-yen motor volatility. |
| Folding Bike Portfolio Diversification | Apartment storage constraints in dense Nordic housing markets drive specification preference shifts. |
Research Methodology
Bottom-up commuter modeling reconciled against top-down battery shipment tracking forms the analytical core of this study. Primary interviews with independent bicycle dealer principals, municipal fleet procurement officers, and Swedish Environmental Protection Agency subsidy administrators combined with secondary validation against Swedish Transport Agency type-approval registries, EU import customs data, and Klimatklivet disbursement records. Triangulation across these sources ensures volume estimates align with actual subsidy claims and motor certification filings.
Input-output matrices map battery capacity deployments to frame assembly volumes across the projection horizon. Segmentation dimensions modeled include product type, battery chemistry, motor power rating, and distribution channel, with regional housing density gradients as an additional industry-specific dimension. CAGRs derive from fitted adoption curves calibrated to historical Klimatklivet utilization rates and Stockholm congestion pricing elasticity estimates. Forecast inputs incorporate lithium-ion energy density improvement trajectories and quarterly subsidy disbursement cycle impacts on municipal tender timing.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook by extending replacement intervals beyond current lithium-ion degradation curves. Forecasts reflect documented assumptions regarding Klimatklivet program continuity and EU type-approval cost structures. A small set of triggers—congestion pricing geographic expansion, mid-drive motor supply disruption, and BIS standard revision timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Italy E-Bike Market