
 Motorcycle Shock Absorbers Market | 2026-2036
Motorcycle Shock Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Shock Absorbers Market Foresight
Adventure touring and off-road motorcycling is expanding as a consumer vertical, pulling premium shock absorber demand upward from recreational users and enthusiast segments. Showa Corporation leverages its long-standing OEM relationships with major Japanese motorcycle manufacturers to sustain dominant supply positions across mass-market and performance tiers. Öhlins Racing specializes in high-adjustability mono-shock systems for racing and premium street applications, anchoring margin-rich positions at the top of the product pyramid. KYB Corporation competes through manufacturing scale and backward integration into precision hydraulic component production.
Motorcycle shock absorbers are hydraulic or gas-charged damping devices, typically featuring piston-cylinder assemblies with coil springs or pressurized nitrogen chambers, engineered to dissipate kinetic energy from road irregularities and maintain tire contact patch stability. Their primary commercial purpose spans rider safety, vehicle handling precision, and component longevity across diverse terrain and load conditions. Mono-shock configurations lead in performance and premium street motorcycles due to centralized mass distribution and tunability, while twin-shock systems occupy mature positions in cruiser and commuter segments where cost simplicity dominates procurement decisions. Aftermarket installation channels capture significant value as enthusiast riders pursue upgrade paths, though OEM supply contracts lock in volume predictability for aluminum and steel material suppliers.
EPA emissions standards in the United States and ECE R41 noise regulations in Europe constrain motorcycle design parameters, indirectly shaping shock absorber weight targets and material specifications as manufacturers pursue overall vehicle compliance. India's BIS certification requirements and China's GB standards for motorcycle components create parallel compliance pathways that influence supplier qualification and testing protocols across export-oriented production bases. Stakeholders must monitor regulatory divergence between established and emerging motorcycle markets to calibrate product platform strategies and certification investments.
Market Dynamics
Adventure touring and off-road motorcycling is compressing product development cycles as manufacturers race to deliver adjustable, terrain-responsive damping systems for recreational enthusiasts seeking premium ride quality.
Growth Catalysts
- EPA emissions standards:United States regulations on motorcycle weight and efficiency are pushing OEMs toward lighter aluminum shock absorber designs that reduce overall vehicle mass.
- Adventure touring segment expansion:Recreational riders across India, Thailand, and Vietnam are upgrading to performance mono-shock systems for long-distance terrain versatility.
- Gas-charged nitrogen technology:Pressurized damping chambers deliver superior heat dissipation and consistent performance across temperature extremes, penetrating premium street and racing applications.
Market Restraints
- Aluminum price volatility:Input cost swings for billet aluminum and precision-machined piston rods compress margin predictability for mid-tier suppliers.
- Supply concentration in East Asia:Hydraulic seal and precision valve manufacturing clusters in Japan and China create single-source vulnerability for Western assemblers.
- Thermal management limitations:Conventional oil-based damping fluids degrade under sustained high-frequency compression, capping performance in extreme off-road conditions.
Strategic Opportunities
- Brazilian aftermarket penetration:Underdeveloped dealer networks for premium suspension upgrades leave white space for direct-to-rider digital channels.
- India's PLI scheme:Production-linked incentives for advanced automotive components are attracting shock absorber manufacturing investment toward domestic OEM supply.
- Electronics-hydraulics convergence:Semi-active damping systems integrating real-time terrain sensors are opening new patentable product tiers above conventional adjustable units.
Industry Challenges
- Precision machining talent scarcity:CNC programming and micro-finishing expertise for piston-cylinder tolerances is concentrating at Japanese and German equipment suppliers.
- Homologation timeline compression:India's BIS certification and China's GB standard updates are running on parallel tracks, forcing dual testing protocols for export-oriented producers.
- Legacy twin-shock integration:Cruiser and commuter OEMs resist platform redesign costs, trapping suppliers in low-margin, high-volume contract structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Shock Absorbers Market |
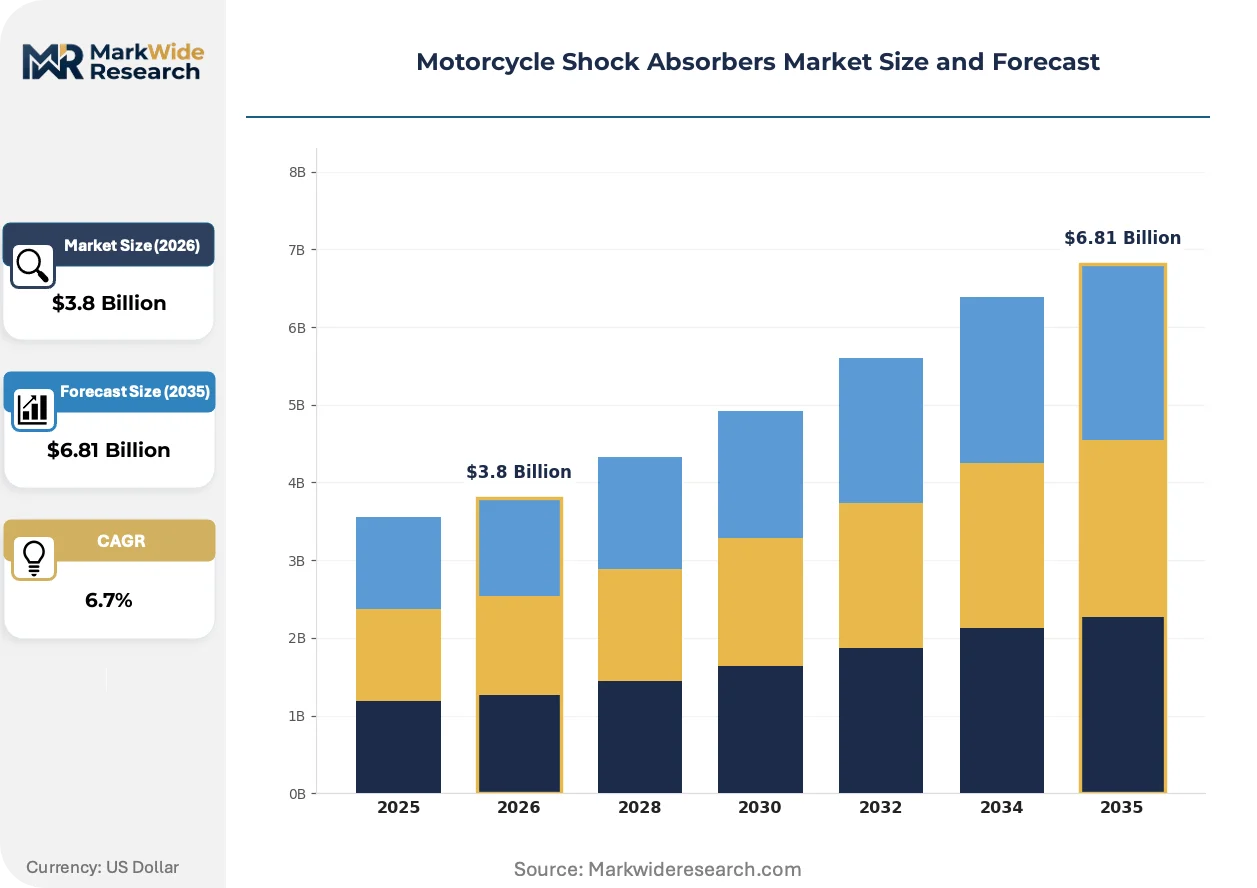
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono-shock, Twin-shock, Air-shock, Adjustable Material: Aluminum, Steel, Composite, Rubber Installation Type: Aftermarket, OEM, Direct Replacement, Custom End User: Motorcycle Enthusiasts, Commercial Riders, OEM Manufacturers, Recreational Users |
| Companies Covered | Showa Corporation, Öhlins Racing, Duroshox, KYB Corporation, WP Suspension, Endurance Technologies Limited, Mingzhen Industrial Holding Group, Chongqing Chuandong Shock Absorber Manufacturing, IKON Suspension, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Shock Absorbers Market Shifts & Advancements
Semi-active damping intelligence is rewriting competitive differentiation as real-time adjustability migrates from racing garages to street-legal production motorcycles.
Magnetorheological fluid technology is rewriting how suspension systems respond to terrain. These iron-particle suspensions alter viscosity within milliseconds under magnetic field modulation. Premium street motorcycle buyers in Germany and Italy are specifying factory-equipped semi-active systems at accelerating rates. The technology is rewriting price architecture across the product pyramid, compressing the gap between aftermarket racing upgrades and OEM-delivered performance.
Europe's ECE R41 noise regulations are tightening permissible sound emissions from motorcycle exhaust and mechanical systems. Component weight reduction has become a parallel compliance pathway as manufacturers shave kilograms to offset acoustic dampening material. Shock absorber specifications in France and Spain are shifting toward hollow piston rods and composite spring retainers to meet combined mass-noise targets.
Rider-direct digital channels are fragmenting traditional distribution for replacement and upgrade shocks. Enthusiast communities in Australia and Canada are sourcing adjustable mono-shock systems through manufacturer-direct portals, bypassing multi-step dealer markups. This pattern is most visible in off-road segments where technical self-selection reduces pre-purchase consultation needs.
Motorcycle Shock Absorbers Market Segmentation
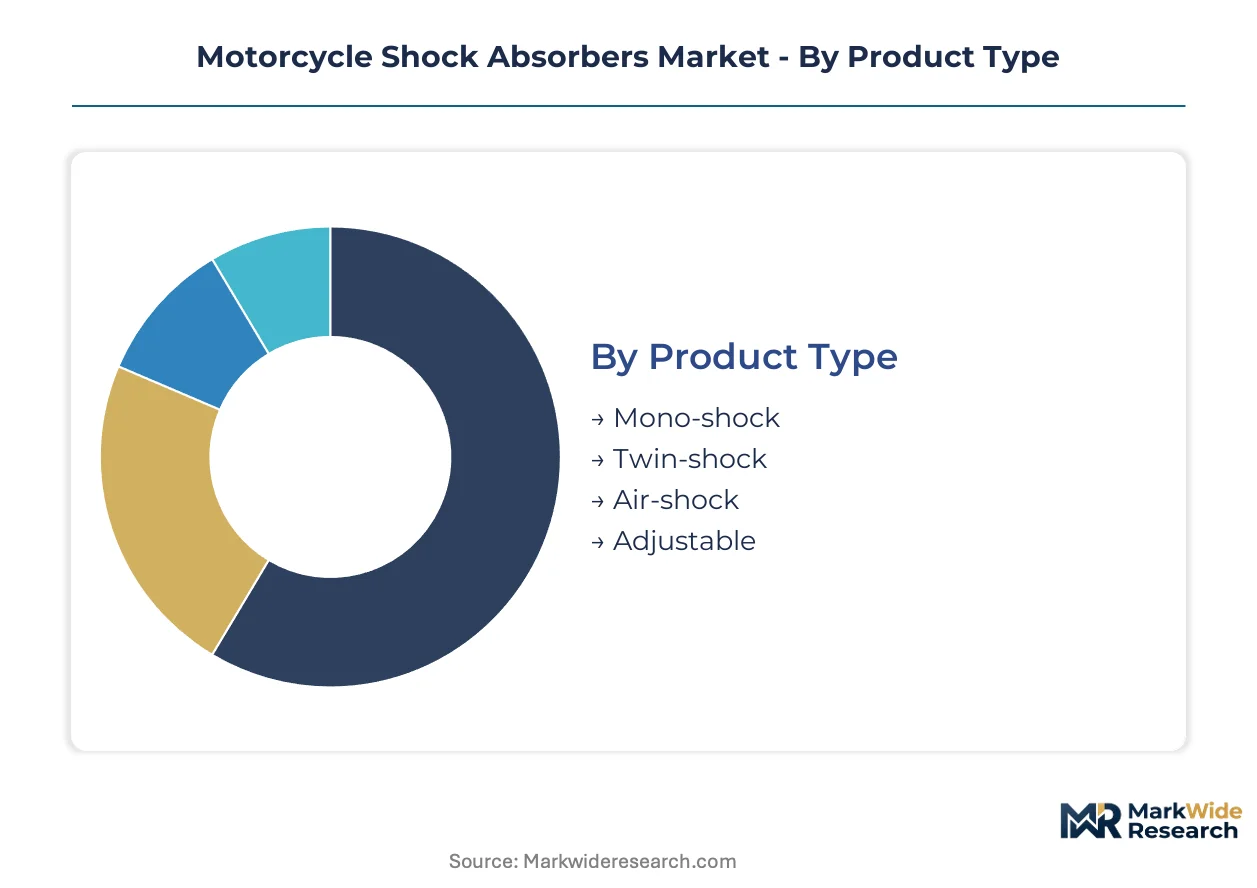
Segmentation in motorcycle shock absorbers reveals how capital allocation, manufacturing complexity, and rider specialization split demand across distinct technical tiers. Each dimension—product architecture, material specification, channel structure, and user profile—carries unique investment thresholds and margin profiles that reshape supplier positioning.
Product Type:
Capital intensity varies sharply across damping architectures, with precision machining requirements and adjustability features driving upfront tooling costs.
- Mono-shock:Centralized single-unit designs demand high-tolerance CNC machining for piston-cylinder assemblies and pressurized nitrogen charging infrastructure. Adventure touring motorcycles in India and Thailand specify these systems for terrain adaptability, pulling capacity expansion toward gas-charged production lines.
- Twin-shock:Dual-unit configurations rely on simpler coil-spring mechanics with lower per-unit tooling investment. Cruiser OEMs in the United States and commuter manufacturers in Vietnam prioritize cost predictability over damping sophistication, sustaining volume production of legacy architectures.
- Air-shock:Pneumatic damping chambers require specialized seal manufacturing and compressor integration, limiting supplier participation to firms with captive rubber processing.
- Adjustable:Multi-setting damping systems incorporate precision valve trains and external adjustment hardware, concentrating production at Japanese and German equipment clusters with micro-finishing expertise.
Most installed capacity flows through Twin-shock. Expansion is steepest in Mono-shock.
Material:
Raw material selection directly determines heat dissipation performance, weight compliance, and supply chain exposure to commodity volatility.
- Aluminum:Billet-machined housings and hollow piston rods dominate premium street applications where EPA emissions standards in the United States enforce mass reduction. Price volatility for aerospace-grade alloys compresses margin predictability for mid-tier suppliers without long-term purchase agreements.
- Steel:Chromoly spring retainers and piston rods anchor cost-optimized commuter segments across China and Brazil. Heat treatment and surface hardening requirements concentrate production at integrated mills with captive forging capacity.
- Composite:Carbon fiber reinforced polymer spring seats and external guards penetrate racing applications where gram-level weight reduction justifies material premiums.
- Rubber:Elastomer bushings, seals, and bump stops require specialized compounding for hydraulic fluid compatibility, with formulation expertise clustering at Japanese chemical suppliers.
Steel commands the largest production footprint. Aluminum is climbing the fastest on regulatory weight mandates.
Installation Type:
Channel structure shapes working capital requirements, with inventory risk and technical support obligations varying across supply chain tiers.
- Aftermarket:Direct-to-rider sales of upgrade kits demand SKU proliferation across motorcycle model years and regional specifications. Enthusiast communities in Australia and Canada source adjustable mono-shock systems through manufacturer portals, bypassing traditional dealer markups.
- OEM:Long-term supply contracts with Japanese and Indian motorcycle manufacturers lock in volume predictability but require dedicated assembly lines and just-in-sequence delivery infrastructure.
- Direct Replacement:Service-channel distribution for worn-component substitution concentrates at national parts distributors with broad model coverage.
- Custom:One-off fabrication for racing teams and specialty builders requires flexible manufacturing cells with rapid prototyping capability.
OEM absorbs the majority of production volume. Aftermarket is gaining share fastest on digital channel penetration.
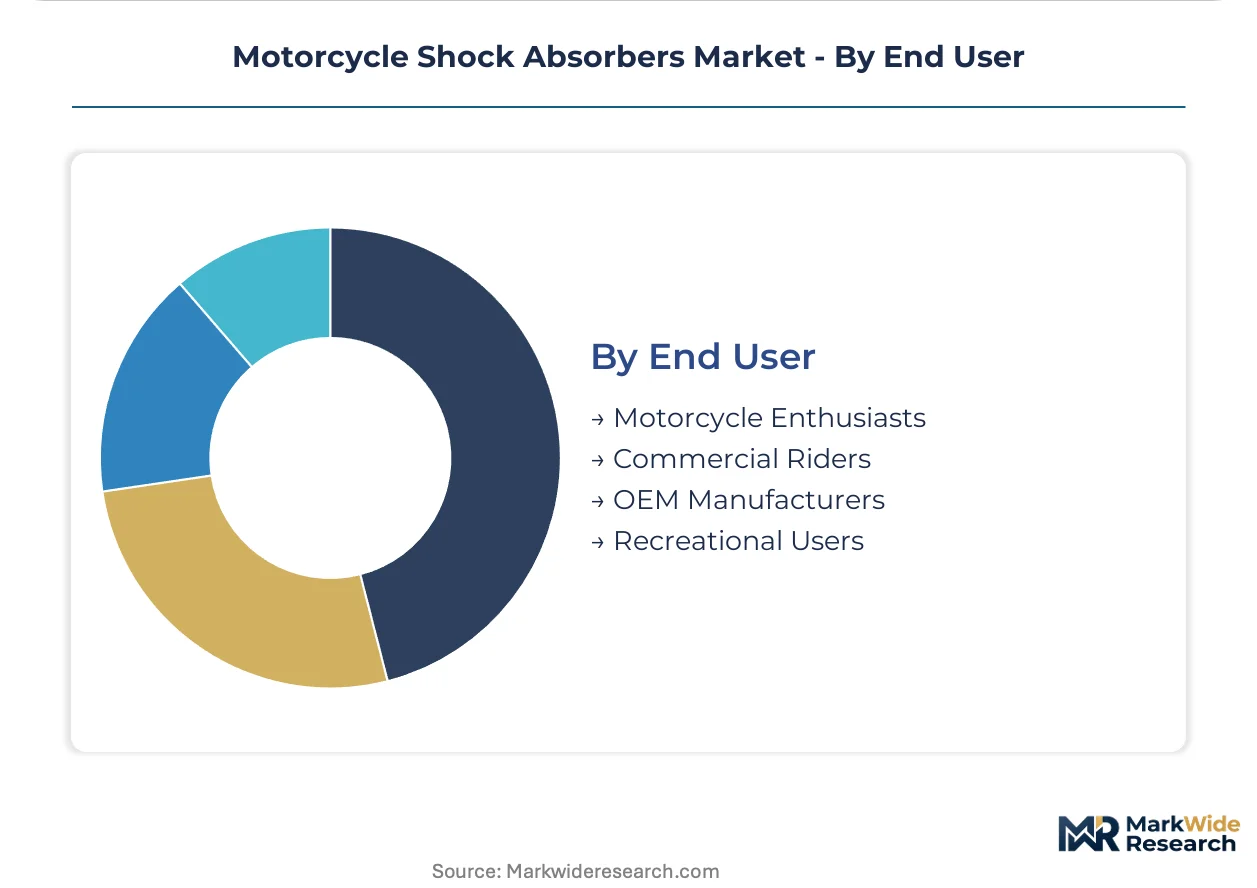
End User:
User sophistication and performance requirements fragment demand across technical self-selection and procurement authority boundaries.
- Motorcycle Enthusiasts:Technically proficient riders with upgrade intent drive premium mono-shock and adjustable system demand through direct channels. German and Italian buyers specify factory-equipped semi-active damping at accelerating rates.
- Commercial Riders:Fleet operators and delivery services in India and Southeast Asia prioritize total cost of ownership and component longevity over damping sophistication, sourcing through OEM service networks.
- OEM Manufacturers:Volume procurement by Honda, Yamaha, and Bajaj Auto anchors production scheduling for mass-market twin-shock and entry mono-shock configurations.
- Recreational Users:Weekend riders across Thailand and Vietnam purchasing adventure touring motorcycles pull mid-tier adjustable system demand upward from basic commuter specifications.
OEM Manufacturers concentrate the heaviest procurement volume. Motorcycle Enthusiasts show the steepest trajectory on upgrade cycle compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between established and emerging motorcycle markets is redirecting shock absorber production toward jurisdictions with streamlined certification pathways and concentrated supplier ecosystems. Cost-of-compliance gaps between EPA-mandated United States markets and BIS-regulated Indian production bases are accelerating capacity migration.
India
Adventure touring motorcycle sales in Maharashtra and Karnataka are pulling premium mono-shock demand from recreational riders upgrading from commuter platforms. India's PLI scheme for advanced automotive components is attracting shock absorber manufacturing investment toward domestic OEM supply chains. Chennai and Pune industrial corridors host expanding CNC machining clusters serving Honda and Bajaj Auto assembly lines.
China
Gas-charged nitrogen shock production is scaling in the Yangtze River Delta to meet export demand for premium street motorcycles. GB standards for motorcycle components and MIIT efficiency mandates are forcing weight reduction specifications that favor hollow aluminum piston rod designs. Chongqing's precision hydraulic component cluster supplies valve trains to Western assemblers facing single-source vulnerability.
Japan
Magnetorheological fluid technology development is concentrating in Kanto region R&D facilities serving factory-equipped semi-active damping specifications. METI industrial standards and JIS certification requirements maintain high technical barriers that protect incumbent supplier positions. Showa Corporation's long-standing OEM relationships with domestic motorcycle manufacturers sustain dominant supply positions across mass-market and performance tiers.
Germany
Aftermarket upgrade channels in Bavaria and Baden-Württemberg are fragmenting traditional distribution as enthusiast riders source adjustable mono-shock systems through manufacturer-direct portals. ECE R41 noise regulations and KBA homologation requirements are compressing product development timelines for export-oriented suppliers. Stuttgart precision machining clusters supply micro-finishing expertise for piston-cylinder tolerances that concentrate at German equipment suppliers.
Brazil
Underdeveloped dealer networks for premium suspension upgrades in São Paulo and Minas Gerais are creating white space for direct-to-rider digital channels targeting off-road segments. ANVISA regulatory frameworks for automotive components remain less stringent than EPA or ECE equivalents, attracting price-sensitive production sourcing. Local steel forging capacity anchors cost-optimized commuter shock production for regional motorcycle assemblers.
Motorcycle Shock Absorbers Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers race to install gas-charged nitrogen production lines and CNC machining infrastructure for adjustable mono-shock systems. The vendor base organizes around three strategic archetypes: integrated hydraulic specialists with captive seal manufacturing, precision machining houses with micro-finishing expertise, and aluminum-forging operations with heat-treatment capabilities. Geographic expansion and backward integration into precision valve production represent the dominant competitive moves as firms seek to reduce single-source vulnerability in East Asian supply clusters.
Within the integrated hydraulic specialist tier, Showa Corporation and KYB Corporation exemplify scale-driven positions anchored by long-term OEM supply relationships. Öhlins Racing occupies the premium-tier vector as a specialist in high-adjustability mono-shock systems for racing and premium street applications. Among China-based fabricators, Chongqing Chuandong Shock Absorber Manufacturing and Mingzhen Industrial Holding Group represent regional capacity expansion as domestic motorcycle consumption centers pull production investment inland.
| Leading Market Players |
|---|
| Showa Corporation |
| Öhlins Racing |
| Duroshox |
| KYB Corporation |
| WP Suspension |
| Endurance Technologies Limited |
| Mingzhen Industrial Holding Group |
| Chongqing Chuandong Shock Absorber Manufacturing |
| IKON Suspension |
| Others |
Supply & Pricing Matrix
Precision CNC programming talent clustering in Japan and Germany creates labor-cost differentials that widen pricing-tier spreads between mass-market twin-shock contracts and premium adjustable mono-shock systems. These regional skill concentrations allow Japanese suppliers to command margin premiums on micro-finished piston-cylinder assemblies while Brazilian and Indian fabricators compete on cost-optimized steel-spring configurations.
Pricing Analysis
Distributor markups compress as direct-to-rider digital channels fragment traditional aftermarket distribution in Australia and Canada. Three-tier pricing structure across premium, standard, and economy levels separates Öhlins Racing semi-active systems from KYB Corporation mass-market units and unbranded commuter replacements. Pricing pressure stems from aluminum billet volatility and EPA weight mandates forcing hollow piston rod redesigns. Commercial riders in India and Southeast Asia exhibit highest price sensitivity, while German and Italian enthusiasts absorb premiums for factory-equipped magnetorheological damping.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns as Honda and Bajaj Auto assembly lines pull precision machining capacity toward Chennai and Pune. Hydraulic seal manufacturing concentrates in Japan and China, with Chongqing's valve train cluster feeding Western assemblers. Raw material dependencies span aerospace-grade aluminum billet, chromoly steel forgings, and specialized rubber compounds from Japanese chemical suppliers. Single-source vulnerability in East Asian precision component clusters threatens supply continuity. Distribution runs through OEM just-in-sequence delivery networks and fragmented aftermarket dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's BIS certification cost advantage against EPA-mandated United States testing protocols attracts export-oriented production investment.
For Market Incumbents: To counter single-source vulnerability in Japanese hydraulic seal manufacturing, Showa Corporation and KYB Corporation should deepen backward integration into captive rubber compounding and expand CNC machining clusters in India's PLI-subsidized corridors. Certification investment in parallel BIS and GB standard compliance will compress homologation timelines against emerging Chinese competitors. For New Entrants and Emerging Players: Launch via direct-to-rider digital channels targeting Brazil's underdeveloped premium suspension dealer networks, where off-road enthusiast technical self-selection reduces pre-purchase consultation friction. White space concentrates in semi-active damping retrofit kits for adventure touring motorcycles and gas-charged nitrogen upgrade paths for commuter-to-touring conversions in Thailand and Vietnam. For Investors and Strategic Acquirers: Integrated automotive suppliers seeking motorcycle platform expansion represent the most active acquirer category in this space. Target precision machining houses with micro-finishing expertise and established OEM qualification status. Long-term viability hinges on electronics-hydraulics convergence patents and India-China production cost positioning. Monitor magnetorheological fluid technology penetration rates in factory-equipped premium street motorcycles as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Valve Production | Reduces single-source exposure to Chongqing valve train clusters for Western assemblers. |
| PLI-Aligned Manufacturing Footprint Expansion | Captures India's production-linked incentives for advanced automotive component supply to Honda and Bajaj Auto. |
| Semi-Active Damping Patent Portfolio Development | Secures defensible positions above conventional adjustable units as magnetorheological technology penetrates premium street segments. |
| Direct-to-Rider Digital Channel Launch | Bypasses multi-step dealer markups in fragmented aftermarket distribution across Australia and Canada. |
| Dual Certification Investment (BIS/GB) | Compresses homologation timelines for export-oriented producers serving India and China domestic markets simultaneously. |
Research Methodology
Coverage spans India, China, Japan, Germany, and Brazil, with primary inputs from each market combining structured interviews with OEM procurement managers, aftermarket distributor operations heads, precision machining facility directors, and regulatory compliance officers at BIS and KBA with secondary validation. Trade data from customs records, MIIT production disclosures, and EPA certification filings anchored supply-side quantification. Bottom-up production capacity tallies triangulated against top-down OEM assembly forecasts.
Rate-of-change decomposition across the analysis window modeled volume and value trajectories through product type segmentation by damping architecture, material specification by alloy grade and composite content, installation channel structure, and end-user sophistication tier. CAGRs derived from fitted growth curves incorporating regulatory phase-in schedules for EPA emissions standards and ECE R41 noise mandates, plus PLI scheme disbursement timelines affecting capacity migration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility spikes or abrupt BIS-GB regulatory divergence. Projections reflect documented assumptions regarding adventure touring segment expansion rates and semi-active damping technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market