
 United States Data Center Networking Market | 2026-2036
United States Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Networking Market Insights
Market Context
Modular switch chassis bundling with software-defined networking controllers is rebalancing procurement patterns across enterprise buyers. Cisco Systems leverages its vertically integrated silicon-to-software stack to sustain pricing power in high-density spine-leaf architectures. Arista Networks differentiates through cloud-optimized operating systems that dominate hyperscale deployment cycles. Juniper Networks anchors its position in service provider edge routing while competing for AI backend fabric contracts.
Technical Definition and Segments
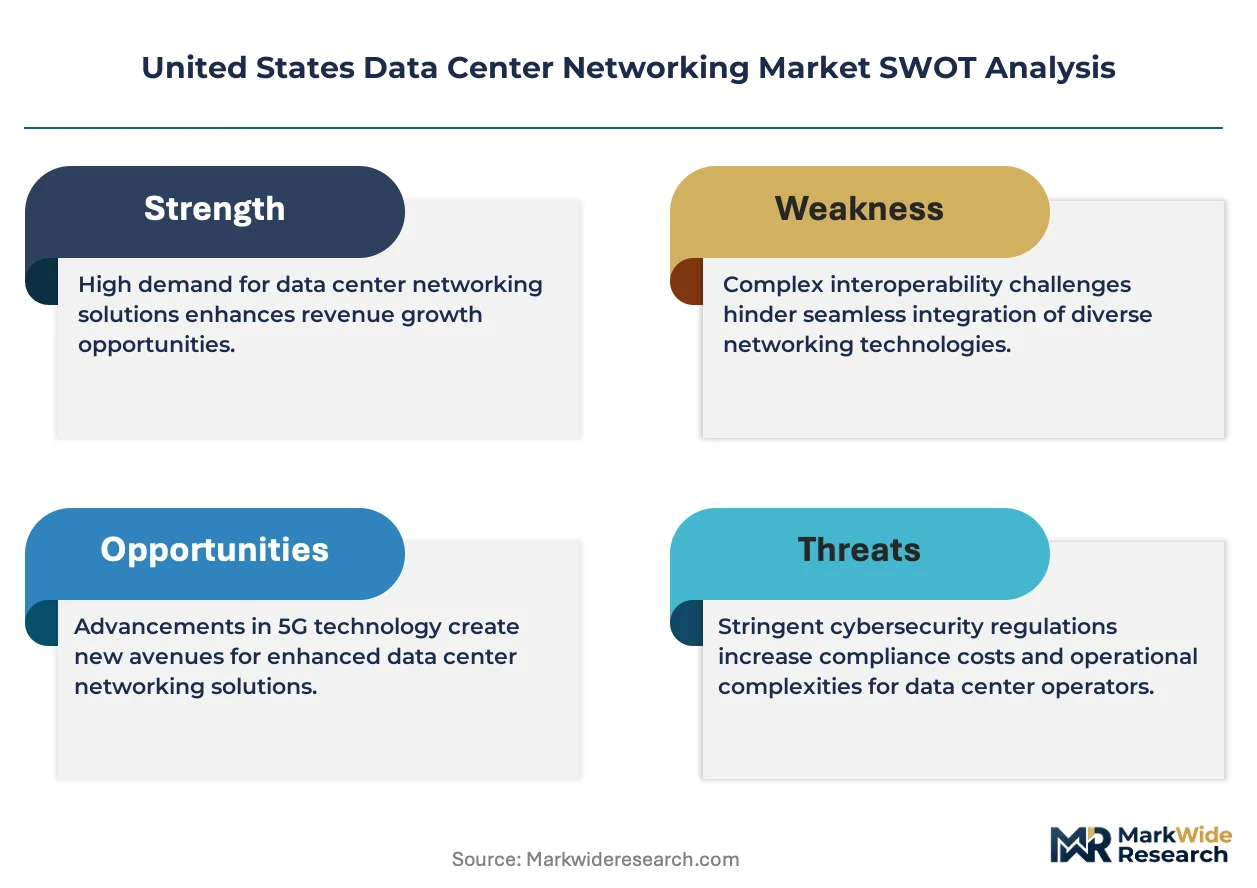
United States Data Center Networking encompasses the switching, routing, security, and interconnect hardware that moves traffic between servers, storage arrays, and external networks within purpose-built facilities, typically operating at speeds from 10 Gbps to 800 Gbps per port with latency budgets under one microsecond for AI workloads. Ethernet switches command the largest product type revenue pool as 400G and 800G port shipments accelerate, while InfiniBand adapters represent the fastest-growing technology segment driven by NVIDIA Corporation's GPU cluster interconnect standards. Hybrid deployment models capture expanding margin pools as enterprises blend colocation tenancy with on-premises control planes.
Regulatory Environment
NIST cybersecurity frameworks mandate zero-trust segmentation that shapes firewall and microsegmentation procurement specifications across federal and defense-adjacent facilities. FCC broadband equity programs subsidize fiber buildouts that expand data center interconnect reach into secondary markets, while EPA power plant emissions rules indirectly constrain facility expansion timelines in coal-dependent grid regions. Stakeholders must monitor state-level renewable energy mandates and utility interconnection queues as these now precede network equipment procurement decisions in capacity-constrained markets.
Market Dynamics
AI training clusters are forcing hyperscalers to rearchitect spine-leaf fabrics for 800G port densities, compressing hardware refresh cycles from five years to eighteen months in Northern Virginia and Dallas-Fort Worth corridors. Power interconnection queues now precede switch procurement decisions, reshaping vendor qualification timelines.
Growth Catalysts
- FCC Broadband Equity Access and Deployment Program:Federal fiber subsidies extend high-capacity interconnect reach into secondary U.S. markets, expanding addressable colocation demand for edge networking hardware.
- GPU cluster densification:NVIDIA's InfiniBand and Ethernet backend fabrics for AI training workloads are pulling 400G and 800G switch shipments into accelerated deployment windows.
- NIST zero-trust mandates:Federal and defense-adjacent facilities must segment east-west traffic, expanding addressable market for microsegmentation-capable switching platforms.
Market Restraints
- Power interconnection delays:Utility queue backlogs in Loudoun County and Prince William County extend facility commissioning timelines, deferring network equipment procurement by twelve to twenty-four months.
- Optical component concentration:Co-packaged optics and 800G DSP supply chains concentrate among Taiwanese and Korean foundries, exposing U.S. switch vendors to geopolitical supply risk.
- Copper thermal limitations:Passive direct attach copper cables face distance and power constraints above 400G, forcing premature fiber transitions that inflate rack-level cabling costs.
Strategic Opportunities
- Secondary market buildouts:Columbus, Ohio and Phoenix, Arizona offer available substation capacity and tax incentives, attracting hyperscale pre-commitments that precede networking infrastructure demand.
- SmartNIC-DPU convergence:Offload of networking, security, and storage virtualization onto data processing units creates attach-rate expansion for switch vendors bundling programmable silicon.
- IRA clean energy credits:Renewable-powered facility certifications unlock federal tax advantages, differentiating networking vendors with power-optimized switch silicon in RFP evaluations.
Industry Challenges
- Optical integration complexity:Co-packaged optics require new thermal management and repair workflows, straining field service organizations and extending mean-time-to-repair commitments.
- Legacy three-tier architecture entrenchment:Enterprise data centers with embedded Cisco Catalyst and Nexus deployments face forklift upgrade costs and operational retraining burdens to adopt spine-leaf designs.
- Certification timeline compression:NIST 800-53 and FedRAMP authorization windows for federal deployments now overlap with hardware refresh cycles, squeezing vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Networking Market |
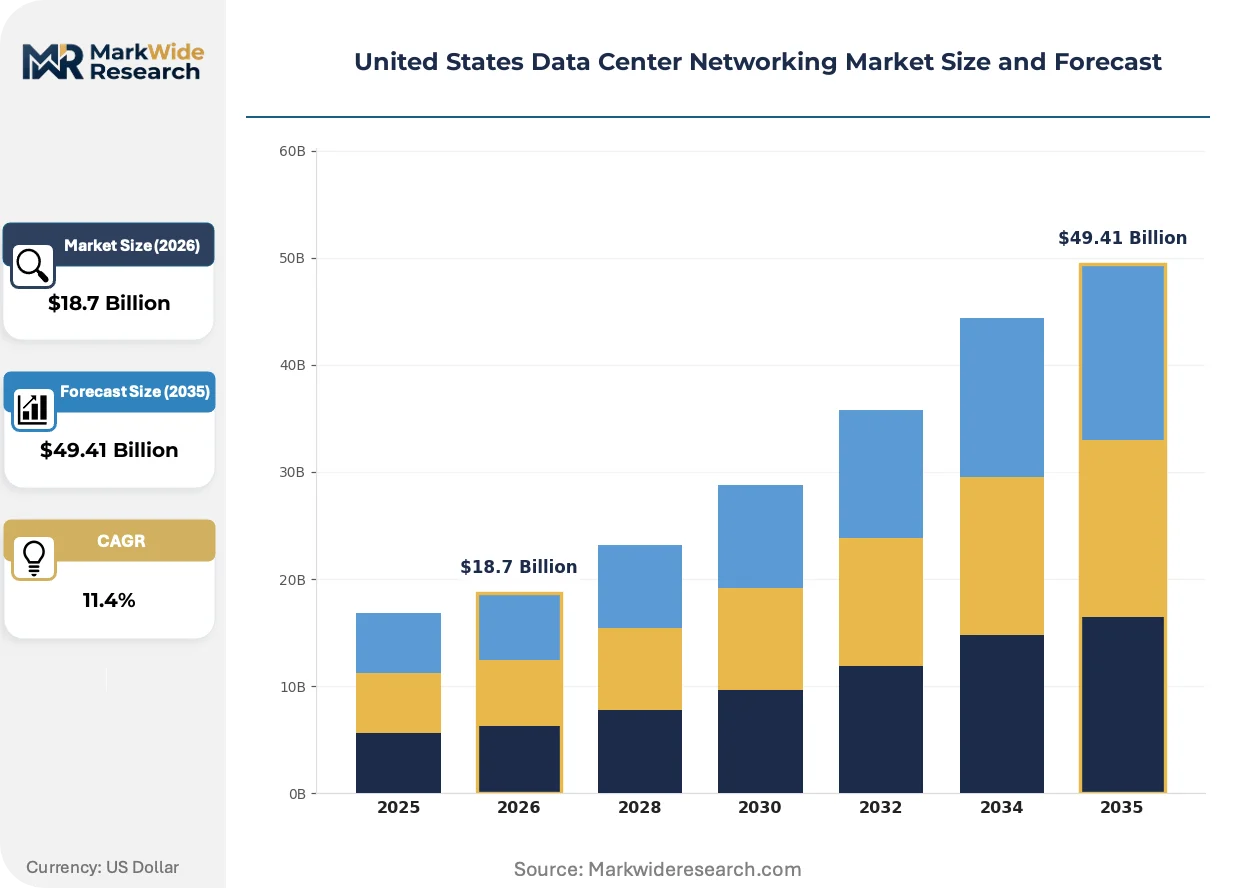
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Adapters Deployment Model: On-Premises, Hybrid, Private, Public End User: Enterprises, Service Providers, Government, Colocation Technology: Ethernet, Fibre Channel, InfiniBand, Others |
| Companies Covered | Cisco Systems, Inc., Arista Networks, Inc., Juniper Networks, Inc., Hewlett Packard Enterprise, Dell Technologies, Inc., NVIDIA Corporation, Extreme Networks, Inc., Broadcom Inc., Intel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Networking Market Trends and Innovations
Silicon photonics and co-packaged optics are collapsing power-per-bit metrics while AI workload scheduling software redefines how network capacity gets provisioned and monetized. Three converging forces are restructuring procurement and engineering priorities.
Co-packaged optics is overtaking pluggable transceivers in hyperscale spine switches. This integration reduces electrical SerDes power by eliminating retimers between switch ASIC and optical engine. Meta Platforms and Microsoft Azure are qualifying 51.2Tbps silicon with embedded optics for 2025 production ramps. The technology is overtaking traditional pluggable economics above 400G, compressing supply chains toward captive optical component strategies.
EPA power plant emissions rules are tightening carbon intensity standards for grid-connected facilities. Coal-dependent regions face effective moratoriums on new data center interconnect approvals until renewable offsets are secured. Northern Virginia operators are responding with behind-the-meter solar and battery storage co-located with switch fabric expansions, reshaping site selection criteria toward ISO 14001-certified hardware vendors.
Consumption-based network-as-a-service contracts are displacing capital-intensive chassis purchases among mid-market enterprises. Colocation providers now bundle white-box switching with cross-connect fees, transferring operational complexity to facility operators. This model is most visible in Dallas-Fort Worth and Atlanta markets where wholesale datacenter operators compete on bundled networking SLAs rather than pure space and power pricing.
United States Data Center Networking Market Segmentation
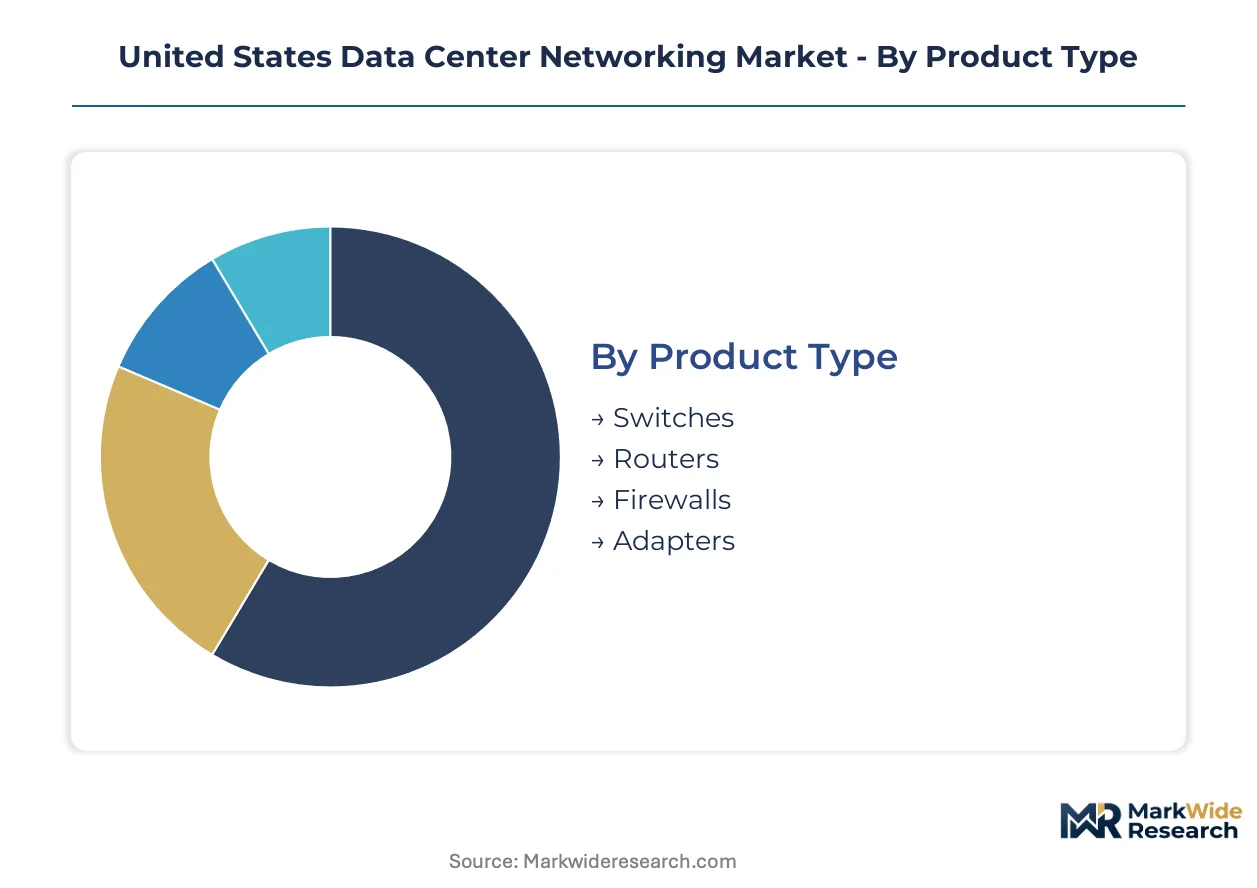
Segmentation in the United States Data Center Networking Market reveals how procurement patterns diverge across infrastructure layers, deployment philosophies, and workload requirements. Understanding these divides exposes where vendor pricing power concentrates and where commoditization pressures mount.
Product Type:
Supply concentration in merchant silicon and optical components concentrates margin capture among switch vendors with captive ASIC programs.
- Switches:Ethernet switching platforms operating at 400G and 800G port densities form the backbone of spine-leaf fabrics. Northern Virginia's Data Center Alley consumes the highest port volumes, though power allocation constraints now stretch procurement timelines by twelve to twenty-four months.
- Routers:Service provider edge and core routing systems handle inter-facility traffic and internet exchange connectivity. Dallas-Fort Worth corridor demand concentrates among hyperscalers building distributed AI training campuses, driven by available substation capacity.
- Firewalls:NIST zero-trust mandates are expanding procurement specifications for microsegmentation-capable platforms.
- Adapters:SmartNIC and DPU offload engines are gaining attach rates in GPU-dense clusters.
Switches absorb the bulk of installed capacity; adapters are expanding most quickly.
Deployment Model:
Cost tier differentiation separates capital-intensive ownership from operational expenditure models, with hybrid architectures capturing mid-market margin pools.
- On-Premises:Enterprise-controlled switching and routing infrastructure requiring full lifecycle management. Financial services and defense-adjacent verticals in Northern Virginia maintain this model to satisfy FedRAMP authorization requirements.
- Hybrid:Blended colocation tenancy with retained control plane ownership. Columbus and Phoenix markets attract these deployments through available power and state tax incentives.
- Private:Single-tenant facilities with dedicated network fabrics. Healthcare systems favor this model for HIPAA compliance.
- Public:Cloud-provider managed infrastructure with no customer visibility into underlying switching. Consumption-based pricing dominates.
On-premises retains the largest installed base; hybrid deployments are climbing the fastest.
End User:
Customer type determines procurement authority, with service providers and hyperscalers exercising volume leverage unavailable to enterprise buyers.
- Enterprises:Mid-market and large corporations operating owned or leased facility space. Legacy three-tier Cisco architectures create forklift upgrade friction for spine-leaf transitions.
- Service Providers:Telecommunications carriers and network-as-a-service operators. These buyers qualify white-box switching for cost optimization at scale.
- Government:Federal agencies and defense facilities. NIST 800-53 and FedRAMP timelines compress vendor engineering resources.
- Colocation:Wholesale and retail datacenter operators bundling networking with space and power. Dallas-Fort Worth and Atlanta operators compete on bundled SLAs.
Service providers command the highest port volumes; government is gaining share fastest on zero-trust mandates.
Technology:
Maturity curves separate established Ethernet dominance from emerging backend fabric alternatives for AI workloads.
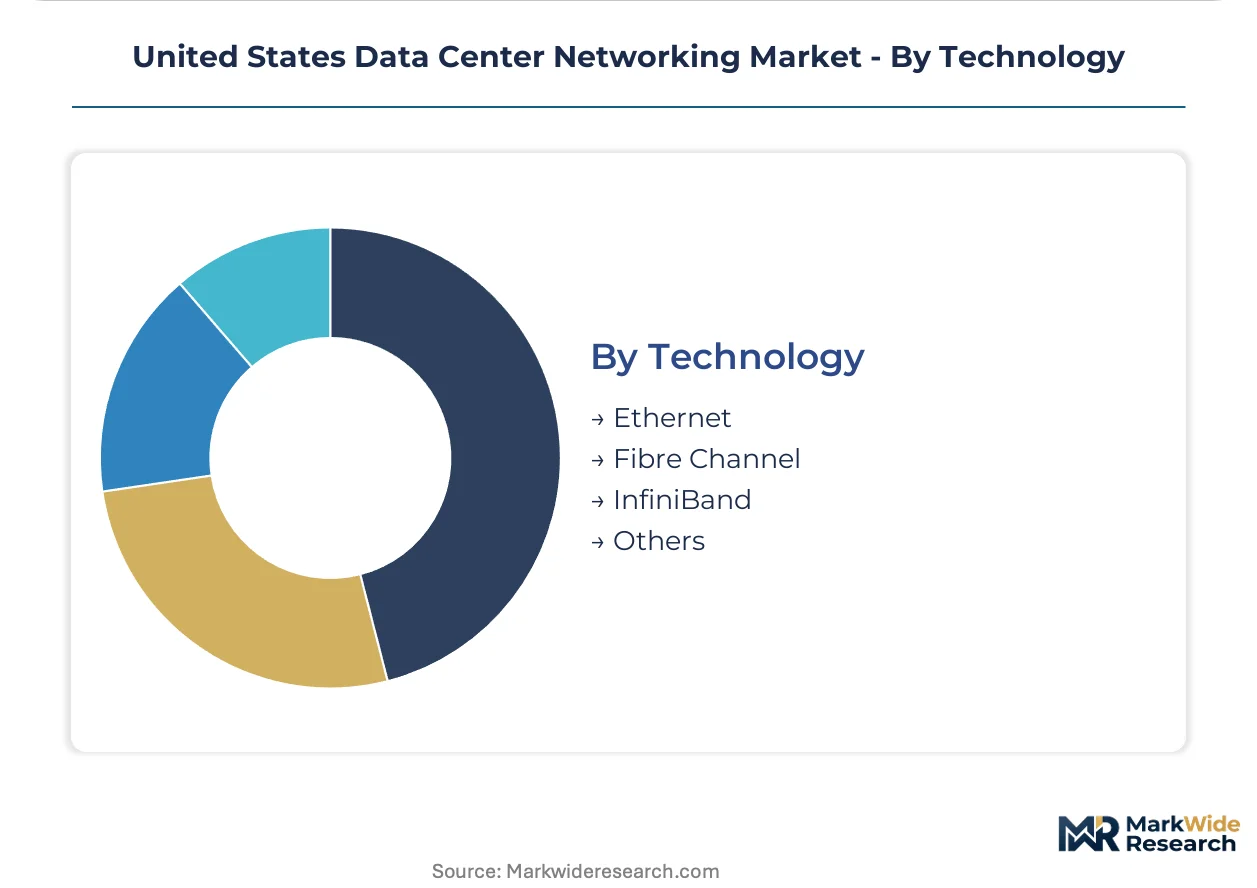
- Ethernet:IEEE-standardized switching and routing protocols commanding the largest product revenue pool. 400G shipments accelerate while 800G ramps in hyperscale qualification cycles.
- Fibre Channel:Storage-area networking protocols for enterprise storage connectivity. Financial services in legacy data centers sustain demand.
- InfiniBand:Low-latency interconnect for GPU cluster backend fabrics. NVIDIA's GPU cluster standards are pulling accelerated deployment windows.
- Others:Proprietary and emerging interconnect technologies including CXL and optical circuit switching.
Ethernet holds the dominant installed position; InfiniBand shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of switch silicon and optical components concentrates in East Asian foundries, while consumption clusters in U.S. metropolitan corridors where hyperscalers deploy AI training infrastructure. Virginia's Data Center Alley absorbs the highest port volumes nationally.
Northern Virginia
Loudoun and Prince William Counties host the densest concentration of colocation facilities in the United States. FCC broadband equity programs subsidize fiber interconnect buildouts that extend reach into secondary markets. Dominion Energy's interconnection queues now stretch twenty-four months, forcing operators to pre-procure networking hardware before substation capacity materializes.
Dallas-Fort Worth
Available ERCOT grid capacity and competitive electricity rates attract hyperscale campus developments. Texas state tax abatements for data center construction accelerate facility commissioning timelines. Richardson and Irving sub-markets see accelerated 800G spine switch deployments as Microsoft and Meta expand AI training footprints.
Phoenix, Arizona
APS and SRP utility zones offer expedited interconnection timelines absent in coastal markets. Arizona's renewable energy mandates align with IRA clean energy credit structures. Mesa and Chandler sub-markets attract enterprise hybrid deployments seeking to escape Northern Virginia power constraints.
Columbus, Ohio
American Electric Power maintains available substation capacity that supports rapid facility scaling. Ohio state data center tax incentives reduce effective property tax burdens for network equipment-heavy deployments. New Albany and Dublin clusters host Intel and Amazon Web Services campuses driving 400G and 800G switch demand.
Silicon Valley
Legacy enterprise data centers sustain refresh demand for microsegmentation-capable platforms under NIST zero-trust mandates. California's SB 100 renewable portfolio standards constrain coal-dependent power sourcing. Santa Clara and San Jose facilities prioritize power-optimized switch silicon to meet emissions disclosure requirements.
United States Data Center Networking Market Competitive Landscape
The competitive structure tilts toward vertically integrated silicon-to-software stacks. Cisco Systems and Arista Networks command premium positioning in high-density spine-leaf architectures through captive ASIC programs and cloud-optimized operating systems. Three archetypes define the field: merchant silicon switch vendors, vertically integrated networking-stack providers, and GPU-interconnect specialists. Consolidation pressures intensify as hyperscaler qualification cycles compress and optical component supply chains concentrate among Taiwanese and Korean foundries.
Among vertically integrated networking-stack providers, Cisco Systems, Inc. occupies a position exemplifying silicon-to-software control, while Arista Networks, Inc. represents the cloud-native operating system archetype. Juniper Networks, Inc. anchors the service provider edge routing segment. NVIDIA Corporation sits within the GPU-interconnect specialist tier, pulling InfiniBand and Ethernet backend fabric standards through its GPU cluster dominance.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Arista Networks, Inc. |
| Juniper Networks, Inc. |
| Hewlett Packard Enterprise |
| Dell Technologies, Inc. |
| NVIDIA Corporation |
| Extreme Networks, Inc. |
| Broadcom Inc. |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
Optical engineering talent concentration in Taiwan's Hsinchu Science Park and South Korea's Pangyo Techno Valley feeds labor-cost differentials into three-tier pricing spreads across merchant silicon, captive ASIC, and co-packaged optics switch tiers. Power-optimized silicon certifications from ISO 14001-compliant vendors command premium positioning in Northern Virginia RFPs where renewable energy mandates shape procurement scoring.
Pricing Analysis
Margin tightening in white-box switching tiers traces to hyperscaler direct sourcing of merchant silicon from Broadcom and Marvell. Three-tier pricing structure across premium, standard, and economy levels separates Cisco's vertically integrated stack from Arista's cloud-optimized platforms and commodity white-box alternatives. Price differentiation hinges on captive ASIC programs and FedRAMP authorization status. Cost-down pressure on mid-market chassis accelerates because colocation providers bundle cross-connect fees into consumption-based contracts. Service providers exercise highest price sensitivity through volume leverage; defense-adjacent facilities show lowest sensitivity given zero-trust mandate compliance requirements.
Supply Chain Analysis
Co-packaged optics and 800G DSP silicon rest on Taiwanese foundry capacity at TSMC and Korean memory packaging at SK Hynix. Switch ASIC production draws from Taiwan, South Korea, and domestic Intel facilities. Raw material dependencies span silicon wafers, indium phosphide for optical engines, and advanced organic substrates. Single-source vulnerability concentrates in Taiwanese co-packaged optics capacity where geopolitical exposure interrupts spine switch qualification timelines. Distribution runs through direct hyperscale procurement teams, OEM channel partners, and colocation operator bundled contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Data Center Networking Market sits in an 800G spine-leaf transition phase as co-packaged optics displace legacy pluggable transceiver architectures. AI training cluster densification is compressing hardware refresh cycles and reshaping vendor qualification priorities.
For Market Incumbents: Anticipate merchant silicon commoditization by deepening captive optical component strategies through backward integration into Taiwanese packaging partnerships. Defend pricing power in federal segments by accelerating NIST 800-53 certification pipelines ahead of compressed authorization windows. Prioritize power-optimized silicon R&D to capture IRA clean energy credit differentiation in Arizona and Ohio RFPs.
For New Entrants and Emerging Players: FCC broadband equity programs in secondary U.S. markets open a window for edge networking hardware plays outside Northern Virginia's power-constrained corridor. Target Columbus and Phoenix colocation buildouts where available substation capacity precedes switch procurement decisions. Pursue white-box switching qualification with wholesale datacenter operators competing on bundled networking SLAs in Dallas-Fort Worth.
For Investors and Strategic Acquirers: Re-rating potential sits with DPU-SmartNIC convergence specialists given NVIDIA's GPU cluster interconnect standards pulling attach-rate expansion. Long-term viability frames around programmable silicon offload engines across the five-to-ten-year AI infrastructure buildout. Monitor hyperscaler 800G spine switch qualification announcements as inflection indicators for co-packaged optics adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Reduces electrical SerDes power by eliminating retimers between switch ASIC and optical engine at Meta and Microsoft. |
| FedRAMP Acceleration Program | Compresses vendor engineering resources to meet overlapping NIST 800-53 authorization and hardware refresh cycles. |
| Secondary Market Facility Buildout | Captures Columbus and Phoenix tax incentives where available substation capacity precedes networking demand. |
| DPU-SmartNIC Convergence | Creates attach-rate expansion for switch vendors bundling programmable silicon in GPU-dense clusters. |
| Renewable Energy Certification | Unlocks IRA clean energy credit differentiation for ISO 14001-certified hardware vendors in Arizona RFPs. |
Research Methodology
Document review covered SEC 10-K filings from Arista Networks and Juniper Networks, hyperscaler capex disclosures from Microsoft and Meta, and FCC broadband equity program allocations, complemented by interviews with datacenter facility operators, network equipment procurement officers, cloud platform engineers, and utility interconnection planners. Secondary validation drew from Dominion Energy interconnection queue data, EIA power plant emissions reports, and NIST cybersecurity framework updates. Bottom-up port shipment estimates triangulated against top-down hyperscaler infrastructure spending projections.
Cross-referencing historical refresh cycle patterns against expert panel input on AI workload scheduling priorities shaped the analytical framework across the modeling period. Segmentation dimensions modeled include product type, deployment model, end user archetype, and technology protocol. CAGRs were derived from volume-weighted average growth trajectories. Industry-specific forecast inputs encompassed GPU cluster densification rates and utility interconnection queue backlogs in Loudoun County.
The model assumes a particular technology adoption path; alternative pathways for co-packaged optics penetration would alter the outlook if pluggable transceiver economics improve through DSP efficiency gains. Forecasts reflect assumptions about hyperscaler qualification timelines and federal zero-trust mandate implementation pacing. Supply chain disruption in Taiwanese foundries, shifts in EPA power plant emissions enforcement, and state-level renewable energy mandate acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Cache Server Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Netherlands Data Center Networking Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Europe Data Center Market