
 Italy Data Center Networking Market | 2026-2036
Italy Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Networking Market Insights
Italian fiber infrastructure deployment is realigning data center interconnection patterns across the peninsula. Cisco Systems Inc. dominates core switching architectures through deep relationships with domestic carriers. Juniper Networks Inc. competes in edge routing with specialized platforms for financial services latency requirements. Arista Networks Inc. positions in hyperscale cloud interconnects with high-density 400G fabric solutions.
Data center networking encompasses the switching, routing, and interconnect hardware that enables compute and storage resource communication within and between facilities, typically operating at speeds from 10G to 800G Ethernet with sub-microsecond latency requirements. Its primary purpose is to maintain deterministic traffic flow across virtualized workloads while minimizing packet loss during peak utilization. Ethernet switching leads product type revenue due to universal compatibility with existing server infrastructure, while InfiniBand technology captures the fastest growth trajectory as Italian research institutions and AI training clusters adopt lossless fabrics for GPU-intensive workloads. SDN deployment models are gaining structural importance as enterprises seek programmable traffic engineering across hybrid cloud topologies.
Italy's national cybersecurity agency (ACN) enforces NIS2 transposition requirements that mandate encrypted east-west traffic segmentation for critical infrastructure operators. BIS technical standards and EU CE marking directives govern electromagnetic compatibility and safety certification for networking equipment sold into Italian facilities. Stakeholders must monitor how forthcoming EU AI Act infrastructure rules reshape compliance spending on network observability and audit logging capabilities.
Market Dynamics
The EU AI Act's infrastructure mandates are compressing upgrade cycles for Italian data center operators, forcing simultaneous investments in encrypted segmentation, observability platforms, and high-throughput fabrics to maintain compliance certification.
Growth Catalysts
- Hyperscale cloud interconnects:Milan's carrier-neutral facilities attract submarine cable landings, creating density that pulls enterprise colocation demand from across the peninsula.
- NIS2 transposition:Italy's national cybersecurity agency mandates encrypted east-west traffic segmentation for critical infrastructure operators, mandating network refresh spending.
- GPU-intensive AI clusters:Research institutions adopt lossless InfiniBand fabrics for training workloads, displacing traditional Ethernet in high-performance computing environments.
Market Restraints
- Optical component concentration:Supply of 400G/800G transceivers concentrates among East Asian contract manufacturers, exposing Italian integrators to lead-time volatility.
- Copper and rare earth input costs:Ethernet cable assemblies and magnetics face raw material price swings that compress hardware margins for domestic distributors.
- Legacy protocol fragmentation:Brownfield facilities running mixed 10G/25G/100G infrastructure resist full-fabric upgrades due to interoperability testing burdens.
Strategic Opportunities
- Southern Italy latency arbitrage:Underdeveloped data center capacity in Sicily and Apulia offers greenfield sites for edge caching nodes serving North African connectivity.
- SD-WAN convergence with SASE:Managed service providers bundle software-defined networking with zero-trust security stacks, capturing mid-market enterprise accounts.
- EU Green Deal power efficiency mandates:Regulations rewarding PUE improvements incentivize adoption of liquid-cooled switching fabrics and intelligent power management.
Industry Challenges
- Certified network engineering scarcity:Domestic labor pools lack sufficient Cisco CCIE and Juniper JNCIE credential holders to execute complex fabric migrations at scale.
- Multi-vendor integration complexity:Heterogeneous environments mixing Arista leaf-spine architectures with legacy Cisco core switches require specialized automation tooling.
- ACN audit timeline compression:Critical infrastructure operators face shortened compliance verification windows that strain documentation and logging infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Networking Market |
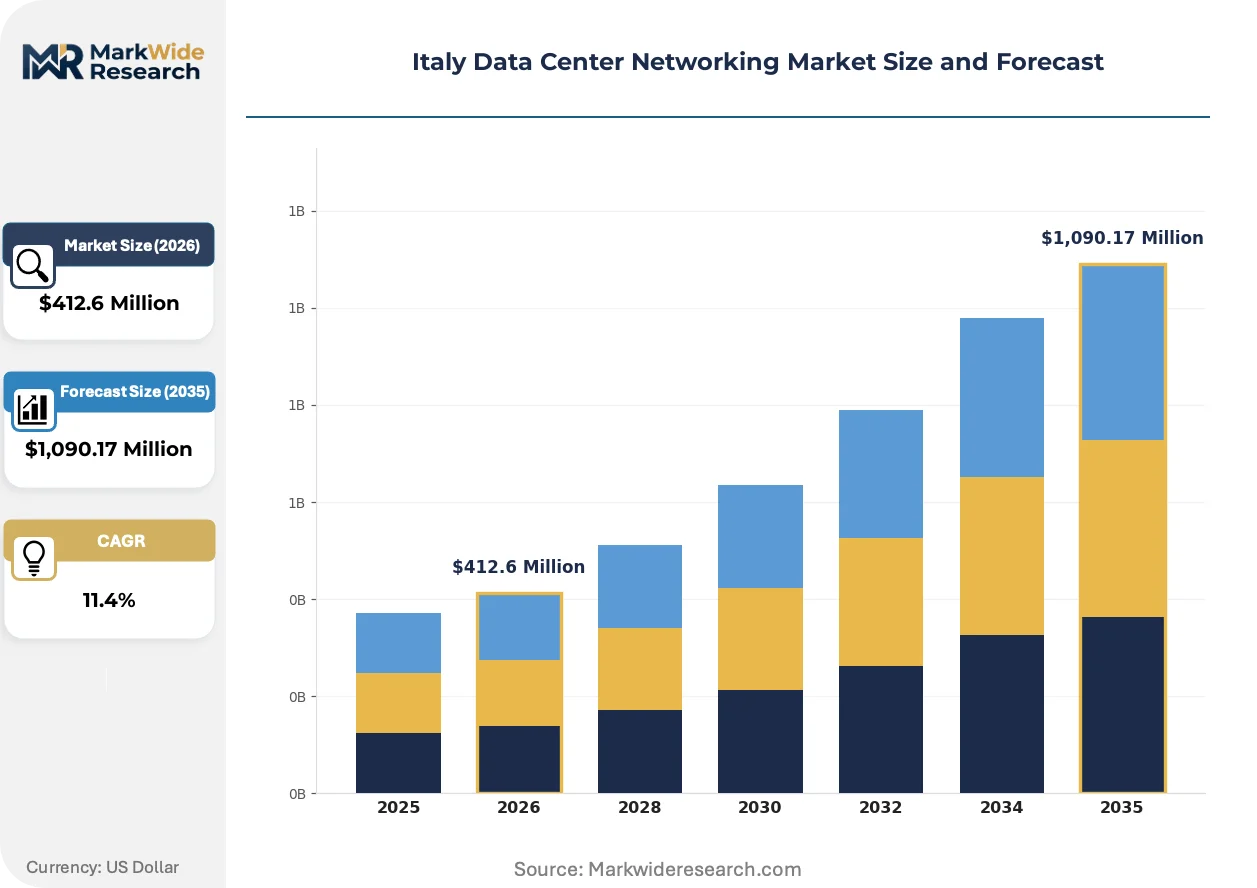
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Interface Cards, Load Balancers Technology: Ethernet, Fibre Channel, InfiniBand, SDN Deployment Model: On-Premises, Cloud-Based, Hybrid, Colocation End User: Telecommunications, IT & Managed Services, Government, BFSI |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Arista Networks Inc., Hewlett Packard Enterprise Company, Dell Technologies Inc., NEC Corporation, International Business Machines Corporation, Schneider Electric SE, ALE International SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Networking Market Trends and Innovations
Intent-based networking systems are automating configuration management across Italian hyperscale deployments, reducing manual provisioning errors while compressing time-to-production for new compute racks.
Software-defined networking controllers are automating traffic engineering across hybrid cloud topologies, enabling Milan-based financial services firms to enforce microsecond-latency policies across multi-site workloads. Large enterprises deploy these platforms to programmatically route traffic between on-premise VMware clusters and AWS Direct Connect circuits. The shift is collapsing traditional network operations team structures into platform engineering functions.
Italy's transposition of NIS2 through ACN enforcement is mandating continuous monitoring and encrypted segmentation for energy and transport sector networks. Operators must deploy east-west traffic inspection and automated threat response by designated compliance deadlines. Critical infrastructure segments are responding by consolidating vendor relationships to reduce certification surface area.
Consumption-based procurement models are displacing capital-intensive hardware purchases among mid-market Italian enterprises, with colocation providers offering network-as-a-service bundles. Channel partners pivot from box-moving to recurring revenue managed services. This pattern concentrates in Turin's automotive supplier ecosystem, where Tier-1 manufacturers prefer operational expenditure treatment for networking infrastructure.
Italy Data Center Networking Market Segmentation
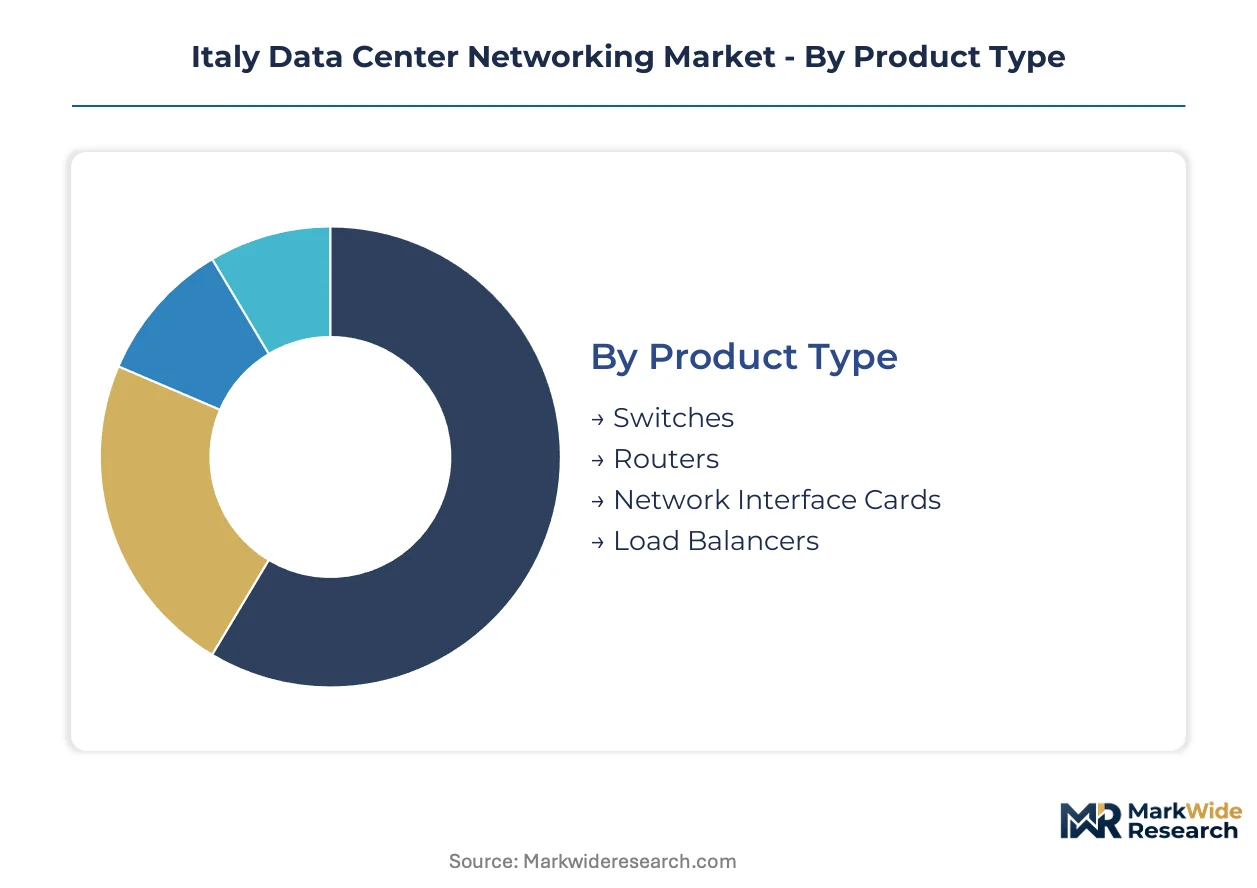
Segmentation in Italy's data center networking market reveals how regulatory pressure from ACN and the EU AI Act differentially impacts procurement patterns across hardware categories, deployment architectures, and customer verticals. Understanding these divides clarifies where compliance spending concentrates and which segments face compressed upgrade cycles.
Product Type:
Ethernet switches and core routers face distinct ACN certification pathways under NIS2 transposition, with encrypted segmentation mandates applying differentially based on port density and east-west traffic handling capabilities.
- Switches:Layer 2/3 switching platforms process intra-rack and spine-leaf traffic at 10G to 800G speeds. Milan's carrier-neutral facilities drive demand for high-density 400G leaf switches as submarine cable landings pull enterprise colocation from across the peninsula.
- Routers:Core and edge routing hardware manages inter-facility and WAN connectivity with microsecond-latency requirements. Financial services firms in Lombardy deploy specialized edge routers to meet latency thresholds for algorithmic trading infrastructure.
- Network Interface Cards:Server-embedded NICs enable host-level network offload and RDMA acceleration. Research institutions prioritize 100G/200G SmartNICs for GPU-intensive AI training clusters.
- Load Balancers:Application delivery controllers distribute traffic across virtualized compute pools. Mid-market enterprises adopt virtualized load balancing instances to avoid hardware refresh cycles.
Leading the category by volume: Switches. Growing fastest: Routers facing NIS2-mandated encryption upgrades.
Technology:
Technology selection in Italian facilities tracks workload intensity, with lossless fabrics commanding premium positioning in research environments while Ethernet retains universal compatibility advantages.
- Ethernet:Dominant interconnect protocol supporting 10G through 800G speeds with universal server compatibility. Brownfield facilities across Turin's automotive supplier ecosystem resist full-fabric upgrades due to mixed 10G/25G/100G interoperability testing burdens.
- InfiniBand:Lossless fabric technology enabling GPU-to-GPU communication at sub-microsecond latency. Italian research institutions and AI training clusters adopt InfiniBand to displace traditional Ethernet in high-performance computing environments.
- Fibre Channel:Storage-area networking protocol for block-level data transport. Legacy SAN environments in government data centers maintain FC investments for mission-critical database workloads.
- SDN:Software-defined networking controllers enable programmable traffic engineering across hybrid cloud topologies. Milan-based financial services firms deploy SDN to enforce microsecond-latency policies across multi-site workloads.
Dominant by installed base: Ethernet. Expanding most quickly: InfiniBand for AI cluster builds.
Deployment Model:
Deployment architecture determines capital treatment and compliance responsibility, with colocation providers increasingly absorbing network infrastructure ownership to capture recurring revenue streams.
- On-Premises:Enterprise-owned facilities with full hardware lifecycle control. Critical infrastructure operators in energy and transport sectors face ACN audit timeline compression that strains documentation capabilities.
- Colocation:Carrier-neutral facilities offering interconnection density and cross-connect services. Milan's submarine cable landings concentrate enterprise demand from across the peninsula into Lombardy facilities.
- Cloud-Based:Fully managed network infrastructure consumed as operational expenditure. Turin's Tier-1 automotive suppliers prefer cloud-based procurement to treat networking as operational spend.
- Hybrid:Split workloads across on-premise and cloud infrastructure with unified policy enforcement. Large enterprises deploy hybrid models to programmatically route traffic between VMware clusters and AWS Direct Connect circuits.
Fastest-growing deployment: Colocation in Milan metro. Largest existing footprint: On-premises legacy facilities.
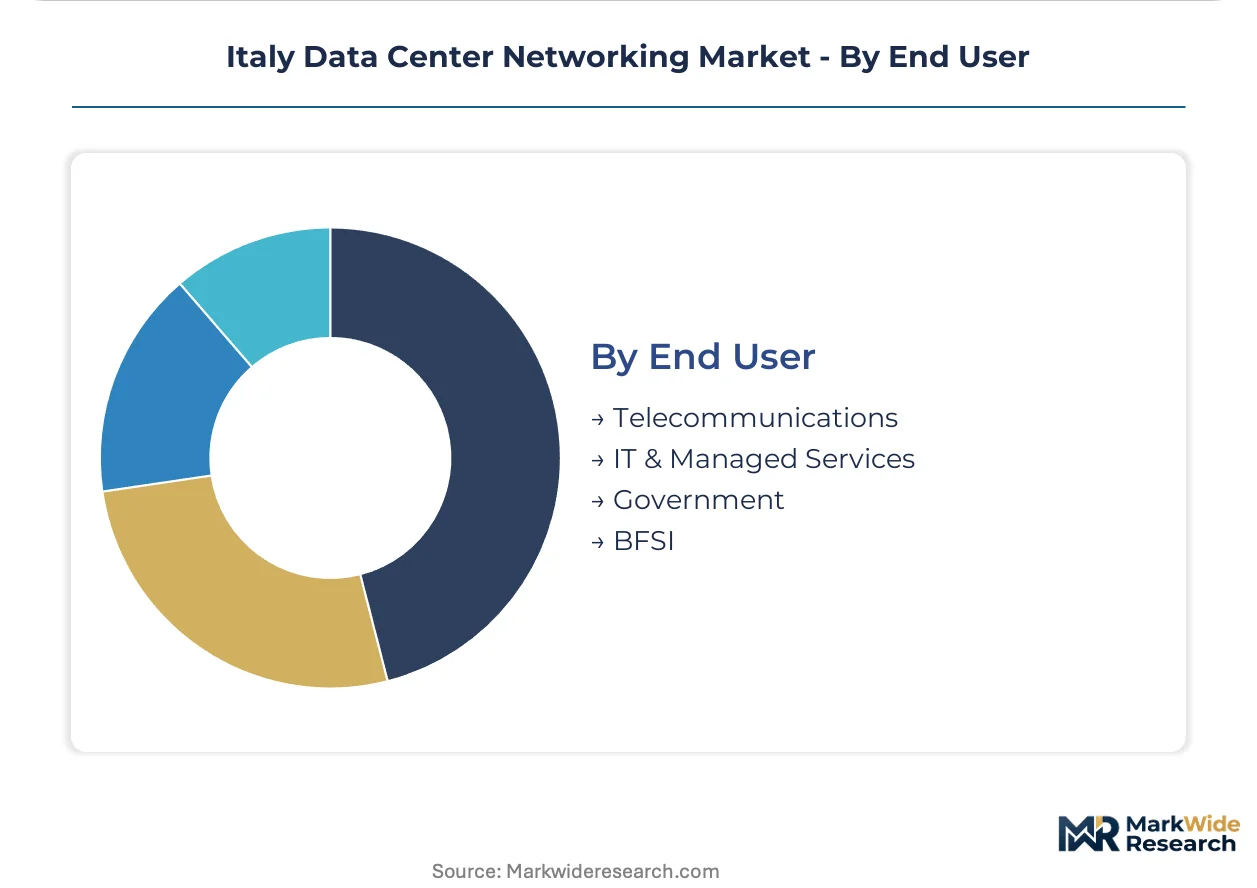
End User:
Vertical-specific compliance deadlines from ACN and sector regulators create staggered procurement waves across telecommunications, financial services, and government segments.
- Telecommunications:National carriers and regional ISPs operating critical infrastructure under NIS2 scope. Encrypted east-west segmentation mandates force simultaneous investments in observability platforms and high-throughput fabrics.
- BFSI:Banks, insurance firms, and payment processors with microsecond-latency requirements. Lombardy financial services clusters drive specialized edge routing demand for algorithmic trading infrastructure.
- IT & Managed Services:Systems integrators and MSPs delivering network-as-a-service bundles. Channel partners pivot from hardware resale to recurring managed services revenue.
- Government:Central and regional agencies subject to ACN cybersecurity frameworks. Public sector procurement consolidates vendor relationships to reduce certification surface area ahead of compliance deadlines.
Highest compliance spending intensity: Telecommunications. Steepest procurement acceleration: BFSI latency-sensitive infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Catania anchors southern Italy's emerging semiconductor corridor, reshaping data center infrastructure investment patterns across the peninsula. Milan's carrier-neutral facilities concentrate submarine cable landings and interconnection density. Rome's government cloud mandates drive public sector network modernization.
Lombardy
Milan's metropolitan area hosts Italy's densest concentration of carrier-neutral colocation facilities, with submarine cable landings from Genoa and Savona pulling enterprise demand across the peninsula. ACN cybersecurity frameworks mandate encrypted east-west traffic segmentation for critical infrastructure operators headquartered in the region. Financial services clusters in the city deploy specialized edge routers to meet microsecond-latency thresholds for algorithmic trading infrastructure.
Piedmont
Turin's automotive supplier ecosystem drives consumption-based procurement models, with Tier-1 manufacturers preferring operational expenditure treatment for networking infrastructure. The EU Green Deal power efficiency mandates incentivize adoption of liquid-cooled switching fabrics among industrial data centers in the province. Channel partners pivot from hardware resale to recurring managed services revenue across the region's manufacturing base.
Lazio
Rome's central government agencies consolidate vendor relationships to reduce certification surface area ahead of ACN compliance deadlines. Public sector procurement concentrates network refresh spending on observability platforms and audit logging capabilities. The city's research institutions adopt lossless InfiniBand fabrics for GPU-intensive AI training clusters, displacing traditional Ethernet in high-performance computing environments.
Sicily
Catania's semiconductor foundry investments create demand for high-throughput network fabrics serving advanced packaging and test facilities. Underdeveloped data center capacity offers greenfield sites for edge caching nodes serving North African connectivity routes. STMicroelectronics' local operations anchor a emerging ecosystem of specialized network engineering talent.
Veneto
Padua and Verona host mid-market manufacturing enterprises adopting SD-WAN convergence with SASE architectures through managed service providers. The region's logistics and pharmaceutical clusters require deterministic traffic flow across virtualized workloads with sub-microsecond latency guarantees. Brownfield facilities resist full-fabric upgrades due to mixed 10G/25G/100G interoperability testing burdens.
Italy Data Center Networking Market Competitive Landscape
Global majors compete with regional champions across switching architectures and routing platforms, with domestic carriers maintaining deep procurement relationships with established vendors. Market structure consolidates around three strategic tiers: core switching incumbents with carrier-certified platforms, specialized edge routing vendors for latency-sensitive verticals, and cloud-native fabric specialists for hyperscale interconnects. Dominant competitive moves include strategic partnerships with colocation providers and portfolio diversification into software-defined controllers.
Among US-based networking vendors, Cisco Systems Inc., Juniper Networks Inc., and Arista Networks Inc. occupy distinct positioning archetypes within the Italian market. Cisco exemplifies the core switching incumbent with entrenched carrier relationships. Juniper represents the specialized edge routing tier targeting financial services latency requirements. Arista anchors the cloud-native fabric specialist position for hyperscale cloud interconnect deployments. Each occupies a defined competitive space without direct substitution across customer segments.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Arista Networks Inc. |
| Hewlett Packard Enterprise Company |
| Dell Technologies Inc. |
| NEC Corporation |
| International Business Machines Corporation |
| Schneider Electric SE |
| ALE International SAS |
| Others |
Pricing and Supply Chain Analysis
400G/800G optical transceiver costs cascade from East Asian contract manufacturers through Italian system integrators, compressing hardware margins at each tier while colocation providers absorb capital risk through network-as-a-service bundling. Copper cable assemblies and magnetics face raw material price volatility that propagates into differentiated pricing for brownfield retrofit versus greenfield deployment.
Pricing Analysis
Extended warranty and software-maintenance bundles separate premium-tier Cisco and Juniper deployments from economy-positioned white-label alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and ACN compliance documentation depth. Cost compression in the standard tier is intensifying because NIS2-mandated encryption upgrades force simultaneous observability platform investments. Mid-market enterprises exhibit highest price sensitivity, while critical infrastructure operators prioritize compliance-grade sourcing over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from ACN-critical operators require qualified secondary suppliers for core switching and routing platforms, extending procurement cycles. Manufacturing concentrates in Taiwan, Malaysia, and China for optical components and merchant silicon. Raw material dependencies span rare earth magnetics, high-purity copper, and specialized photonic substrates. Single-source vulnerability in 800G transceiver supply exposes Italian integrators to lead-time volatility. Distribution runs through authorized distributors with ACN certification pathways, bypassing gray-market channels for critical infrastructure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's data center networking market sits in an infrastructure-transition phase, with InfiniBand fabrics displacing traditional Ethernet in GPU-intensive AI clusters and NIS2 compliance forcing encrypted segmentation upgrades across legacy brownfield facilities.
For Market Incumbents: To counter Arista's hyperscale cloud interconnect encroachment, Cisco and Juniper should deepen carrier certification programs and automate multi-vendor fabric orchestration tooling. Priority levers include captive supply of ACN-prequalified optical components and vertical integration into liquid-cooled switching architectures for EU Green Deal compliance. For New Entrants and Emerging Players: Cloud-native SD-WAN platforms offer the most penetrable entry vector, targeting Turin's Tier-1 automotive suppliers with consumption-based procurement models. White-space concentrates in southern Italy edge caching nodes and SASE-converged managed services for mid-market manufacturing clusters. Go-to-market should route through MSP channel partners pivoting from hardware resale to recurring revenue. For Investors and Strategic Acquirers: ACN audit timeline compression announcements are the leading indicator that compliance-automation software vendors will command acquisition premiums. Long-term viability centers on vendors with certified network engineering training pipelines and multi-cloud orchestration capabilities. Target acquisition archetype: SDN controller specialists with existing ACN certification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| ACN Certification Prequalification | Accelerates procurement cycles for critical infrastructure operators facing compressed compliance deadlines. |
| Liquid-Cooled Switching Fabric Development | Aligns hardware roadmaps with EU Green Deal PUE improvement mandates for Lombardy facilities. |
| InfiniBand-Ethernet Gateway Integration | Enables hybrid fabric deployments bridging AI training clusters with legacy enterprise workloads. |
| Network-as-a-Service Bundling | Captures recurring revenue from Turin automotive suppliers preferring operational expenditure treatment. |
| Submarine Cable Landing Partnerships | Secures interconnection density in Milan carrier-neutral facilities pulling peninsula-wide demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with data center operations directors, ACN compliance officers, colocation procurement leads, and network engineering specialists. Secondary sources included ACN cybersecurity framework documentation, EU AI Act infrastructure rulemaking, BIS technical standards, SEC filings from US-based networking vendors, and hyperscaler capex disclosures. Bottom-up equipment shipment tracking reconciled against top-down facility investment announcements through triangulation protocols.
Data-stream reconciliation across shipment volumes, port-density specifications, and compliance-spending estimates informed the analytical framework. Segmentation dimensions modeled include product type, technology protocol, deployment architecture, and end-user vertical across the projection horizon. CAGRs derived from curve-fitting historical upgrade cycles against regulatory deadline impacts, with specific inputs for NIS2 transposition spending waves and AI cluster buildout acceleration.
The model holds under stable ACN enforcement timelines and continued hyperscaler expansion in Milan; deviation in optical component supply disruption or EU AI Act infrastructure rule acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Fog Networking Market