
 United States Data Center Power Market | 2026-2036
United States Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Power Market Insights
Hyperscale cloud service providers are unwinding the historical dominance of enterprise-owned data centers in United States power procurement. Schneider Electric SE leverages its integrated power distribution architecture to capture utility-scale interconnection projects. ABB Ltd anchors its position through high-voltage direct current systems that bridge renewable generation sites and data center loads. Vertiv Holdings Co competes on thermal-electrical co-design, embedding power and cooling intelligence into single platforms.
United States data center power encompasses the generation, conditioning, distribution, and backup infrastructure that delivers continuous electrical energy to server environments, typically operating at voltages from 480V to 34.5kV with redundancy tiers from N+1 to 2N+1. The primary purpose is to eliminate downtime from grid instability while scaling density beyond 50 kilowatts per rack. Diesel generators retain the largest installed base among power sources, though renewable energy-backed microgrids now attract the fastest capital deployment. Liquid cooling systems are pulling ahead of air-cooled architectures in new hyperscale builds, as rack densities exceed the thermal limits of traditional CRAC units. Small and medium scale facilities face margin compression from stranded capacity, while hyperscale contracts concentrate procurement leverage among a handful of buyers.
The Federal Energy Regulatory Commission governs interstate transmission access that determines where gigawatt-scale data center campuses can interconnect, while the EPA enforces emissions standards that constrain diesel generator runtime and accelerate battery storage adoption. OSHA electrical safety regulations shape installation labor costs and contractor qualification requirements across state jurisdictions. Stakeholders must monitor interconnection queue reform proceedings and state-level renewable portfolio standards that will determine which power source configurations remain economically viable for new construction.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for multi-hundred-megawatt power infrastructure while interconnection queues in Northern Virginia and Dallas-Fort Worth extend beyond thirty-six months. This supply-demand asymmetry is forcing developers to pre-commit capital years ahead of server deployment.
Growth Catalysts
- Inflation Reduction Act tax credits:The IRA's investment tax credits for standalone battery storage and solar-plus-storage configurations are redirecting developer capital toward renewable-backed data center campuses in Arizona and Nevada.
- Liquid cooling adoption:Rack densities exceeding 100 kilowatts in AI training clusters are mandating direct-to-chip liquid cooling systems that reduce power usage effectiveness below 1.15.
- Texas ERCOT market structure:The nodal pricing regime and streamlined interconnection protocols in Texas are attracting hyperscale buyers seeking faster utility integration than PJM queue timelines permit.
Market Restraints
- Transformer supply concentration:North American medium-voltage transformer manufacturing concentrates among a handful of suppliers, extending lead times for 34.5kV substation equipment beyond eighteen months.
- FERC interconnection reform delays:Proposed queue restructuring under Federal Energy Regulatory Commission Order 2023 remains in implementation limbo, perpetuating first-come-first-served bottlenecks.
- Diesel generator runtime restrictions:EPA Tier 4 Final emissions standards constrain emergency generator testing hours and accelerate capital costs for exhaust aftertreatment systems.
Strategic Opportunities
- Behind-the-meter nuclear:Small modular reactor developers are targeting direct power purchase agreements with hyperscale operators seeking 24/7 carbon-free baseload outside renewable intermittency constraints.
- Second-life battery storage:Repurposed electric vehicle battery packs are entering the data center uninterruptible power supply market at 40% cost discounts versus new lithium-ion installations.
- Ohio and Indiana greenfield sites:States with surplus transmission capacity and streamlined permitting are attracting developers priced out of Northern Virginia's congested utility zones.
Industry Challenges
- Medium-voltage electrical contractor scarcity:Specialized crews qualified for 15kV and 34.5kV data center substation construction command premium wages and multi-month scheduling backlogs across the Southwest and Midwest.
- Legacy air-cooled facility retrofit complexity:Enterprise data centers built for 8-12 kilowatt per rack densities face stranded asset risk as AI workloads demand infrastructure rebuilds rather than incremental upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Power Market |
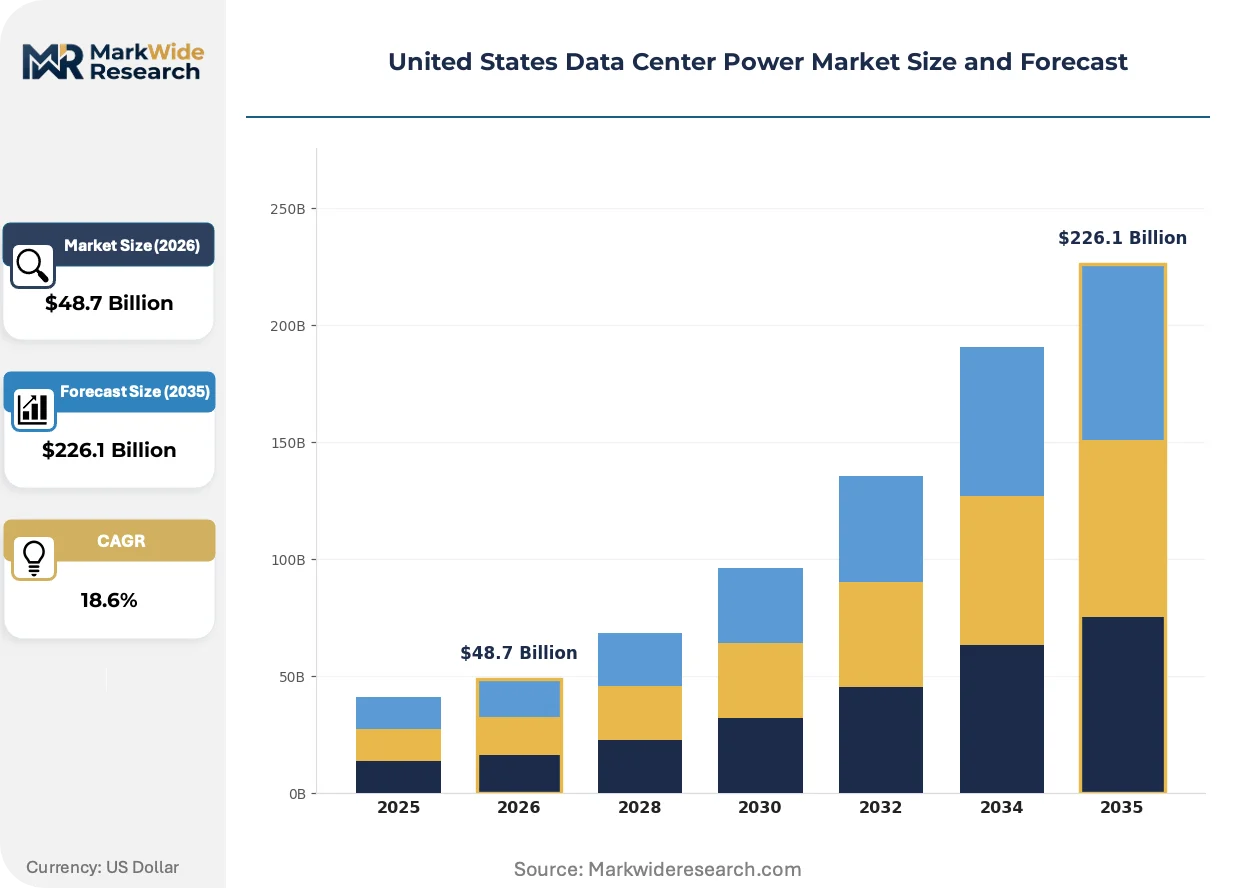
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $226.1 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, UPS Systems, Grid Power Cooling System: Chilled Water, Air Cooled, Evaporative Cooling, Liquid Cooling Capacity: Small Scale, Medium Scale, Large Scale, Hyperscale End User: Colocation Providers, Enterprises, Cloud Service Providers, Government Agencies |
| Companies Covered | Schneider Electric SE, ABB Ltd, Vertiv Holdings Co, Eaton Corp plc, Delta Electronics Inc, Cummins Inc, Caterpillar Inc, Generac Power Systems, Mitsubishi Electric Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Power Market Trends and Innovations
Power infrastructure architectures are bifurcating between ultra-dense AI training facilities demanding specialized high-voltage distribution and enterprise colocation sites optimizing for legacy workloads. This technical divergence is fragmenting vendor roadmaps and procurement specifications.
Solid-state transformers with silicon carbide power electronics are displacing conventional oil-filled units in new hyperscale builds. Microsoft and Google data center engineering teams are specifying 10kV-to-480V solid-state distribution for sub-cycle voltage regulation. The technology is displacing electromechanical tap changers and enabling direct integration with battery energy storage systems without separate power conversion stages.
The EPA's proposed Good Neighbor Plan ozone transport rule is tightening nitrogen oxide emission budgets for fossil fuel power plants in twenty-three states. This regulatory pressure is accelerating hyperscale operator commitments to 100% renewable energy matching and forcing diesel generator reliance toward zero-emission alternatives. Data center developers in the Ohio River Valley are responding by procuring grid-interactive battery systems sized for multi-hour runtime rather than traditional fifteen-minute UPS bridging.
Power purchase agreement structures are migrating from virtual renewable energy credits to 24/7 hourly carbon-free energy matching. Hyperscale procurement teams are rejecting annualized renewable claims and demanding time-coincident clean power verification through emerging certificate tracking platforms. This behavioral shift is most visible in Northern Virginia, where Dominion Energy's proposed offshore wind and solar-plus-storage portfolios are being sized to hourly load shapes rather than annual megawatt-hour totals.
United States Data Center Power Market Segmentation
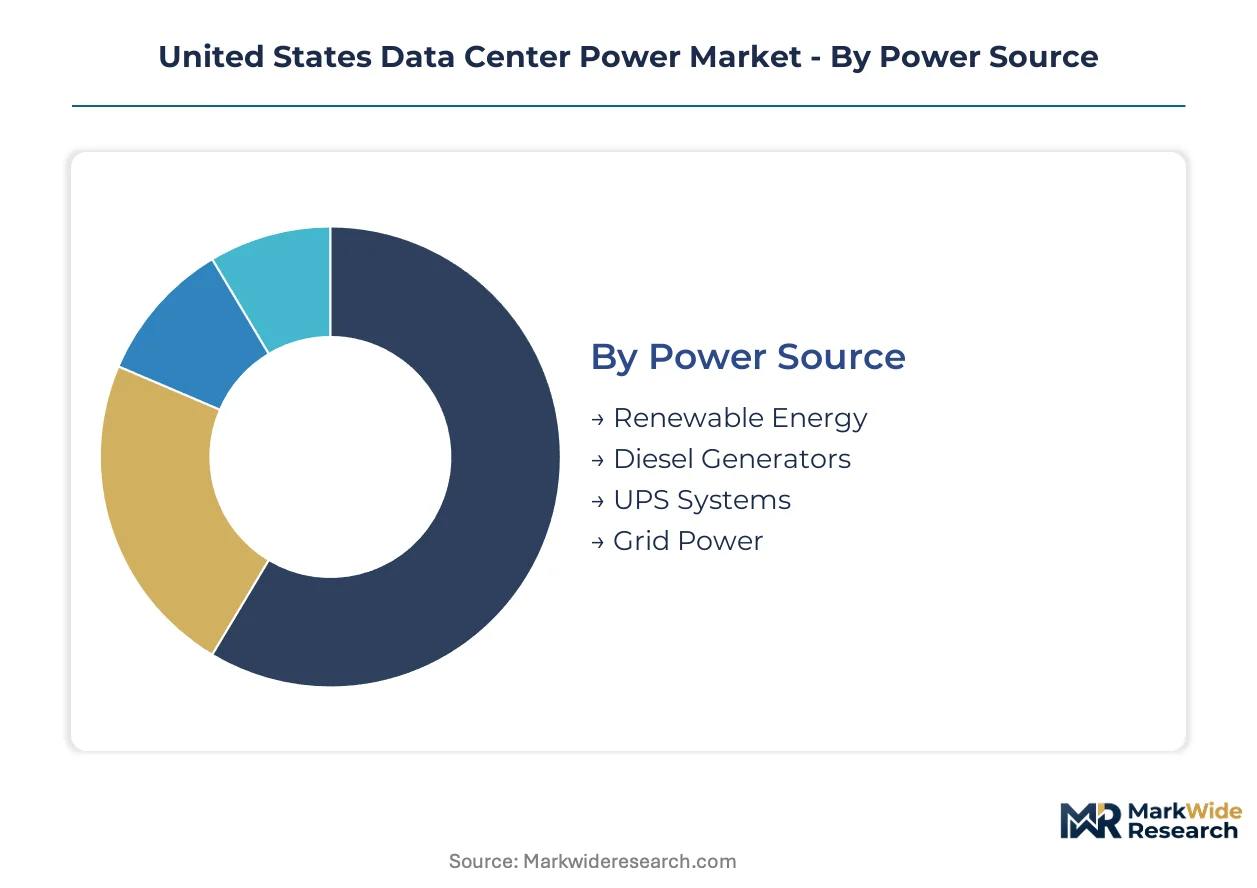
Power infrastructure segmentation in United States data centers reveals how procurement priorities diverge between legacy enterprise facilities and AI-driven hyperscale campuses. Each dimension—power source, cooling architecture, facility scale, and buyer type—carries distinct interconnection constraints and capital intensity profiles that reshape vendor competitive positioning.
Power Source:
Substitution pressure from renewable-backed microgrids is eroding the historical dominance of diesel-dependent backup architectures, particularly as EPA emissions enforcement tightens.
- Renewable Energy:Solar-plus-storage and wind-backed power purchase agreements now dominate new hyperscale procurement in Arizona, Nevada, and Texas. Dominion Energy's hourly carbon-free matching requirements in Northern Virginia are forcing developers to abandon annualized renewable credit claims.
- Diesel Generators:EPA Tier 4 Final aftertreatment systems and runtime restrictions are inflating capital costs and maintenance burdens. Stranded capacity risk looms for facilities that cannot retrofit to battery or fuel-cell alternatives within compliance timelines.
- UPS Systems:Lithium-ion and emerging second-life EV battery configurations are displacing valve-regulated lead-acid architectures in facilities below 10 megawatts.
- Grid Power:FERC-jurisdictional interconnection queues stretching thirty-six months in PJM territory are pushing developers toward behind-the-meter generation or ERCOT's streamlined nodal market.
Grid Power retains volume leadership across installed base; Renewable Energy holds the steepest expansion curve among new construction commitments.
Cooling System:
Cost tier stratification separates premium liquid-cooled AI training facilities from standardized air-cooled enterprise colocation, with thermal design power thresholds dictating architecture selection.
- Liquid Cooling:Direct-to-chip and immersion systems are mandatory for rack densities exceeding 100 kilowatts in AI training clusters. Microsoft and Google engineering specifications now embed liquid cooling into power distribution co-design, collapsing the historical separation of thermal and electrical infrastructure procurement.
- Air Cooled:Legacy CRAC and CRAH architectures face obsolescence risk as average rack densities climb past 30 kilowatts, though they retain economic viability in secondary markets and enterprise retention workloads.
- Chilled Water:Central plant configurations persist in large-scale colocation facilities with predictable base loads, constrained by water availability and local utility rate structures.
- Evaporative Cooling:Water-scarce regions in the Southwest are rejecting adiabatic designs due to municipal supply constraints and drought contingency regulations.
Air Cooled maintains installed base dominance; Liquid Cooling is climbing the fastest as hyperscale AI deployment accelerates.
Capacity:
Customer type concentration among hyperscale buyers is compressing procurement leverage and fragmenting vendor roadmaps between commodity-scale and specialized high-density equipment.
- Hyperscale:Facilities exceeding 100 megawatts command dedicated substations at 34.5kV and direct renewable power purchase agreements. Interconnection pre-commitment timelines now extend three to five years ahead of server deployment in Northern Virginia and Dallas-Fort Worth.
- Large Scale:Enterprise-owned campuses and wholesale colocation operators face margin compression from stranded capacity as AI workloads migrate to hyperscale-optimized environments.
- Medium Scale:Regional colocation providers in Ohio and Indiana are capturing demand priced out of congested Northern Virginia utility zones, leveraging surplus transmission capacity.
- Small Scale:Edge computing and retail colocation facilities below 5 megawatts are consolidating under national operators as standalone economics deteriorate against hyperscale scale advantages.
Large Scale retains transaction volume leadership; Hyperscale is gaining share fastest in absolute megawatt terms.
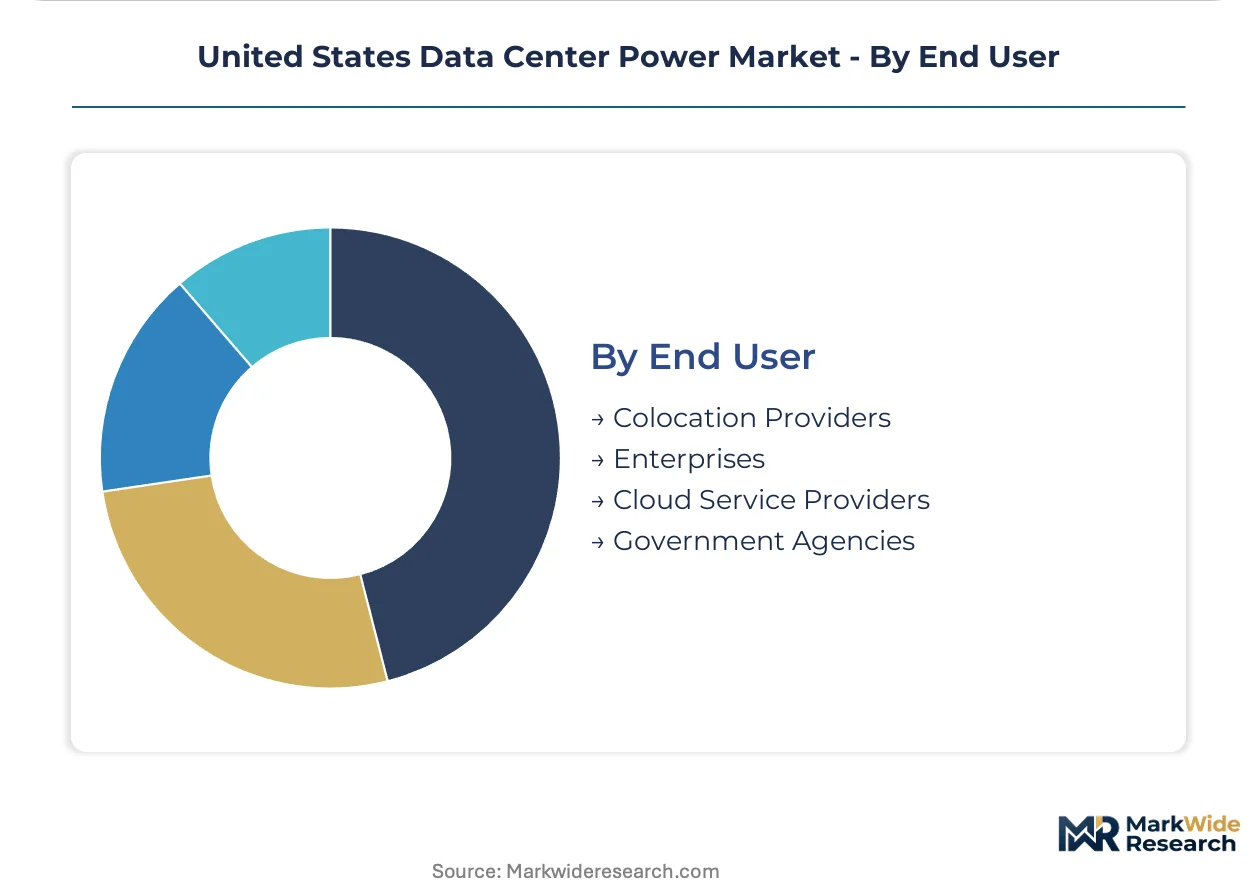
End User:
Application-driven procurement divergence separates cloud service providers seeking 24/7 carbon-free baseload from government agencies bound by federal sustainability mandates and domestic content requirements.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform are compressing power infrastructure procurement cycles and mandating solid-state transformer specifications for sub-cycle voltage regulation. Behind-the-meter small modular reactor discussions are advancing for baseload outside renewable intermittency.
- Enterprises:Fortune 500 captive data centers face retrofit-or-exit decisions as AI training demands exceed legacy air-cooled infrastructure limits. Third-party colocation migration is accelerating for workloads lacking hyperscale-scale density requirements.
- Colocation Providers:Wholesale operators like Equinix and Digital Realty are bifurcating portfolios between hyperscale-optimized campuses and multitenant retail facilities with divergent power and cooling specifications.
- Government Agencies:Federal data centers operate under Executive Order 14057 clean electricity procurement mandates and Buy American domestic content requirements for electrical equipment, constraining supplier pools.
Colocation Providers retain facility count leadership; Cloud Service Providers are expanding most quickly in power capacity committed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 765-kilovolt transmission backbone spanning PJM territory underwrites Northern Virginia's dominance in United States data center power demand. ERCOT's nodal market structure and streamlined interconnection protocols are redirecting hyperscale investment toward Texas. Federal and state-level clean energy incentives are reshaping power procurement geography across multiple jurisdictions.
Northern Virginia
Dominion Energy's interconnection queues now stretch beyond thirty-six months for multi-hundred-megawatt data center campuses. The Virginia Clean Economy Act mandates carbon-free electricity by 2045, forcing developers to abandon annualized renewable credit claims for hourly matching. Loudoun County's Data Center Alley concentrates over 35 percent of United States hyperscale capacity, with utility-scale substation construction commanding premium contractor wages.
Texas
ERCOT's nodal pricing regime attracts hyperscale buyers seeking faster grid integration than PJM timelines permit. The state lacks a renewable portfolio standard, though property tax abatements under Chapter 313 incentivize solar-plus-storage deployments. Dallas-Fort Worth and Austin metro areas host expanding Google and Microsoft campuses, with behind-the-meter generation reducing transmission dependency.
Arizona
APS and SRP utility territories offer surplus transmission capacity absent in coastal markets. The Inflation Reduction Act's investment tax credits redirect developer capital toward solar-backed data center campuses in Phoenix and Mesa. Water scarcity constraints are forcing evaporative cooling rejection in favor of liquid-cooled architectures.
Ohio
Surplus transmission capacity and streamlined permitting attract developers priced out of Northern Virginia's congested zones. The Ohio Power Siting Board has accelerated review timelines for renewable-backed generation interconnecting to hyperscale loads. Columbus and Cincinnati metro areas are capturing enterprise colocation migration from legacy East Coast facilities.
Nevada
NV Energy's green tariff programs enable direct renewable power purchase agreements outside traditional utility rate structures. The state's abundant solar resource and minimal water availability mandate air-cooled and liquid-cooled hybrid designs. Northern Nevada's Tahoe-Reno Industrial Center hosts Apple and Tesla data center infrastructure with dedicated substation capacity.
United States Data Center Power Market Competitive Landscape
Concentration sits with integrated electrical infrastructure conglomerates possessing utility-scale interconnection expertise. The vendor base stratifies between transformer and switchgear specialists, thermal-electrical co-design platforms, and backup power generation manufacturers. Three archetypes dominate: European industrial conglomerates with power distribution heritage, North American electrical equipment specialists, and Asian electronics manufacturers with silicon carbide capabilities. Competitive moves center on solid-state transformer R&D partnerships and renewable-backed microgrid engineering contracts.
Among European industrial conglomerates, Schneider Electric SE and ABB Ltd exemplify the integrated power distribution archetype with high-voltage direct current and medium-voltage equipment portfolios. Vertiv Holdings Co anchors the thermal-electrical co-design tier, embedding power and cooling intelligence into unified platforms. These three entities represent the competitive core around which specialized contractors and component suppliers orbit.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Vertiv Holdings Co |
| Eaton Corp plc |
| Delta Electronics Inc |
| Cummins Inc |
| Caterpillar Inc |
| Generac Power Systems |
| Mitsubishi Electric Corp |
| Others |
Pricing and Supply Chain Analysis
Solid-state transformer adoption replacing conventional oil-filled units simultaneously redraws procurement geography toward silicon carbide foundries and collapses historical pricing premiums on electromechanical voltage regulation. This substitution dynamic concentrates buyer leverage among hyperscale operators while fragmenting vendor margins across legacy and next-generation equipment tiers.
Pricing Analysis
Volume-discount tiering structures separate hyperscale contracts exceeding 100 megawatts from enterprise procurement below 10 megawatts, with the former commanding 15-25 percent unit cost reductions on medium-voltage switchgear. Price differentiation rests on UL 891 certification tier and geographic delivery distance from manufacturing clusters, with Southwest destinations bearing elevated logistics premiums. Pricing pressure stems from transformer supply concentration extending equipment lead times and inflating spot-market premiums for 34.5kV substation components. Hyperscale cloud providers exhibit lowest price sensitivity due to long-term power purchase agreement structures, while small-scale colocation operators face acute margin compression from stranded capacity against scale advantages.
Supply Chain Analysis
China and South Korea anchor silicon carbide wafer and power electronics fabrication for solid-state transformer components, while Germany and Switzerland concentrate precision winding and insulation systems for conventional medium-voltage equipment. Raw material dependencies encompass copper rod for busbar systems, grain-oriented electrical steel for magnetic cores, and lithium carbonate for battery energy storage integration. Supply chain risk centers on single-source vulnerability for 34.5kV-class transformer bushings and tap changers from limited North American foundry capacity. Distribution runs through electrical equipment distributors serving EPC contractors, with direct OEM relationships increasingly bypassing traditional channel intermediaries for hyperscale campus projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from the technical bifurcation between AI-optimized liquid-cooled facilities and legacy air-cooled enterprise environments, creating distinct procurement niches with divergent vendor qualification requirements.
For Market Incumbents: Consolidate utility-scale interconnection expertise through captive relationships with FERC-jurisdictional transmission planners, insulating against emerging entrants lacking queue navigation capabilities. Deepen backward integration into silicon carbide power electronics manufacturing to secure solid-state transformer supply chains against Asian component concentration. Prioritize certification investment for EPA Tier 4 Final emissions compliance to capture diesel generator retrofit demand ahead of regulatory deadlines.
For New Entrants and Emerging Players: Lead with behind-the-meter nuclear engineering partnerships targeting hyperscale operators seeking 24/7 carbon-free baseload outside renewable intermittency constraints. Target Ohio and Indiana greenfield development corridors where surplus transmission capacity and streamlined state permitting attract demand priced out of Northern Virginia congestion. Pursue second-life battery storage configurations for facilities below 10 megawatts, leveraging 40 percent cost discounts versus new lithium-ion installations to penetrate price-sensitive edge computing segments.
For Investors and Strategic Acquirers: The market sits at a capital-deployment acceleration phase that favors integrated electrical infrastructure platforms with utility-scale interconnection track records. Long-term viability over the coming decade hinges on positioning across solid-state transformer and liquid-cooled co-design capabilities rather than legacy air-cooled equipment exposure. Acquisition target archetypes include specialized medium-voltage electrical contractors with 34.5kV qualification scarcity and renewable-backed microgrid engineering firms with ERCOT or PJM interconnection experience. The signal to watch is FERC Order 2023 implementation progress, where queue restructuring would unlock stranded project pipelines and revalue interconnection-ready development sites.
| Strategic Initiative | Industry Significance |
|---|---|
| Interconnection Queue Pre-Commitment | Secures multi-year utility integration timelines ahead of server deployment in PJM territory. |
| Solid-State Transformer R&D Partnership | Captures hyperscale specifications for sub-cycle voltage regulation at 10kV-to-480V distribution. |
| Renewable-Backed Microgrid Engineering | Aligns with IRA tax credits redirecting capital toward solar-plus-storage campus configurations. |
| Second-Life Battery Storage Integration | Penetrates cost-sensitive facilities below 10 megawatts with repurposed EV pack economics. |
| Behind-the-Meter Nuclear Development | Addresses hyperscale demand for 24/7 carbon-free baseload outside renewable intermittency. |
Research Methodology
A spread of perspectives from hyperscale cloud engineering directors, utility interconnection planners, EPC contractor project managers, and electrical equipment procurement officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA generation capacity databases, EPA emissions compliance records, and state-level renewable portfolio standard documentation. Bottom-up facility-level power capacity aggregation triangulated against top-down utility interconnection queue data to establish market sizing boundaries.
Segmentation dimensions modeled span power source configuration, cooling architecture thermal design power thresholds, facility capacity tiers from edge to hyperscale, and end-user procurement archetypes across the projection horizon. CAGRs derive from regression analysis of historical interconnection commitments against forward utility disclosure filings, with scenario weighting applied to IRA tax credit utilization rates and FERC regulatory implementation timelines. Forecast inputs incorporate transformer manufacturing capacity constraints, silicon carbide substrate availability, and medium-voltage electrical contractor labor market tightness.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale capital deployment, unaltered IRA credit structures, or accelerated FERC queue reform would require recalibration. Forecasts reflect documented assumptions regarding renewable energy cost trajectories, battery storage cycle economics, and nuclear regulatory licensing timelines. Recalibration cycles align with material shifts in interconnection queue reform proceedings, EPA emissions enforcement stringency, and hyperscale operator carbon-free energy matching requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Singapore Data Center Rack Market