
 United States (US) Data Center Construction Market | 2026-2036
United States (US) Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
United States (US) Data Center Construction Market Insights
The split between hyperscale and enterprise-grade data center construction is hardening into two distinct procurement ecosystems. Turner Construction leverages its design-build scale to dominate mission-critical builds for cloud operators. DPR Construction anchors its position through integrated project delivery models that compress commissioning timelines. Skanska USA differentiates via sustainability-led construction protocols targeting net-zero operational facilities.
Data center construction encompasses the engineering, structural build-out, and mechanical-electrical-plumbing integration of facilities housing compute, storage, and network infrastructure, typically requiring power densities exceeding 150 watts per square foot and precision cooling within plus-or-minus one degree Fahrenheit. Tier 3 data centers command the largest share of new ground-up investment due to concurrent maintainability requirements that reduce operational risk for financial and healthcare clients. Modular data centers represent the fastest-expanding product type as edge computing deployments accelerate in secondary markets. General contracting remains the most mature construction type, though integrated project delivery is capturing margin pools through risk-sharing mechanisms that align designer and builder incentives.
OSHA governs worker safety protocols during data center construction, while the EPA regulates diesel generator emissions and hazardous material handling on site. State-level public utility commissions in Texas, Arizona, and Ohio shape interconnection timelines that directly gate project completion schedules. Stakeholders must monitor evolving grid interconnection queues and utility-scale renewable power purchase agreement availability as decisive variables for site selection and total cost of ownership.
Market Dynamics
The US data center construction market is bifurcating around power density requirements, with cloud hyperscalers demanding 300+ watts per square foot while enterprise facilities stagnate at legacy densities. This divergence is fragmenting the contractor base into two non-overlapping specialization tiers.
Growth Catalysts
- Inflation Reduction Act tax credits:The IRA's clean energy production and investment tax credits are accelerating renewable power purchase agreements for data center load commitments. Developers in Texas and Arizona are structuring builds around solar-plus-storage configurations to capture these incentives.
- Hyperscale facility expansion:Cloud service providers are commissioning multi-gigawatt campuses across secondary markets including Columbus, Ohio and Salt Lake City, Utah. These projects require specialized mission-critical construction expertise that commands premium contracting margins.
- Edge computing deployment:Latency-sensitive applications in autonomous vehicles and industrial IoT are driving modular data center installations in tier-two metropolitan areas. Prefabricated electrical-mechanical modules are compressing deployment timelines from months to weeks.
Market Restraints
- Transformer and switchgear supply concentration:Domestic manufacturing capacity for medium-voltage electrical infrastructure remains concentrated among a limited supplier base. Lead times for critical power distribution equipment now extend eighteen to twenty-four months, gating project completion schedules.
- Grid interconnection queue congestion:Regional transmission organizations and independent system operators across Texas, PJM, and SPP territories face backlogs exceeding five thousand megawatts of pending data center interconnection requests. Utility commission staffing limitations are extending study timelines unpredictably.
- Liquid cooling infrastructure immaturity:Direct-to-chip and immersion cooling systems required for high-density AI training clusters lack standardized installation protocols. Mechanical contractor expertise remains concentrated among a handful of specialized firms, constraining scalable deployment.
Strategic Opportunities
- Secondary market penetration:Markets including Atlanta, Georgia and Phoenix, Arizona offer available transmission capacity and lower land costs compared to Northern Virginia. Developers are securing multi-hundred-acre sites with pre-approved zoning for hyperscale expansion.
- Waste heat recovery integration:District heating applications and industrial process heat offtake agreements are monetizing thermal output from high-density facilities. Municipal utilities in colder climate zones are piloting heat export contracts with data center operators.
- Nuclear power colocation:Small modular reactor developers are securing sites adjacent to planned data center campuses for dedicated baseload power supply. The Department of Energy is streamlining permitting for advanced reactor deployments at industrial facilities.
Industry Challenges
- Mission-critical construction labor scarcity:Journeyman electricians with experience in 480-volt and medium-voltage distribution systems command wage premiums exceeding forty percent above standard commercial rates. Apprenticeship programs through the National Electrical Contractors Association are insufficient to meet demand acceleration.
- Commissioning complexity for Tier 3 certification:Uptime Institute's concurrent maintainability testing requires extended operational validation periods that compress revenue recognition timelines. Design-build contractors are absorbing extended warranty obligations to accelerate certificate issuance.
- Water scarcity in southwestern markets:Evaporative cooling systems in Arizona and Nevada facilities face regulatory pressure from state water authorities. Developers are retrofitting designs for air-cooled chillers and adiabatic systems that increase capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States (US) Data Center Construction Market |
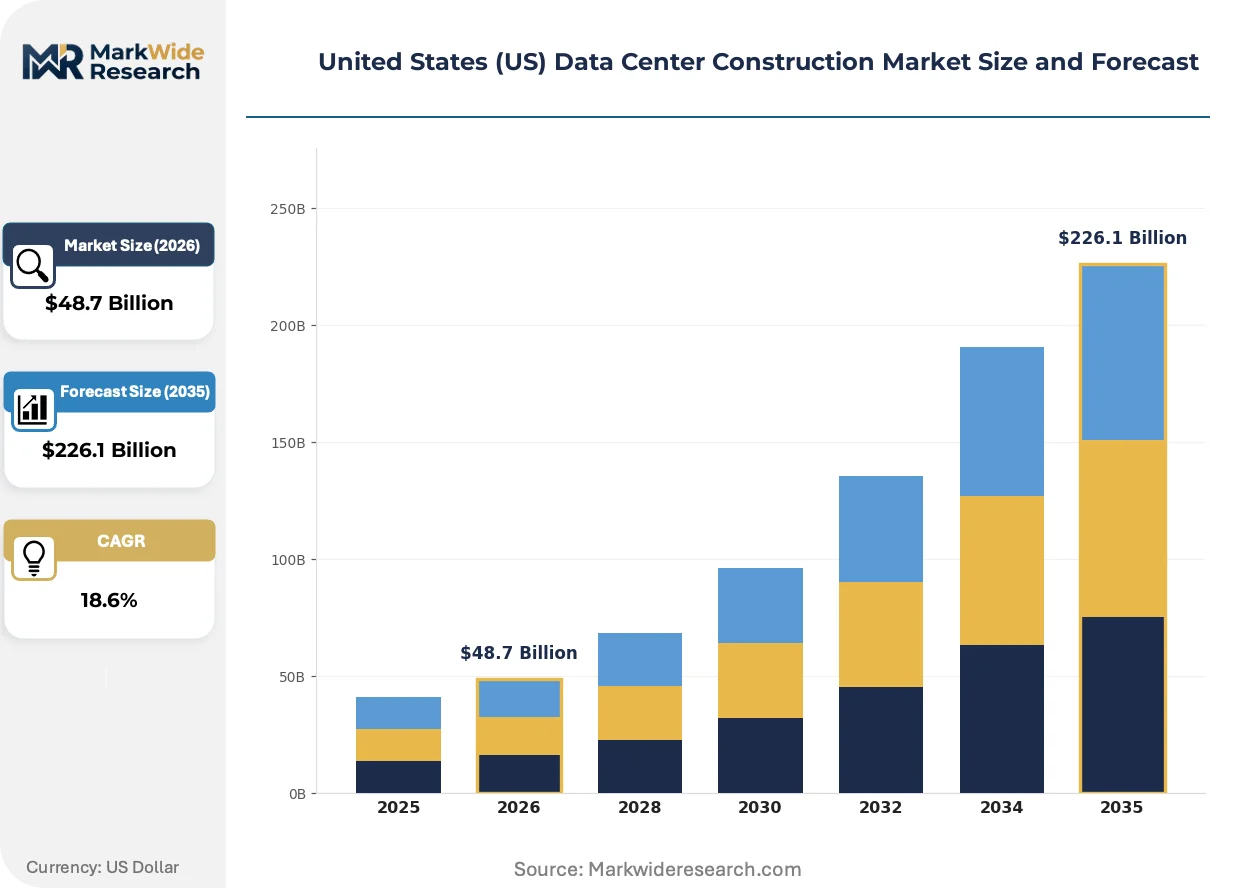
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $226.1 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Tier 1 Data Centers, Tier 2 Data Centers, Tier 3 Data Centers Construction Type: Design-Build, General Contracting, Construction Management, Integrated Project Delivery End User: Cloud Service Providers, Telecommunication Companies, Enterprises, Colocation Providers Power Source: Renewable Energy, Diesel Generators, Grid Power, Uninterruptible Power Supply |
| Companies Covered | AECOM, Turner Construction, DPR Construction, Holder Construction, Skanska USA, Fortis Construction, Kiewit Corporation, Clayco, Gensler, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States (US) Data Center Construction Market Trends and Innovations
Construction methodology is pivoting from stick-built to industrialized prefabrication as power density requirements exceed the practical limits of field-installed mechanical systems. This shift is redrawing competitive advantage around supply chain control rather than traditional general contracting relationships.
Modular electrical and mechanical skids are decentralizing the traditional data center construction model by shifting assembly to offsite manufacturing facilities. Cloud operators including hyperscale deployers are specifying factory-integrated power modules that arrive with pre-tested switchgear, UPS systems, and busway connections. This prefabrication approach is compressing on-site construction schedules and reducing commissioning risk for complex electrical infrastructure.
The EPA's proposed Good Neighbor Plan and state-level emissions regulations are tightening constraints on diesel generator runtime and fuel storage capacity. Developers in non-attainment zones are procuring battery energy storage systems and fuel cells as backup power alternatives that satisfy air quality requirements. Financial and healthcare tenants with stringent uptime requirements are driving specification changes that favor lithium-ion and emerging solid-state battery technologies over traditional genset configurations.
Power purchase agreement structures are evolving from virtual to sleeved arrangements that provide physical delivery of renewable electrons rather than certificate-based claims. Corporate sustainability officers at technology and financial services firms are demanding additionality proof and hourly matching for carbon-free energy claims. This contractual sophistication is forcing developers to structure site selection around real-time grid carbon intensity and co-located solar or wind generation rather than generic regional renewable penetration statistics.
United States (US) Data Center Construction Market Segmentation
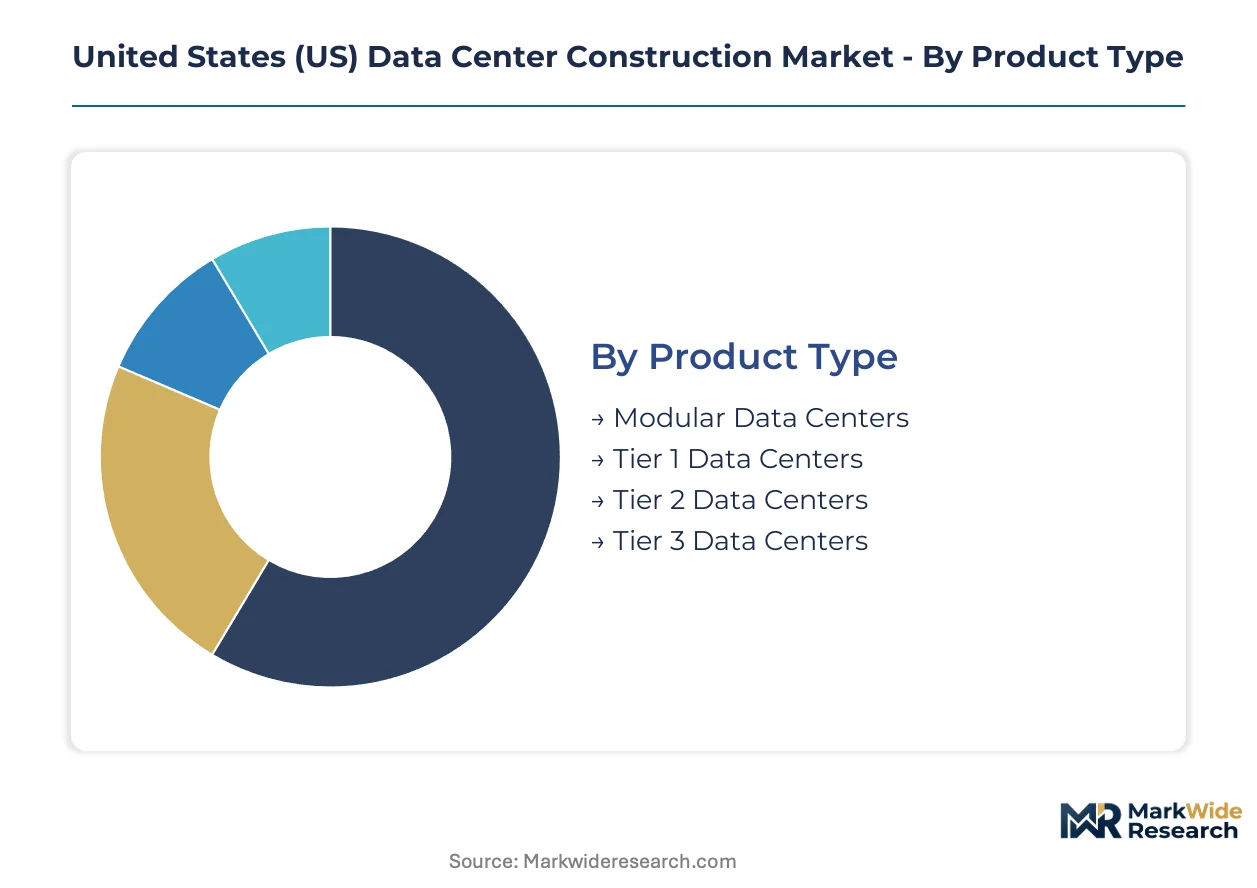
Data center construction segmentation reveals how procurement ecosystems fragment around technical risk tolerance and delivery speed requirements. Contractor selection, certification standards, and power architecture decisions cascade differently across each dimension.
Product Type:
Integration depth varies sharply: Tier 3 facilities demand embedded mechanical-electrical systems with concurrent maintainability, while modular units ship as standalone skids requiring minimal field integration.
- Tier 3 Data Centers:Concurrent maintainability specifications mandate dual-corded power paths and N+1 cooling redundancy. Financial services and healthcare tenants in Northern Virginia and Dallas-Fort Worth drive specification intensity, with Uptime Institute certification extending commissioning timelines. OSHA and EPA compliance layers add regulatory complexity to these mission-critical builds.
- Modular Data Centers:Prefabricated electrical-mechanical skids arrive with pre-tested switchgear and factory-integrated UPS systems. Edge computing deployments in Columbus, Ohio and Salt Lake City, Utah compress deployment from months to weeks, though liquid cooling integration for AI clusters remains technically immature.
- Tier 2 Data Centers:Redundant capacity components with single distribution paths serve mid-market enterprise colocation in secondary markets.
- Tier 1 Data Centers:Basic capacity without redundancy supports non-critical backup and development environments with minimal mechanical complexity.
Volume placements concentrate in Tier 3 facilities; the faster expansion belongs to modular data centers.
Construction Type:
Cost tier stratification separates premium risk-sharing models from commoditized procurement, with margin capture shifting toward design-build and integrated project delivery.
- Design-Build:Single-contractor accountability compresses schedule risk for hyperscale cloud operators demanding 300+ watts per square foot. Turner Construction and DPR Construction dominate this tier through mission-critical expertise and compressed commissioning timelines.
- Integrated Project Delivery:Risk-sharing mechanisms align designer and builder incentives, capturing margin pools unavailable in traditional contracting. Cloud service providers in Texas and Arizona specify this model for multi-gigawatt campuses where grid interconnection delays threaten revenue recognition.
- General Contracting:Mature procurement model retains share in enterprise builds with legacy power densities and predictable mechanical scopes.
- Construction Management:Owner-retained risk suits institutional investors with internal technical staffing and long-dated hold periods.
Revenue concentration sits with design-build; integrated project delivery is climbing the fastest.
End User:
Customer type determines power density thresholds, with cloud hyperscalers operating an entirely separate procurement ecosystem from enterprise facilities.
- Cloud Service Providers:Hyperscale operators commission multi-gigawatt campuses with 300+ watts per square foot requirements. Amazon Web Services, Microsoft Azure, and Google Cloud Platform drive specification intensity across Northern Virginia, Phoenix, and Columbus, Ohio, with Inflation Reduction Act tax credits shaping renewable power purchase agreement structures.
- Enterprises:Financial services and healthcare tenants demand Tier 3 certification with stringent uptime requirements. JPMorgan Chase and UnitedHealth Group specifications favor lithium-ion battery backup over diesel generators in EPA non-attainment zones.
- Colocation Providers:Equinix and Digital Realty operate multi-tenant facilities requiring flexible power increments and rapid customer onboarding.
- Telecommunication Companies:AT&T and Verizon edge deployments prioritize latency reduction over density, favoring modular installations in tier-two metros.
Capital deployment concentrates with cloud service providers; enterprise demand is expanding most quickly in regulated sectors.
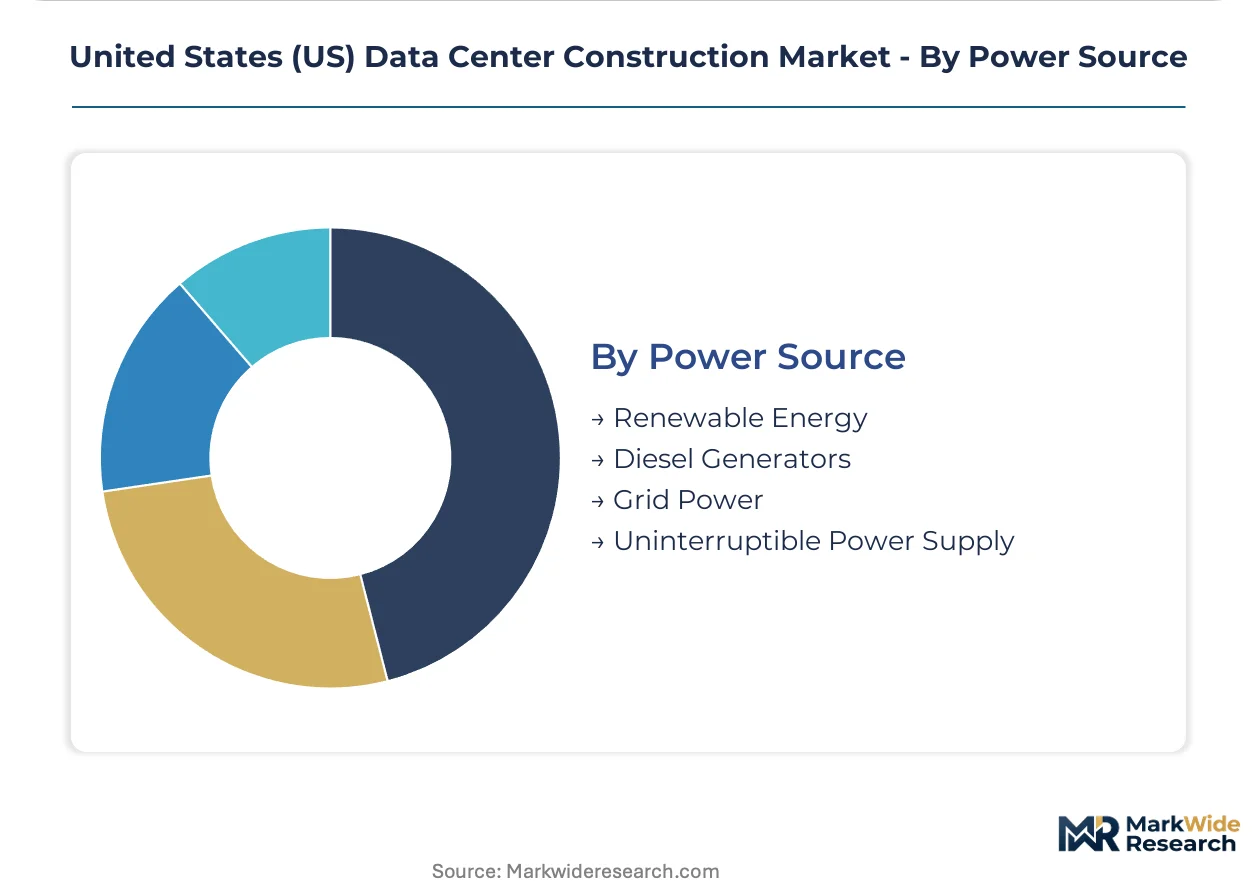
Power Source:
Supply concentration and regulatory pressure are fragmenting backup power architectures, with diesel generators facing displacement in certain air quality jurisdictions.
- Renewable Energy:Solar-plus-storage configurations in Texas and Arizona capture Inflation Reduction Act production and investment tax credits. Sleeved power purchase agreements with hourly carbon matching replace virtual structures as corporate sustainability officers demand additionality proof.
- Uninterruptible Power Supply:Lithium-ion and emerging solid-state battery technologies satisfy EPA Good Neighbor Plan constraints in non-attainment zones. Financial and healthcare tenants with stringent uptime requirements drive specification away from traditional genset configurations.
- Diesel Generators:EPA runtime restrictions and fuel storage capacity limits constrain deployment in California and northeastern markets.
- Grid Power:Primary load supply faces interconnection queue congestion across ERCOT, PJM, and SPP territories exceeding five thousand megawatts of pending data center requests.
Installed base concentrates on grid power with diesel backup; renewable-plus-storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Loudoun and Prince William counties concentrate over one-third of national data center capacity under active construction, with power commitments exceeding twelve gigawatts across Ashburn, Manassas, and Gainesville corridors.
Northern Virginia
Hyperscale cloud operators drive demand through multi-gigawatt campus commitments in Loudoun County's Data Center Alley. Virginia's Department of Environmental Quality enforces air quality permits for backup generators while Dominion Energy manages interconnection queues exceeding three thousand megawatts. Ashburn and Manassas host the densest concentration of Tier 3 facilities under construction in the United States.
Texas
Solar-plus-storage configurations attract developers capturing Inflation Reduction Act production tax credits across ERCOT territory. The Public Utility Commission of Texas oversees interconnection studies facing eighteen-month backlogs for multi-hundred-megawatt loads. Dallas-Fort Worth and Austin metro areas lead ground-up construction with pre-approved zoning for hyperscale expansion.
Arizona
Phoenix and Mesa offer available transmission capacity and lower land costs compared to saturated coastal markets. The Arizona Corporation Commission regulates water use for evaporative cooling systems amid state drought declarations. Chandler and Mesa industrial corridors concentrate modular data center deployments for edge computing workloads.
Ohio
Enterprise financial services tenants demand Tier 3 certification for Columbus-region facilities serving Midwest latency requirements. The Ohio Power Siting Board coordinates with PJM Interconnection on transmission upgrades for data center load clusters. New Albany and Dublin suburbs anchor development with fiber-rich infrastructure and favorable property tax abatements.
Utah
Salt Lake City metro attracts cloud operators seeking geographic diversity for disaster recovery architectures. Rocky Mountain Power manages interconnection timelines under Utah Public Service Commission oversight. West Valley City and Bluffdale host expanding campus developments leveraging cool ambient temperatures for free cooling economization.
United States (US) Data Center Construction Market Competitive Landscape
Premium-margin players sit above commodity-margin players across mission-critical construction expertise, with design-build specialists commanding forty percent contracting premiums over generalist commercial builders. The contractor base fragments into two non-overlapping tiers: hyperscale specialists delivering 300+ watts per square foot densities and enterprise-grade builders serving legacy power requirements. Three archetypes dominate: integrated project delivery firms, design-build mission-critical specialists, and sustainability-led contractors targeting net-zero operational facilities. Capacity expansion and risk-sharing mechanism adoption constitute the dominant competitive moves reshaping procurement relationships.
Within the mission-critical specialist tier, Turner Construction and DPR Construction exemplify design-build scale advantages for cloud operator engagements. Turner Construction anchors premium-tier positioning through compressed commissioning timelines for hyperscale facilities. DPR Construction occupies a position within integrated project delivery models that align designer and builder incentives across multi-gigawatt campuses. Skanska USA represents the sustainability-led archetype, targeting net-zero operational protocols that satisfy EPA emissions constraints and corporate renewable energy commitments.
| Leading Market Players |
|---|
| AECOM |
| Turner Construction |
| DPR Construction |
| Holder Construction |
| Skanska USA |
| Fortis Construction |
| Kiewit Corporation |
| Clayco |
| Gensler |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators concentrating procurement through multi-gigawatt campus awards command premium design-build rates while compressing payment terms for electrical-mechanical contractors. This buyer concentration anchors value-based contracting tied to concurrent maintainability certification and compressed commissioning timelines rather than cost-plus arrangements.
Pricing Analysis
Uptime certification levels anchor value-based pricing tiers across mission-critical construction engagements. Tier 3 concurrent maintainability specifications command forty percent contracting premiums over Tier 2 builds due to extended warranty obligations and specialized labor requirements. Cost compression in enterprise-grade segments intensifies as generalist commercial builders enter legacy density facilities. Cloud hyperscalers exhibit least price sensitivity, prioritizing schedule certainty over unit cost minimization.
Supply Chain Analysis
Freight costs for medium-voltage switchgear and prefabricated electrical skids from Mexico and Southeast Asia amplify total landed cost volatility. Domestic data center construction draws from transformer manufacturing concentrated in Mexico, China, and South Korea, with copper busway and lithium-ion battery cells resting on East Asian production clusters. Single-source vulnerability for 480-volt distribution equipment creates procurement risk. Distribution runs through direct OEM relationships with hyperscale operators and tier-one electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as contractors pursue captive control over prefabricated electrical-mechanical module production to capture margin pools and compress delivery timelines.
For Market Incumbents: Deploy design-build scale advantages to secure multi-year hyperscale master service agreements before integrated project delivery models commoditize mission-critical expertise. Consolidate specialized liquid cooling contractor networks to preempt scarcity-driven wage inflation. Threat of modular data center manufacturers backward-integrating into field installation services pressures traditional construction margins. For New Entrants and Emerging Players: Digital channel routes through cloud marketplace procurement platforms offer lower customer acquisition friction than traditional RFP processes. White-space targets include waste heat recovery system integration for district heating applications and small modular reactor colocation project development. Most penetrable segment: Tier 2 enterprise colocation in Columbus and Salt Lake City secondary markets lacking incumbent design-build relationships. For Investors and Strategic Acquirers: The window for entry favors prefabrication specialists with factory-integrated power module capabilities and established utility interconnection relationships. Long-term viability hinges on positioning ahead of nuclear power colocation and liquid cooling standardization inflections. Signal to watch: Department of Energy permitting acceleration for advanced reactor deployments at industrial facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Facility Investment | Factory-integrated power modules compress on-site schedules and reduce commissioning risk for hyperscale cloud operators. |
| Liquid Cooling Expertise Acquisition | Direct-to-chip installation capabilities address AI cluster density requirements constraining scalable deployment. |
| Utility Interconnection Partnership | Early engagement with Dominion Energy and ERCOT streamlines study timelines exceeding three thousand megawatts. |
| Renewable PPA Structuring | Sleeved agreements with hourly carbon matching satisfy corporate sustainability officer additionality demands. |
| Nuclear Colocation Site Development | Adjacent small modular reactor positioning secures dedicated baseload power for multi-gigawatt campuses. |
Research Methodology
SEC 10-K filings, FERC interconnection queue databases, and EPA air quality permit records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with data center development executives, mission-critical construction project managers, utility interconnection planners, and electrical-mechanical procurement leads validated demand assumptions and pricing dynamics. Bottom-up project pipeline aggregation triangulated against top-down hyperscaler capex disclosure analysis.
Bottom-up modeling segmented construction value across Tier 1 through Tier 3 facilities, modular deployments, and power source configurations over the projection horizon. CAGRs derived from weighted average of disclosed project timelines and utility interconnection completion curves. Industry-specific forecast inputs included PJM and ERCOT queue progression rates, Inflation Reduction Act tax credit capture assumptions, and Uptime Institute certification issuance velocity.
The model holds under stable utility commission staffing and transformer supply normalization; deviation in grid interconnection study delays or trade policy shifts would shift completion timelines. Forecasts reflect these assumptions without contingency buffers for regulatory acceleration or supply chain disruption. Stakeholders should weight assumptions against their own operating context and regional utility relationships.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
North America Data Center Server Market