
 Europe Data Center Market | 2026-2036
Europe Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Market Analysis
France is reshaping competitive dynamics through aggressive renewable-powered campus development near Paris and Marseille. Vantage Data Centers leverages vertical integration to control land, power, and construction timelines across multiple European metros. Microsoft Corporation anchors its position through sustained hyperscale build-outs aligned with carbon-negative commitments. Equinix differentiates via interconnection density and carrier-neutral positioning in financial and cloud exchange nodes.
Europe data centers constitute specialized facilities housing compute, storage, and networking infrastructure for enterprise and consumer digital services, typically operating within power densities of 10–50 kW per rack and requiring precision cooling to maintain 18–27°C ambient thresholds. Hyperscale deployments dominate capital allocation as cloud providers internalize server, storage, and network fabric design. Colocation maintains margin resilience through multi-tenant economics and cross-connect revenue streams. Edge infrastructure is gaining structural attention from telecom operators seeking distributed latency reduction for 5G and IoT workloads.
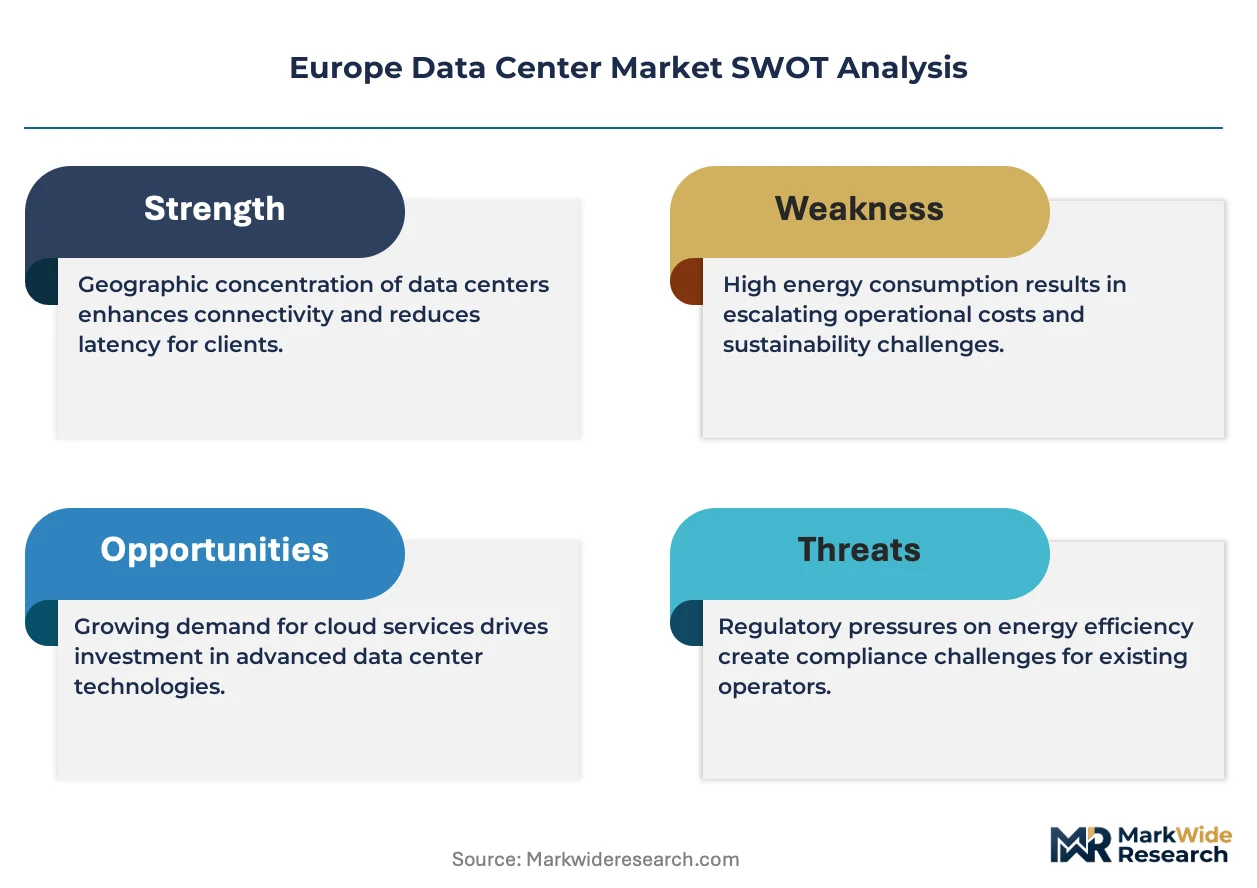
The EU Energy Efficiency Directive and national building codes enforce power usage effectiveness reporting and waste heat recovery mandates, while ECHA REACH restrictions govern flame-retardant materials in cable and enclosure systems. The EU AI Act introduces tiered compliance obligations for training infrastructure above specified compute thresholds, redirecting facility investment toward certified GPU clusters. Stakeholders must monitor evolving grid interconnection queues and carbon border adjustment mechanisms as determinants of site selection economics.
Market Dynamics
Hyperscale cloud operators are internalizing infrastructure design and construction timelines, compressing traditional colocation procurement cycles and forcing facility operators to restructure power contracting and land acquisition strategies across the continent.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates for power usage effectiveness reporting and waste heat recovery are accelerating facility modernization investments and creating retrofit demand across existing campuses.
- AI training clusters:The EU AI Act's tiered compliance obligations for compute-intensive infrastructure are redirecting capital toward certified GPU-ready facilities with enhanced cooling density.
- Grid interconnection queues:Proactive land and substation reservations by operators in Germany, Ireland, and the Netherlands are securing multi-hundred-megawatt power allocations before competing industrial loads.
Market Restraints
- Copper and electrical steel volatility:Transformer lead times extending beyond 24 months are freezing project timelines and inflating balance-of-plant costs for new builds.
- ECHA REACH restrictions:Flame-retardant material compliance is eliminating certain cable specifications from approved vendor lists and forcing enclosure redesigns.
- On-premise enterprise retention:Financial services and defense sectors maintaining captive server rooms are limiting colocation addressable market expansion in security-sensitive verticals.
Strategic Opportunities
- Nordic expansion:Norway and Sweden offer sub-50ms latency to continental Europe with abundant hydroelectric power and free-air cooling potential for compute-intensive workloads.
- Liquid cooling convergence:Integration of direct-to-chip and immersion systems with existing chilled-water infrastructure enables 100+kW rack densities without full facility reconstruction.
- Carbon border adjustment mechanisms:Upcoming EU carbon pricing on imported electricity is incentivizing renewable power purchase agreements with long-term price certainty.
Industry Challenges
- Critical facilities engineering talent:Shortages of professionals certified in Tier III/IV design and commissioning are extending project delivery timelines and inflating labor costs.
- Legacy mechanical interoperability:Integrating advanced economizer and heat wheel systems with existing raised-floor cooling architectures requires complex controls engineering and downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Market |
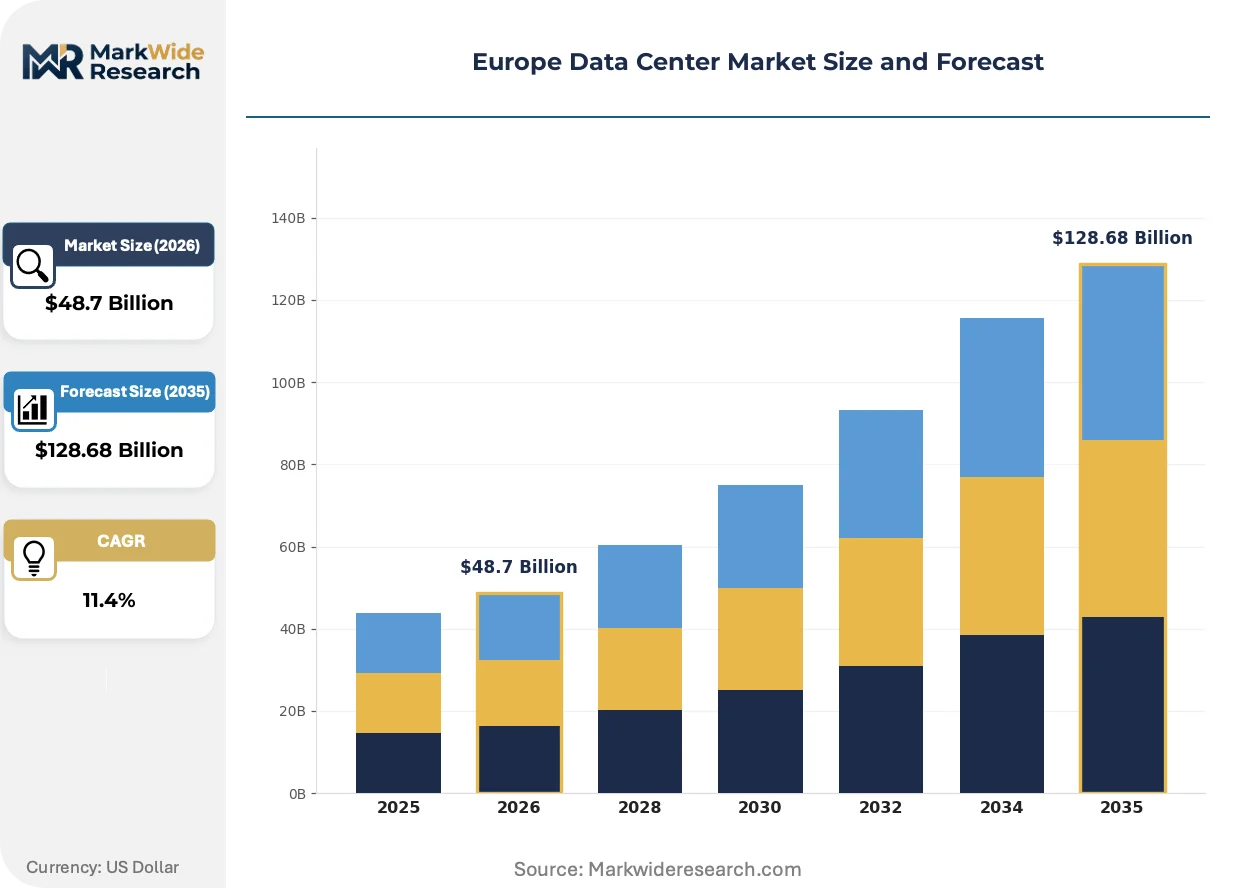
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyperscale, Colocation, Edge, Enterprise Installation Type: Modular, Traditional, Containerized, Hybrid Service Type: Managed Services, Cloud Services, Disaster Recovery, Colocation Services End User: IT & Telecom, BFSI, Healthcare, Government |
| Companies Covered | Vantage Data Centers, Microsoft Corporation, Digital Realty, Iron Mountain, Google, Equinix, Amazon Web Services, Start Campus, NTT Global Data Centers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Market Emerging Trajectories
Facility architecture is converging around modular power and cooling blocks that decouple infrastructure scaling from building construction, enabling faster deployment and reducing stranded asset risk as workload densities evolve.
Immersion cooling using engineered dielectric fluids is collapsing the thermal management footprint for AI training clusters. Hyperscale operators in Frankfurt and Amsterdam are piloting two-phase immersion for 50+kW GPU racks. This technology is collapsing the traditional chilled-water infrastructure investment required per megawatt of IT load.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with aggressive GWP reduction targets. Facility operators must transition to natural refrigerants or low-GWP synthetics for cooling systems. Germany and France are seeing accelerated ammonia and CO2 chiller deployments as compliance deadlines approach.
Enterprise procurement is compressing contract durations from traditional ten-year terms toward five-year agreements with renewal options. Colocation providers in London and Dublin are responding with modular pricing structures that separate power, space, and cross-connect components. Financial services buyers are driving this shift to preserve flexibility for cloud migration timelines.
Europe Data Center Market Segmentation
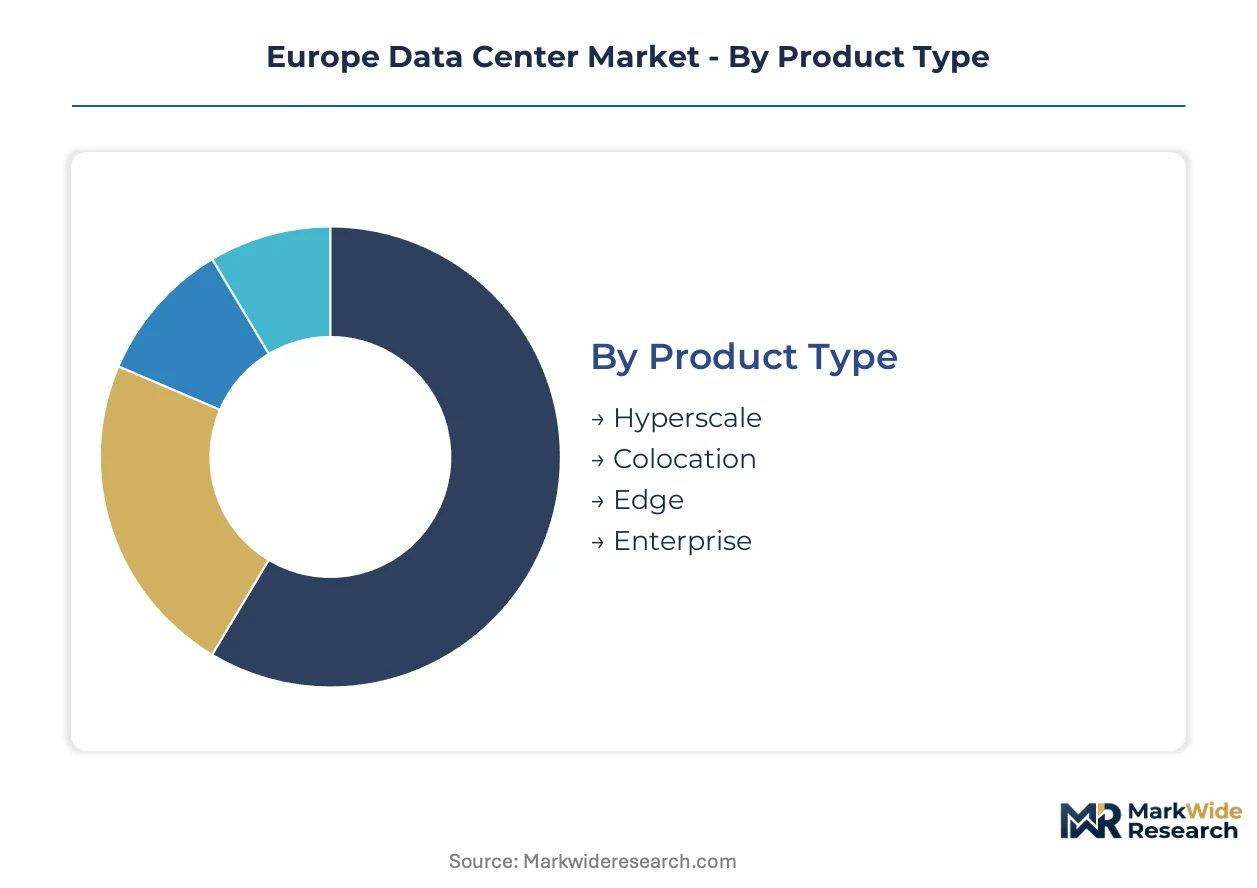
Segmentation reveals how capital allocation, facility design, and procurement patterns diverge across deployment models and customer requirements. Distinct operational economics govern hyperscale builds versus multi-tenant colocation versus distributed edge infrastructure.
Product Type:
Cost tier differentiates facility investment intensity, with hyperscale deployments commanding the largest capital commitments and edge infrastructure operating at leaner unit economics.
- Hyperscale:Single-tenant facilities exceeding 15 MW designed for cloud providers' proprietary server, storage, and network fabric. Microsoft Corporation and Amazon Web Services are concentrating new builds in Germany, Ireland, and the Netherlands to secure renewable power allocations ahead of industrial competitors.
- Colocation:Multi-tenant data centers where operators lease space, power, and cooling to enterprises and cloud providers. Equinix and Digital Realty are expanding interconnection density in Frankfurt, London, and Amsterdam financial exchange nodes to capture cross-connect revenue streams.
- Edge:Distributed facilities under 1 MW positioned for sub-10ms latency to end users. Telecom operators in France and Spain are deploying these for 5G network functions and IoT aggregation.
- Enterprise:Captive facilities owned and operated by single organizations for internal workloads. Financial services firms in Switzerland and defense contractors in the UK maintain these for data sovereignty compliance.
Hyperscale commands the established base. The steepest expansion runs through Edge.
Installation Type:
Deployment speed and asset flexibility separate modular approaches from permanent construction, with hybrid configurations gaining traction for phased capacity expansion.
- Modular:Prefabricated power and cooling blocks factory-assembled and site-integrated. Vantage Data Centers deploys these across European metros to compress construction timelines and reduce stranded asset risk as GPU densities evolve.
- Traditional:Stick-built facilities with permanent mechanical and electrical infrastructure. Established operators in Frankfurt and London retain these for long-term lease commitments from enterprise tenants.
- Containerized:Self-contained IT and infrastructure modules for rapid deployment or remote locations. Mining and oil exploration firms in Norway use these for temporary compute clusters.
- Hybrid:Combinations of permanent core infrastructure with modular expansion pods. New projects in Marseille and Milan adopt this to phase capital deployment against actual demand uptake.
Traditional installations hold the incumbent position. Modular approaches are climbing the fastest.
Service Type:
Customer relationship depth and margin structure vary by service tier, with managed services capturing higher value per rack than pure space-and-power leasing.
- Managed Services:Operators assume responsibility for server administration, patching, and monitoring. Banks in Frankfurt and healthcare networks in Copenhagen procure these to internalize operational burden without building captive facilities.
- Cloud Services:Direct infrastructure-as-a-service or platform-as-a-service offerings from data center operators. STACK Infrastructure and CyrusOne are layering these atop wholesale colocation in Amsterdam and Dublin.
- Disaster Recovery:Secondary site provisioning for business continuity with defined recovery time objectives. Insurance and reinsurance firms in Luxembourg and Zurich contract these under regulatory pressure.
- Colocation Services:Space, power, cooling, and physical security without operational management. Retail and mid-market enterprises in Madrid and Milan favor this for cost control.
Colocation Services anchor current revenue. Managed Services show the steepest margin expansion trajectory.
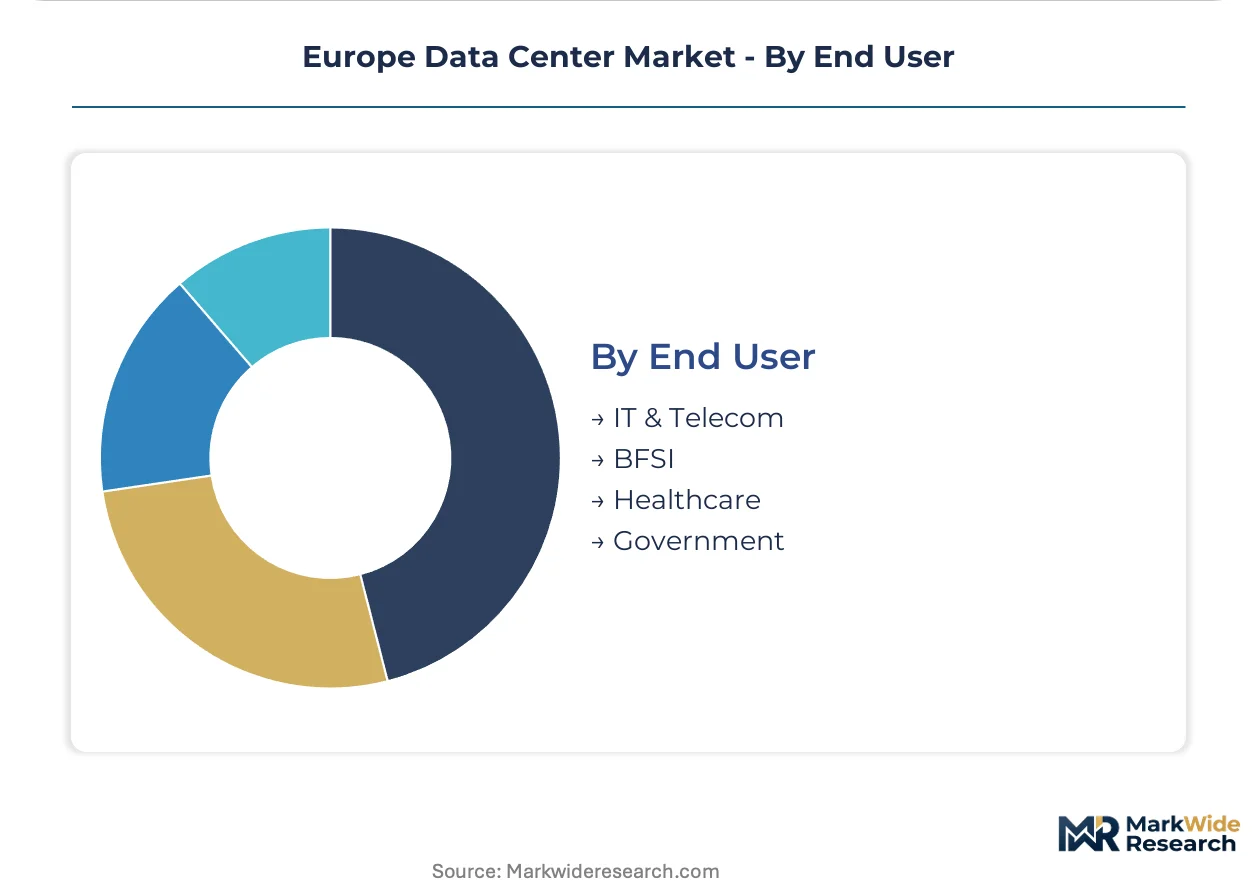
End User:
Vertical-specific compliance requirements and latency sensitivity reshape facility specifications, with financial services and healthcare imposing the most stringent operational constraints.
- IT & Telecom:Cloud providers, content delivery networks, and mobile network operators. These buyers in Germany and the Netherlands are driving 100+ kW rack densities for AI training clusters under the EU AI Act's tiered compliance framework.
- BFSI:Banks, insurers, and payment processors with regulatory mandates for data residency and operational resilience. Frankfurt and Zurich facilities serve these under ECB and FINMA supervision requirements.
- Healthcare:Hospital systems, pharmaceutical research, and medical device manufacturers. EMA clinical trial data hosting rules and GDPR health data provisions govern their procurement in Denmark and the Netherlands.
- Government:National and EU-level public sector workloads. NATO and defense ministries in Belgium and the UK require cleared personnel and air-gapped infrastructure.
IT & Telecom dominates capacity absorption. Healthcare is gaining share fastest as genomic and imaging workloads expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bundesnetzagentur grid interconnection rules in Germany anchor capacity deployment decisions across the continent, with national regulators in Ireland, the Netherlands, and France shaping secondary site selection through renewable energy mandates and building code enforcement.
Germany
Frankfurt's financial exchange proximity and Frankfurt Rhine-Main fiber density attract hyperscale cloud builds for AI training clusters. The Federal Network Agency enforces grid stability standards that extend substation commissioning timelines to 36 months in some districts. Vantage Data Centers and Microsoft Corporation are securing land parcels in Offenbach and Hanau to bypass central Frankfurt power constraints.
Ireland
Dublin's sub-10ms latency to London and Amsterdam underpins its role as a transatlantic cable landing hub. EirGrid's data center connection policy caps new power allocations in the capital region until 2028, redirecting investment toward Athenry and Dundalk. Amazon Web Services and Microsoft Corporation hold reserved substation capacity in these secondary markets.
Netherlands
Amsterdam's AMS-IX internet exchange density sustains carrier-neutral colocation demand from financial services buyers. The Dutch Data Center Association's covenant with TenneT mandates waste heat reuse for district heating networks in metropolitan zones. Digital Realty and Equinix are retrofitting existing facilities with liquid cooling infrastructure to serve GPU-intensive workloads.
France
Marseille's submarine cable landing stations and Paris-Saclay research cluster create dual demand poles for compute infrastructure. ANSM and CNIL data residency requirements for health and financial data restrict certain workload placement to certified facilities. Start Campus is developing renewable-powered campuses in both metros with direct high-voltage grid connections.
Europe Data Center Market Vendor Landscape
Hyperscale operators and colocation specialists split the market into distinct procurement ecosystems with limited customer overlap. Facility ownership concentrates among REIT-structured operators and captive cloud infrastructure divisions, creating tiered access to power and land. Three archetypes dominate: vertically integrated hyperscale builders, interconnection-focused colocation platforms, and emerging GPU-cluster specialists. Capacity expansion and renewable power contracting represent the dominant competitive moves, with land banking in constrained grid zones serving as a secondary battleground.
Within the hyperscale builder tier, Vantage Data Centers exemplifies vertical control over development timelines, while Microsoft Corporation anchors cloud-provider captive infrastructure strategies. Among interconnection specialists, Equinix occupies a position defined by carrier-neutral exchange density in financial hub markets.
| Leading Market Players |
|---|
| Vantage Data Centers |
| Microsoft Corporation |
| Digital Realty |
| Iron Mountain |
| Equinix |
| Amazon Web Services |
| Start Campus |
| NTT Global Data Centers |
| Others |
Supply Flow & Price Mechanics
Tight capacity in Frankfurt and Amsterdam is compressing supplier margins while amplifying pricing power for operators holding reserved substation allocations. This utilization squeeze simultaneously accelerates long-term power purchase agreements and forces retroactive contract renegotiations across multi-tenant facilities.
Pricing Analysis
Power pricing spreads of 40-60% separate Nordic hydroelectric zones from constrained German grid nodes. Colocation contracts stratify across premium certified tiers, standard commercial grades, and economy wholesale blocks, with certification under the EU AI Act's compute thresholds commanding substantial uplifts. Cost compression in standard-tier leasing is intensifying because hyperscale cloud operators are internalizing construction and bypassing traditional procurement channels. Financial services buyers exhibit the lowest price sensitivity due to regulatory mandates, while retail and mid-market enterprises drive aggressive negotiation on per-kW rates.
Supply Chain Analysis
Export controls on advanced GPU and AI accelerator chips under US Commerce Department restrictions are fragmenting equipment procurement channels across European build-outs. Supply concentrates in Taiwan for advanced semiconductors, Germany for precision cooling components, and China for electrical steel and copper processing. Transformer lead times, dielectric fluid formulations, and specialized cable assemblies constitute critical input dependencies. Single-source vulnerability runs through Taiwanese foundry capacity for high-performance compute silicon. Distribution runs through direct OEM relationships for hyperscale operators and tiered distributor networks for mid-market colocation procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals certified in Tier III/IV design and commissioning is constraining expansion timelines and inflating project delivery costs across the continent. This capability gap separates operators who can secure talent from those facing extended commissioning delays.
For Market Incumbents: Entrench position by securing multi-hundred-megawatt land and substation reservations in constrained grid zones before industrial competitors queue. Deepen backward integration into modular power and cooling block manufacturing to compress construction timelines and reduce exposure to transformer lead time volatility. Prioritize certification investment under the EU AI Act's tiered compliance framework to capture premium pricing from GPU-intensive workloads.
For New Entrants and Emerging Players: Build out presence in secondary Nordic markets where abundant hydroelectric capacity and free-air cooling potential offset latency disadvantages for batch compute workloads. Target the distributed edge segment in France and Spain where telecom operators are deploying sub-1MW facilities for 5G network functions with less incumbent saturation. Pursue joint development agreements with municipal utilities to secure renewable power allocations ahead of queue-based allocation systems.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-ready facilities with liquid cooling infrastructure and direct high-voltage grid connections. Long-term viability favors operators with secured power pipelines and demonstrated commissioning velocity rather than speculative greenfield positions. Acquisition target archetype: mid-scale regional operators holding reserved substation capacity in constrained markets with retrofit-ready mechanical infrastructure. Monitor grid interconnection queue lengths in Germany and Ireland as the critical inflection signal for capacity scarcity pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Long-term price certainty under EU carbon border adjustment mechanisms secures margin visibility for hyperscale builds. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip and immersion systems enable 100+ kW rack densities required for EU AI Act certified GPU clusters. |
| Land and Substation Banking | Proactive reservations in Offenbach, Hanau, and Athenry bypass central Frankfurt and Dublin power constraints. |
| Waste Heat Recovery Integration | District heating network connections under Dutch Data Center Association covenants unlock regulatory compliance and revenue streams. |
| Modular Power Block Manufacturing | Factory-assembled infrastructure decouples scaling from building construction and reduces stranded asset risk. |
Methodological Framework
Cross-validation between hyperscaler capital expenditure disclosures and EPC contractor project pipelines anchors the qualitative findings. Primary interviews with data center development executives, critical facilities engineering directors, utility interconnection planners, and colocation procurement officers combined with secondary validation from Bundesnetzagentur grid filings, EirGrid connection policy documents, TenneT capacity allocation records, and SEC 10-K infrastructure disclosures. Bottom-up project aggregation and top-down market sizing triangulate volume estimates across deployment models.
Calibration against historical commissioning timelines and power contracting patterns informs the projection framework. Segmentation dimensions modeled include facility scale tier, cooling architecture type, service relationship depth, and end-user vertical with regional regulatory cluster overlays. CAGRs derive from capacity absorption rates, power allocation trajectories, and workload density evolution across the analysis window. Forecast inputs incorporate grid interconnection queue dynamics, EU Energy Efficiency Directive compliance cost curves, and AI training cluster deployment schedules.
Practitioners should monitor grid stability standard revisions, F-Gas Regulation phase-down deadlines, and carbon border adjustment implementation schedules for early signals requiring forecast reassessment. Cross-checking against EIA international energy data and IEA power system transformation benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
GPU Database Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Chile Data Center Networking Market