
 South Africa Data Center Server Market | 2026-2036
South Africa Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Server Market Insights
Hyperscale cloud providers are reorganizing procurement patterns across the South Africa data center landscape, displacing traditional enterprise direct-buy as the dominant demand archetype. Dell Inc. leverages its direct sales infrastructure to sustain channel control among large enterprise accounts in Johannesburg. Hewlett Packard Enterprise competes through specialized edge-to-core server portfolios targeting financial services workloads. Huawei Technologies Co., Ltd. anchors its position via aggressive pricing on rack and blade configurations for telecommunications operators.
A data center server is a high-performance computing device engineered with multi-socket processors, error-correcting memory, and redundant power supplies, designed to process, store, and distribute data across networked environments with 99.999% uptime requirements. Rack servers dominate installed capacity due to standardized form factors that maximize floor space efficiency in colocation facilities. Blade servers represent the fastest-expanding product category as hyperscalers pursue density-optimized deployments that reduce per-rack cabling complexity. Liquid-cooled configurations are capturing margin pools as power densities exceed 30 kilowatts per rack and NERSA tariff structures penalize inefficient thermal management.
South Africa's National Energy Regulator enforces electricity licensing conditions that directly shape data center site selection and cooling technology adoption, while the country's national standards body (SABS) mandates electromagnetic compatibility certification for all imported server equipment. The Independent Communications Authority of South Africa (ICASA) spectrum allocations influence edge server deployment patterns by determining wireless backhaul economics for distributed facilities. Stakeholders must monitor NERSA's embedded generation licensing reforms, as on-site solar and battery co-location rights will determine whether Cape Town or Gauteng emerges as the preferred server deployment corridor.

Market Dynamics
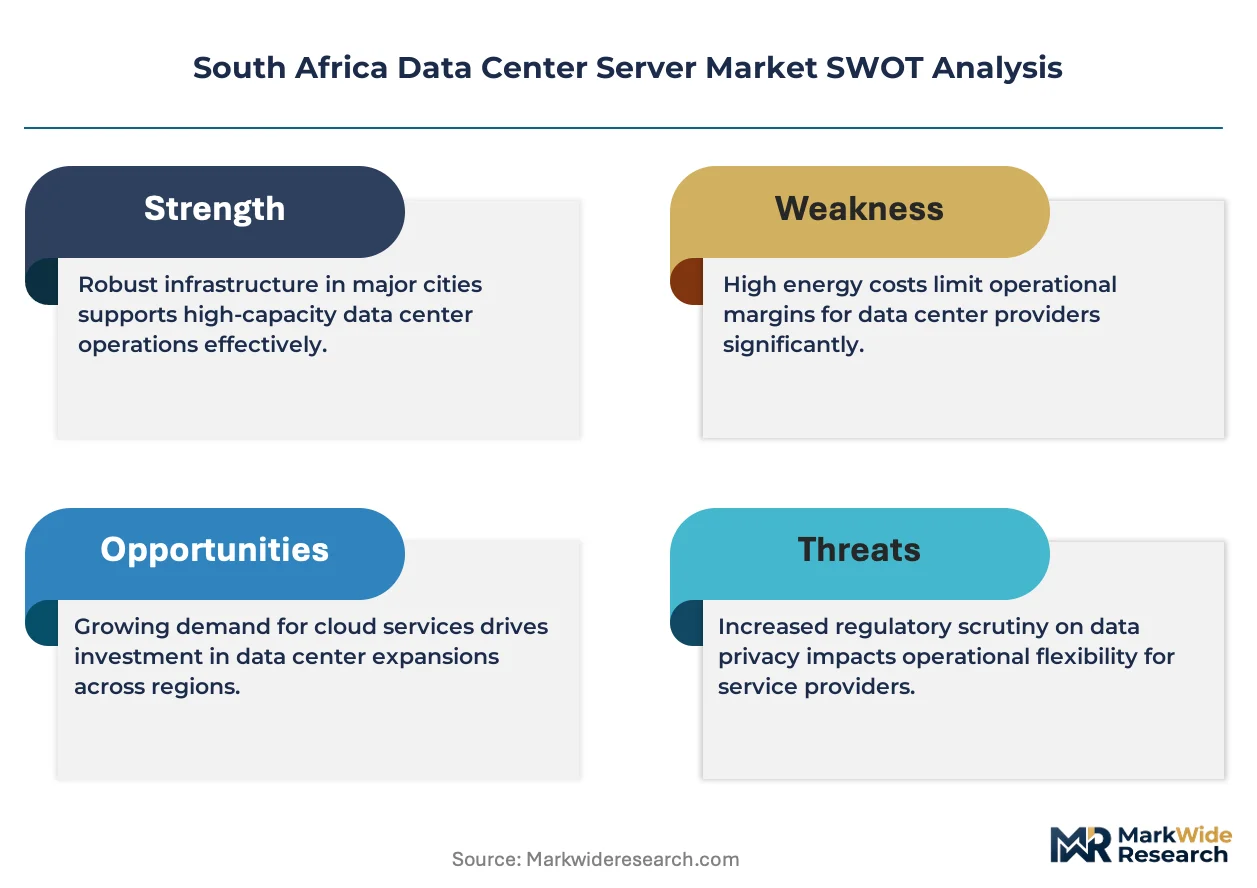
NERSA's embedded generation licensing reforms are restructuring capital deployment patterns across South Africa's data center corridor, forcing operators to co-locate solar and battery assets with server infrastructure or face escalating tariff penalties.
Growth Catalysts
- Submarine cable landings:Cape Town's landing stations for Equiano and 2Africa cables are concentrating hyperscaler demand in the Western Cape corridor, driving rack server procurement from international cloud operators.
- Liquid cooling mandates:NERSA electricity pricing reforms penalize inefficient thermal management above 30 kilowatts per rack, accelerating adoption of direct-to-chip and immersion cooling architectures.
- Financial services cloud migration:Johannesburg-based banks and insurers are reorganizing infrastructure procurement toward cloud-adjacent server deployments, creating sustained demand for edge-to-core configurations.
Market Restraints
- Import certification delays:SABS electromagnetic compatibility testing creates 12-16 week lead times for server equipment entering South African ports, compressing deployment windows for time-sensitive hyperscale builds.
- Grid instability:Eskom's load-shedding schedule forces operators to oversize on-site generation capacity, inflating capex requirements and extending payback periods for colocation investments.
- Skills concentration:Certified data center engineers cluster in Gauteng and Western Cape provinces, creating talent scarcity for facilities in secondary markets like KwaZulu-Natal and Eastern Cape.
Strategic Opportunities
- Free State renewable corridor:Abundant land and solar irradiance in the Free State province offer greenfield sites for solar-powered hyperscale campuses, though transmission infrastructure remains underdeveloped.
- Edge server wireless backhaul:ICASA's spectrum allocations for 5G mid-band are enabling distributed edge facilities in mining and logistics corridors previously unserved by fiber.
- Blade server density optimization:Hyperscalers pursuing per-rack cabling reduction are creating margin pools for integrated blade chassis with shared power and cooling infrastructure.
Industry Challenges
- Legacy facility retrofitting:Johannesburg's aging enterprise data centers require structural reinforcement and power upgrades to support liquid-cooled racks above 50 kilowatts, triggering complex landlord-tenant negotiations.
- Skills pipeline gaps:South Africa's technical vocational institutions produce insufficient numbers of certified HVAC technicians and electrical engineers specialized in high-density compute environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Server Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,330.58 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Hybrid Servers Service Type: Managed Services, Colocation Services, Professional Services, Support Services Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud Cooling Technology: Air-Cooled, Liquid-Cooled, Immersion Cooling, Rear Door Heat Exchangers |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, Lenovo Group Limited, Huawei Technologies Co., Ltd., International Business Machines Corp., Cisco Systems Inc., Fujitsu, Inspur Group, Atos SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Server Market Trends and Innovations
Server architecture is fragmenting into workload-optimized configurations as power density requirements exceed the thermal limits of traditional air-cooled designs, forcing a wholesale rethinking of facility engineering.
Blade server enclosures with shared midplane infrastructure are decomposing the traditional rack-and-stack deployment model. Hyperscalers operating Cape Town facilities are adopting these configurations to halve per-rack cabling complexity and reduce installation labor. The structural consequence is compressing margins for system integrators previously capturing value through custom integration services.
NERSA's time-of-use tariff restructuring is mandating thermal storage and load-shifting capabilities for facilities above 10 megawatts. Operators must now engineer cooling systems that pre-chill thermal masses during off-peak hours, adding mechanical complexity but reducing electricity costs by 18-24 percent. Large colocation providers in Johannesburg are responding by contracting directly with independent power producers to bypass municipal distribution tariffs.
Hyperscaler procurement teams are consolidating server purchasing through direct manufacturer relationships, marginalizing traditional value-added distributors. Enterprise buyers in South Africa's financial sector increasingly specify workload-optimized configurations rather than standard catalog SKUs, forcing channel partners to restructure around technical presales and managed services. This behavioral shift is most visible in Gauteng, where three major banks have established direct supply agreements with original equipment manufacturers for their private cloud infrastructure.
South Africa Data Center Server Market Segmentation
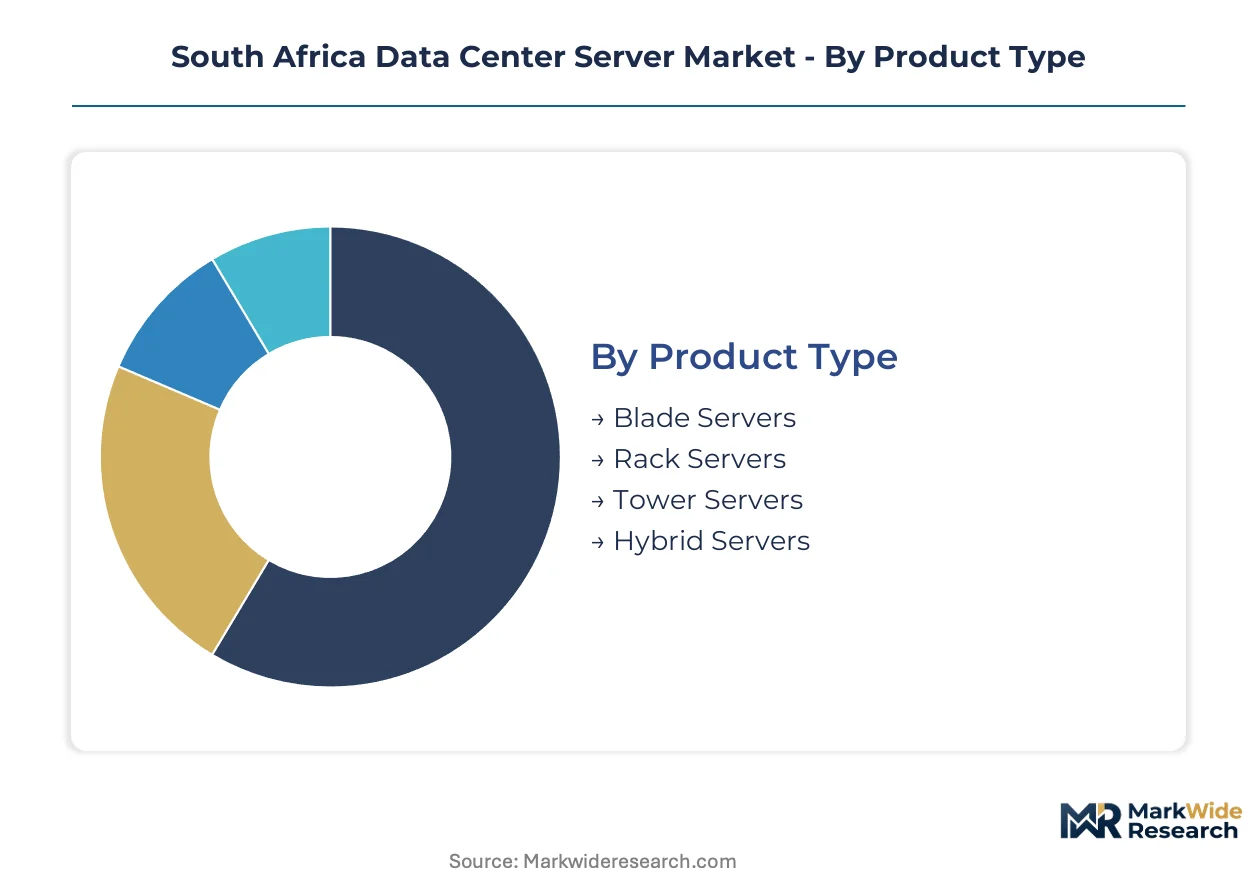
Server procurement patterns in South Africa diverge sharply across deployment configurations, with NERSA electricity pricing and ICASA spectrum policy creating distinct margin structures for each segment. Understanding these fault lines enables targeted positioning across Johannesburg financial services clusters and Western Cape hyperscaler corridors.
Product Type:
NERSA's embedded generation licensing reforms and tariff penalties above 30 kilowatts per rack are fragmenting server procurement by thermal envelope and density requirements.
- Rack Servers:Standardized 19-inch form factors with multi-socket x86 architectures dominate installed capacity across Johannesburg enterprise facilities. NERSA's time-of-use tariffs favor these configurations in legacy air-cooled environments where power densities stay below regulatory thresholds.
- Blade Servers:Shared midplane infrastructure with integrated power and cooling delivers maximum compute per square meter. Cape Town hyperscalers pursuing Equiano cable connectivity are standardizing on these enclosures to minimize per-rack cabling and installation labor.
- Tower Servers:Standalone vertical chassis serve remote branch offices and small enterprise deployments in secondary cities lacking colocation infrastructure.
- Hybrid Servers:Modular architectures supporting mixed workload types address mid-market buyers seeking gradual cloud migration paths without full infrastructure replacement.
Established volume favors rack servers; emerging adoption favors blade servers.
Service Type:
Customer capex constraints and Eskom load-shedding risks are shifting procurement toward operational expenditure models with embedded resilience guarantees.
- Managed Services:End-to-end infrastructure operation including remote monitoring, patch management, and capacity planning. Johannesburg banks facing Basel III operational risk requirements are outsourcing server lifecycle management to specialized providers.
- Colocation Services:Wholesale and retail space with redundant power and cross-connect options. Western Cape facilities near Cape Town cable landings command premium pricing for international cloud operators requiring low-latency African connectivity.
- Professional Services:Migration consulting, workload assessment, and architecture design support enterprise transitions from legacy three-tier infrastructure.
- Support Services:Break-fix contracts and spare parts logistics address skills scarcity in KwaZulu-Natal and Eastern Cape provinces where certified engineers cluster in Gauteng and Western Cape.
Margin concentration sits with managed services; volume expansion tracks colocation.
Deployment Model:
Financial services regulatory scrutiny and data sovereignty requirements are bifurcating procurement between controlled private infrastructure and elastic cloud capacity.
- Private Cloud:Dedicated virtualized infrastructure with single-tenant isolation. South African Reserve Bank prudential guidelines on critical system resilience are sustaining demand among Johannesburg-tier banks and insurers.
- Hybrid Cloud:Orchestrated workloads spanning on-premises and hyperscaler capacity. Three major Gauteng banks have established direct OEM supply agreements for these configurations to maintain audit trail continuity.
- On-Premises:Traditional owned-and-operated server rooms persist in mining and logistics corridors with unreliable fiber backhaul.
- Public Cloud:Shared hyperscaler infrastructure serves development environments and non-regulated workloads with elastic scaling requirements.
Compliance mandates anchor private cloud; cost optimization drives hybrid expansion.
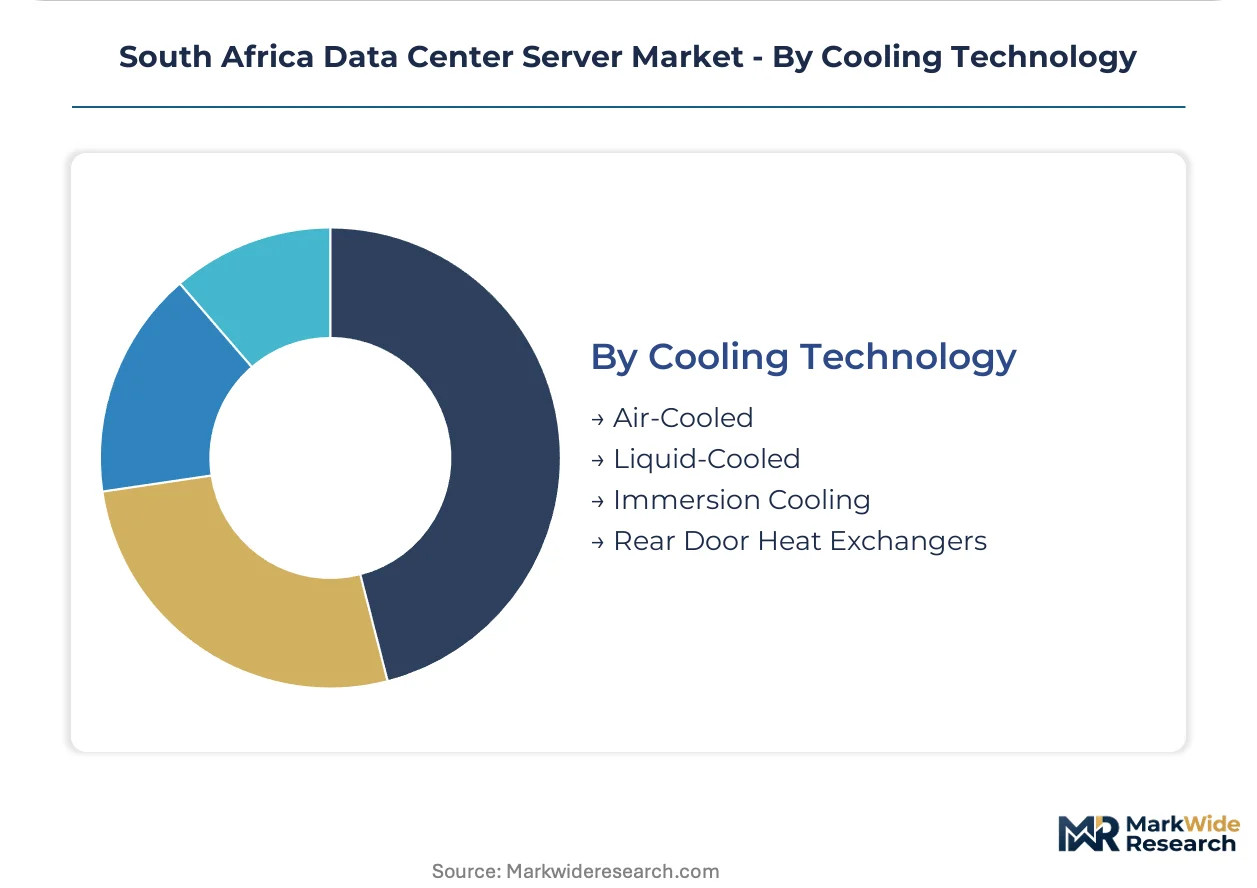
Cooling Technology:
Thermal management selection now determines facility economics under NERSA's revised tariff structures penalizing inefficient designs.
- Liquid-Cooled:Direct-to-chip or cold plate architectures removing heat at the processor package. Facilities above 10 megawatts in Johannesburg are retrofitting for these systems to avoid NERSA penalties on racks exceeding 30 kilowatts with air cooling.
- Air-Cooled:Conventional raised-floor designs with computer room air handlers dominate legacy installed base. SABS certification delays and structural reinforcement costs are trapping operators in these configurations despite rising operating expenses.
- Immersion Cooling:Dielectric fluid submersion of entire server assemblies enables densities above 50 kilowatts per rack. Free State greenfield developments are piloting these systems for solar-powered hyperscale campuses.
- Rear Door Heat Exchangers:Passive or active door-mounted cooling coils offer incremental retrofit options for existing rack infrastructure without full facility redesign.
Regulatory pressure accelerates liquid-cooled; budget constraints prolong air-cooled.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler procurement teams concentrate in Western Cape corridor facilities near submarine cable landings, while Johannesburg financial services clusters sustain enterprise server demand through private cloud migrations.
Western Cape
Cape Town's submarine cable landing stations for Equiano and 2Africa cables anchor hyperscaler demand in this corridor. NERSA's embedded generation licensing reforms favor facilities co-locating solar assets with server infrastructure. Stellenbosch and Paarl sub-regions are attracting greenfield developments for liquid-cooled hyperscale campuses.
Gauteng
Johannesburg-based banks and insurers drive procurement of edge-to-core server configurations for cloud-adjacent deployments. South African Reserve Bank prudential guidelines on critical system resilience sustain private cloud investments. Midrand and Centurion industrial zones concentrate colocation facilities serving financial services workloads.
KwaZulu-Natal
Durban's port logistics and manufacturing base generates demand for tower servers in branch office deployments lacking fiber backhaul. ICASA spectrum allocations for 5G mid-band are enabling distributed edge facilities in mining corridors. Skills scarcity for certified data center engineers constrains facility expansion outside eThekwini metro.
Free State
Abundant land and solar irradiance offer greenfield sites for solar-powered hyperscale campuses targeting carbon-neutral server operations. Transmission infrastructure underdevelopment limits grid-connected capacity. Bloemfontein and Sasolburg sub-regions are piloting immersion cooling systems for densities above 50 kilowatts per rack.
Eastern Cape
Gqeberha's automotive manufacturing and Coega Industrial Development Zone anchor enterprise server demand for industrial IoT workloads. SABS electromagnetic compatibility certification delays compress deployment windows for imported equipment. Nelson Mandela Bay metro lacks certified engineer concentration found in Gauteng and Western Cape.
South Africa Data Center Server Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with direct sales infrastructure and telecommunications-focused hardware specialists. Market structure exhibits tiered consolidation with three to four vendors capturing hyperscale procurement and a fragmented long tail serving mid-market enterprise accounts. Strategic archetypes include direct-sales infrastructure incumbents, edge-to-core workload optimizers, and price-aggressive telecommunications suppliers. Dominant competitive moves center on bypassing traditional distribution channels through direct OEM agreements and retrofitting legacy facilities for liquid-cooled density thresholds.
Among diversified technology conglomerates, Dell Inc. and Hewlett Packard Enterprise occupy positions exemplifying direct-sales infrastructure control and specialized workload portfolio breadth respectively. Huawei Technologies Co., Ltd. represents the telecommunications-focused hardware specialist archetype with aggressive positioning on rack and blade configurations. These three companies anchor the competitive landscape across Johannesburg enterprise accounts and Western Cape hyperscaler corridors.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| Lenovo Group Limited |
| Huawei Technologies Co., Ltd. |
| International Business Machines Corp. |
| Cisco Systems Inc. |
| Fujitsu |
| Inspur Group |
| Atos SE |
| Others |
Pricing and Supply Chain Analysis
Hyperscale procurement volumes concentrated in Cape Town's cable landing corridor compress unit costs for blade server configurations while elevating price floors for rack servers in Johannesburg's fragmented enterprise channel. NERSA's embedded generation licensing reforms add solar co-location costs that propagate through colocation pricing structures, forcing operators to recover capital outlays through long-term contract structures.
Pricing Analysis
Cost-plus contracts with NERSA tariff indexation dominate hyperscale procurement agreements, insulating operators from electricity price volatility while embedding thermal efficiency premiums into liquid-cooled server pricing. Price differentiation separates direct OEM agreements for Johannesburg banks from distributor-mediated transactions for mid-market enterprises, with certification grade and volume scale as primary tiering variables. Pricing pressure stems from Huawei's aggressive rack and blade positioning for telecommunications operators, compressing margins for traditional channel partners. Enterprise buyers in KwaZulu-Natal and Eastern Cape exhibit highest price sensitivity due to skills scarcity driving support service premiums.
Supply Chain Analysis
Durban port congestion and SABS electromagnetic compatibility testing create chokepoints that extend server equipment lead times and inflate working capital requirements for South African operators. Supply concentrates in China, Taiwan, and the United States for x86 processors, memory modules, and power supply units, with final assembly distributed across Malaysia and Mexico. Single-source vulnerability in advanced processor architectures from Intel and AMD feeds into procurement risk, compounded by ICASA spectrum allocation delays affecting edge server deployment timing. Distribution runs through Johannesburg-based value-added distributors for enterprise accounts, while hyperscalers maintain direct manufacturer relationships bypassing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's data center server market fragments across thermal envelope requirements, cooling technology mandates, and hyperscaler-versus-enterprise procurement patterns, creating specialized niches as NERSA reforms and submarine cable landings reshape demand geography.
For Market Incumbents: Fortify channel control in Johannesburg financial services clusters by embedding managed services capabilities around server lifecycle operations, countering direct OEM agreements that three major banks have established. Deepen backward integration into liquid-cooled rack design to capture NERSA tariff premiums, while reinforcing technical presales capacity to offset margin compression from standardized hyperscale procurement. For New Entrants and Emerging Players: Lead with immersion cooling system integration for Free State solar-powered hyperscale campuses, where transmission infrastructure gaps favor off-grid server deployments. Target KwaZulu-Natal mining corridor edge facilities enabled by ICASA 5G mid-band allocations, penetrating a geography underserved by certified engineer concentration in Gauteng and Western Cape. Position through wireless backhaul optimization as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cooling infrastructure providers and edge-to-core workload optimizers over commodity rack server distributors. Long-term viability hinges on NERSA regulatory continuity and embedded generation licensing enforcement sustaining thermal efficiency premiums. Target acquisition archetypes include liquid-cooled system integrators with Johannesburg financial services relationships and distributed edge facility operators in secondary provinces. Watch ICASA spectrum auction timing as the critical inflection signal for edge server demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | NERSA tariff penalties above 30 kilowatts per rack make thermal efficiency a margin determinant for Johannesburg facilities. |
| Direct OEM Supply Agreement | Hyperscalers and major banks bypass distributors to secure workload-optimized server configurations with audit trail continuity. |
| Solar Co-location Licensing | NERSA embedded generation reforms require on-site renewable assets, reshaping Cape Town hyperscale campus economics. |
| Edge Facility Wireless Backhaul | ICASA 5G spectrum allocations enable distributed computing in mining corridors previously unserved by fiber infrastructure. |
| Skills Pipeline Certification Investment | Technical vocational partnerships address HVAC technician scarcity constraining KwaZulu-Natal and Eastern Cape expansion. |
Research Methodology
Cross-validation between primary interviews with data center operators, financial services infrastructure heads, and telecommunications procurement executives and secondary validation through NERSA regulatory filings, ICASA spectrum allocation records, and hyperscaler capex disclosures anchors the qualitative findings. Bottom-up triangulation aggregates facility-level server deployment data across Western Cape, Gauteng, KwaZulu-Natal, Free State, and Eastern Cape provinces, while top-down reconciliation applies national electricity consumption patterns and import certification volumes.
Sensitivity analysis around NERSA tariff trajectory scenarios and submarine cable capacity utilization rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, cooling technology, deployment model, and provincial regulatory cluster, with CAGRs derived from facility expansion pipelines and enterprise cloud migration timelines. Server power density thresholds and solar irradiance patterns for embedded generation economics serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in NERSA electricity licensing and ICASA spectrum management regimes; material policy shifts would require re-modeling thermal management adoption curves and edge deployment patterns. Practitioners should keep alternative scenarios live as embedded generation licensing reforms and submarine cable landing schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Data Center Interconnect Market