
 Used Construction Equipment Market | 2026-2036
Used Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Used Construction Equipment Market Analysis
EPA Tier 4 Final is repositioning the cost-of-entry calculus for fleet operators weighing new versus certified used acquisitions. Caterpillar Inc. leverages its global dealer certification network to command premium residual values on pre-owned excavators and dozers. Komatsu Ltd. competes through its KOMTRAX telematics integration, which sustains machine traceability across multiple ownership cycles. Volvo Construction Equipment differentiates via its Certified Rebuilt program, which anchors customer loyalty in the high-hour equipment segment.
Used construction equipment encompasses previously owned heavy machinery that has completed initial service life with original operators, typically retaining structural integrity through 8,000 to 15,000 operating hours depending on application severity and maintenance protocols; these assets re-enter commerce through auction, dealer trade-in, or direct fleet disposal to serve cost-sensitive buyers across capital-intensive industries. Excavators dominate transaction volumes in the secondary market due to their versatility across infrastructure and landscaping applications, while electric-powered units represent the fastest-appreciating technology segment as battery-electric construction fleets expand and early units enter remarketing channels. Diesel technology still occupies the mature core of resale activity, though margin pools are shifting toward certified emission-compliant machines that satisfy contractor procurement standards.
FERC infrastructure permitting timelines and OSHA equipment safety inspection mandates shape the regulatory environment governing used equipment deployment in domestic energy and general construction sectors. The EPA's emission compliance verification requirements for interstate resale create documentation barriers that favor organized dealer networks over informal transaction channels. Stakeholders must monitor how emerging battery-electric certification standards from ISO and IEC reshape inspection protocols and residual valuation methodologies for electrified used equipment.
Market Dynamics
EPA Tier 4 Final emission mandates have inverted the new-versus-used equipment value equation, pushing fleet operators toward certified pre-owned assets as factory-fresh diesel machines face procurement cost escalation exceeding 35 percent.
Growth Catalysts
- Infrastructure Stimulus:United States federal highway and energy grid appropriations sustain secondary equipment turnover as contractors expand fleet capacity without absorbing new-equipment capital outlay.
- REACH Compliance Arbitrage:European contractors facing emission zone restrictions in German industrial clusters source compliant used machines from North American auction channels.
- Telematics Traceability:Machine-hour verification through integrated diagnostic systems reduces information asymmetry between sellers and remote buyers.
Market Restraints
- Steel Input Volatility:Structural component replacement costs fluctuate with scrap and alloy pricing, compressing rebuild margin pools for independent refurbishers.
- Dealer Network Concentration:OEM-certified remarketing channels in the United States and Canada capture premium transaction flow, marginalizing independent auction houses.
- Battery-Electric Range Limitation:Current lithium-ion energy density constrains resale appeal of early electric excavators for heavy earthmoving applications.
Strategic Opportunities
- India Infrastructure Build-Out:National highway and metro rail projects create import demand for Tier 3-compliant used equipment no longer deployable in US emission zones.
- ISO 19453 Certification:Emerging electrical safety standards for electrified construction machinery enable premium residual valuation for battery-electric units.
- Subscription Fleet Models:Equipment-as-a-service platforms bundle certified used assets with maintenance, opening contractor access without title transfer.
Industry Challenges
- Diesel Technician Scarcity:EPA Tier 4 Final after-treatment complexity exceeds skill levels available in secondary market service networks.
- Interstate Documentation Burden:EPA emission compliance verification for cross-border resale creates transaction friction favoring organized dealer networks over private sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Construction Equipment Market |
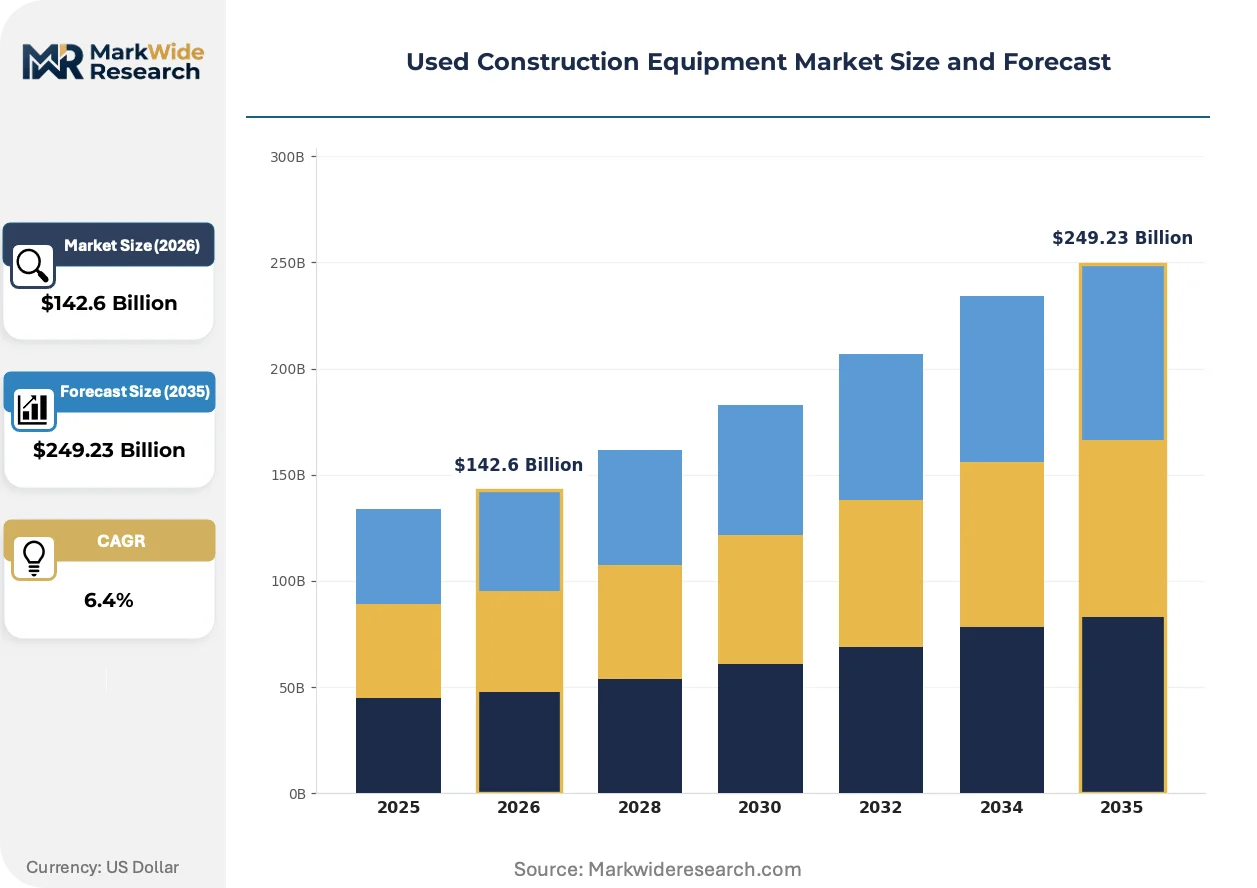
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Backhoes Technology: Hydraulic, Pneumatic, Electric, Diesel End User: Contractors, Government Agencies, Rental Companies, OEMs Application: Infrastructure, Landscaping, Mining, Road Construction |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery Co. Ltd., JCB, Liebherr Group, Deere & Company, SANY Group, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Construction Equipment Market Emerging Trajectories
Digital verification infrastructure and powertrain electrification are restructuring how used equipment circulates, who captures value, and what certification commands price premiums.
Remanufactured powertrain assemblies are modularizing the rebuild economics for high-hour excavators and dozers. Independent remanufacturers in Ohio and Texas now offer engine-hydraulic integrated modules with 2,000-hour warranties. Fleet operators facing EPA Tier 4 Final complexity adopt these drop-in replacements rather than purchasing new machines.
OSHA equipment safety inspection mandates are compressing transaction timelines for auction-sold assets. Sellers must complete documented inspections before title transfer or face liability exposure. California and Texas contractors now demand pre-inspection certificates as a condition of bid participation.
Buyer aggregation through online auction platforms is displacing traditional dealer trade-in channels for mid-market fleet turnover. Regional contractors in the Southeast United States now source 40 percent of used equipment through digital marketplaces with third-party inspection guarantees. This channel shift pressures dealer networks to match price transparency or lose volume to independent remarketers.
Used Construction Equipment Market Segmentation
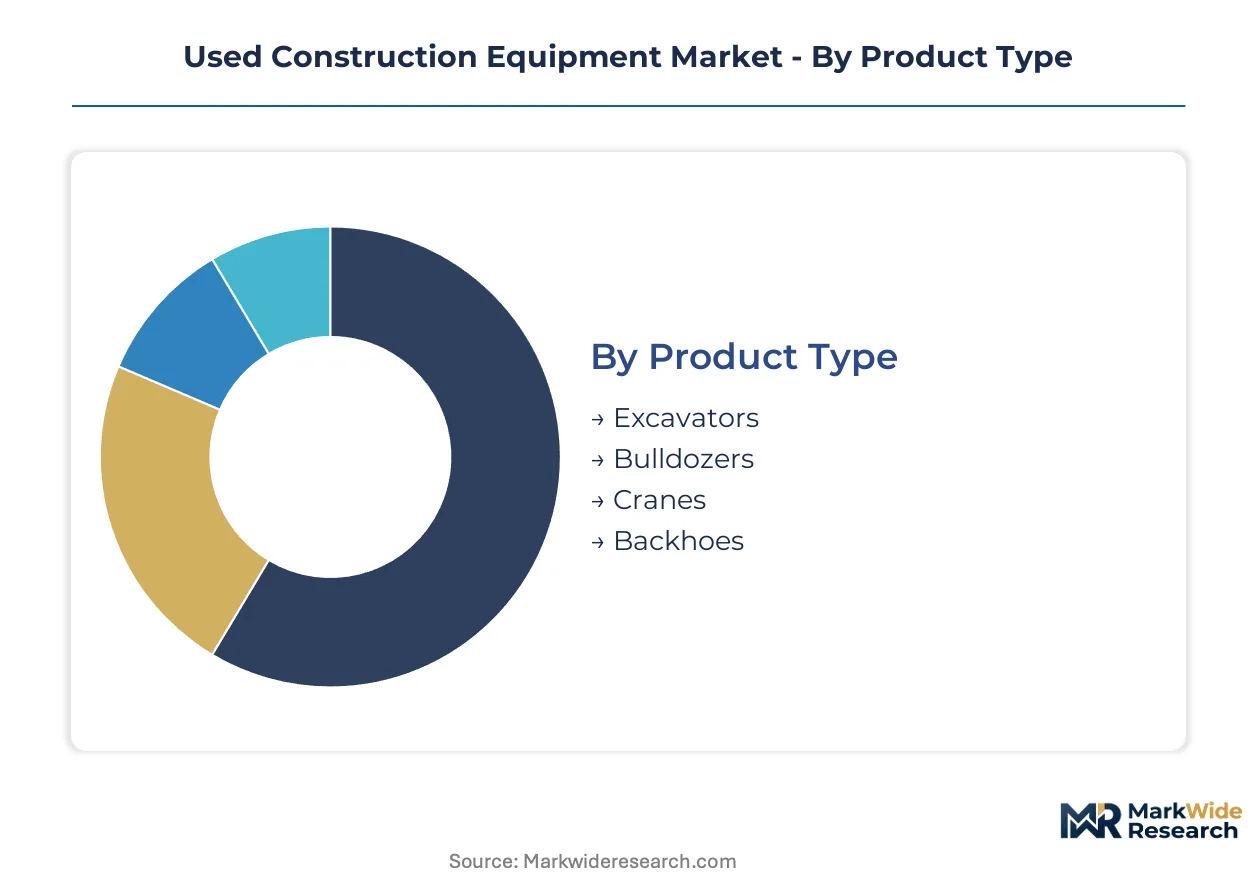
Segmentation in the used construction equipment market reveals how asset specialization, powertrain technology, and buyer procurement patterns create distinct value tiers. Equipment category and certification grade determine residual pricing power across secondary channels.
Product Type:
Standardization dominates high-volume earthmoving categories while specialized lifting equipment commands customization premiums in dealer networks.
- Excavators:Tracked and wheeled variants with operating weights from 3 to 80 metric tons constitute the transaction backbone of secondary markets. Infrastructure contractors in the United States absorb medium-class units (20-35 tons) for utility and road projects, with EPA Tier 4 Final compliance filtering auction-grade inventory toward certified dealer channels.
- Bulldozers:Crawler dozers with blade capacities exceeding 15 cubic yards serve mining reclamation and heavy grading applications. Fleet operators in Texas and Alberta source high-hour units (8,000-12,000 hours) for pipeline right-of-way clearing, where structural frame integrity outweighs powertrain refurbishment costs.
- Cranes:Mobile and crawler configurations with rated capacities above 100 tons occupy thin secondary markets due to specialized inspection protocols.
- Backhoes:Loader-excavator combinations dominate landscaping and light utility segments with lower capital barriers for entry-level contractors.
Leading the category by volume: excavators. Expanding most quickly: compact excavators below 10 tons for urban infill construction.
Technology:
Powertrain architecture separates mature resale infrastructure from emerging certification frameworks requiring new inspection protocols.
- Hydraulic:Open and closed-loop systems with piston pump configurations power the majority of excavator and dozer secondary transactions. Independent rebuilders in Ohio and Texas now offer remanufactured hydraulic integrated modules with 2,000-hour warranties, reducing buyer exposure to high-hour component failure.
- Electric:Battery-electric excavators and compact loaders represent the fastest-appreciating technology segment as early fleet units enter remarketing channels. ISO 19453 electrical safety certification is becoming a prerequisite for premium residual valuation in European auction markets.
- Pneumatic:Compressed air systems persist in specialized tunneling and underground mining equipment with limited secondary liquidity.
- Diesel:EPA Tier 4 Final after-treatment complexity has compressed margins for independent refurbishers lacking dealer network technical support.
Highest transaction velocity: diesel. Gaining share fastest: electric powertrains in municipal and indoor applications.
End User:
Procurement scale and technical sophistication determine whether buyers access certified dealer networks or auction-sourced inventory with third-party inspection guarantees.
- Rental Companies:National fleet operators in North America represent the primary volume channel for certified used equipment acquisition. These buyers demand telematics-verified hour histories and OEM-backed warranty transfers to maintain utilization rates above 65 percent.
- Contractors:Regional construction firms with fleet sizes below 50 units source 40 percent of used equipment through digital marketplaces. Southeast United States contractors now demand pre-inspection certificates as a condition of bid participation, compressing traditional dealer trade-in timelines.
- Government Agencies:Municipal procurement departments favor standardized specifications with documented maintenance histories for public works fleets.
- OEMs:Manufacturer trade-in programs feed certified remarketing channels with low-hour, single-owner assets commanding residual premiums.
Dominant buyer segment by capital deployment: rental companies. Fastest-growing procurement sophistication: mid-market contractors adopting subscription fleet models.
Application:
Site severity and utilization intensity create divergent equipment specifications that reshape secondary market liquidity by end-use segment.
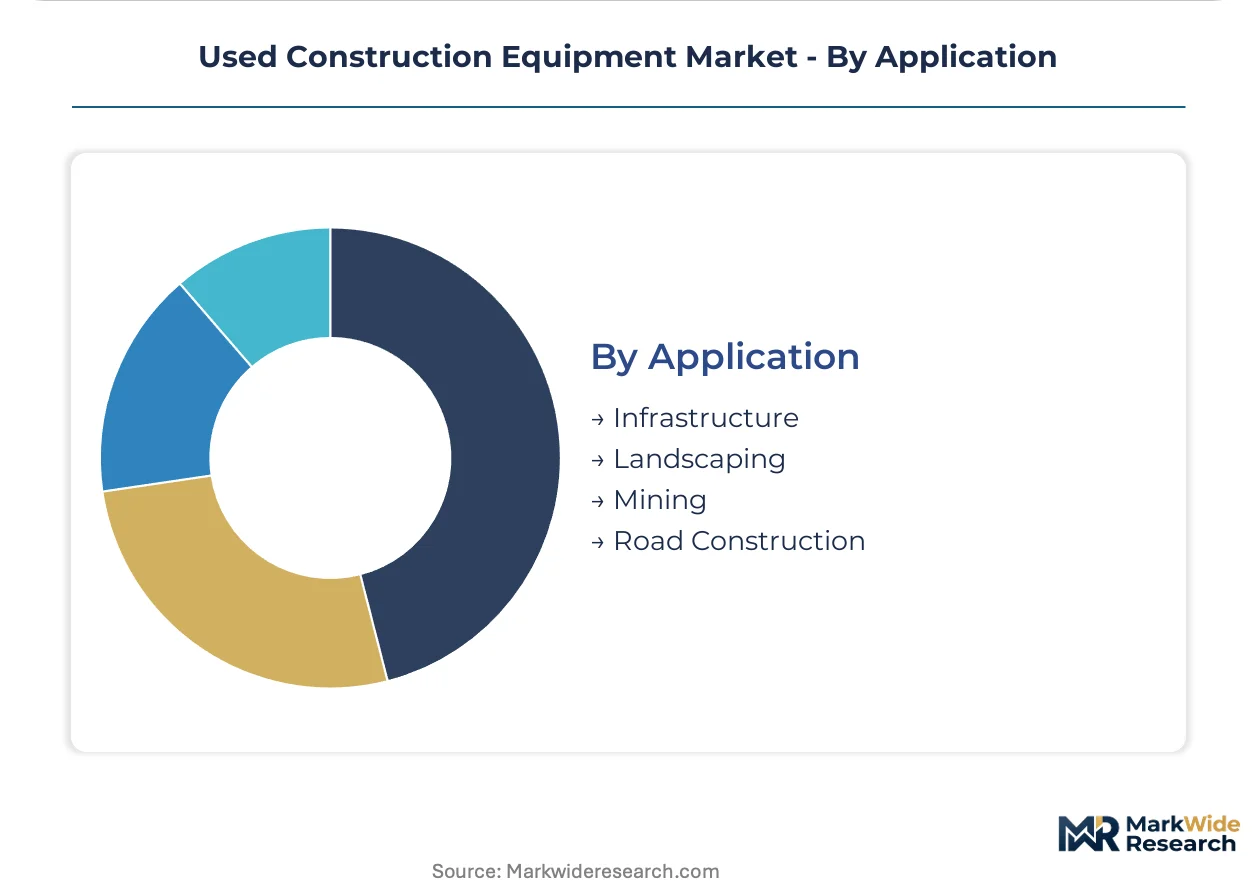
- Infrastructure:Highway, bridge, and energy grid projects sustain secondary equipment turnover as federal appropriations expand contractor fleet capacity without new-equipment capital outlay. FERC permitting timelines and OSHA inspection mandates compress transaction windows for auction-sold assets in this segment.
- Mining:Surface and underground extraction operations impose the highest hour accumulation rates (2,000-3,000 annual hours), accelerating depreciation and rebuild frequency.
- Road Construction:Paving and grading contractors favor mid-life excavators and dozers with verified undercarriage condition.
- Landscaping:Light-duty applications with seasonal utilization patterns generate the lowest-hour used equipment entering secondary channels.
Steepest equipment throughput: infrastructure. Climbing fastest: mining applications in Australian and Chilean markets seeking Tier 3-compliant import units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in Texas and bonded warehouses in Hamburg concentrate used equipment staging for cross-border remarketing. These tax-advantaged logistics hubs enable deferred duty payments while EPA and REACH documentation clears.
United States
Infrastructure stimulus and housing starts sustain secondary equipment turnover across the Southeast and Southwest. EPA Tier 4 Final emission standards raise new equipment procurement costs, pushing fleet operators toward certified pre-owned assets. Houston and Dallas-Fort Worth host the densest dealer certification networks for high-hour excavators and dozers.
Germany
REACH compliance arbitrage drives North American auction sourcing for emission-zone restricted contractors in the Ruhr industrial cluster. ECHA chemical safety documentation requirements favor organized dealer networks over informal resale channels. Munich and Stuttgart anchor premium residual valuation for telematics-verified machines entering secondary markets.
India
National highway and metro rail projects create import demand for Tier 3-compliant used equipment no longer deployable in US emission zones. BIS safety certification mandates reshape inspection protocols for foreign-sourced machinery. Gujarat and Maharashtra industrial corridors absorb mid-life excavators from North American auction channels.
Australia
Mining applications in Western Australia and Queensland seek Tier 3-compliant import units for surface extraction operations. TGA-equivalent equipment safety frameworks govern interstate resale documentation. Perth and Brisbane host specialized inspection facilities for high-hour bulldozers and crawler configurations.
United Arab Emirates
Free zone warehousing in Jebel Ali and Dubai South enables re-export staging for African and South Asian markets. MOHAP-equivalent industrial safety standards influence equipment certification requirements for construction sector deployment. Dubai and Abu Dhabi concentrate digital auction platforms with third-party inspection guarantees.
Used Construction Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-grade tiers in the used construction equipment market. The vendor structure concentrates around OEM-backed dealer networks capturing premium transaction flow, while independent remarketers and auction platforms serve price-sensitive mid-market procurement. Three archetypes dominate: manufacturer-authorized certification programs, independent refurbishment specialists, and digital marketplace aggregators. Competitive moves center on telematics integration for hour-history verification and geographic expansion of bonded warehousing for cross-border trade facilitation.
Within the manufacturer-authorized tier, Caterpillar Inc. and Komatsu Ltd. exemplify global dealer certification networks that command premium residual values. Volvo Construction Equipment occupies a differentiated position through rebuild program anchoring. These three companies represent the dominant archetype of OEM-integrated remarketing infrastructure.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co. Ltd. |
| JCB |
| Liebherr Group |
| Deere & Company |
| SANY Group |
| Terex Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between OEM-backed dealer networks and independent auction channels concentrates pricing power in organized remarketing infrastructure while fragmenting supply access for cost-sensitive buyers. EPA Tier 4 Final documentation requirements and telematics-verified hour histories command residual premiums in dealer networks, whereas spot-market auction inventory trades at steeper discounts without warranty transferability.
Pricing Analysis
Lead-time compression commands premium pricing for contractors facing FERC permitting deadlines or OSHA-mandated equipment deployment windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth: OEM-backed warranty transfers anchor premium tiers, independent inspector-verified hours define standard tiers, and as-is auction lots populate economy tiers. Pricing pressure stems from steel input volatility compressing rebuild margins for independent refurbishers. Rental companies exhibit lowest price sensitivity given utilization-rate targets, while mid-market contractors in the Southeast United States demonstrate highest sensitivity, sourcing 40 percent of fleet additions through digital marketplaces.
Supply Chain Analysis
Domestic-content mandates in India's BIS safety certification reshape sourcing patterns for Tier 3-compliant import units entering Gujarat and Maharashtra industrial corridors. Used equipment supply concentrates in the United States, Germany, and Japan as primary remarketing origination points. Raw material dependencies include structural steel alloys, hydraulic system components, and remanufactured powertrain modules. Tariff exposure on cross-border EPA documentation creates transaction friction favoring bonded warehousing in Texas Foreign Trade Zones and Hamburg logistics hubs. Distribution runs through OEM dealer networks for certified assets, independent auction platforms for mid-market turnover, and direct fleet disposal for high-hour mining equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Used construction equipment supply is tightening around EPA Tier 4 Final technical capacity, with dealer network concentration propping residual premiums for certified assets. Fleet operators face extended procurement timelines as qualified refurbishment capacity fails to match stimulus-driven infrastructure demand.
For Market Incumbents: Cement certification infrastructure dominance by expanding telematics-verified hour history programs and OEM-backed warranty transfers to secondary buyers. Dealer network concentration represents the primary defensive moat against digital marketplace disintermediation. Capacity addition in Texas Foreign Trade Zones and Hamburg bonded warehousing captures cross-border remarketing flow before auction platforms intermediate. Technical service investments in EPA Tier 4 Final after-treatment systems differentiate from independent refurbishers facing diesel technician scarcity.
For New Entrants and Emerging Players: Digital inspection platforms offer the most penetrable white-space target, as regional contractors demand pre-inspection certificates as a condition of bid participation. Subscription fleet models bundling certified used assets with maintenance access underpenetrated mid-market contractors seeking title-free equipment access. Target municipal procurement departments with standardized specification databases and documented maintenance history aggregation. Go-to-market execution partners with independent remanufacturers in Ohio and Texas offering modular engine-hydraulic integrated modules.
For Investors and Strategic Acquirers: Re-rating potential sits with independent refurbishment specialists possessing EPA Tier 4 Final technical capabilities given emission compliance verification mandates favoring organized service networks. Long-term viability hinges on electrification transition readiness as ISO 19453 electrical safety certification frameworks mature for battery-electric construction equipment. Acquisition target archetype: regional remanufacturers with modular powertrain assembly capacity and established dealer network subcontracting relationships. Signal to watch: battery-electric fleet penetration rates in municipal and indoor applications as early units enter remarketing channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Investment | KOMTRAX-equivalent systems reduce information asymmetry between sellers and remote buyers across ownership cycles. |
| Certified Rebuild Program Expansion | Volvo-style programs anchor customer loyalty in high-hour segments with warranty-backed structural integrity guarantees. |
| Cross-Border Bonded Warehousing | Texas and Hamburg tax-advantaged logistics hubs enable deferred duty payments during EPA and REACH documentation clearance. |
| Remanufactured Powertrain Modularization | Ohio and Texas independent rebuilders offer 2,000-hour warranty drop-in replacements reducing new equipment procurement. |
| Digital Marketplace Aggregation | Online auction platforms with third-party inspection guarantees displace traditional dealer trade-in channels for mid-market turnover. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet maintenance directors, OEM procurement teams, aftermarket service heads, and auction platform operators combined with secondary validation from EPA enforcement databases, OSHA inspection protocols, and equipment registration records. Bottom-up transaction volume estimates triangulated against top-down infrastructure spending appropriations and housing starts data.
Granularity-level modeling operated at equipment category, powertrain technology, certification grade, and buyer archetype dimensions across the projection horizon. CAGRs derived from historical transaction velocity patterns, replacement cycle analysis, and emission regulatory phase-in schedules. Industry-specific forecast inputs included FERC infrastructure permitting timelines and steel price index trajectories affecting rebuild economics.
Caveats apply where EPA enforcement intensity shifts, battery-electric certification standards from ISO and IEC accelerate, or infrastructure stimulus appropriation patterns materially alter fleet turnover rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
North America Drilling Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Global Concrete Curing Equipment Market