
 Welding and Cutting Equipment Market | 2026-2036
Welding and Cutting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Welding and Cutting Equipment Market Analytics
Project finance and equipment leasing is tilting competitive dynamics toward asset-light fabricators who previously could not afford automated systems. Lincoln Electric leverages captive financing programs to anchor its position among mid-sized job shops. Fronius International differentiates through inverter technology leadership, while ESAB competes on geographic breadth across emerging industrial corridors.
Welding and cutting equipment encompasses arc, laser, plasma, and resistance-based systems that fuse or sever metals using controlled thermal energy, typically operating at temperatures exceeding 6,500°C for plasma processes. These systems serve primary industrial purposes across fabrication, repair, and metalworking operations where structural integrity and precision tolerances determine product performance. Arc welding equipment occupies the largest installed base due to its versatility across construction and shipyard environments, while laser cutting commands premium positioning in automotive sheet-metal processing where speed and kerf quality justify higher capital outlays. Resistance welding sustains steady demand from manufacturing lines producing high-volume stamped assemblies.
The EPA enforces air-quality standards that limit fume emissions from arc welding operations, pushing fabricators toward filtered extraction systems and lower-emission processes. OSHA mandates worker exposure limits for hexavalent chromium and manganese compounds generated during stainless and high-strength steel welding, directly shaping ventilation equipment attachments and consumable formulations. The EU F-Gas Regulation restricts fluorinated greenhouse gases used in plasma cutting shielding, compelling equipment redesigns. Stakeholders must monitor how tightening energy-efficiency standards in China and Europe reshape total cost-of-ownership calculations for capital-intensive cutting platforms.
Market Dynamics
Automotive lightweighting mandates are compressing welding cycle times while expanding laser and friction stir adoption across aluminum-intensive chassis architectures. Tier-one suppliers now demand sub-millimeter repeatability from equipment vendors, forcing R&D priorities toward sensor-integrated adaptive control systems.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in plasma cutting shielding gases is accelerating equipment retrofit cycles and creating replacement demand for compliant inverter-based systems.
- Automotive aluminum joining:Battery enclosure and body-in-white applications are pulling resistance welding and laser brazing equipment into high-volume EV production lines.
- China's dual carbon goals:Industrial energy-efficiency mandates are concentrating investment in high-efficiency arc welding power sources across the Yangtze River Delta manufacturing belt.
Market Restraints
- Helium supply concentration:US Bureau of Land Management stewardship and Qatar's production dominance create price volatility for plasma and laser cutting shielding gas costs.
- OSHA hexavalent chromium exposure limits:Stainless steel welding ventilation requirements add capex burden to smaller fabricators, constraining fleet expansion.
- Copper winding substitution:Aluminum magnet wire adoption in transformer-based welders introduces thermal performance trade-offs that limit duty cycle ratings.
Strategic Opportunities
- India PLI scheme for auto components:Domestic manufacturing incentives are creating greenfield demand for automated welding cells in Tamil Nadu and Gujarat supplier parks.
- Equipment-as-a-service models:Usage-based pricing and remote monitoring subscriptions are opening mid-sized job shops to robotic welding adoption previously blocked by capital constraints.
- Laser-arc hybrid convergence:Combined heat source systems are penetrating thick-section shipbuilding and pressure vessel applications where pure laser power was cost-prohibitive.
Industry Challenges
- Welding engineer scarcity:Certified robotic programming and process development expertise concentrates in automotive supplier clusters, leaving general fabrication segments underserved.
- CE marking timeline compression:EU Machinery Directive conformity assessment delays for novel laser safety architectures are extending product launch windows by 6-12 months.
- Legacy MIG/MAG fleet integration:Analog power source retrofit with Industry 4.0 data acquisition requires middleware development that fragments vendor support capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding and Cutting Equipment Market |
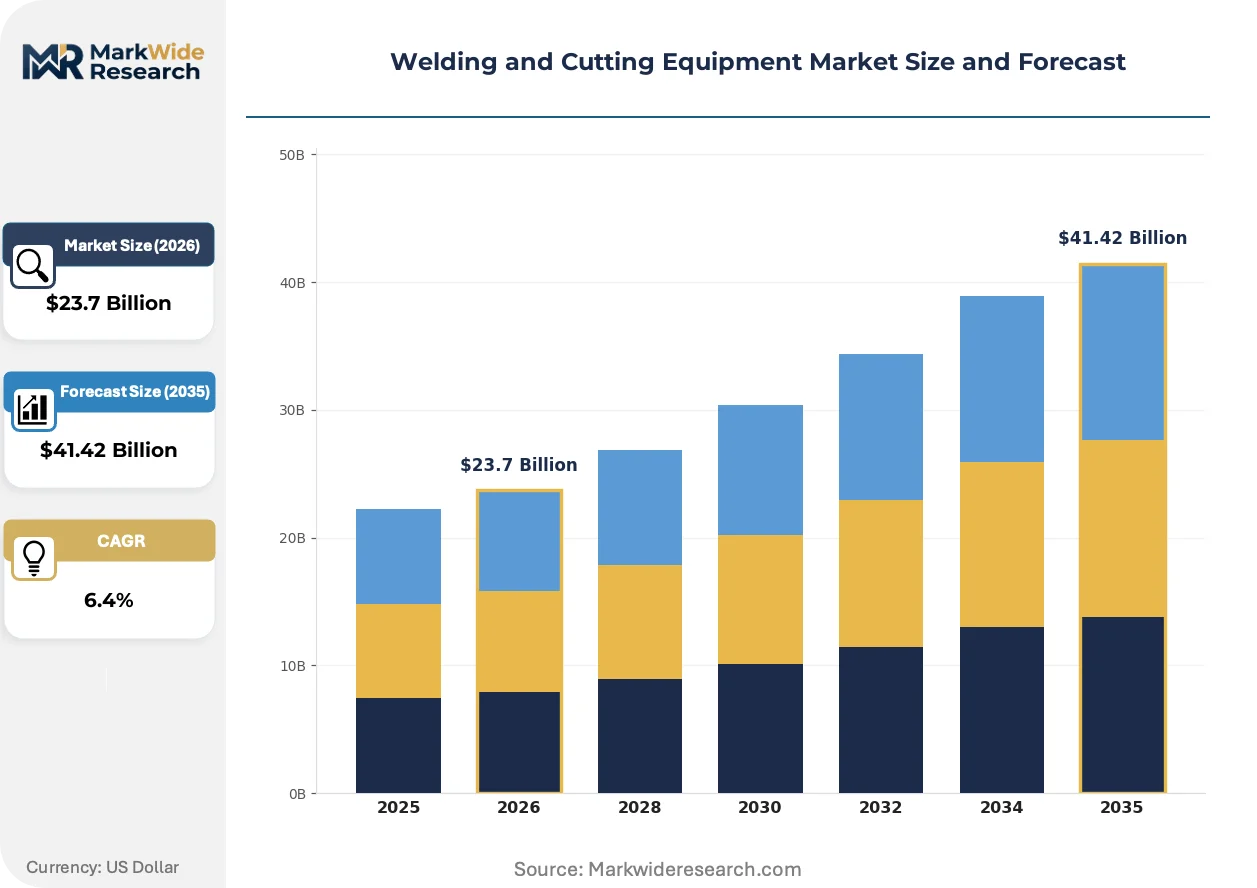
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arc Welding, Laser Cutting, Plasma Cutting, Resistance Welding Technology: MIG, TIG, Stick, Submerged Arc End User: Manufacturing, Construction, Automotive, Shipbuilding Application: Fabrication, Repair, Maintenance, Metalworking |
| Companies Covered | Fronius International, Illinois Tool Works Inc., Lincoln Electric, Coherent Inc., OTC DAIHEN Inc., ESAB, Kemppi, ACRO Automation Systems Inc., Miller Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding and Cutting Equipment Market Evolving Landscape
Process convergence and closed-loop control architectures are displacing open-loop welding systems across quality-critical applications. Equipment vendors now compete on data granularity and predictive maintenance integration rather than amperage range alone.
Hybrid laser-arc welding is hybridizing penetration characteristics of gas metal arc with speed and distortion control of fiber laser sources. European shipyards and wind tower fabricators are piloting 20kW-class systems for 25mm+ single-pass joining. The technology is hybridizing two formerly separate equipment categories into unified platform offerings that compress floor space and training requirements.
The EU F-Gas Regulation's 2030 phase-down targets are forcing plasma cutting OEMs to redesign torch gas delivery for argon-hydrogen and nitrogen-based alternatives. Equipment manufacturers in Germany and Italy are accelerating R&D spending on high-purity gas mixing systems. The regulation most directly impacts high-definition plasma users in metal service centers, who face consumable cost increases of 30-40% without process requalification.
Buying committees at automotive tier-one suppliers now unbundle welding equipment procurement from consumables and service contracts, reversing decades of bundled pricing. This disintermediation pressures traditional distributor networks and opens direct vendor relationships. The pattern is most visible in Germany's automotive supplier belt, where Volkswagen and BMW group purchasing organizations have mandated separate RFQs for capital equipment versus wire and gas supply.
Welding and Cutting Equipment Market Segmentation
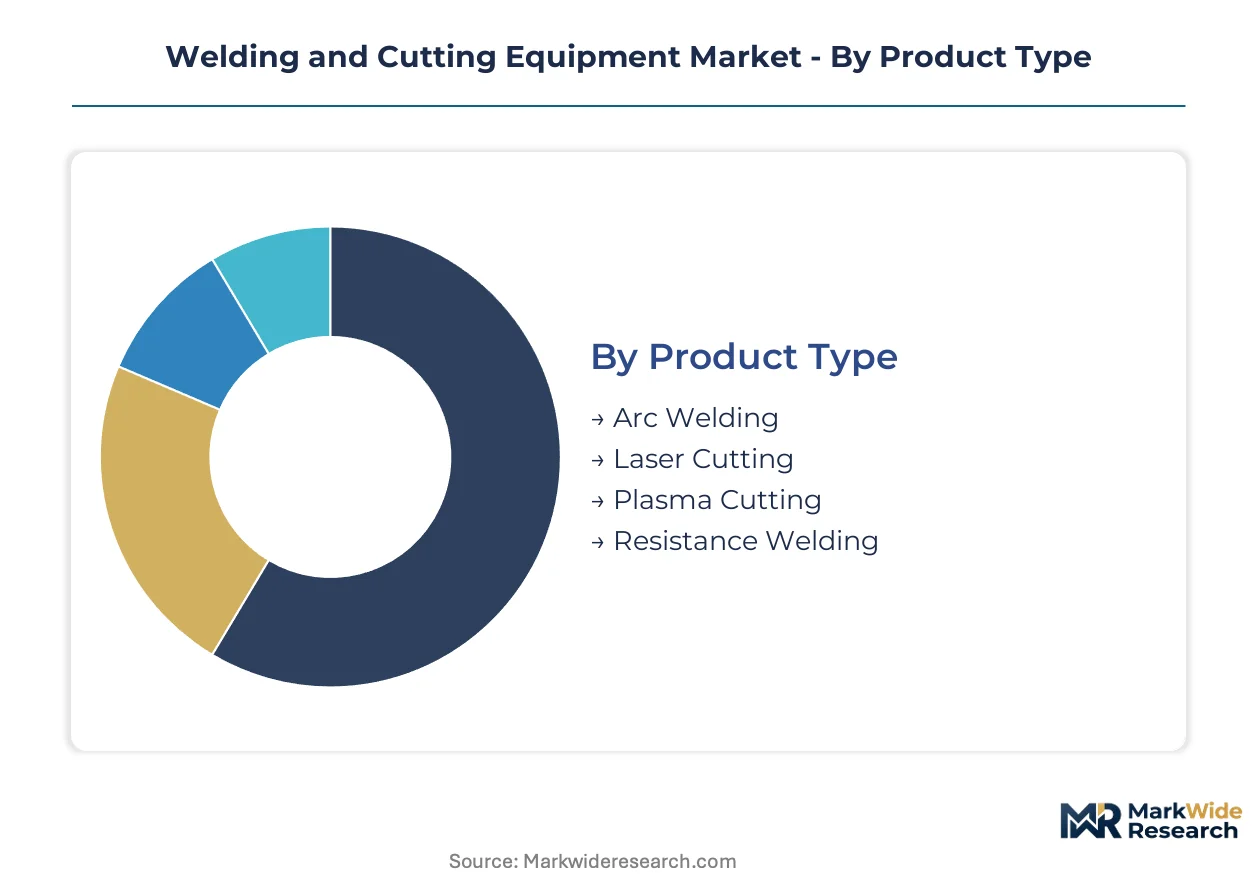
Segmentation in welding and cutting equipment reveals how capital allocation priorities diverge across process technologies and end-use requirements. Equipment specifications, duty cycle demands, and regulatory compliance burdens vary sharply between automotive production lines and field construction environments.
Product Type:
Cost tier differentiation separates commodity arc systems from premium laser platforms requiring specialized infrastructure and operator certification.
- Arc Welding:Consumes electrodes or wire filler metal to generate coalescence through electric arc temperatures reaching 6,500°C. Construction contractors across Germany's industrial belt favor portable inverter units for structural steel erection where mobility outweighs precision requirements. OSHA fume exposure mandates are accelerating filtered extraction attachments for stainless applications.
- Laser Cutting:Deploys focused coherent light beams to achieve kerf widths below 0.3mm in automotive sheet metal processing. Tier-one suppliers in Stuttgart and Munich demand fiber laser systems with adaptive beam shaping for aluminum-intensive EV architectures. Capital intensity limits adoption to high-volume production environments.
- Plasma Cutting:Ionizes compressed gas through electric arc to sever conductive metals up to 50mm thickness. Metal service centers utilize high-definition plasma for plate processing where speed tolerates wider kerf than laser alternatives.
- Resistance Welding:Applies mechanical pressure and electric current to forge welds without filler material. Stamped assembly lines for battery enclosures and body-in-white structures sustain steady equipment demand.
Arc welding commands the established base. The steepest expansion runs through laser cutting.
Technology:
Application severity and base metal characteristics dictate process selection across fabrication workflows.
- MIG:Continuous wire electrode feeding enables high-deposition-rate joining of carbon and low-alloy steels. Shipyards along China's Yangtze River Delta specify pulsed MIG systems for thick-section hull construction where productivity targets compress cycle times.
- TIG:Non-consumable tungsten electrode delivers precise arc control for critical root passes and exotic alloys. Aerospace component suppliers and nuclear pressure vessel fabricators mandate TIG for code-qualified joints requiring radiographic inspection.
- Stick:Flux-coated electrode simplicity sustains dominance in outdoor construction and remote maintenance where shielding gas logistics prove impractical. Wind tower erection crews and pipeline repair teams specify stick equipment for field portability.
- Submerged Arc:Granular flux blanket eliminates atmospheric contamination during high-current welding of thick plate. Offshore platform fabricators and heavy equipment manufacturers deploy submerged arc for longitudinal seam welding in girth positions.
Stick welding retains the broadest installed footprint. MIG technology is climbing the fastest as automation penetrates repetitive production environments.
End User:
Volume scale and quality certification requirements fragment equipment specifications across industrial verticals.
- Manufacturing:Encompasses general fabrication shops producing industrial machinery, agricultural equipment, and material handling systems. China's dual carbon efficiency mandates are concentrating investment in inverter-based power sources across the Pearl River Delta manufacturing corridor.
- Construction:Structural steel erection and infrastructure projects demand portable equipment with generator compatibility. German construction consortiums specify four-roll wire feeders and synergic control interfaces to reduce operator skill dependencies on congested job sites.
- Automotive:OEM and tier-one production lines require robotic integration, real-time quality monitoring, and sub-millimeter repeatability. Battery enclosure welding for electric vehicles is pulling resistance and laser brazing equipment into high-volume greenfield facilities in Tamil Nadu and Gujarat.
- Shipbuilding:Thick-section joining and curved panel fabrication necessitate heavy-duty submerged arc and flux-cored systems. European yards are piloting hybrid laser-arc systems for 25mm single-pass welding in wind tower transition piece production.
Manufacturing holds the deepest equipment penetration. Automotive applications are expanding most quickly as powertrain electrification reshapes joining requirements.
Application:
Customer type and workpiece characteristics determine equipment mobility, automation level, and consumable strategy.
- Fabrication:Original equipment manufacturing of metal structures, pressure vessels, and industrial components demands repeatable process parameters. Job shops in India's PLI-supported auto component parks are installing automated welding cells to meet OEM qualification standards.
- Repair:Field service and breakdown maintenance requires portable equipment with rapid setup capabilities. Offshore oil platform operators and mining equipment maintainers specify engine-driven welders with multiprocess flexibility.
- Maintenance:Scheduled upkeep of industrial infrastructure and production equipment prioritizes reliability and parts availability. Plant maintenance departments favor established brands with distributor networks guaranteeing 24-hour consumable delivery.
- Metalworking:Custom architectural metal, artistic fabrication, and prototype development values precision and aesthetic control. Artisan workshops specify TIG equipment with pulse frequency modulation for thin-gauge stainless and aluminum finishing.
Fabrication anchors capital equipment procurement. Repair services are gaining share fastest as asset life extension priorities extend fleet maintenance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial policy incentives are redirecting capital flows across manufacturing belts worldwide. Government-backed production subsidies and emissions regulations are reshaping where fabricators upgrade welding fleets and how suppliers configure distribution networks.
United States
Infrastructure spending packages are accelerating structural steel demand across bridge and highway projects. OSHA hexavalent chromium exposure mandates are pushing stainless fabricators toward filtered extraction systems. Equipment procurement concentrates in Texas Gulf Coast petrochemical corridors and Great Lakes automotive supplier networks.
Germany
Automotive lightweighting mandates from BMW and Volkswagen procurement organizations are compressing welding cycle time requirements. The EU F-Gas Regulation's 2030 phase-down targets are forcing plasma cutting OEMs to redesign torch gas delivery systems. Precision welding investment dominates capital plans across Baden-Württemberg and Bavaria supplier belts.
China
Dual carbon energy-efficiency mandates are concentrating investment in high-efficiency arc welding power sources. MIIT industrial upgrading programs are subsidizing robotic cell adoption across state-owned shipyards. The Yangtze River Delta manufacturing belt leads inverter-based system deployment for carbon steel fabrication.
India
PLI scheme incentives for auto components are creating greenfield demand for automated welding cells. BIS certification requirements for industrial equipment are extending qualification timelines for imported systems. Tamil Nadu and Gujarat supplier parks are anchoring resistance welding equipment deployment for battery enclosure manufacturing.
Japan
METI energy-efficiency standards are reshaping total cost-of-ownership calculations for capital-intensive cutting platforms. JIS certification requirements maintain quality barriers for precision joining equipment. Automotive tier-one suppliers in Aichi Prefecture are specifying sub-millimeter repeatability from robotic welding vendors.
Welding and Cutting Equipment Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Specialist inverter technology developers compete against diversified industrial conglomerates with captive financing arms. Pure-play automation integrators occupy a middle tier focused on robotic cell deployment. Competitive dynamics center on equipment-as-a-service pricing models and geographic expansion into emerging industrial corridors.
Within the diversified industrial tier, Lincoln Electric and Illinois Tool Works exemplify capital-access strategies that anchor market position among mid-sized fabricators. Fronius International occupies a specialist position representing inverter technology leadership, while ESAB sits within the geographic breadth archetype across emerging manufacturing belts. These three anchors demonstrate how financing programs, technical specialization, and distribution scale serve as alternative vectors for competitive differentiation.
| Leading Market Players |
|---|
| Fronius International |
| Illinois Tool Works Inc. |
| Lincoln Electric |
| Coherent Inc. |
| OTC DAIHEN Inc. |
| ESAB |
| Kemppi |
| ACRO Automation Systems Inc. |
| Miller Electric |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese inverter-based welding power sources is compressing margins across mid-tier equipment categories and forcing European and Japanese suppliers toward premium positioning anchored by certification differentiation.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with CE-marked and ISO-certified systems commanding 25-40% premiums over uncertified alternatives in regulated markets. Three-tier pricing structure across premium, standard, and economy levels reflects duty cycle ratings, automation integration depth, and after-sales service bundling. Cost compression in standard-tier arc welders is intensifying because Chinese manufacturers are exporting excess capacity into Southeast Asian and Middle Eastern markets. Job shops and small fabricators exhibit the highest price sensitivity, while automotive tier-one suppliers prioritize total cost-of-ownership metrics over upfront capital expenditure.
Supply Chain Analysis
Copper winding feedstock draws from Chilean and Peruvian mining concentration, with Chinese smelters dominating refined cathode processing for magnet wire production. IGBT power modules hinge on Taiwanese and South Korean semiconductor fabrication, while high-purity shielding gases rest on Qatari helium and Ukrainian argon extraction. Single-source vulnerability in rare earth magnet supply for servo motors in robotic welding cells exposes equipment OEMs to export restriction risk. Distribution runs through authorized dealer networks for capital equipment, with consumables flowing via industrial gas distributors and welding supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service platforms are reconfiguring buyer-supplier relationships around usage metrics rather than asset ownership, with interoperability standards for remote monitoring becoming the decisive ecosystem battleground.
For Market Incumbents: Pre-empt margin erosion in standard arc welding by deepening captive financing penetration and locking in consumables bundling before unbundling spreads beyond German automotive procurement. Vertical integration into high-purity gas mixing systems addresses EU F-Gas Regulation compliance requirements while creating switching costs. Prioritize sensor-integrated adaptive control R&D to defend against pure-play automation integrators. For New Entrants and Emerging Players: Mid-market job shops in India's PLI-supported auto component corridors represent the most penetrable entry point, where capital constraints block incumbent robotic solutions and equipment-as-a-service models open new customer relationships. Target resistance welding and laser brazing equipment for battery enclosure manufacturing in Tamil Nadu and Gujarat supplier parks. Lead with remote monitoring subscriptions and predictive maintenance guarantees rather than hardware specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers with installed telemetry platforms, suggesting superior long-term viability through the electrification-driven replacement cycle. Acquisition candidates with inverter technology specialization and established automotive tier-one relationships offer defensive positioning. Monitor helium supply contract renegotiation patterns as an inflection indicator for plasma cutting equipment profitability stress.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Platform Launch | Transforms capital-constrained job shops into addressable customers via usage-based pricing. |
| EU F-Gas Compliant Torch Redesign | Secures market access as 2030 phase-down deadlines approach for plasma cutting OEMs. |
| Sensor-Integrated Adaptive Control R&D | Meets sub-millimeter repeatability demands from BMW and Volkswagen procurement organizations. |
| Captive Financing Program Expansion | Anchors Lincoln Electric's position among mid-sized fabricators previously blocked by capital constraints. |
| Remote Monitoring Infrastructure Buildout | Enables predictive maintenance subscriptions that differentiate beyond amperage specifications. |
Research Methodology
A standing panel of welding equipment procurement managers at automotive tier-one suppliers, plant engineers at metal fabrication facilities, aftermarket service heads at distributor networks, and R&D directors at inverter technology specialists provided ongoing calibration across the study period. Primary interview findings were cross-referenced against secondary sources including SEC filings from diversified industrial conglomerates, EU ECHA regulatory impact assessments, customs trade data for welding equipment imports, and MIIT industrial upgrading program disclosures. Bottom-up equipment shipment data was triangulated against top-down capital expenditure surveys from manufacturing trade associations.
Scenario-bracketing around automotive electrification pace and EU F-Gas Regulation enforcement timelines framed the analytical approach across the projection horizon. Segmentation modeling incorporated process technology, automation integration level, end-use industry vertical, and regional regulatory cluster dimensions. CAGRs were derived from equipment replacement cycle analysis and greenfield capacity installation patterns. Forecast inputs included MIIT robotic cell adoption subsidies and OSHA enforcement intensity projections for hexavalent chromium exposure limits.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, Chinese export credit availability, or helium spot pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology substitution elasticities. Cross-checking against IHS Markit industrial production indices and automotive OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotary Dryers Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Rotomolding Market
Construction Equipment
Assembly Machine Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Log Splitters Rental Market