
 Asia Pacific Construction Equipment Market | 2026-2036
Asia Pacific Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Construction Equipment Market Intelligence
Multi-source procurement among large contractors is expanding across Asia Pacific project sites as equipment availability constraints reshape sourcing strategy. Komatsu sustains technology leadership through its integrated telematics platforms deployed across Australian mining contracts. Sany Heavy Industry anchors Chinese domestic supply through in-house hydraulic system production and extensive dealership networks. Volvo Construction Equipment differentiates in Southeast Asia via its electric powertrain pilot programs targeting urban development zones with strict noise ordinances.
Asia Pacific construction equipment encompasses heavy machinery engineered for earthmoving, material handling, and vertical construction tasks, typically powered by diesel engines rated above 75 kW or emerging electric powertrains delivering equivalent torque output for emission-restricted environments. Excavators dominate product type revenue as trenching and foundation work intensity rises across transportation projects in Indonesia and Vietnam. Telematics penetration within the technology dimension is accelerating fastest among rental service providers seeking utilization optimization across dispersed fleets. Diesel engines retain installed-base dominance but face margin compression as China's dual carbon goals and India's CEA efficiency mandates elevate electric powertrain development costs.
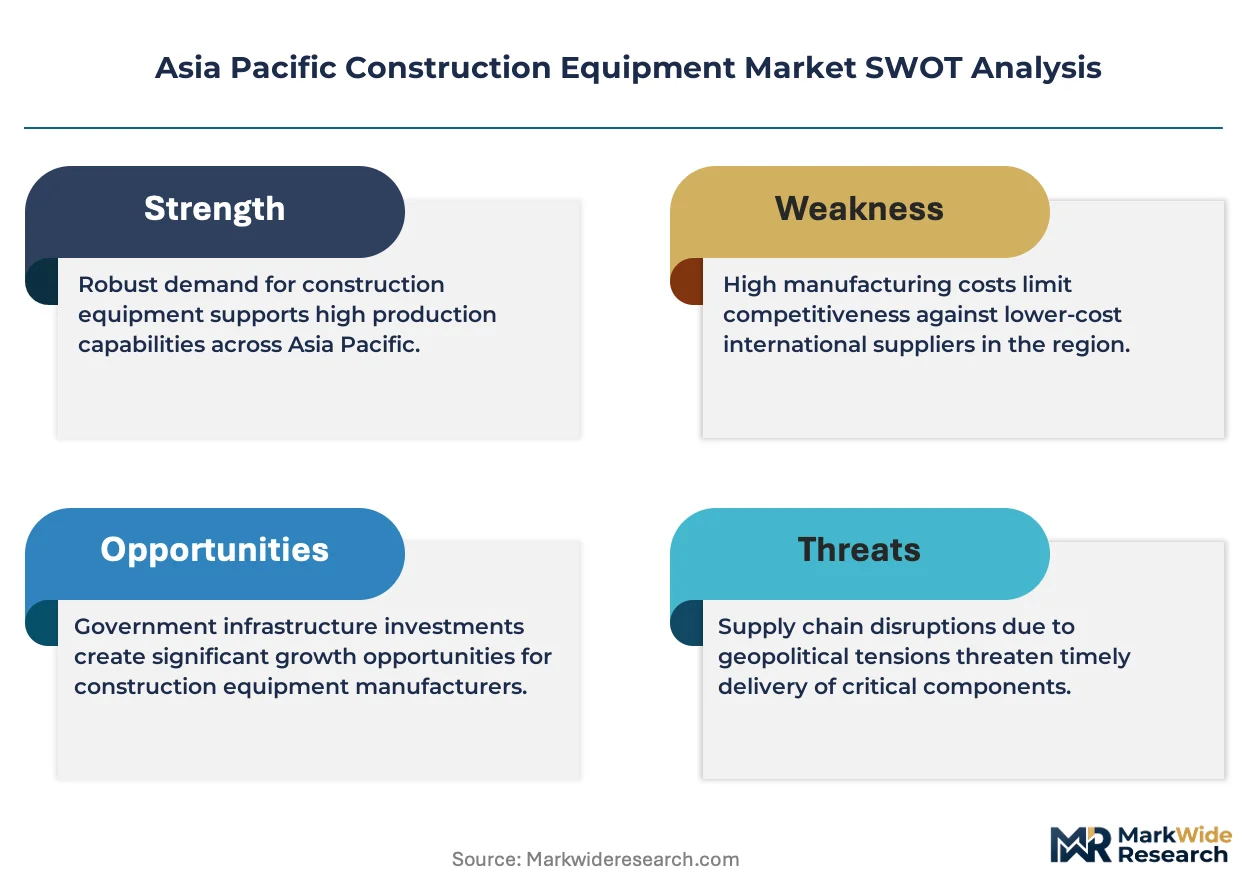
Japan's METI enforces stringent construction machinery emission tiers that limit import eligibility for non-compliant equipment, while China's MIIT administers GB standards governing hydraulic efficiency and noise thresholds for domestic manufacturers. Australia's state-level environmental regulators impose progressive diesel particulate limits on mining operations, directly conditioning fleet replacement cycles. India's BIS certification requirements for cranes and concrete mixers create compliance barriers for unapproved imports. Stakeholders must weigh powertrain transition timelines against residual value risks in markets with divergent enforcement calendars.
Market Dynamics
China's MIIT emission standards are forcing powertrain redesigns across domestic manufacturing bases while Australian mining operators accelerate diesel-to-electric fleet conversions under state environmental mandates. These dual regulatory pressures are compressing equipment replacement cycles and redrawing supplier qualification requirements across the region.
Growth Catalysts
- Australian Mining Fleet Modernization:State-level environmental regulators impose progressive diesel particulate limits that condition replacement cycles. Mining operators upgrade aging fleets with telematics-enabled machinery to maintain operational licenses.
- India's Urban Development Corridor:Infrastructure intensity across the Delhi-Mumbai-Bangalore axis generates sustained equipment demand for earthmoving and vertical construction tasks. Foundation work volume drives excavator deployment rates.
- Telematics Integration:Rental service providers adopt utilization optimization platforms across dispersed fleets. Asset tracking capabilities improve fleet turnover economics and reduce idle-time losses.
Market Restraints
- Powertrain Transition Costs:China's dual carbon goals and India's CEA efficiency mandates elevate electric powertrain development expenditures. Diesel engine margins compress as compliance investments accumulate.
- Import Certification Barriers:India's BIS certification requirements for cranes and concrete mixers block unapproved foreign equipment entry. Compliance timelines extend procurement lead times for international suppliers.
- Hydraulic System Supply Concentration:In-house production capabilities anchor domestic Chinese supply, limiting external component sourcing flexibility for regional assemblers.
Strategic Opportunities
- Southeast Asian Urban Zones:Electric powertrain pilot programs target development areas with strict noise ordinances. Battery-electric compact equipment addresses after-hours construction restrictions in dense metropolitan cores.
- Indonesia-Vietnam Transportation Infrastructure:Trenching and foundation work intensity across road and rail projects generates excavator demand above regional averages. Project pipelines extend equipment procurement visibility.
- Japan's METI Emission Tier Alignment:Stringent construction machinery standards limit import eligibility for non-compliant equipment. Early powertrain redesign investments position suppliers for premium market access.
Industry Challenges
- Residual Value Risk Management:Divergent enforcement calendars across Australia, China, and India complicate fleet valuation and secondary market timing. Stakeholders must weigh transition timelines against asset depreciation curves.
- After-Sales Service Network Density:Telematics-enabled machinery requires specialized diagnostic capabilities and technician training. Remote mining sites and dispersed urban projects strain service response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Construction Equipment Market |
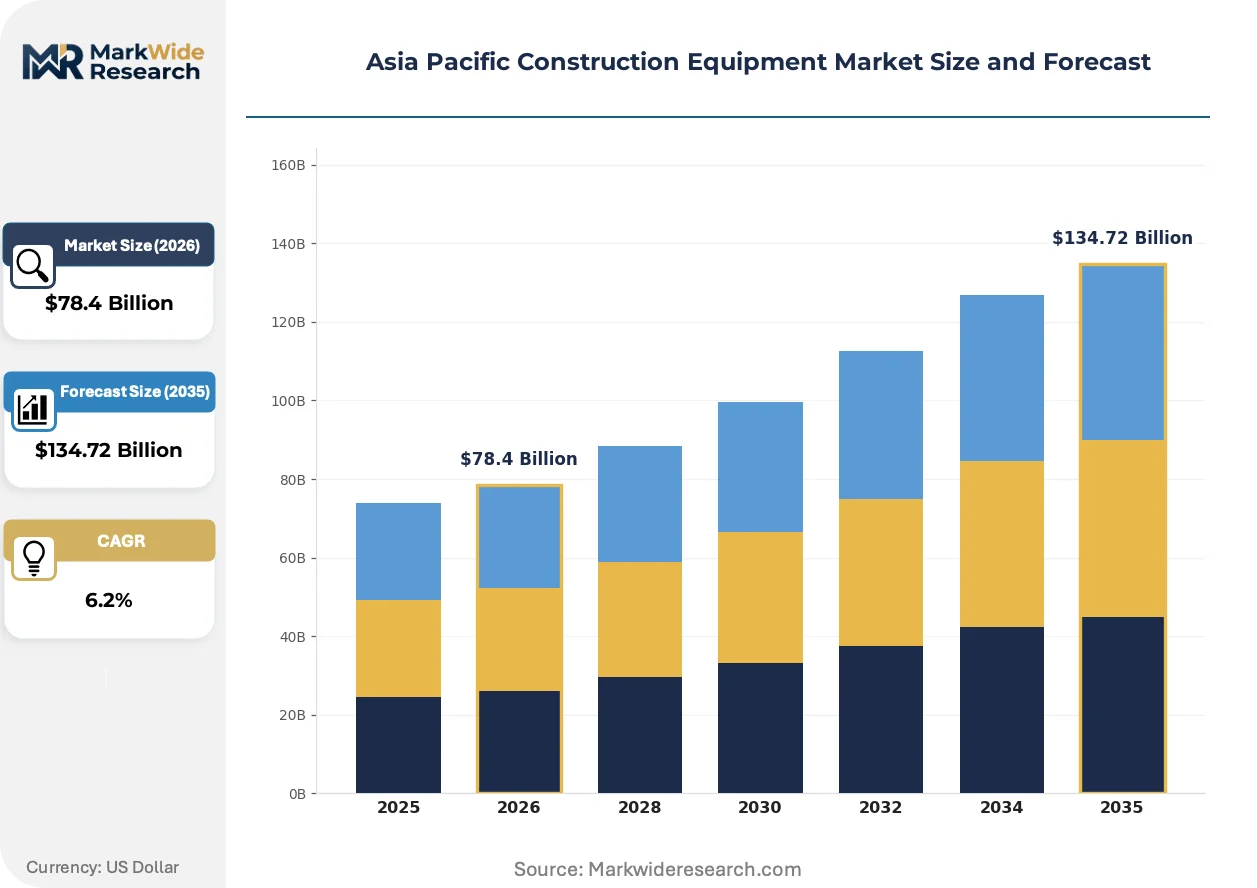
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers, Dump Trucks, Concrete Mixers Technology: Telematics, GPS Tracking, Autonomous Operation, Hydraulic Systems, Electric Powertrain, Diesel Engines End User Industry: Infrastructure Development, Mining Operations, Utilities Sector, Commercial Building, Transportation Projects, Urban Development Distribution Channel: Dealerships, Rental Service Providers, Direct Sales, Online Platforms, Franchise Networks, Equipment Auctions |
| Companies Covered | Volvo Construction Equipment, XCMG Group, Caterpillar, HD Hyundai Construction Equipment, Doosan Infracore, Komatsu, Sany Heavy Industry, Liebherr Group, Hitachi Construction Machinery, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Construction Equipment Market Strategic Shifts & Innovations
Equipment architecture is fragmenting into interoperable subsystems as regulatory pressure and operational complexity outpace integrated design cycles. This decomposition enables faster compliance adaptation and supplier specialization.
Battery-electric powertrain architecture is modularizing around swappable pack configurations and standardized motor-controller interfaces. Australian mining contractors pilot these systems in 24-hour continuous operations where rapid energy replenishment compresses downtime. This modularity is enabling equipment-as-a-service business models that transfer residual value risk from operators to manufacturers.
China's MIIT administers GB standards governing hydraulic efficiency and noise thresholds that domestic manufacturers must satisfy for market access. These technical mandates accelerate in-house component development and reduce reliance on imported hydraulic systems. Construction equipment producers redesign valve architectures and pump geometries to meet efficiency benchmarks while maintaining torque output parity with legacy diesel equivalents.
Rental channel consolidation is reshaping equipment procurement patterns across Asia Pacific project sites. Large contractors deploy multi-source strategies as single-supplier availability constraints intensify. Indonesia and Vietnam transportation projects exhibit the most pronounced shift, with project managers splitting excavator and compactor orders across competing rental fleets to secure delivery schedules.
Asia Pacific Construction Equipment Market Segmentation
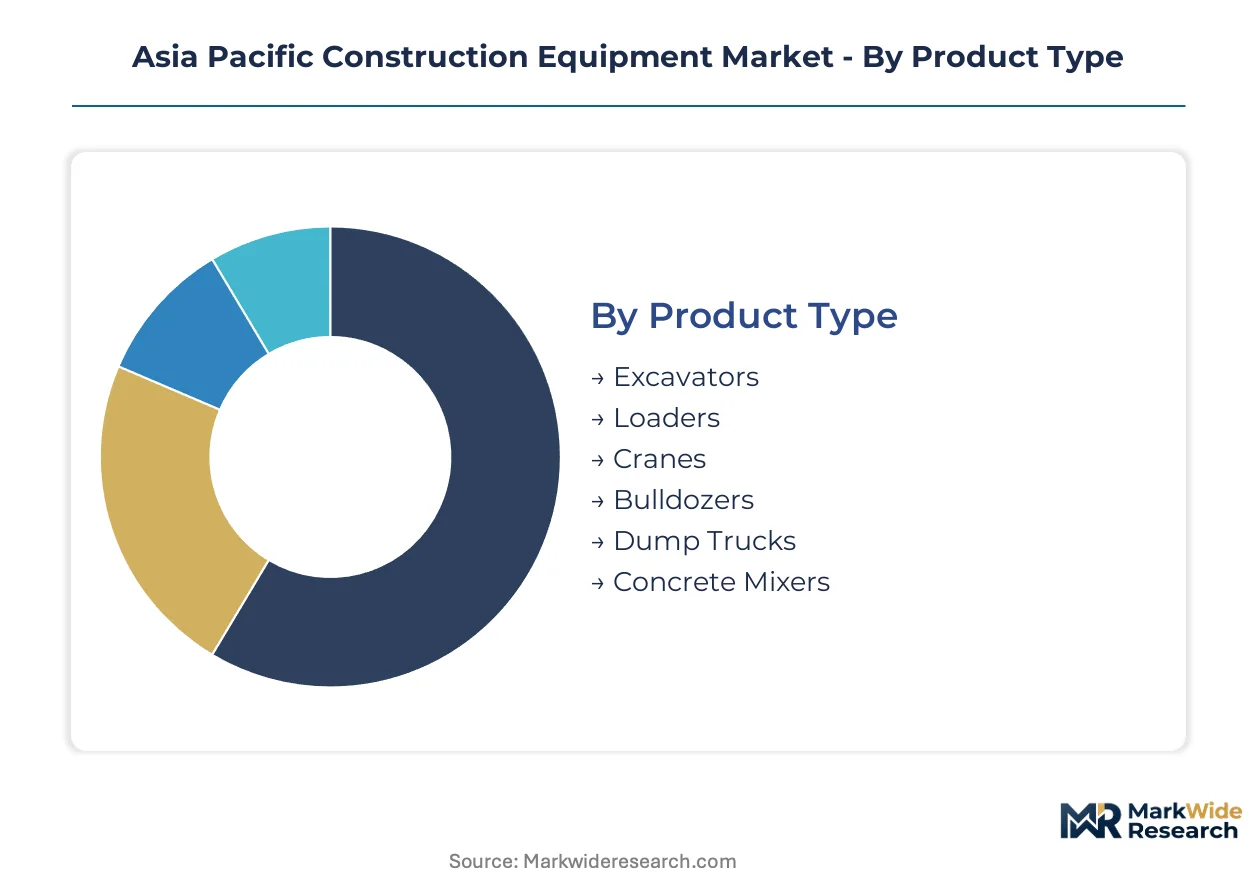
Segmentation in Asia Pacific construction equipment reveals how regulatory fragmentation and project-scale diversity create distinct procurement patterns. Buyers prioritize different specifications based on whether they operate under Australia's mining emission mandates, India's urban density constraints, or China's domestic content requirements.
Product Type:
Equipment selection hinges on soil conditions, project duration, and labor cost structures across the region's construction corridors.
- Excavators:Hydraulic crawler units dominate trenching and foundation work across Indonesia and Vietnam transportation projects. Demand concentrates in the Delhi-Mumbai-Bangalore urban development corridor where metro rail expansion drives long-reach and compact variants.
- Loaders:Wheel loaders handle material stockpiling at Australian mining sites and aggregate processing plants. Surface mining operators specify high-lift configurations for truck loading efficiency under state environmental license conditions.
- Cranes:Tower and mobile units serve vertical construction in dense metropolitan cores.
- Bulldozers:Track-type tractors perform land clearing and grading for infrastructure corridors.
- Dump Trucks:Articulated and rigid haulers move overburden at Australian open-cut operations.
- Concrete Mixers:Transit and volumetric units supply ready-mix for urban high-rise construction.
Excavators lead volumes today; electric powertrain variants across all product types are gaining share fastest.
Technology:
Technology adoption splits between compliance-driven upgrades and operational efficiency investments, with regulatory calendars determining deployment sequencing.
- Telematics:Integrated sensor platforms transmit utilization data, fault codes, and geolocation to fleet managers. Rental service providers deploy these systems most aggressively across dispersed Australian and Indian assets to minimize idle-time losses.
- Electric Powertrain:Battery-electric architectures with swappable pack configurations enable 24-hour continuous operations at pilot mining sites. Modular motor-controller interfaces support equipment-as-a-service models that shift residual value risk to manufacturers.
- GPS Tracking:Satellite-based location monitoring supports theft recovery and route optimization.
- Autonomous Operation:Remote and self-driving capabilities reduce labor exposure in hazardous extraction environments.
- Hydraulic Systems:High-efficiency valve architectures and pump geometries meet China's GB efficiency benchmarks.
- Diesel Engines:Compression-ignition powertrains retain installed-base dominance despite margin compression from emission compliance investments.
Telematics penetration is expanding most quickly; diesel engines still anchor the installed base.
End User Industry:
Industry verticals impose distinct duty cycles, environmental exposure, and financing structures on equipment procurement.
- Mining Operations:Australian surface and underground extraction sites demand ruggedized machinery with telematics integration to maintain operational licenses under state diesel particulate limits. Fleet replacement cycles compress as environmental regulators tighten progressive emission thresholds.
- Transportation Projects:Road and rail construction across Indonesia and Vietnam generates sustained excavator and compactor demand. Trenching intensity for bridge foundations and tunnel portals extends equipment procurement visibility across multi-year project pipelines.
- Infrastructure Development:Water, energy, and communications backbone projects require specialized earthmoving fleets.
- Utilities Sector:Power transmission and pipeline corridors need compact equipment for right-of-way maintenance.
- Commercial Building:High-rise construction in metropolitan cores specifies cranes and concrete placing equipment.
- Urban Development:Dense residential and mixed-use zones drive demand for low-noise, low-emission compact machinery.
Mining operations command the highest equipment spend per site; transportation projects are climbing the fastest.
Distribution Channel:
Channel selection reflects project scale uncertainty, capital constraints, and service network proximity across dispersed geographies.
- Rental Service Providers:Fleet owners aggregate utilization optimization platforms and maintenance capabilities across dispersed project sites. Large contractors deploy multi-source procurement strategies through competing rental networks to secure delivery schedules amid availability constraints.
- Dealerships:Manufacturer-authorized networks anchor parts availability and technician training in established markets. Sany Heavy Industry's extensive Chinese dealership footprint demonstrates how captive distribution supports domestic market penetration.
- Direct Sales:Large mining houses and government agencies purchase equipment without intermediary markup.
- Online Platforms:Digital marketplaces facilitate used equipment transactions and specification comparison.
- Franchise Networks:Semi-independent operators extend brand presence in secondary cities.
- Equipment Auctions:Secondary market clearinghouses manage fleet turnover and residual value realization.
Dealerships still handle the most transaction volume; rental service providers are expanding share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara mining district anchors equipment demand intensity across the Asia Pacific region. State environmental mandates compress fleet replacement cycles while telematics penetration rises among rental service providers.
Australia
Western Australian surface mining operations drive diesel-to-electric fleet conversions under progressive state particulate limits. The country's environmental regulators tighten emission thresholds quarterly. The Pilbara region hosts 24-hour continuous operations where swappable battery packs enable equipment-as-a-service models.
China
Domestic manufacturers redesign powertrain architectures to satisfy MIIT emission standards and GB hydraulic efficiency benchmarks. The ministry's dual carbon goals accelerate in-house component development. The Yangtze River Delta concentration houses captive hydraulic system production facilities serving regional assemblers.
India
Metro rail expansion across the Delhi-Mumbai-Bangalore corridor generates excavator demand for foundation and trenching work. BIS certification requirements for cranes and concrete mixers extend procurement lead times for international suppliers. The National Capital Region cluster concentrates rental fleet aggregation for multi-source contractor procurement.
Indonesia
Transportation infrastructure projects spanning road and rail networks sustain above-average equipment deployment rates. State procurement guidelines favor domestic content thresholds for public works. The Java corridor links Jakarta to Surabaya with multi-year project pipelines extending equipment visibility.
Japan
METI emission tiers limit import eligibility for non-compliant construction machinery. Domestic manufacturers invest early in powertrain redesign to secure premium market positioning. The Kanto industrial belt around Tokyo maintains stringent noise and efficiency standards for urban development zones.
Asia Pacific Construction Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and telematics integration. The vendor base splits between integrated manufacturers with captive component supply and assembly-focused operators sourcing hydraulic systems externally. Three archetypes dominate: mining-specialized heavy equipment builders, urban-focused compact machinery producers, and rental fleet aggregators with utilization platforms. Competitive moves concentrate on strategic partnerships for battery technology access and geographic expansion through dealership network acquisition.
Among Asia-Pacific-based manufacturers, Sany Heavy Industry and XCMG Group exemplify the integrated production archetype with captive hydraulic system capabilities. Komatsu occupies a position representing the mining-specialized tier with telematics-enabled fleet deployments. These three anchors demonstrate how regional players balance domestic content requirements against export qualification standards.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| XCMG Group |
| Caterpillar |
| HD Hyundai Construction Equipment |
| Doosan Infracore |
| Komatsu |
| Sany Heavy Industry |
| Liebherr Group |
| Hitachi Construction Machinery |
| Others |
Cost & Logistics Intelligence
Steel and high-grade alloy inputs flow from Chinese and Japanese mills through tiered fabrication stages before reaching equipment assemblers, with hydraulic component costs separating premium telematics-integrated machinery from standard diesel units across Australian mining contracts and Indian urban development zones.
Pricing Analysis
Input-cost pass-through from steel plate and hydraulic valve architectures shapes contract-based long-term offtake structures favored by Australian mining houses and Indian rental fleet aggregators. Price differentiation hinges on MIIT emission tier certification and telematics platform integration, with certified electric powertrain variants commanding premiums over legacy diesel equivalents. Pricing pressure stems from China's dual carbon goals elevating R&D amortization across domestic manufacturers. Mining operators show lowest price sensitivity due to operational license compliance imperatives; small urban contractors exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Hydraulic system supply rests on captive production facilities concentrated in China's Yangtze River Delta, Japanese precision component manufacturers, and South Korean pump specialists. Critical inputs include high-pressure steel forgings, electronic control modules, and rare-earth magnet materials for electric motor assemblies. Single-source vulnerability concentrates around proprietary valve architectures developed by integrated Chinese producers. Distribution runs through manufacturer-authorized dealership networks in established markets and rental service provider aggregators in fragmented procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electric powertrain variants where emission compliance premiums offset battery pack cost premiums, and in telematics-enabled fleet contracts where utilization optimization software captures recurring revenue streams.
For Market Incumbents: Anticipate compressed replacement cycles in Australian mining by securing swappable battery pack supply agreements before state particulate limits tighten further. Deepen backward integration into hydraulic control systems to defend against Chinese domestic content advantages. Prioritize technician certification programs for electric powertrain diagnostics as after-sales service density becomes the primary retention lever against rental channel consolidation. For New Entrants and Emerging Players: Begin with battery-electric compact excavators targeting Southeast Asian urban zones with strict noise ordinances and limited incumbent electric portfolios. Indonesia's transportation infrastructure pipeline offers the most penetrable geography given multi-year project visibility and fragmented rental procurement. Pursue equipment-as-a-service partnerships with regional rental aggregators to bypass capital-intensive dealership network buildouts. For Investors and Strategic Acquirers: Roll-up economics work for regional rental fleet aggregators because utilization optimization platforms create network effects that compound across dispersed asset bases. Five-to-ten-year viability hinges on telematics data monetization capabilities and electric fleet transition timing. Target acquisition archetypes: second-tier rental operators with dense Southeast Asian urban footprints and underinvested service infrastructure. Watch state-level emission enforcement calendars in Australia and MIIT standard revision timing in China as inflection indicators for residual value risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Systems | Captive valve production insulates margin pressure from Chinese domestic content advantages under MIIT standards. |
| Swappable Battery Pack Partnerships | Modular energy architecture enables 24-hour mining operations and equipment-as-a-service risk transfer models. |
| Telematics Platform Expansion | Utilization optimization software captures recurring revenue from rental service providers across dispersed Australian and Indian fleets. |
| Electric Powertrain Pilot Programs | Battery-electric compact equipment addresses noise ordinance restrictions in dense Southeast Asian metropolitan cores. |
| Dealership Network Acquisition | Regional footprint expansion accelerates parts availability and technician training density in secondary Indonesian and Vietnamese markets. |
Research Approach
Direct dialogue with mining fleet managers, rental service provider procurement directors, OEM product strategy leads, and aftermarket service heads combined with customs trade data, MIIT regulatory filings, state environmental regulator enforcement records, and equipment registration databases. Bottom-up equipment shipment analysis triangulates against top-down construction spend projections across the analysis window.
Market sizing outputs reflect segment-level modeling across product type, powertrain architecture, end-use industry, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis against historical fleet replacement patterns, project pipeline visibility, and regulatory enforcement trajectory assumptions. Industry-specific inputs include diesel particulate limit phase-in schedules, BIS certification timelines, and electric powertrain cost curves.
Caveats apply where accelerated MIIT standard revisions or unanticipated Australian state emission threshold adjustments could materially shift the outlook. Forecasts reflect assumptions around mining commodity price stability and infrastructure project financing availability. A small set of regulatory enforcement calendars and battery supply contract renegotiations warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Static Crane Market
Construction Equipment
Concrete Testers Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Casting Equipment Market