
 Track Mounted Gangway Market | 2026-2036
Track Mounted Gangway Market Size, Share, and Industry Trends Forecast 2026-2036
Track Mounted Gangway Market Intelligence
Skilled marine fabrication labor availability is redrawing competitive boundaries across the Track Mounted Gangway landscape. SafeRack leverages its Gulf Coast manufacturing footprint to anchor domestic supply chains for US port authorities. GREEN Manufacturing specializes in aluminum-intensive designs that dominate European offshore platform retrofits. Zarges competes through its modular platform architecture, extending configurability across naval and commercial vessel classes.
A track mounted gangway is a rail-guided personnel access bridge engineered to traverse variable elevations and horizontal offsets between dockside infrastructure and vessels or rolling stock, typically fabricated from marine-grade aluminum or galvanized steel with load ratings between 500 and 1,500 pounds. The system employs wheeled or trolley-based carriage assemblies that ride fixed tracks, enabling precise positioning during loading, unloading, and maintenance operations in corrosive maritime environments. Automated gangways are capturing premium margin pools as port operators prioritize remote-operated systems that reduce crew exposure during severe weather events. Fixed gangway configurations sustain dominant volume share in shipbuilding yards where permanent infrastructure justifies capital-intensive installations. Manual gangway variants retain cost-sensitive positioning across developing port clusters where electrification remains incomplete.
The US Coast Guard and OSHA enforce fall protection and load testing standards that dictate gangway certification cycles for domestic maritime facilities. The EU Machinery Directive and CE marking requirements shape product design parameters for manufacturers serving European port authorities and North Sea offshore operators. Classification societies including Lloyd's Register and DNV GL impose material traceability and weld qualification protocols that filter market access for non-compliant suppliers. Stakeholders must monitor evolving decarbonization mandates for port infrastructure, as shore power integration and electrified access systems reshape procurement specifications ahead of regulatory deadlines.
Market Dynamics
Port electrification mandates and offshore platform fleet renewal programs are compressing procurement cycles for automated track mounted gangway systems, forcing fabricators to reconfigure aluminum supply chains and weld qualification protocols around stricter EU F-Gas Regulation and Machinery Directive compliance thresholds.
Growth Catalysts
- EU F-Gas Regulation:Tightened material compliance thresholds accelerate aluminum-intensive gangway adoption across North Sea offshore retrofits, favoring suppliers with documented refrigerant-free fabrication processes.
- Automated trolley systems:Remote-operated carriage assemblies reduce crew exposure during severe weather events, capturing premium positioning among North American port authorities prioritizing operational safety.
- Shore power integration:Electrified access infrastructure at German Port of Hamburg cluster facilities creates bundled procurement specifications linking gangway electrification to vessel shore connection mandates.
Market Restraints
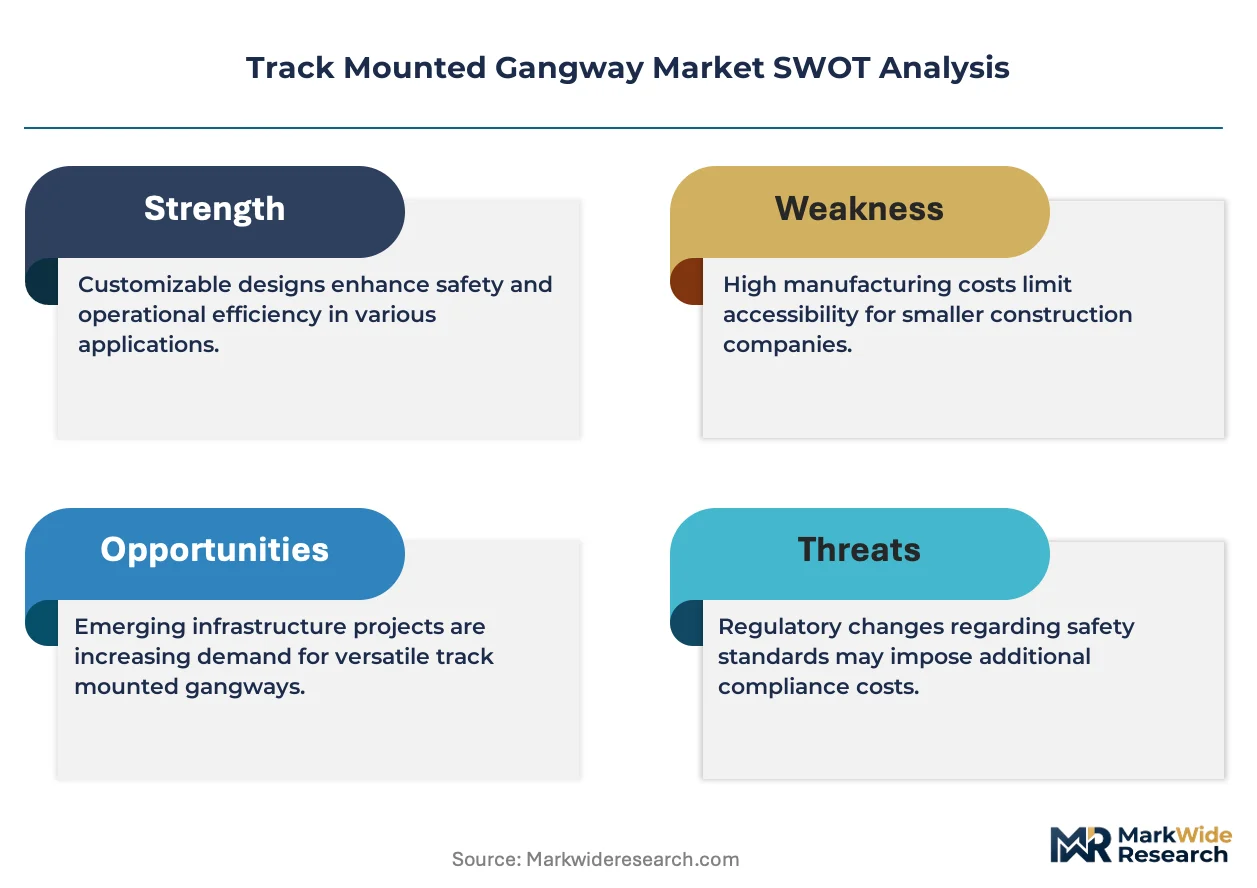
- Marine-grade aluminum pricing volatility:LME aluminum fluctuations and energy-intensive smelting costs compress fabrication margins, particularly for mid-tier suppliers lacking long-term billet contracts.
- Weld qualification bottlenecks:Lloyd's Register and DNV GL material traceability protocols filter market access, creating six-to-nine-month certification delays for non-incumbent fabricators.
- Fixed gangway substitution:Permanent shipyard installations sustain dominant volume share in newbuild corridors, limiting track mounted system penetration where capital-intensive infrastructure already exists.
Strategic Opportunities
- Developing port clusters:Manual gangway variants retain cost-sensitive positioning across Southeast Asian and West African facilities where electrification remains incomplete, offering volume expansion paths.
- Naval vessel configurability:Modular platform architectures extend across military procurement specifications, opening defense-funded retrofit programs with multi-year maintenance contracts.
- OSHA fall protection alignment:US Coast Guard coordinated enforcement creates certification-driven preference shifts, rewarding domestic fabricators with established testing laboratory relationships.
Industry Challenges
- Skilled marine fabrication labor scarcity:Certified aluminum welders and trolley assembly technicians concentrate in Gulf Coast and North Sea industrial corridors, constraining capacity expansion elsewhere.
- Legacy dock infrastructure integration:Retrofit projects face mechanical interface mismatches with existing bollard and fender systems, requiring custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Track Mounted Gangway Market |
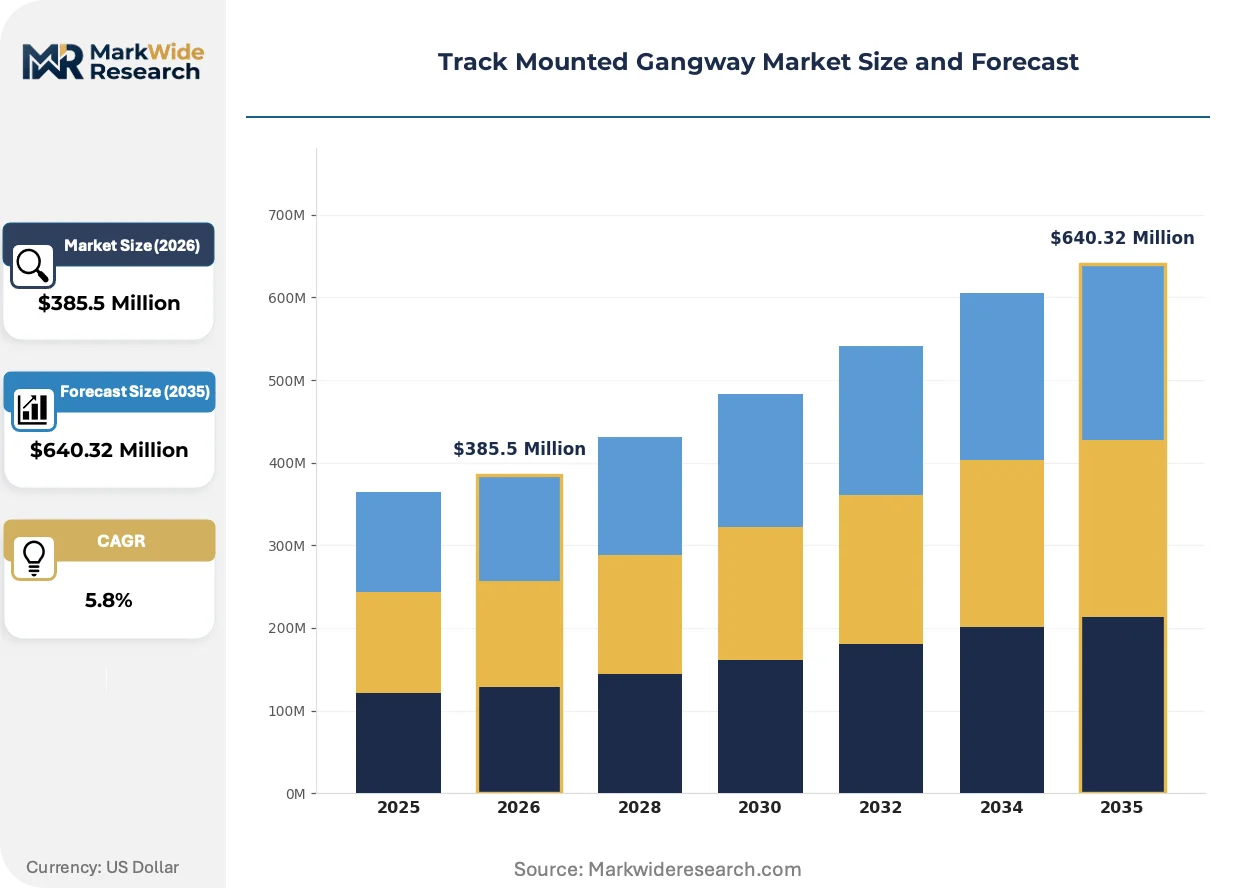
| Market Size in 2026 | $385.5 Million |
| Market Size in 2035 | $640.32 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Gangway, Fixed Gangway, Automated Gangway, Manual Gangway End User: Ports, Shipbuilding, Offshore Platforms, Railways Technology: Hydraulic, Electric, Pneumatic, Manual Application: Loading, Unloading, Maintenance, Transportation |
| Companies Covered | GREEN Manufacturing, S&S Technical, SafeRack, Zarges, JBT Corporation, Hemco Industries, Carbis Solutions, Cotterman, Bullard Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Track Mounted Gangway Market Strategic Shifts & Innovations
Corrosion-resistant coating chemistries and predictive maintenance sensor arrays are redefining asset lifecycle economics, while procurement specifications increasingly bundle gangway systems with broader port electrification packages.
Electroless nickel-phosphorus plating is fragmenting traditional hot-dip galvanization for trolley wheel assemblies and track surfaces in high-salinity environments. Offshore platform operators in the North Sea are specifying these coatings for twenty-year maintenance intervals. The technology is fragmenting supplier tiers, separating coating-qualified fabricators from commodity metal finishers.
The EU Machinery Directive's 2023 update tightened emergency-stop and remote-monitoring requirements for marine access equipment. Fabricators serving European port authorities must now integrate PLC-based safety systems with CE-marked components. German shipyards and Dutch offshore service operators are absorbing compliance costs through extended warranty pricing.
Buyer consolidation among multinational terminal operators is compressing vendor qualification cycles and unbundling after-sales service contracts from initial equipment procurement. Third-party maintenance providers are capturing recurring revenue streams previously held by original manufacturers. This pattern concentrates in Rotterdam-Antwerp corridor container terminals and US East Coast port authority clusters.
Track Mounted Gangway Market Segmentation
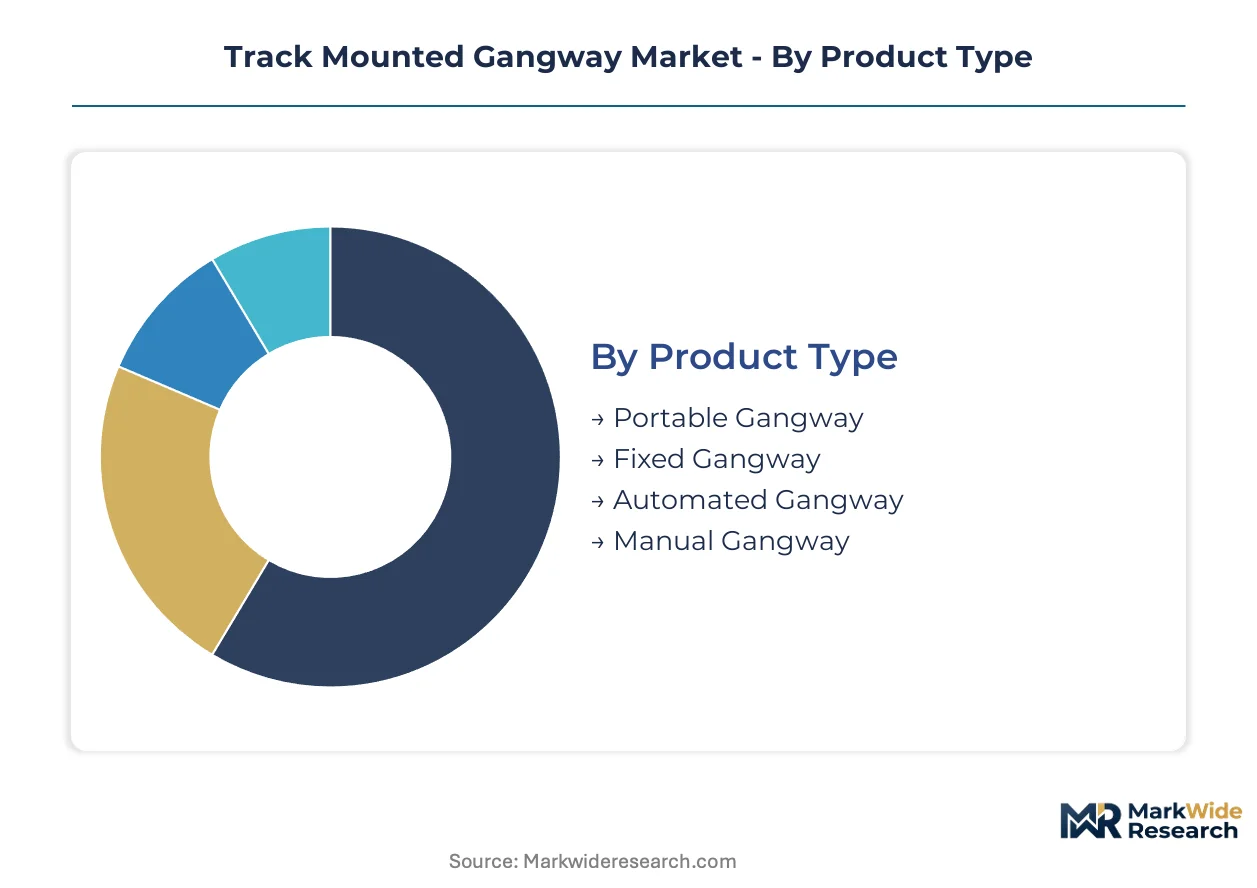
Segmentation in the track mounted gangway market reveals how substitution pressures and procurement specifications fragment demand across port infrastructure, offshore platforms, and shipbuilding corridors. Understanding these divisions exposes where automated systems displace manual configurations and where fixed installations resist track-based alternatives.
Product Type:
Fixed gangway configurations face the strongest substitution pressure from automated track mounted systems as port operators prioritize remote-operated access bridges that reduce crew exposure during severe weather events.
- Portable Gangway:Modular aluminum structures designed for temporary deployment across multiple berths without permanent track installation. Demand concentrates in developing port clusters where capital constraints limit fixed infrastructure investment, particularly across Southeast Asian facilities lacking electrification.
- Fixed Gangway:Permanent rail-guided installations with welded track foundations and integrated trolley assemblies rated for continuous duty cycles. Shipbuilding yards in Germany's Port of Hamburg cluster sustain dominant procurement volumes where newbuild corridors justify capital-intensive infrastructure.
- Automated Gangway:PLC-controlled carriage systems with remote monitoring capabilities compliant with EU Machinery Directive emergency-stop requirements. North Sea offshore platform operators specify these for twenty-year maintenance intervals.
- Manual Gangway:Hand-operated trolley configurations with mechanical braking and basic fall protection for low-frequency access operations. West African port authorities favor these where skilled maintenance labor remains scarce.
Fixed gangway anchors the volume base while automated gangway gains share at the steepest rate.
End User:
Cost tier differentiation separates premium-specification offshore platform procurement from price-sensitive railway maintenance contracts, with port authorities occupying the mid-tier volume position.
- Ports:Container terminals and bulk cargo facilities requiring gangway systems compatible with variable vessel freeboard heights and shore power integration mandates. German and Dutch operators bundle electrified access with vessel shore connection specifications.
- Shipbuilding:New construction yards demanding permanent track infrastructure with load ratings exceeding 1,500 pounds for heavy component transport. North Sea corridors sustain concentrated demand despite fixed gangway substitution headwinds.
- Offshore Platforms:North Sea oil and gas installations specifying corrosion-resistant coatings and predictive maintenance sensor arrays for extended asset lifecycles. EU F-Gas Regulation compliance filters supplier qualification.
- Railways:Rolling stock maintenance depots utilizing gangway systems for elevated platform access during component replacement operations. Manual configurations dominate where electrification remains incomplete.
Shipbuilding commands the largest procurement volumes while offshore platforms deliver the highest margin realization per unit.
Technology:
Application intensity varies dramatically across technology tiers, with hydraulic systems dominating heavy-load offshore operations and electric configurations capturing port electrification mandates.
- Hydraulic:High-pressure fluid power systems delivering precise positioning control for variable elevation adjustments in corrosive maritime environments. Offshore platform retrofits specify these for dynamic positioning compatibility.
- Electric:Motor-driven trolley assemblies integrated with shore power infrastructure and PLC-based safety systems. EU Machinery Directive compliance requirements accelerate adoption across Rotterdam-Antwerp corridor terminals.
- Pneumatic:Compressed air actuation for explosion-risk environments where electrical ignition hazards restrict alternative technologies. Niche positioning in specific offshore chemical handling facilities.
- Manual:Mechanical leverage and hand-crank operation without external power dependencies. Developing port clusters retain these where grid reliability and maintenance technician availability constrain electrification.
Electric technology expands most quickly under regulatory pressure while hydraulic retains offshore platform dominance.
Application:
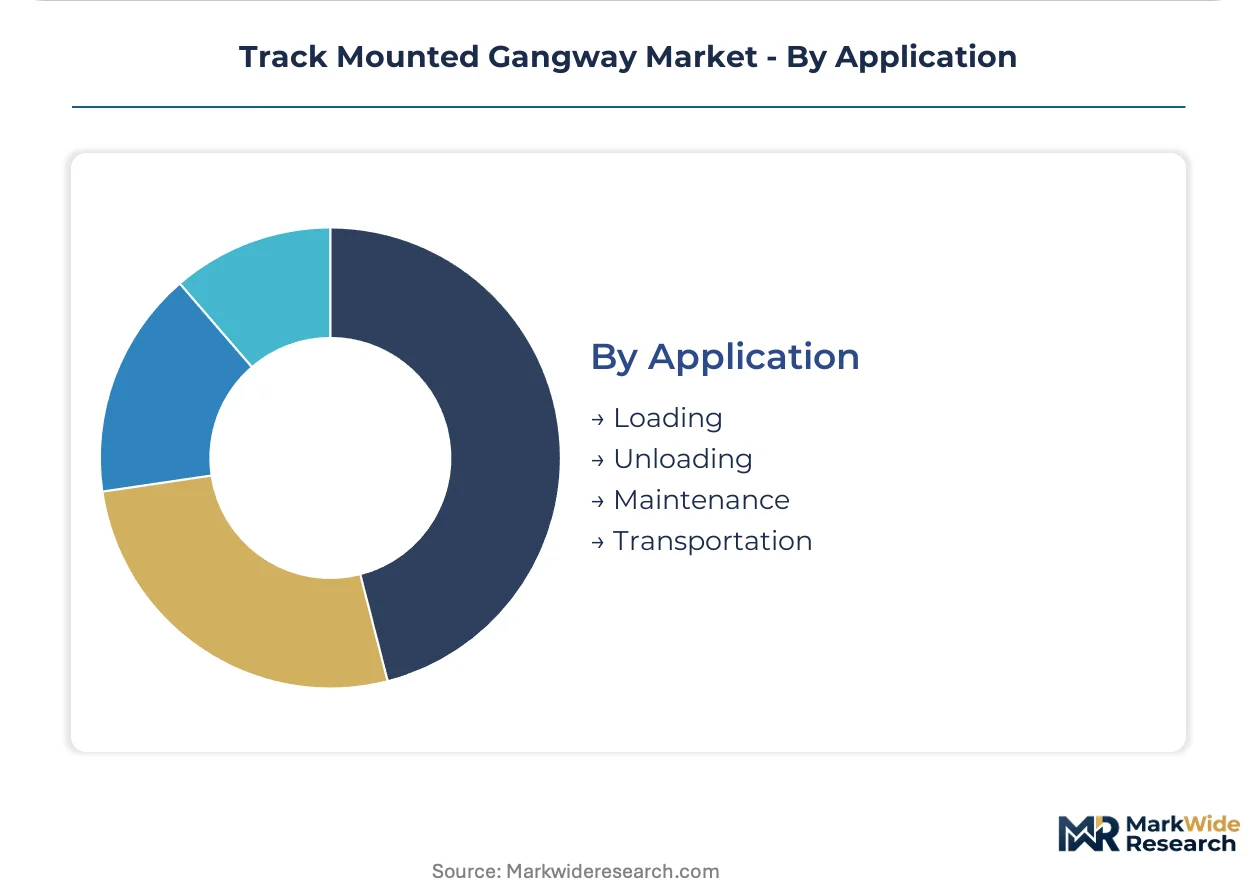
Customer type segmentation separates continuous-duty loading operations from intermittent maintenance access, with transportation applications representing emerging demand from railway rolling stock corridors.
- Loading:High-frequency cargo transfer operations requiring automated positioning and integration with terminal operating systems. Container terminals prioritize these for throughput optimization.
- Unloading:Bulk material discharge operations with dust suppression and spill containment specifications. Mineral export facilities drive procurement in West African and Australian port clusters.
- Maintenance:Scheduled inspection and repair access with extended dwell times and variable crew sizing. Offshore platforms specify predictive maintenance sensor integration.
- Transportation:Personnel movement between dockside infrastructure and vessels or rolling stock without cargo handling. Railway depots utilize these for crew boarding at elevated platforms.
Loading operations anchor procurement volumes while transportation applications climb the fastest as railway corridor investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation enforcement anchors European procurement specifications, while US Coast Guard mandates and developing port electrification programs across Asia-Pacific and Latin America fragment demand patterns across regulatory jurisdictions.
United States
Port authorities along the Gulf Coast and US East Coast prioritize OSHA-aligned fall protection systems for container terminal retrofits. US Coast Guard certification cycles dictate gangway procurement timelines for domestic maritime facilities. Houston-Galveston and New Orleans port clusters absorb automated trolley systems as hurricane-season operational safety investments.
Germany
Shore power integration mandates at Hamburg and Bremerhaven terminals bundle electrified gangway specifications with vessel shore connection infrastructure. EU Machinery Directive compliance filters supplier qualification for North Sea offshore retrofits. German shipyards in the Port of Hamburg cluster sustain fixed gangway procurement volumes for newbuild corridors.
Netherlands
Rotterdam-Antwerp corridor terminal operators compress vendor qualification cycles through buyer consolidation. EU F-Gas Regulation material traceability requirements accelerate aluminum-intensive gangway adoption. Dutch offshore service operators absorb PLC-based safety system compliance costs through extended warranty pricing structures.
China
State-owned port groups in Shanghai and Ningbo-Zhoushan drive container terminal automation investments. GB standards and MIIT industrial policy shape domestic fabrication specifications for marine access equipment. Yangtze River Delta shipyards concentrate manual gangway production for cost-sensitive Southeast Asian export markets.
Brazil
Mineral export facilities in Santos and Paranaguá drive bulk cargo unloading gangway procurement. ANVISA and national maritime regulator protocols filter equipment import certification timelines. Developing electrification gaps in Northeast port clusters sustain manual gangway positioning for intermittent maintenance access operations.
Track Mounted Gangway Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Gulf Coast and North Sea fabrication corridors concentrating certified aluminum welding capacity. The structure rewards documented refrigerant-free processes and Lloyd's Register weld qualification protocols. Three archetypes dominate: integrated port infrastructure suppliers, aluminum-intensive offshore specialists, and modular platform configurability providers. Competitive moves center on strategic partnerships with classification societies and geographic expansion into developing port clusters lacking electrification.
Among North American fabricators, SafeRack occupies a position within the integrated port infrastructure tier, while GREEN Manufacturing exemplifies aluminum-intensive specialization for offshore platform retrofits. Zarges anchors the modular configurability archetype, representing European engineering approaches to naval and commercial vessel specifications. These three companies collectively illustrate how regulatory compliance documentation and fabrication corridor proximity filter market access across distinct procurement channels.
| Leading Market Players |
|---|
| GREEN Manufacturing |
| S&S Technical |
| SafeRack |
| Zarges |
| JBT Corporation |
| Hemco Industries |
| Carbis Solutions |
| Cotterman |
| Bullard Company |
| Others |
Cost & Logistics Intelligence
Electroless nickel-phosphorus plating displacing hot-dip galvanization for trolley assemblies is redrawing supplier geography toward coating-qualified fabricators in Germany and the Netherlands while compressing margin pools for commodity metal finishers lacking corrosion-resistant process documentation.
Pricing Analysis
North Sea offshore retrofits command 25-40% premiums over Southeast Asian port installations due to EU F-Gas Regulation compliance documentation and Lloyd's Register weld qualification requirements. Three-tier pricing structure across premium automated systems, standard fixed configurations, and economy manual variants separates buyers by certification grade and after-sales service bundling. Price erosion runs through mid-tier suppliers as buyer consolidation among Rotterdam-Antwerp terminal operators compresses vendor margins. Railway maintenance depots exhibit highest price sensitivity, while offshore platform operators prioritize lifecycle cost over initial procurement outlay.
Supply Chain Analysis
Strategic stockpiling of marine-grade aluminum billet concentrates among Gulf Coast and North Sea fabricators with long-term smelter contracts, while just-in-timematerial flows dominate manual gangway assemblers serving developing port clusters. Germany, the United States, and China anchor fabrication capacity, with raw material draws from Norwegian smelters and Australian bauxite sources. Single-source vulnerability concentrates in certified aluminum welder availability across Gulf Coast and Hamburg industrial corridors. Distribution runs through OEM-direct channels for automated systems and regional distributors for manual configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party maintenance providers are capturing recurring revenue streams previously held by original manufacturers, expanding faster than hardware procurement as buyer consolidation unbundles after-sales service contracts from initial equipment sales.
For Market Incumbents: Consolidate certification laboratory relationships to defend against six-to-nine-month Lloyd's Register and DNV GL qualification delays threatening market access. Deepen backward integration into marine-grade aluminum billet supply through long-term Norwegian smelter contracts, insulating margin compression from LME price volatility. Channel control through exclusive service agreements with Rotterdam-Antwerp terminal operators blocks emerging competitors from aftermarket revenue capture.
For New Entrants and Emerging Players: Lead with modular platform architectures targeting naval vessel retrofit programs where multi-year maintenance contracts and defense-funded procurement cycles offset initial certification investment. West African and Southeast Asian developing port clusters offer the most penetrable white space, with manual gangway demand persisting where electrification gaps constrain automated system adoption. Partner with regional distributors possessing established customs clearance capabilities to circumvent ANVISA and national maritime regulator import bottlenecks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum-intensive offshore specialists possessing documented refrigerant-free fabrication processes and twenty-year maintenance interval track records. Five-to-ten-year viability hinges on shore power integration mandate acceleration across EU port authorities. Monitor EU Machinery Directive update implementation as inflection indicator for PLC-based safety system compliance cost absorption capacity among target fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Partnership | Lloyd's Register weld qualification protocols filter market access for compliant suppliers. |
| Long-term Aluminum Billet Contract | Norwegian smelter agreements insulate fabrication margins from energy-intensive pricing volatility. |
| Third-party Maintenance Capability | Rotterdam-Antwerp terminal operators unbundle service contracts from initial equipment procurement. |
| Modular Platform Architecture | Naval vessel configurability extends across military procurement specifications with multi-year contracts. |
| Coating Process Qualification | Electroless nickel-phosphorus plating documentation separates premium-tier fabricators from commodity finishers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating port authority procurement managers, offshore platform maintenance directors, shipyard project engineers, and certified aluminum welding supervisors. Secondary validation drew from Lloyd's Register certification databases, EU Machinery Directive implementation notices, SEC filings of listed marine equipment suppliers, and customs trade records for aluminum gangway exports. Bottom-up installation counts across Hamburg, Rotterdam, and Houston port clusters were triangulated against top-down market sizing derived from offshore platform fleet renewal program disclosures.
Across the analysis window, projections integrate product type segmentation by automation level, end-user segmentation across port, shipbuilding, offshore, and railway channels, and technology segmentation distinguishing electric, hydraulic, pneumatic, and manual configurations. CAGRs were derived from regression analysis against port electrification investment flows and offshore platform capital expenditure cycles. Forecast inputs incorporate EU F-Gas Regulation compliance cost absorption rates and OSHA fall protection enforcement intensity variations across US Coast Guard districts.
Forecasts assume regulatory continuity in EU F-Gas Regulation and Machinery Directive regimes; material policy shifts would require re-modeling. Aluminum price volatility, weld qualification bottleneck duration, and buyer consolidation pace among multinational terminal operators represent specific revision triggers. Revision becomes warranted when certified marine fabrication labor scarcity crosses capacity expansion constraints in Gulf Coast and North Sea corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Part Feeder Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Street Cleaning Machine Market