
 United States Commercial Real Estate Market | 2026-2036
United States Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Real Estate Market Outlook
Institutional capital deployment is rewriting the competitive map of US commercial real estate. Blackstone Inc. leverages its scale advantage across multiple property types and investment strategies. Hines anchors development activity in gateway metros with its vertically integrated platform. Starwood Capital Group competes through opportunistic positioning in distressed and transitional assets.
United States commercial real estate encompasses income-producing properties including office towers, retail centers, industrial warehouses, and hospitality assets, typically valued through discounted cash flow models using capitalization rates derived from comparable transactions and lease rollover schedules. Its primary commercial purpose is to generate risk-adjusted returns for capital providers while facilitating business operations across the national economy. Industrial assets lead transaction velocity as e-commerce fulfillment requirements reshape logistics networks, while value-add strategies capture widening margin pools where renovation premiums exceed construction cost inflation. Core office holdings in coastal gateway cities face structural repricing pressure as hybrid work protocols persist.
The Securities and Exchange Commission governs REIT disclosure standards and investor protections, while the Department of Energy enforces building efficiency benchmarks through ASHRAE-derived codes that affect retrofit economics and obsolescence risk. State-level rent control statutes in California and New York constrain income growth projections for multifamily and retail assets. Stakeholders must monitor interest rate trajectories and regional bank lending capacity as these factors determine acquisition leverage availability and refinancing viability.
Market Dynamics
Institutional capital rotation into Sun Belt logistics corridors is compressing cap rate spreads and forcing repricing across secondary metros, while the Inflation Reduction Act's clean energy retrofit mandates reshape obsolescence risk calculations for aging office stock.
Growth Catalysts
- Inflation Reduction Act incentives:Tax credits for energy-efficient retrofits are accelerating capital deployment into building electrification and solar integration across Class B and C office assets.
- E-commerce fulfillment densification:Last-mile logistics requirements from Amazon, Walmart, and Target are driving speculative industrial development in Dallas-Fort Worth and Central Florida submarkets.
- Life sciences cluster formation:NIH funding concentration and biotech venture formation in Boston, San Diego, and Research Triangle Park is absorbing specialized lab and R&D space.
Market Restraints
- Regional bank lending contraction:Stress on balance sheets at mid-tier institutions is constraining acquisition financing for sub-$50 million transactions in secondary and tertiary markets.
- Structural obsolescence in coastal gateway office:Hybrid work permanence in San Francisco and Manhattan is compressing effective rents below operating expense burdens for 1980s-vintage towers.
- Construction cost escalation:Steel and concrete input volatility, compounded by skilled labor shortages in electrical and HVAC trades, is eroding development pro forma yields.
Strategic Opportunities
- Data center conversion of obsolete retail:Power-dense big-box shells in suburban Chicago and Northern Virginia are being repositioned for hyperscaler colocation demand.
- Build-to-rent single-family housing:Institutional SFR platforms are aggregating scattered-site portfolios in Phoenix, Atlanta, and Charlotte to capture rent growth from millennial household formation.
- Cold storage infrastructure gaps:Temperature-controlled warehouse supply deficits in the Interstate 35 corridor are supporting development premiums for automated facilities serving grocery and pharmaceutical distribution.
Industry Challenges
- Environmental site assessment delays:Phase II remediation timelines for brownfield industrial acquisitions in legacy manufacturing corridors are extending hold periods and diluting IRR targets.
- Property tax assessment volatility:Mass appraisal methodologies in Texas and Florida are producing contested valuations that disrupt debt service coverage ratios and lender underwriting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Real Estate Market |
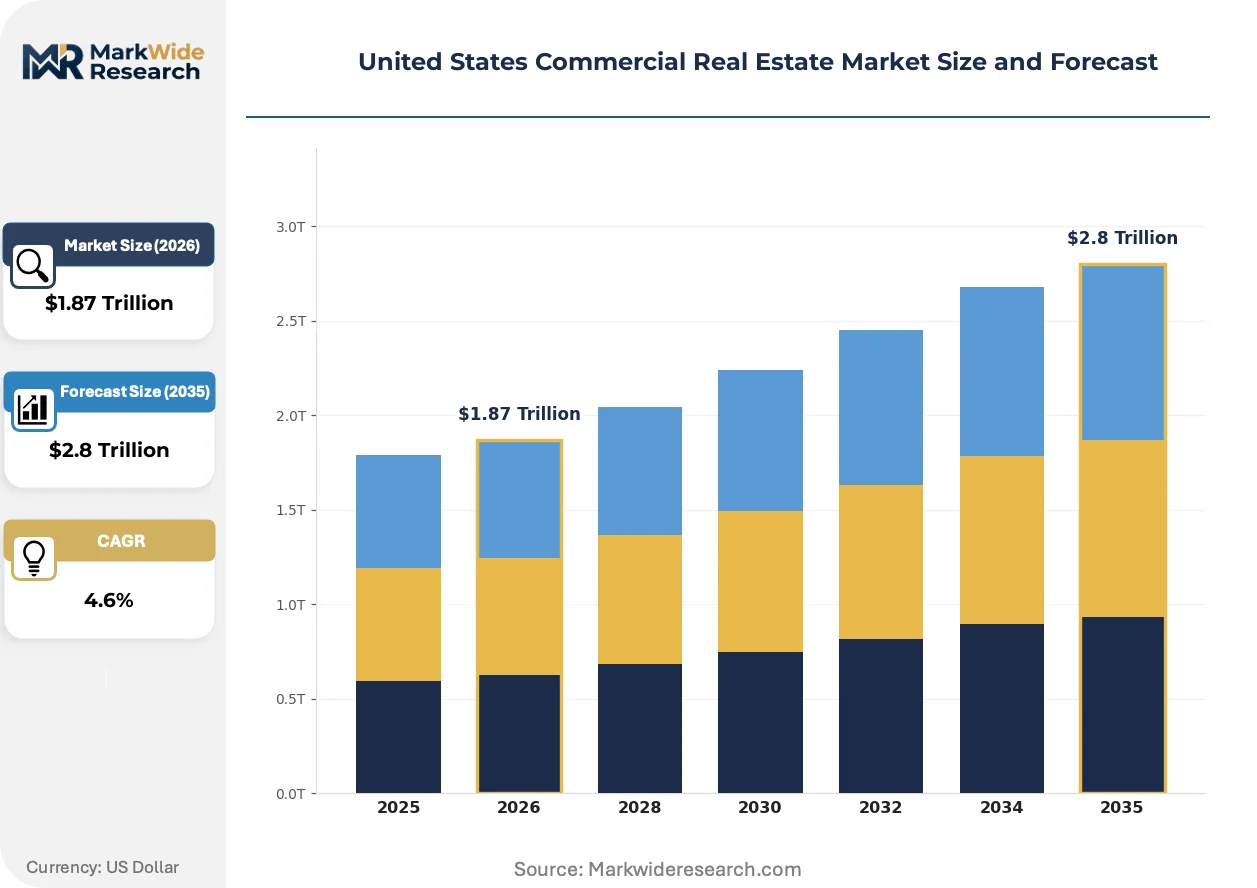
| Market Size in 2026 | $1.87 Trillion |
| Market Size in 2035 | $2.8 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Investment Strategy: Value-Add, Core, Opportunistic, Development Client Type: Institutional Investors, Private Equity, REITs, Family Offices Transaction Size: Small, Medium, Large, Mega |
| Companies Covered | Hines, Nuveen Real Estate, Blackstone Inc., Starwood Capital Group, Invesco Investment Services, Inc., Brookfield, PGIM Real Estate Inc., LaSalle Investment Management, CBRE Investment Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Real Estate Market Strategic Shifts
Smart building systems and predictive maintenance platforms are migrating from pilot installations to portfolio-wide standards, compressing operating expense ratios and redefining asset competitiveness in institutional quality tiers.
Digital twin technology is migrating from design-phase visualization to operational optimization, enabling real-time energy and space utilization monitoring across multi-asset portfolios. Blackstone and Prologis are deploying these platforms at scale across industrial and logistics holdings. The structural consequence is a widening performance gap between technology-enabled assets and legacy buildings with manual building management systems.
The Securities and Exchange Commission's climate disclosure rules are mandating granular emissions reporting and third-party verification for REITs and institutional owners. This is accelerating capital allocation toward assets with existing LEED or BREEAM certifications and defunding speculative development without clear decarbonization pathways. Sun Belt industrial and life sciences assets face the steepest compliance cost escalation given their concentration of new institutional capital.
Occupier requirements for flexibility and shorter commitment horizons are fragmenting traditional ten-year lease structures into modular term arrangements with expansion and contraction options. Landlords in Austin and Nashville are responding with speculative core-and-shell deliveries and tenant improvement allowances rather than pre-leasing commitments. This shift is most visible in technology and professional services verticals where headcount volatility outpaces real estate planning cycles.
United States Commercial Real Estate Market Segmentation
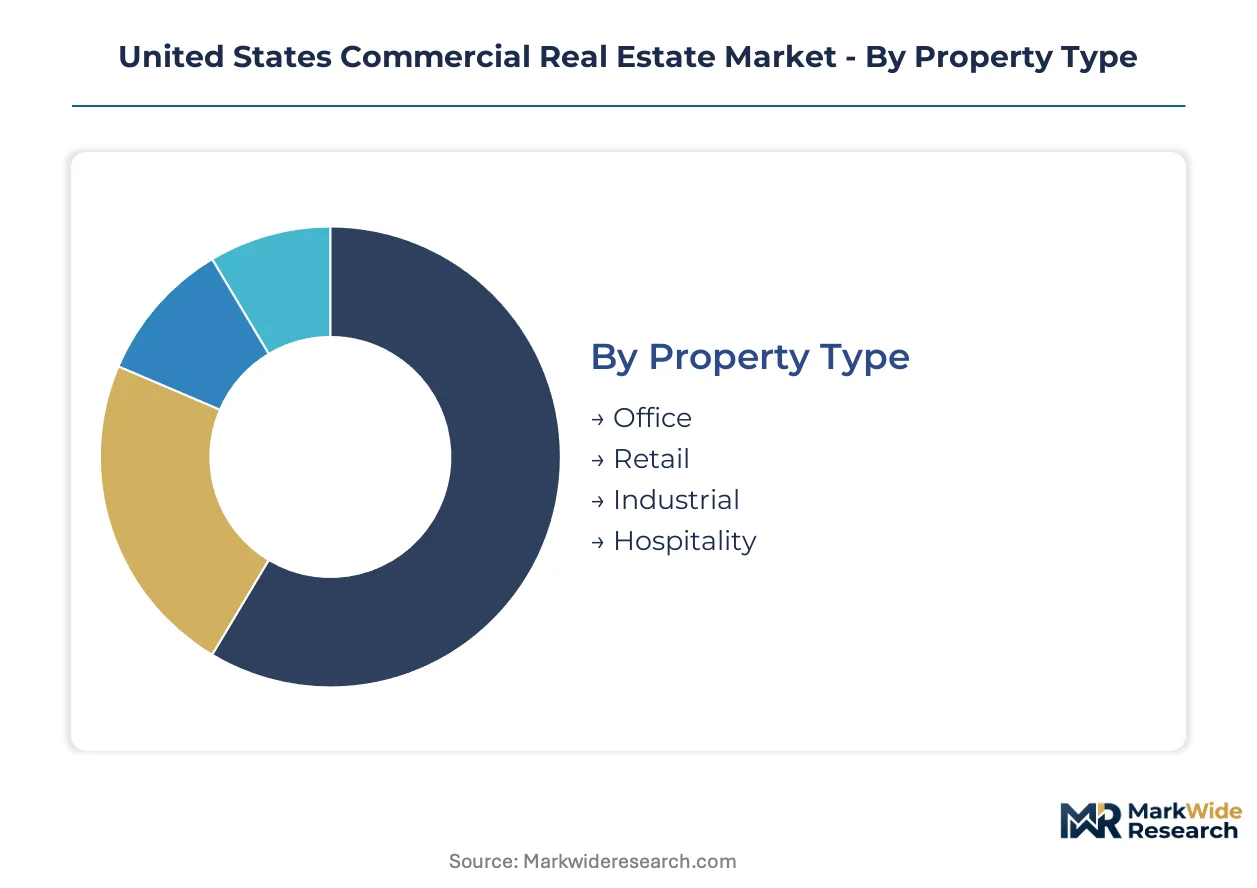
Property type classification drives capital allocation decisions across US commercial real estate, with each segment exhibiting distinct risk-return profiles and sensitivity to macroeconomic cycles. Investment strategy segmentation determines leverage levels, hold periods, and operational intensity required from asset managers.
Property Type:
Mature segments dominate institutional portfolios, while emerging subcategories capture yield compression from structural demand shifts.
- Office:Class A towers in gateway cities face repricing pressure from hybrid work permanence, with effective rents in San Francisco and Manhattan compressing below operating expense burdens for 1980s-vintage stock. Value-add opportunities concentrate in energy retrofit mandates under IRA incentives.
- Industrial:Logistics warehouses and fulfillment centers absorb the majority of institutional capital deployment, driven by e-commerce densification requirements from Amazon, Walmart, and Target across Dallas-Fort Worth and Central Florida submarkets. Cold storage and automated facilities command development premiums.
- Retail:Power-dense big-box shells in suburban Chicago and Northern Virginia are repositioning for hyperscaler data center colocation demand. Neighborhood centers with grocery anchors retain stable cash flow profiles.
- Hospitality:Select-service assets in Sun Belt leisure corridors recover occupancy faster than full-service urban properties dependent on corporate group business.
Industrial handles the majority of throughput; data center conversion of obsolete retail is gaining share fastest.
Investment Strategy:
Cost tier segmentation separates fee structures, operational intensity, and return hurdle requirements across the capital stack.
- Core:Stabilized, fully leased assets in primary markets generate current income with minimal operational intervention. Cap rate compression in Sun Belt logistics corridors is forcing repricing across secondary metros.
- Value-Add:Renovation premiums exceeding construction cost inflation capture widening margin pools where lease rollover schedules permit mark-to-market repricing. Active management requirements demand vertically integrated platforms.
- Opportunistic:Distressed and transitional assets compete on sourcing relationships and execution speed. Starwood Capital Group anchors this segment through specialized workout capabilities.
- Development:Ground-up construction carries entitlement risk and input cost volatility in steel and concrete. Skilled labor shortages in electrical and HVAC trades erode pro forma yields.
Core strategies anchor institutional allocations; opportunistic positioning climbs fastest on risk-adjusted return targets.
Client Type:
Volume concentration varies by transaction scale and operational capability requirements.
- Institutional Investors:Pension funds and sovereign wealth vehicles deploy through separate accounts and commingled funds, prioritizing governance standards and reporting transparency.
- Private Equity:Blackstone Inc. leverages scale advantage across multiple property types with shorter hold periods and higher leverage tolerance than core capital.
- REITs:Publicly traded vehicles face SEC climate disclosure mandates requiring granular emissions reporting and third-party verification, accelerating allocation toward LEED-certified assets.
- Family Offices:Direct ownership structures permit longer hold periods and bespoke asset management without fund-level fee drag.
Institutional investors deploy the deepest capital pools; private equity vehicles expand most quickly on dry powder accumulation.
Transaction Size:
Geography determines financing source availability and competitive bidding dynamics.
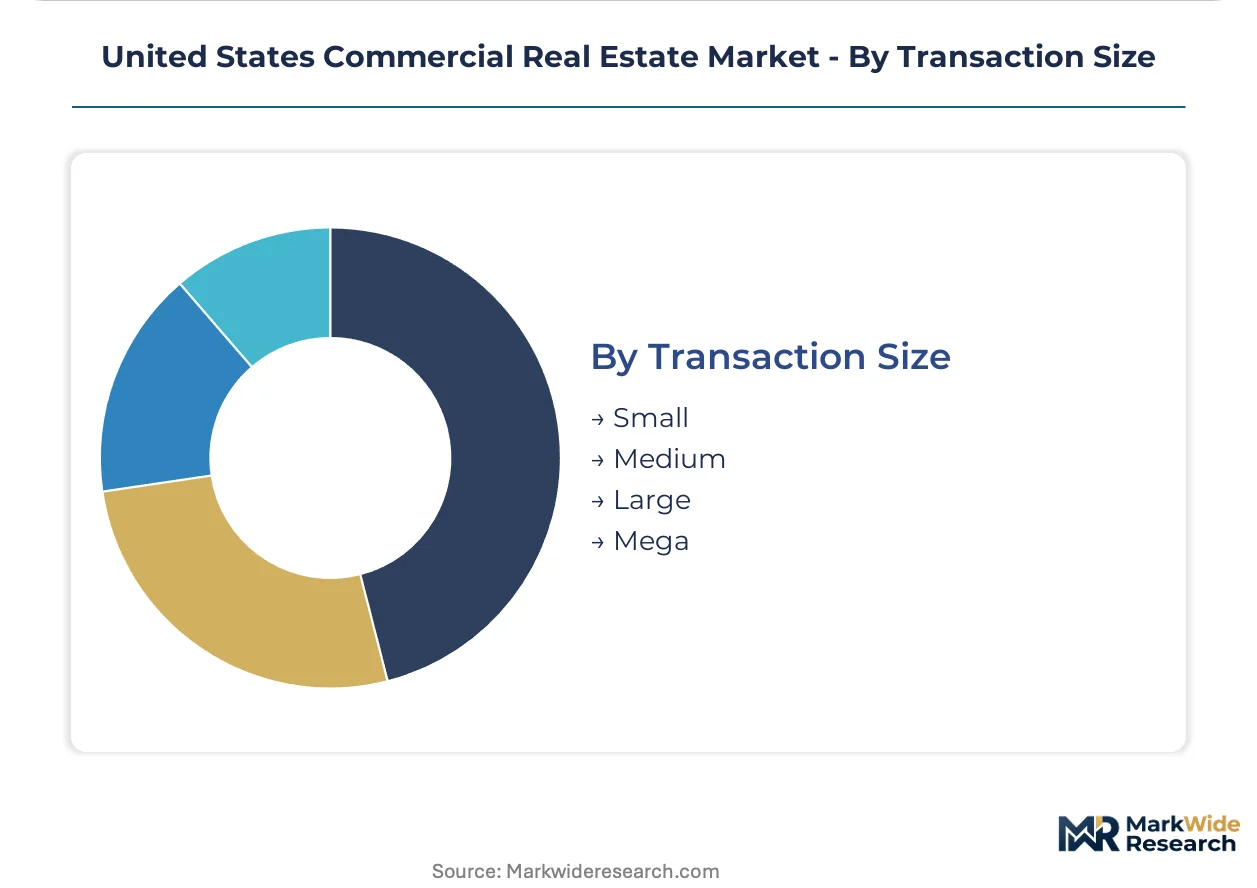
- Small:Sub-$50 million acquisitions face constrained financing from regional bank lending contraction, extending hold periods for sponsors dependent on mid-tier institution balance sheets.
- Medium:$50-200 million transactions attract institutional capital with operational platforms capable of active asset management.
- Large:$200-500 million deals concentrate in gateway market office and industrial portfolios with established tenant credit profiles.
- Mega:Platform acquisitions and portfolio trades above $500 million require club arrangements or sovereign wealth co-investment structures.
Medium transactions handle the majority of deal flow; mega deals capture the steepest expansion trajectory on portfolio rationalization by listed REITs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC governs disclosure standards for institutional capital deployment across US commercial real estate, while state-level regulators shape local market conditions through rent control statutes and property tax methodologies.
Southeast
Technology firms expanding distribution center footprints across Florida and Georgia are accelerating demand for industrial assets. Florida's mass appraisal methodologies produce contested valuations that disrupt debt service coverage ratios. Miami and Tampa submarkets absorb speculative industrial development from Amazon and Target fulfillment requirements.
Southwest
Build-to-rent single-family housing platforms aggregate scattered-site portfolios in Phoenix to capture millennial household formation. Arizona's property tax assessment volatility extends hold periods for sponsors dependent on regional bank financing. Dallas-Fort Worth anchors logistics corridor development with cold storage infrastructure gaps supporting automated facility premiums.
Northeast Corridor
NIH funding concentration and biotech venture formation in Boston absorbs specialized lab and R&D space. New York's rent control statutes constrain income growth projections for multifamily assets. Manhattan and San Francisco face structural repricing pressure as hybrid work permanence compresses effective rents below operating expense burdens for 1980s-vintage office towers.
Pacific Northwest
Data center conversion of obsolete retail shells attracts hyperscaler colocation demand in suburban Seattle corridors. Washington State enforces building efficiency benchmarks through ASHRAE-derived codes affecting retrofit economics. The Interstate 5 corridor concentrates temperature-controlled warehouse supply deficits serving pharmaceutical distribution networks.
Mountain West
Institutional capital rotation into Sun Belt logistics corridors is compressing cap rate spreads across Denver and Salt Lake City submarkets. The Department of Energy enforces clean energy retrofit mandates reshaping obsolescence risk calculations. Colorado's entitlement timelines for ground-up construction extend hold periods amid skilled labor shortages in electrical and HVAC trades.
United States Commercial Real Estate Market Competitive Environment
Vertically integrated developers and scale-driven asset managers split the market between operational intensity and capital efficiency. The competitive structure concentrates around platform breadth and sourcing relationships rather than price competition. Three archetypes dominate: gateway market developers with in-house construction capabilities, opportunistic specialists in distressed and transitional assets, and diversified private equity vehicles with multi-strategy deployment. Dominant competitive moves include portfolio rationalization through club-arrangement co-investment and technology platform deployment for operational optimization.
Among scale-driven asset managers, Blackstone Inc. and Starwood Capital Group occupy positions exemplifying divergent strategic archetypes. Blackstone represents the diversified multi-strategy approach spanning core through opportunistic risk profiles. Starwood anchors the distressed and transitional asset specialization with workout execution capabilities. Hines sits within the vertically integrated developer tier with gateway market concentration. These three entities illustrate how capital deployment scale, operational platform breadth, and asset class specialization define competitive positioning in institutional commercial real estate.
| Leading Market Players |
|---|
| Hines |
| Nuveen Real Estate |
| Blackstone Inc. |
| Starwood Capital Group |
| Invesco Investment Services, Inc. |
| Brookfield |
| PGIM Real Estate Inc. |
| LaSalle Investment Management |
| CBRE Investment Management |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in skilled construction trades across Texas and Florida is compressing development timelines and inflating labor premiums, forcing sponsors to absorb cost escalation or pass through to tenants via base rent adjustments and operating expense recoveries.
Pricing Analysis
Cap rate spreads between coastal gateway office and Sun Belt industrial assets have widened to historic extremes, with Dallas-Fort Worth logistics facilities commanding premium valuations against Manhattan towers facing hybrid work repricing. Pricing stratifies across core stabilized assets, value-add renovation opportunities, and opportunistic distressed positions based on lease rollover schedules and energy retrofit eligibility. Pricing pressure stems from regional bank lending contraction constraining sub-$50 million transaction financing. Institutional investors exhibit lowest price sensitivity in core logistics corridors, while family office direct buyers face highest sensitivity to appraisal volatility and debt service coverage disruptions.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment have redirected data center investment flows toward domestic server assembly and modular construction components. Supply concentrates in Mexico for precast concrete and structural steel, in Canada for mass timber and engineered wood products, and in China for electrical switchgear and HVAC control systems. Raw material dependencies span steel rebar, copper wiring, and low-emissivity glazing. Single-source vulnerability in electrical transformer production extends equipment lead times and compresses project completion windows. Distribution runs through regional building material distributors with direct-to-site logistics coordination by general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Execution capability gaps in energy retrofit project management and entitlement navigation are constraining capital deployment velocity, favoring sponsors with in-house construction platforms and established municipal relationships over capital-only participants.
For Market Incumbents: Harden portfolio resilience through backward integration into property management and construction services, capturing margin pools where third-party fees currently erode NOI. Consolidate scattered-site industrial holdings in Dallas-Fort Worth and Central Florida to achieve operational scale against Amazon and Walmart leasing teams. Defend against distressed asset specialists by pre-positioning capital for opportunistic acquisitions before loan maturity cliffs. For New Entrants and Emerging Players: Establish a beachhead in cold storage development across the Interstate 35 corridor, where temperature-controlled supply deficits support automated facility premiums and limited institutional competition. Target build-to-rent single-family housing in Phoenix and Charlotte submarkets with millennial household formation tailwinds. Pursue municipal incentive packages for brownfield industrial repositioning before Phase II environmental timelines extend hold periods. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across life sciences and data center development, favoring platforms with sovereign wealth co-investment structures over fund-level leverage. Long-term viability rests on exposure to secular demand drivers—e-commerce fulfillment densification, biotech venture formation, hyperscaler colocation—rather than cyclical office recovery. Monitor regional bank lending capacity as the inflection signal for transaction velocity and refinancing viability across secondary markets.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Retrofit Program | IRA tax credits for building electrification capture widening margin pools in Class B office repositioning. |
| Last-Mile Development | Speculative industrial delivery in Miami and Tampa submarkets absorbs Amazon and Target fulfillment requirements. |
| Data Center Conversion | Power-dense retail shell repositioning in Northern Virginia attracts hyperscaler colocation demand. |
| Cold Storage Buildout | Automated temperature-controlled facilities in Texas address pharmaceutical distribution infrastructure gaps. |
| Platform Acquisition | Club-arrangement co-investment structures enable portfolio rationalization by listed REITs above $500 million. |
Study Parameters
Cross-validation between primary interviews with asset managers, development executives, and municipal planning officers anchors the qualitative findings against secondary validation from SEC REIT filings, FERC interconnection queues, and ASHRAE code adoption databases. Bottom-up triangulation aggregates transaction-level cap rate and rent data across CoStar, Real Capital Analytics, and MSCI RCA indices. Top-down calibration incorporates Federal Reserve senior loan officer surveys and Census Bureau construction spending reports.
Calibration against historical absorption patterns and entitlement timeline distributions ensures forecast robustness across the projection horizon. Segmentation dimensions span property type, investment strategy, client type, and transaction size, with regional regulatory clusters and energy retrofit eligibility modeled as cross-cutting variables. CAGRs derive from lease rollover schedule analysis, construction cost inflation trajectories, and institutional capital flow projections. Forecast inputs incorporate NIH funding concentration, e-commerce fulfillment densification requirements, and hyperscaler data center capex disclosures.
Sensitivities concentrate around interest rate trajectory shifts, regional bank lending capacity contractions, and ASHRAE code stringency escalations. Forecasts reflect documented assumptions regarding hybrid work permanence, IRA incentive continuity, and skilled trade labor availability. Material shifts in Federal Reserve policy stance or mass appraisal methodology reforms in Texas and Florida would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
North America Coworking Spaces Market