
 UK Commercial Real Estate Market | 2026-2036
UK Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
UK Commercial Real Estate Market Insights
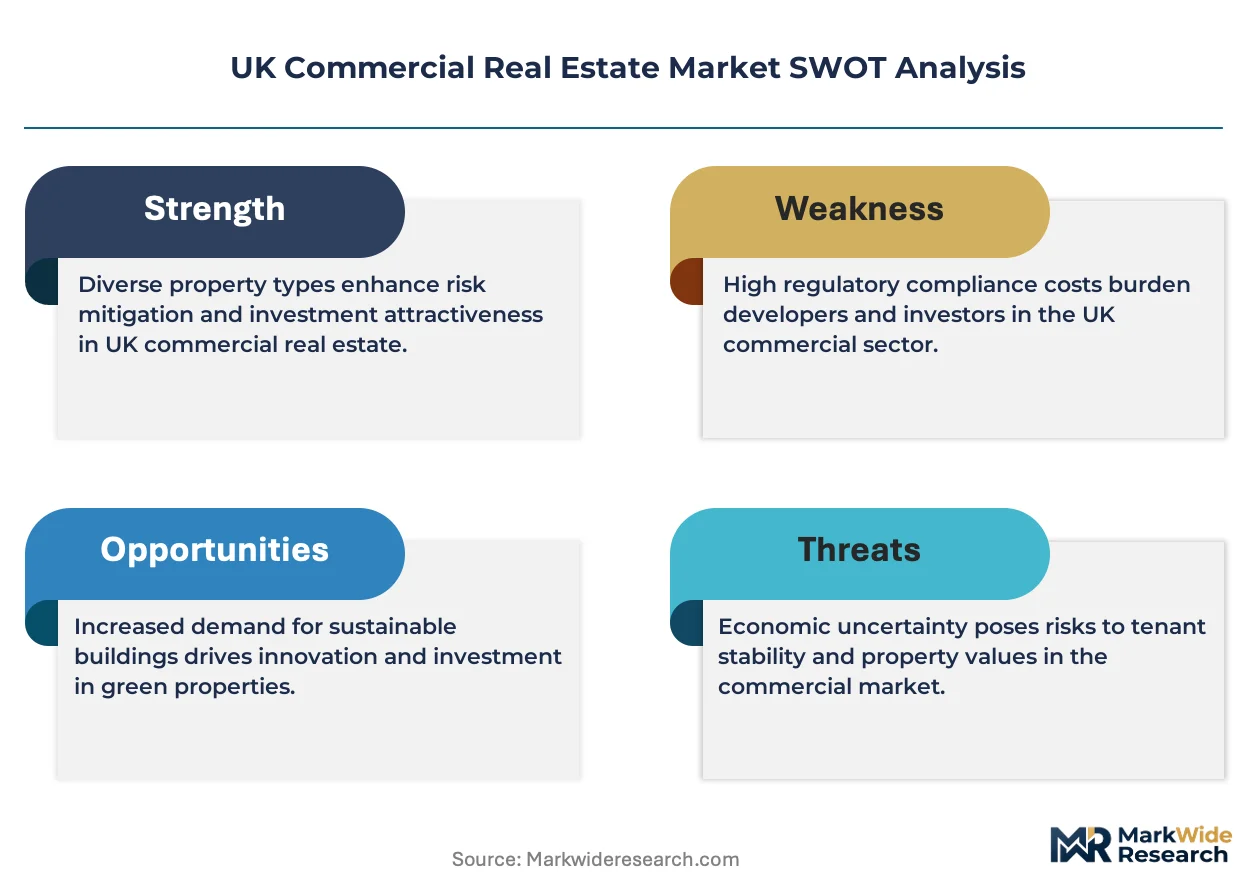
MEES is rebalancing the cost-of-entry calculus for investors targeting older stock. Tritax Big Box REIT plc dominates logistics-focused portfolios across the East Midlands and Thames Valley. Savills plc navigates valuation complexity for assets requiring substantial capital expenditure to meet efficiency thresholds. British Land Company plc anchors regeneration schemes that integrate office and residential components in central London.
UK commercial real estate comprises income-generating property assets including office towers, retail parades, logistics warehouses, and mixed-use schemes, typically valued through discounted cash flow models against lease terms and tenant covenant strength. Industrial assets lead transaction velocity as e-commerce fulfillment requirements reshape spatial demand around motorway corridors. Office stock faces structural repricing where Grade A space with EPC B ratings or better captures rental premiums over secondary buildings. Retail warehousing and convenience-led schemes sustain investor attention while traditional high street formats occupy a narrower buyer pool.
The Building Safety Regulator enforces higher accountability standards for higher-risk structures, reshaping development timelines and insurance costs across residential-commercial mixed schemes. BREEAM certification and the Future Buildings Standard progressively tighten operational carbon benchmarks, filtering capital toward assets with clear retrofit pathways. Stakeholders must weigh hold-sell decisions against the trajectory of compliance costs and the narrowing pool of institutional capital willing to underwrite stranded efficiency risk.
Market Dynamics
The UK's Minimum Energy Efficiency Standards (MEES) are compressing investment timelines as landlords face 2027 and 2030 efficiency thresholds that render secondary office stock unlettable without substantial capital deployment.
Growth Catalysts
- Last-mile logistics densification:E-commerce fulfillment networks are expanding warehouse footprints across the East Midlands and Thames Valley motorway corridors.
- MEES retrofit mandates:The 2027 EPC C and 2030 EPC B thresholds are accelerating capital flows toward assets with clear energy upgrade pathways.
- Institutional capital rotation:Pension funds and sovereign wealth vehicles are reallocating from traditional retail to mixed-use regeneration schemes in Greater London.
Market Restraints
- Debt cost volatility:Sterling interest rate movements have compressed acquisition leverage capacity for value-add strategies targeting secondary office stock.
- Insurance market contraction:The Building Safety Regulator's higher-risk structure designations have narrowed the underwriter pool for residential-commercial mixed schemes.
- Construction input inflation:Steel and concrete cost fluctuations are extending development timelines for speculative industrial builds.
Strategic Opportunities
- Science and technology clusters:Cambridge and Oxford's life science corridors offer underpenetrated laboratory and R&D space formats.
- Future Buildings Standard alignment:Assets achieving operational carbon benchmarks early will capture rental premiums as institutional capital screens for stranded efficiency risk.
- Urban logistics micro-fulfillment:Last-mile operators are penetrating constrained city-center sites previously considered economically unviable for industrial use.
Industry Challenges
- Retrofit skill scarcity:The shortage of BREEAM assessors and building physics specialists is extending certification timelines for efficiency upgrade programs.
- Valuation model opacity:Discounted cash flow assumptions struggle to price regulatory compliance cost trajectories for assets with uncertain EPC improvement pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Commercial Real Estate Market |
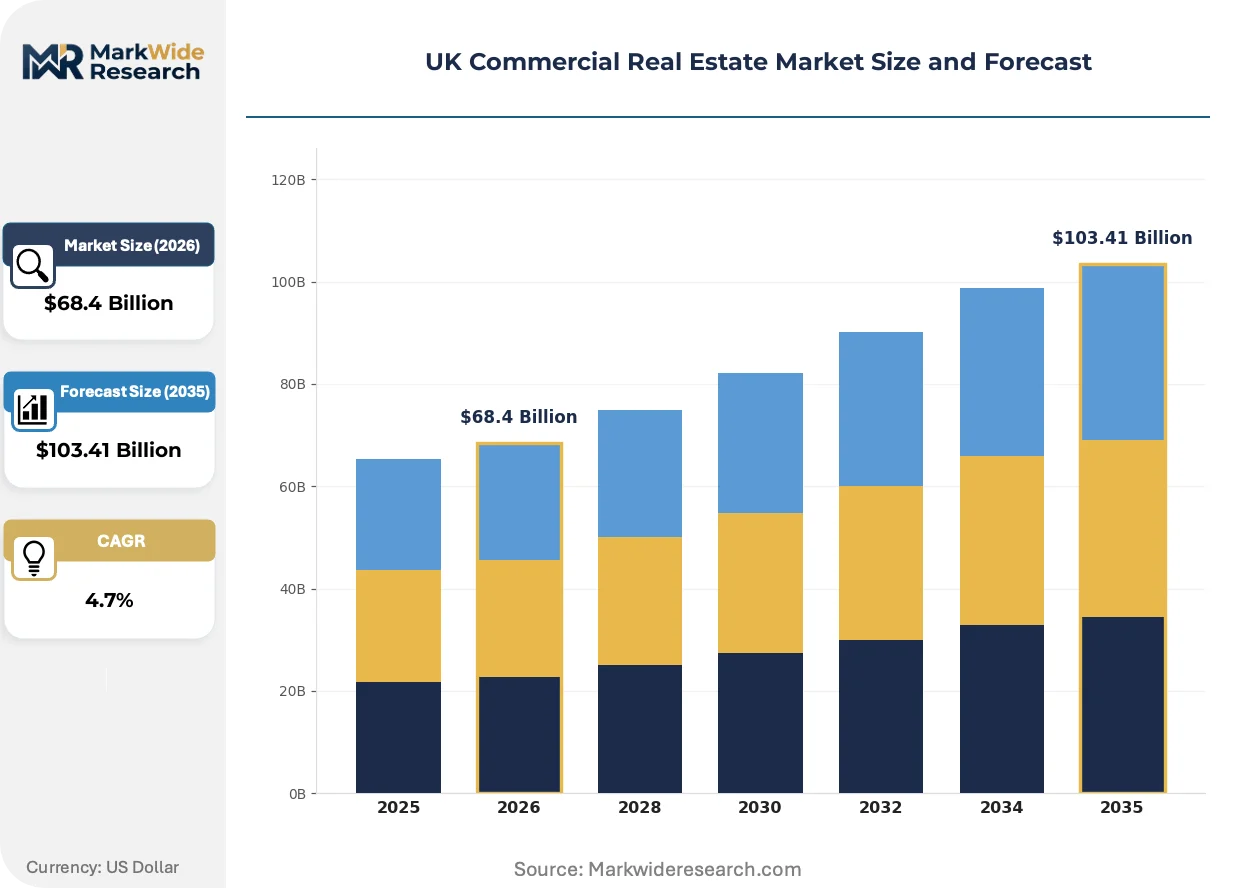
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Tenure Type: Leasehold, Freehold, Shared Ownership, Tenancy Investment Strategy: Core, Core Plus, Value-Added, Opportunistic Usage Type: Commercial, Residential, Recreational, Others |
| Companies Covered | Tritax Big Box REIT plc, Savills plc, SEGRO plc, Cushman & Wakefield, Knight Frank LLP, Land Securities Group plc, British Land Company plc, Jones Lang LaSalle Ltd, LondonMetric Property plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Commercial Real Estate Market Trends and Innovations
PropTech platforms and embedded sensor networks are restructuring how landlords monitor asset performance and tenant behavior. Three developments are compressing traditional operating models.
Smart building management systems are decentralizing operational control across distributed sensor networks. Industrial landlords in the Midlands are deploying these platforms to optimize energy consumption across multi-tenant warehouse portfolios. The technology is decentralizing facility management from centralized engineering teams to automated edge-computing nodes that adjust HVAC and lighting in real time.
The Future Buildings Standard is tightening operational carbon benchmarks for new construction and major renovations. Developers face stepped thermal efficiency requirements that eliminate gas heating systems from 2025 compliance pathways. Speculative office schemes in central London are responding by integrating air-source heat pumps and photovoltaic arrays as standard specifications rather than premium upgrades.
Tenant covenant scrutiny is intensifying as remote work patterns destabilize traditional lease security assumptions. Institutional investors are weighting lease structures toward shorter terms with break clauses rather than the 10-15 year commitments that historically underpinned financing structures. This recalibration is most visible in Greater London's Grade A office market, where tenants are trading covenant strength for occupational flexibility.
UK Commercial Real Estate Market Segmentation
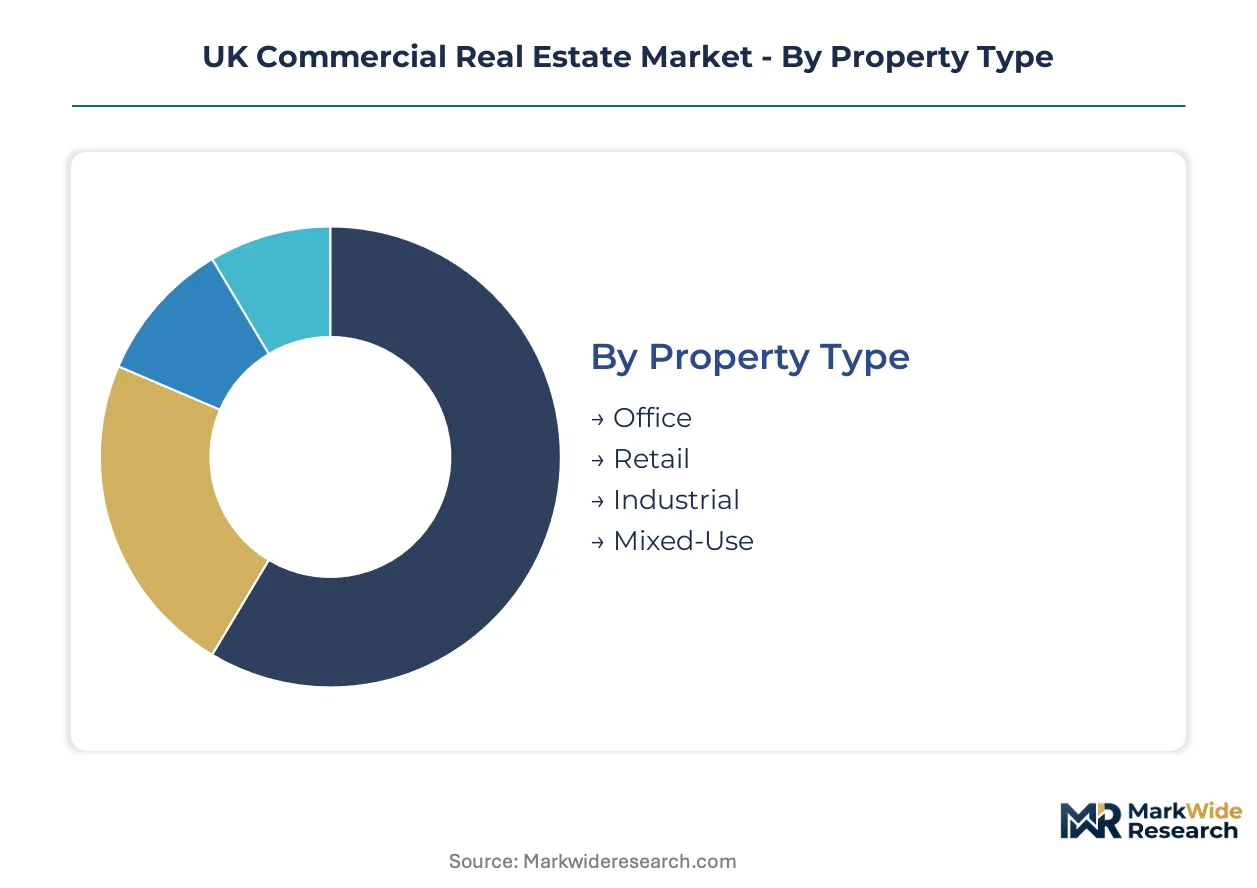
UK commercial real estate segmentation reveals how capital allocates across risk-return profiles and operational characteristics. Property type determines physical asset exposure, while tenure and investment strategy govern cash flow stability and capital appreciation potential.
Property Type:
Buyers differentiate by lease duration predictability and exposure to structural demand shifts.
- Office:Grade A space with EPC B ratings or better commands rental premiums over secondary buildings in central London and regional hubs. Demand concentrates in Greater London's mixed-use developments where institutional capital screens for stranded efficiency risk under MEES thresholds.
- Industrial:Logistics warehouses and distribution centers span East Midlands and Thames Valley motorway corridors. Tritax Big Box REIT plc dominates this segment as e-commerce fulfillment requirements reshape spatial demand around last-mile densification nodes.
- Retail:Convenience-led schemes and retail warehousing sustain investor attention while traditional high street formats occupy a narrower buyer pool.
- Mixed-Use:Regeneration schemes integrate office and residential components, with British Land Company plc anchoring central London developments that navigate Building Safety Regulator accountability standards.
Volume sits with Industrial; growth tilts toward Mixed-Use.
Tenure Type:
Capital deployment varies by control intensity and liability exposure.
- Freehold:Absolute ownership of land and buildings enables full development control and captures long-term land value appreciation. Pension funds and sovereign wealth vehicles favor this structure for core allocations in Greater London.
- Leasehold:Time-limited interests with ground rent obligations suit value-add strategies targeting lease regearing or asset repositioning. Savills plc navigates valuation complexity where MEES retrofit mandates compress investment timelines.
- Shared Ownership:Partial equity stakes with occupancy rights appear in residential-commercial hybrid structures.
- Tenancy:Short-term occupational agreements dominate urban logistics micro-fulfillment sites previously considered economically unviable.
Institutional capital clusters around Freehold; flexibility seekers migrate toward Leasehold.
Investment Strategy:
Risk tolerance separates passive income seekers from active repositioning specialists.
- Core:Stabilized assets with long-lease income profiles and minimal capital requirements. These holdings anchor pension fund portfolios seeking inflation-linked returns.
- Core Plus:Light value-add opportunities with modest lease rollover or minor refurbishment potential.
- Value-Added:Assets requiring substantial capital expenditure to meet EPC improvement pathways or reposition for alternative use. Debt cost volatility has compressed acquisition leverage capacity for this approach.
- Opportunistic:Distressed or development-stage exposure with highest return thresholds and execution risk.
Capital deployment peaks at Core; return expansion concentrates in Value-Added.
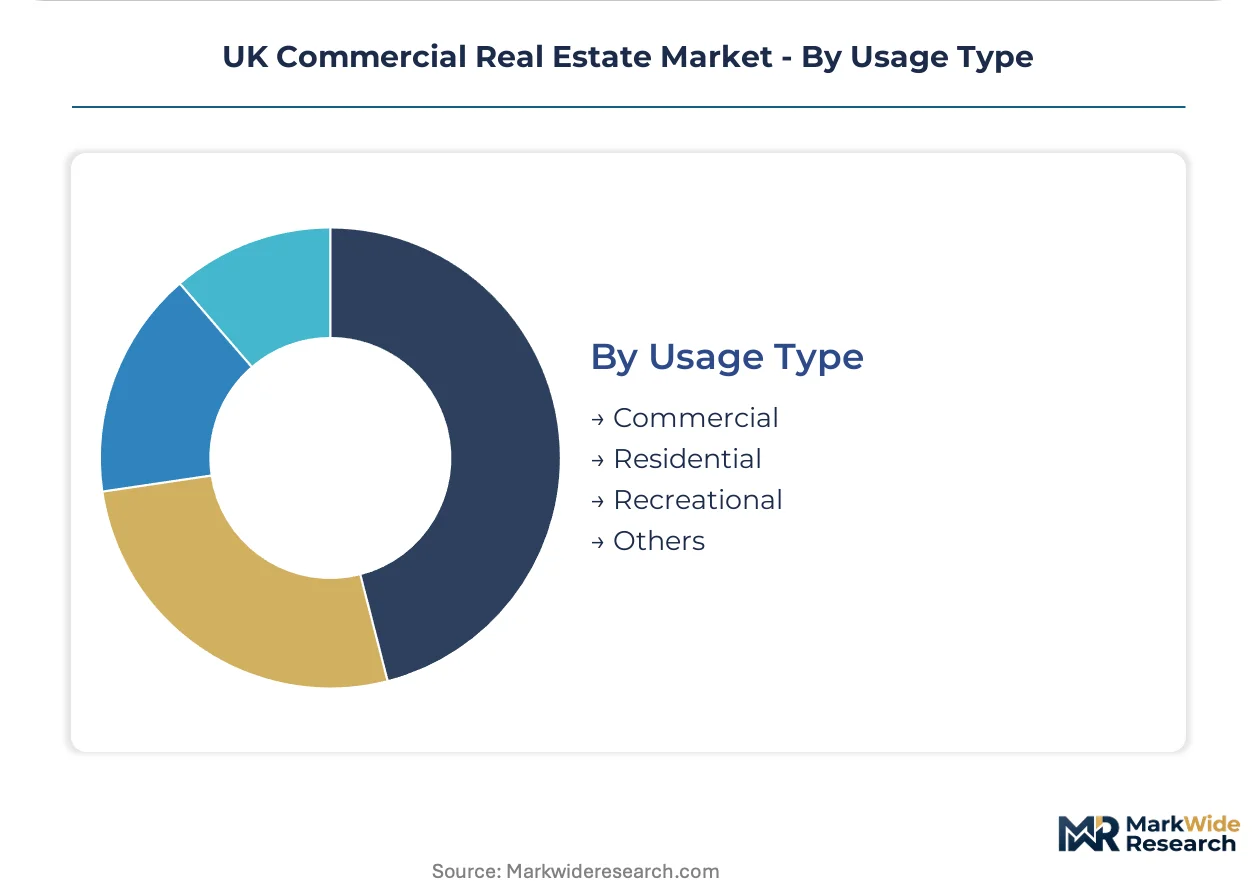
Usage Type:
Functional end-use governs planning permission pathways and operational complexity.
- Commercial:Income-generating business premises including offices, warehouses, and retail units valued through discounted cash flow models against tenant covenant strength.
- Residential:Build-to-rent and student housing components within mixed-use schemes face Future Buildings Standard thermal efficiency requirements.
- Recreational:Leisure and hospitality assets with higher operational intensity and shorter lease structures.
- Others:Life science laboratories and R&D facilities in Cambridge and Oxford corridors offer underpenetrated formats.
Transaction velocity favors Commercial; yield compression is steepest in Residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London concentrates institutional capital deployment for mixed-use regeneration schemes. The Midlands corridor dominates logistics warehouse absorption. Northern England and Scotland face steeper repricing for secondary office stock under efficiency mandates.
Greater London and the Southeast
Grade A office space with EPC B ratings commands rental premiums over secondary buildings. The Building Safety Regulator enforces higher accountability standards for higher-risk residential-commercial mixed schemes. Canary Wharf and King's Cross anchor regeneration developments integrating office and residential components.
East Midlands and Thames Valley
E-commerce fulfillment networks expand warehouse footprints across motorway corridors. MEES retrofit mandates compress investment timelines for landlords facing 2027 and 2030 efficiency thresholds. Milton Keynes and Northampton cluster last-mile densification nodes where logistics operators penetrate constrained sites.
North England
Secondary office stock faces structural repricing where Grade A space captures institutional attention. The Future Buildings Standard tightens operational carbon benchmarks for new construction and major renovations. Manchester and Leeds regeneration schemes navigate valuation complexity for assets requiring substantial capital expenditure.
Scotland
Science and technology clusters offer underpenetrated laboratory and R&D space formats in Edinburgh and Glasgow. Scottish building regulations align with UK-wide MEES thresholds while adding local energy efficiency requirements. Aberdeen's energy transition is repurposing commercial stock for alternative life science and technology use.
Wales
Urban logistics micro-fulfillment operators target constrained city-center sites in Cardiff and Newport. Welsh building regulations enforce efficiency standards parallel to English MEES frameworks. Cardiff Bay regeneration integrates mixed-use schemes where institutional capital screens for stranded efficiency risk.
UK Commercial Real Estate Market Competitive Landscape
London-based REITs anchor the core portfolio tier; regional specialists hold development-stage exposure. The market structures around three archetypes: scale-driven logistics landlords, integrated mixed-use developers, and advisory-heavy service platforms. Competitive moves concentrate on portfolio diversification into life science corridors and strategic partnerships for retrofit execution capability.
Within the logistics-focused tier, Tritax Big Box REIT plc and SEGRO plc exemplify scale-driven warehouse accumulation across Midlands motorway corridors. British Land Company plc anchors the integrated regeneration archetype through central London mixed-use schemes. Savills plc occupies the advisory-intensive position navigating valuation complexity for assets facing MEES compliance thresholds.
| Leading Market Players |
|---|
| Tritax Big Box REIT plc |
| Savills plc |
| SEGRO plc |
| Cushman & Wakefield |
| Knight Frank LLP |
| Land Securities Group plc |
| British Land Company plc |
| Jones Lang LaSalle Ltd |
| LondonMetric Property plc |
| Others |
Pricing and Supply Chain Analysis
BREEAM assessor scarcity across the East Midlands and Thames Valley widens labor-cost spreads between premium-certified assets and uncertified stock. This workforce concentration feeds directly into pricing-tier differentiation, as landlords with in-house sustainability teams capture faster retrofit completion and earlier rental premium realization.
Pricing Analysis
Volume concentrates in secondary office stock where margin compression runs deepest; Grade A space with EPC B ratings commands sustained premiums. Pricing stratifies across premium, standard, and economy tiers based on certification grade and tenant covenant strength. Cost compression in secondary buildings intensifies because MEES retrofit mandates accelerate capital deployment requirements. Value-add investors show highest price sensitivity; core pension fund buyers absorb premium-grade assets with limited negotiation.
Supply Chain Analysis
UK domestic-content rules under the Building Safety Regulator reshape sourcing toward certified local contractors for higher-risk residential-commercial mixed schemes. Steel and concrete supply draws from China, Turkey, and domestic UK production. Air-source heat pump components rest on German and Dutch manufacturing. Single-source vulnerability sits with specialized glazing systems for thermal efficiency upgrades. Distribution runs through regional contractor networks anchored by quantity surveyors and project management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK commercial real estate market sits in a technology-transition phase as smart building management systems displace centralized facility engineering teams. Embedded sensor networks and edge-computing nodes now automate HVAC and lighting adjustments that previously required manual intervention.
For Market Incumbents: Anchor portfolio resilience through backward integration into retrofit execution capability. Build captive teams of BREEAM assessors and building physics specialists to compress certification timelines. Acquire regional contractor networks to secure labor access as skill scarcity intensifies.
For New Entrants and Emerging Players: Begin with urban logistics micro-fulfillment penetration in constrained city-center sites across Cardiff, Newport, and Milton Keynes. Target tenancy structures with short-term occupational agreements that incumbent industrial landlords avoid. Pursue partnerships with last-mile operators seeking densification nodes.
For Investors and Strategic Acquirers: The window for entry favors value-added specialists with capital deployment capacity for MEES-driven repositioning. Five-to-ten year viability hinges on assets with clear EPC improvement pathways and identified retrofit contractors. Watch the narrowing pool of institutional capital willing to underwrite stranded efficiency risk as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Execution Capability Buildout | In-house BREEAM teams compress certification timelines against scarce assessor supply. |
| Last-Mile Densification Partnership | Urban logistics micro-fulfillment unlocks previously unviable city-center industrial sites. |
| Smart Building Platform Integration | Embedded sensor networks displace centralized facility management with automated edge control. |
| Science and Technology Corridor Entry | Cambridge and Oxford laboratory formats offer underpenetrated R&D space exposure. |
| Green Certification Program | Future Buildings Standard alignment captures rental premiums from institutional capital screening. |
Research Methodology
Document review covered UK Land Registry transaction records, MHCLG building safety guidance, and BREEAM certification databases, complemented by interviews with property fund managers, development directors at mixed-use regeneration schemes, quantity surveyors specializing in retrofit programs, and sustainability consultants advising on MEES compliance pathways. Secondary validation drew from British Property Federation market reports, MSCI UK real estate indices, and planning application data from local authorities. Bottom-up lease-level cash flow modeling triangulated against top-down sector allocation surveys from institutional investors.
Output projections span market value and transaction velocity across the analysis window, with segmentation modeling across property type, tenure structure, investment strategy, and regional cluster. CAGRs derive from lease rollover schedules, development pipeline tracking, and capital flow surveys. Forecast inputs incorporate MEES threshold compliance cost curves and logistics absorption rates along motorway corridors.
Underlying measurement precision varies by segment; Grade A office and prime industrial carry tighter precision than secondary stock with uncertain retrofit pathways. Forecasts embed assumptions around interest rate stability and construction input cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Canada Hospitality Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Indonesia Commercial Real Estate Market