
 Qatar Commercial Real Estate Market | 2026-2036
Qatar Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Commercial Real Estate Market Analytics
Grade-A office specifications are reorganizing tenant expectations across Doha and Lusail. Qatari Diar leverages its sovereign-linked project pipeline to dominate master-planned developments on the city's periphery. Alfardan Properties sustains premium positioning through concentrated ownership of West Bay assets. Barwa Real Estate Company anchors its competitive stance via large-scale industrial and logistics land holdings near Hamad Port.
Qatar commercial real estate comprises income-generating built assets designed for business occupancy, typically engineered to shell-and-core or Category-A fit-out standards with reinforced concrete frames, integrated MEP systems, and minimum energy performance thresholds aligned with the Gulf's harsh climate. These assets serve as operational infrastructure for corporate headquarters, retail distribution, light manufacturing, and public administration functions. Office buildings command the deepest institutional capital pools due to long-lease covenant structures with government-related entities, while warehouses represent the fastest-appreciating segment as e-commerce fulfillment and port-linked logistics reshape last-mile requirements. Retail spaces retain structural importance but face margin compression from experiential repositioning demands.
Qatar's Ministry of Municipality and Environment enforces building codes that mandate escalating thermal efficiency and water conservation metrics, directly elevating construction costs and filtering developer entry. The Qatar Central Bank's real estate lending guidelines and the Qatar Financial Centre's regulatory framework shape foreign ownership access and investment structuring options. Stakeholders must track how Lusail's freehold title experiments and Msheireb Downtown's mixed-use zoning evolve as templates for subsequent district-scale approvals.
Market Dynamics
Sovereign capital deployment and energy sector consolidation are compressing lease cycles while elevating specification thresholds across Qatar's commercial property inventory.
Growth Catalysts
- Energy Sector Consolidation:Multinational headquarters expansions in Doha are generating pre-commitment demand for premium office stock with long-lease covenants.
- Qatar Central Bank Lending Guidelines:Structured real estate financing frameworks are channeling institutional capital toward income-generating assets with government-linked tenants.
- Hamad Port Logistics Cluster:E-commerce fulfillment requirements are accelerating warehouse absorption rates in industrial zones adjacent to the port infrastructure.
Market Restraints
- Construction Input Volatility:Reinforced concrete and MEP system costs fluctuate with regional supply chain disruptions, compressing developer margins on fixed-price contracts.
- Green Certification Mandates:Qatar's updated building energy codes mandate escalating thermal efficiency thresholds that extend project timelines and elevate capital requirements.
- Development Concentration Risk:Master-planned project pipelines concentrate delivery risk with sovereign-linked developers, limiting private market entry.
Strategic Opportunities
- Lusail Freehold Title Experiments:Mixed-use district zoning innovations are creating templates for foreign ownership access beyond traditional leasehold structures.
- Msheireb Downtown Zoning:Integrated retail-office-residential approvals are demonstrating viability for compact, transit-linked development formats.
- Smart Building Convergence:IoT-enabled building management systems converging with energy performance monitoring are opening premium rental differentiation.
Industry Challenges
- Specialized Fit-Out Talent Scarcity:Category-A specification expertise for shell-and-core delivery remains concentrated among limited contractor pools.
- Green Certification Timeline Compression:GSAS and LEED-equivalent compliance pathways extend pre-leasing periods, straining developer carry costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Commercial Real Estate Market |
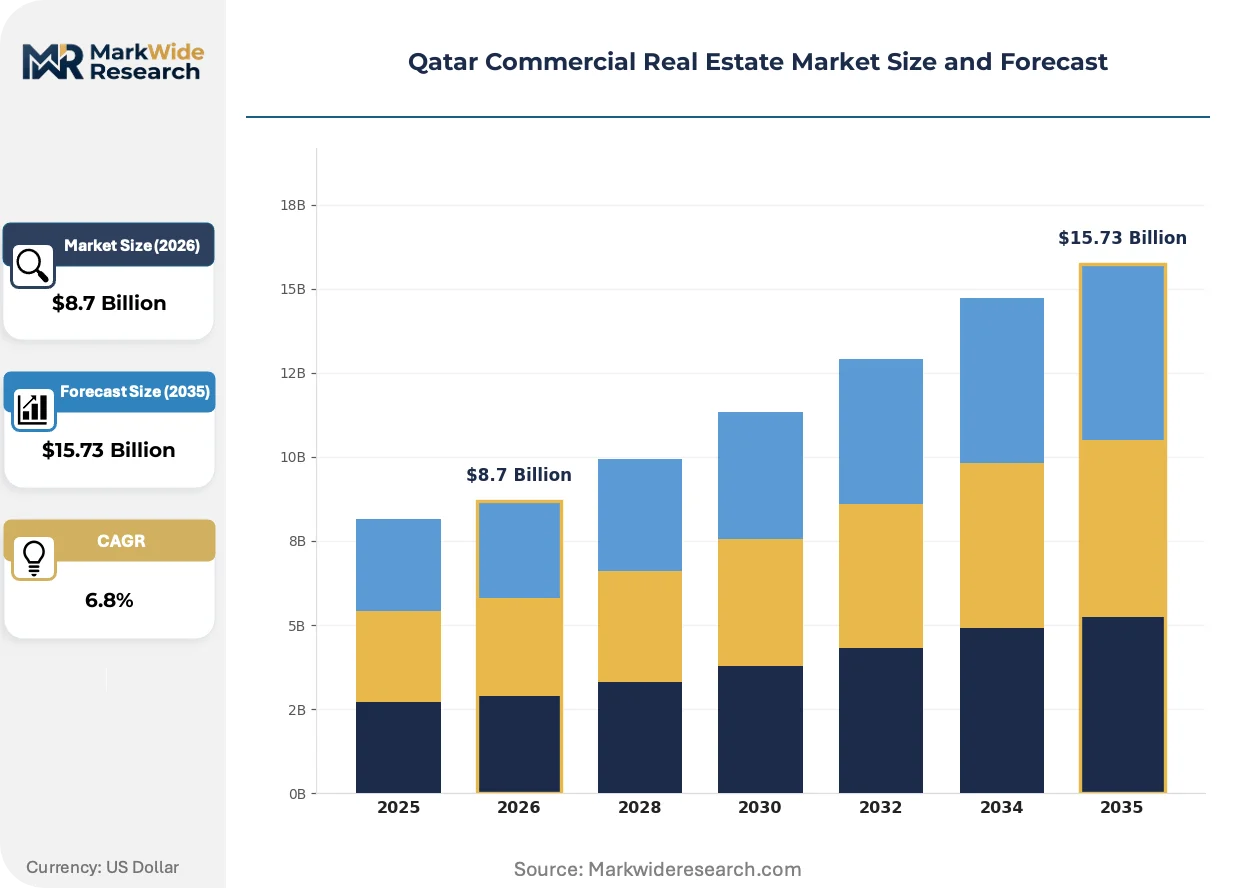
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Type: Office Buildings, Retail Spaces, Warehouses, Industrial Parks Property Ownership: Freehold, Leasehold, Joint Venture, Government-owned Investment Stage: Development, Acquisition, Stabilized Assets, Redevelopment End User: Corporations, SMEs, Government Entities, Investors |
| Companies Covered | Qatari Diar, Alfardan Properties, Barwa Real Estate Company, Al Asmakh Real Estate, Msheireb Properties, Ezdan Holding Group, Mazaya Real Estate Development, JMJ Group Holding, United Development Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Commercial Real Estate Market Evolving Landscape
Digital twin technology and predictive asset management are restructuring how institutional owners monitor portfolio performance and tenant satisfaction across Qatar's commercial inventory.
Building information modeling integrated with IoT sensor networks is supplanting reactive maintenance schedules across Grade-A office assets. Property managers at Lusail's mixed-use districts are deploying these systems to optimize MEP performance in real-time. This convergence is compressing operational expenditure variance and enabling outcome-based service contracting with facility vendors.
Qatar's Ministry of Municipality and Environment has escalated thermal efficiency mandates within its updated building energy code framework. These regulations now require water conservation metrics and energy performance thresholds that filter developer entry. Office and retail segments face the steepest compliance ramps, with projects in West Bay and Msheireb Downtown adopting integrated renewable systems to meet certification timelines.
Tenant procurement of space is rotating toward flexible lease structures with embedded expansion options. Corporate headquarters in the energy and financial sectors are negotiating shorter initial terms with right-of-first-refusal on adjacent floor plates. This pattern is most visible in Doha's central business district, where institutional landlords are unbundling traditional long-lease covenants to retain sovereign-linked tenants.
Qatar Commercial Real Estate Market Segmentation
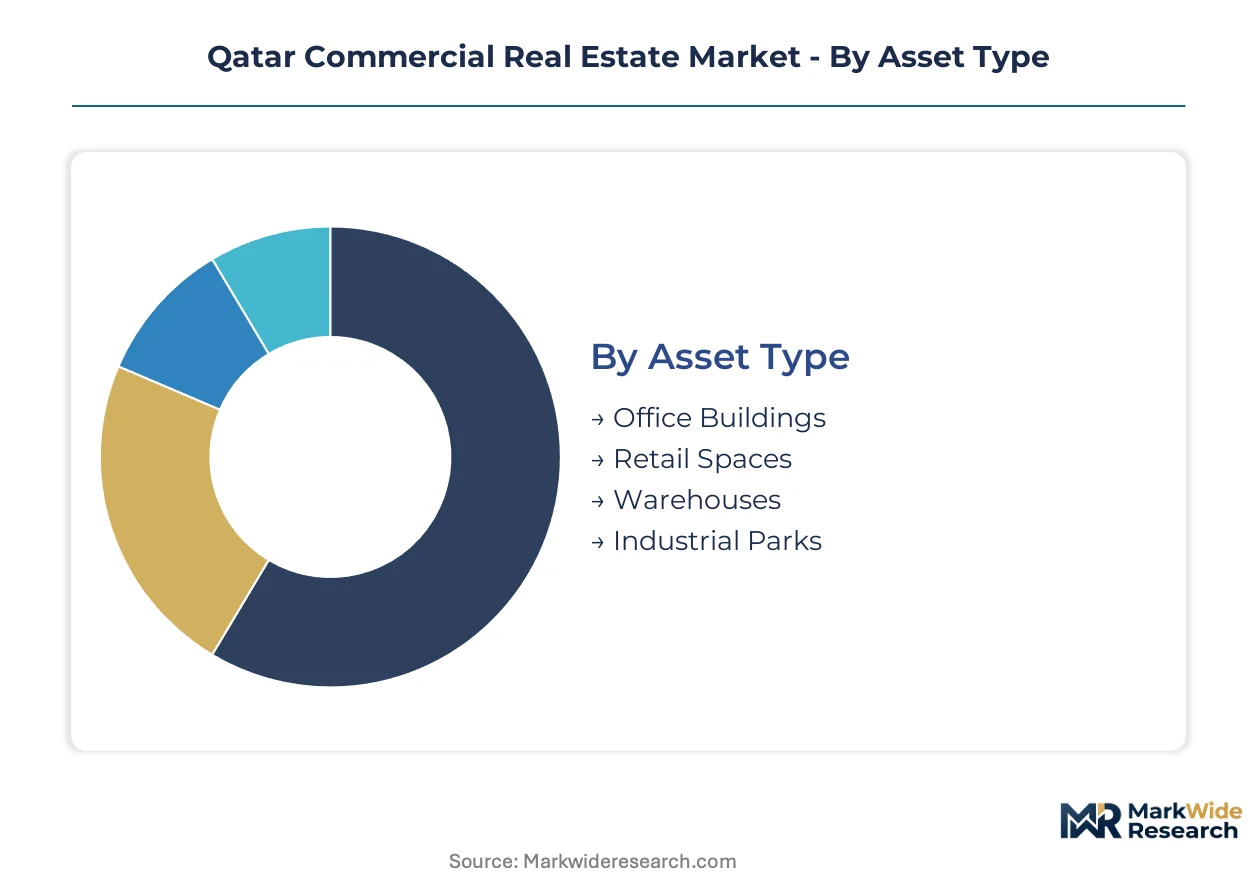
Segmentation reveals how capital allocation priorities diverge across Qatar's commercial property inventory. Sovereign-linked developers, foreign institutional investors, and corporate occupiers each target distinct risk-return profiles within the same geographic footprint.
Asset Type:
Margin pools concentrate in premium office stock with long-lease government covenants, while logistics assets capture yield compression from e-commerce fulfillment demand.
- Office Buildings:Shell-and-core structures with Category-A fit-out specifications dominate institutional capital deployment. Energy sector headquarters expansions in Doha and Lusail are pre-committing to Grade-A stock with integrated MEP systems and GSAS certification pathways.
- Retail Spaces:Mixed-use configurations within Msheireb Downtown and Lusail City demonstrate viability for experiential repositioning formats. Margin pressure from tenant experience demands is filtering development specifications toward flexible floor plates with integrated F&B and entertainment zoning.
- Warehouses:E-commerce fulfillment requirements near Hamad Port are accelerating absorption rates for high-bay distribution centers with automated material handling compatibility.
- Industrial Parks:Large-scale land holdings near port infrastructure anchor Barwa Real Estate's competitive positioning for light manufacturing and logistics clustering.
Office Buildings hold installed capacity. Warehouses are rotating up the share rankings.
Property Ownership:
Foreign capital access patterns determine pricing stratification across ownership structures, with freehold experiments commanding premium valuations.
- Freehold:Lusail City's title experiments are creating templates for foreign ownership access beyond traditional leasehold restrictions. Qatar Financial Centre regulatory frameworks enable 100% foreign equity participation in designated zones.
- Leasehold:West Bay and central Doha assets remain predominantly leasehold, with Alfardan Properties sustaining premium positioning through concentrated ownership of long-lease covenant structures.
- Joint Venture:Sovereign-linked developers leverage project pipelines to dominate master-planned developments while private partners contribute specialized fit-out expertise.
- Government-owned:Ministry of Municipality and Environment holdings anchor public administration functions and filter private market entry through controlled land release schedules.
Leasehold maintains transaction velocity. Freehold is climbing the fastest in investor preference surveys.
Investment Stage:
Risk-adjusted return thresholds segment capital deployment across development timelines, with stabilized assets commanding compressed yields.
- Development:Green certification mandates from Qatar's Ministry of Municipality and Environment extend project timelines and elevate capital requirements for thermal efficiency compliance.
- Acquisition:Qatar Central Bank lending guidelines channel institutional capital toward income-generating assets with government-linked tenant covenants.
- Stabilized Assets:Long-lease office stock with energy sector occupants trades at yield premiums reflecting covenant quality and GSAS certification status.
- Redevelopment:Existing West Bay inventory faces repositioning pressure from Grade-A specification thresholds that render older stock functionally obsolete.
Stabilized Assets hold institutional allocation. Development is gaining share fastest among sovereign capital deployment.
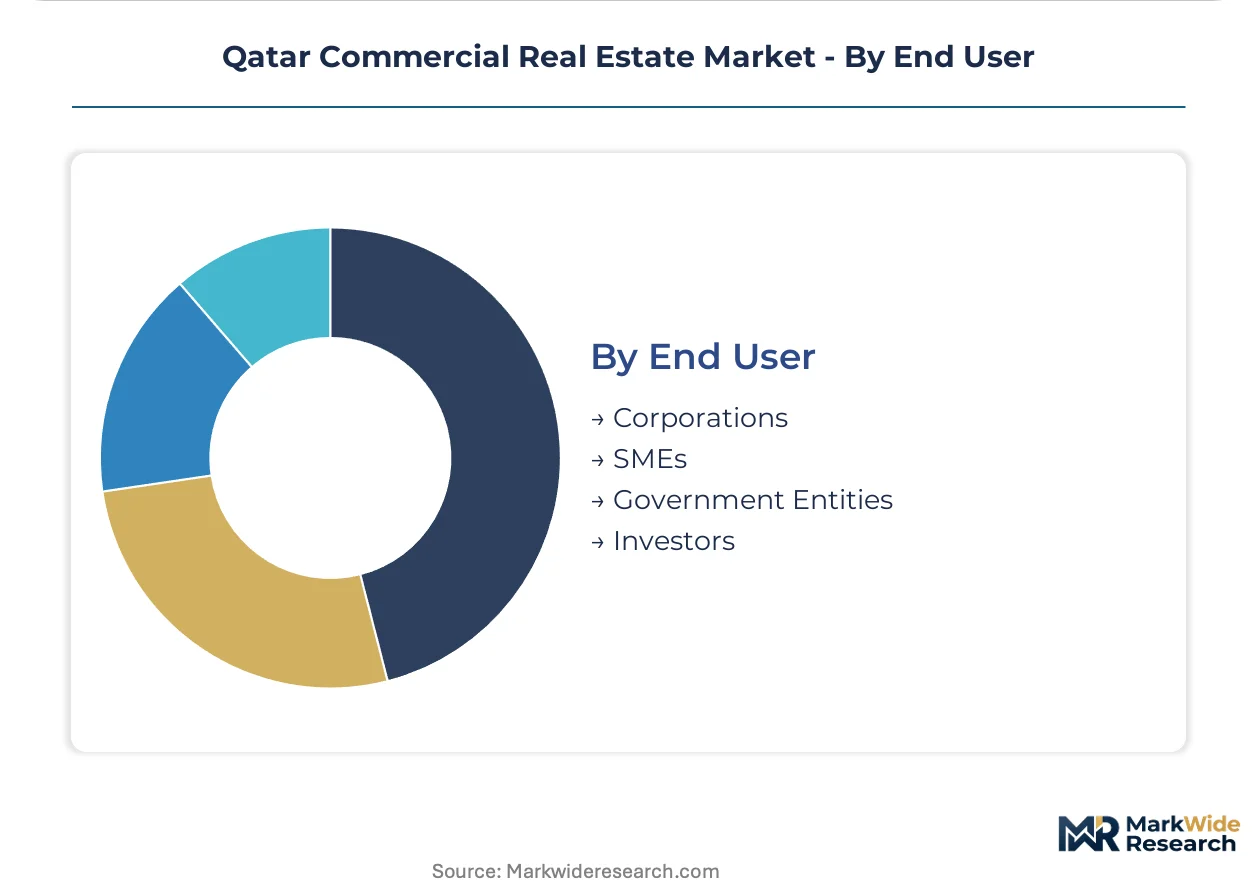
End User:
Tenant procurement patterns segment space absorption across lease structure preferences and specification demands.
- Corporations:Energy and financial sector headquarters negotiate flexible lease structures with embedded expansion options and right-of-first-refusal on adjacent floor plates.
- SMEs:Smaller footprint requirements concentrate in serviced office formats and co-working configurations within Msheireb Downtown's mixed-use zoning.
- Government Entities:Qatar's sovereign ministries anchor long-lease demand for premium office stock with reinforced security specifications and integrated public administration functions.
- Investors:Institutional capital pools target income-generating assets with predictable cash flows, filtering development entry through Qatar Financial Centre regulatory frameworks.
Government Entities anchor lease volume. Corporations are rotating up the share rankings in pre-commitment activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development pipelines concentrate with sovereign-linked entities across Qatar's commercial property inventory, filtering private market entry through controlled land release schedules and master-planned district approvals.
Doha Central Business District
Energy sector headquarters expansions and financial services consolidation are pre-committing to Grade-A office stock with integrated MEP systems. Qatar Central Bank lending guidelines channel institutional capital toward income-generating assets with government-linked tenant covenants. West Bay assets command premium positioning through concentrated ownership of long-lease covenant structures.
Lusail City
Mixed-use district zoning experiments are creating templates for foreign ownership access beyond traditional leasehold restrictions. Qatar Financial Centre regulatory frameworks enable equity participation in designated zones. The city's freehold title experiments are demonstrating viability for compact, transit-linked development formats with institutional tenant pre-commitments.
Msheireb Downtown
Integrated retail-office-residential approvals are concentrating serviced office demand from SMEs and co-working configurations. Qatar's Ministry of Municipality and Environment escalated thermal efficiency mandates within updated building energy codes. Heritage-sensitive redevelopment is filtering development specifications toward flexible floor plates with experiential repositioning capacity.
Hamad Port Logistics Corridor
E-commerce fulfillment requirements are accelerating warehouse absorption rates for high-bay distribution centers. Green certification mandates from the Ministry extend project timelines for thermal efficiency compliance. Industrial land holdings near port infrastructure anchor competitive positioning for light manufacturing and logistics clustering.
Al Wakrah and Southern Suburbs
Population dispersal from central Doha is generating secondary office and retail demand along the Lusail-Expressway corridor. Government-owned land release schedules filter private developer entry through joint venture structures. Peripheral master-planned developments concentrate delivery risk with sovereign-linked developers leveraging project pipelines.
Qatar Commercial Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Qatar's commercial real estate inventory. Sovereign-linked developers dominate master-planned project pipelines through controlled land access and regulatory influence, while specialized private operators sustain premium positioning through concentrated asset ownership in established districts. Three archetypes structure competitive dynamics: state-backed master developers with integrated project pipelines, premium-focused private owners with established district presence, and diversified holding groups with cross-sector asset exposure. Dominant competitive moves include portfolio diversification into mixed-use formats and strategic partnerships securing specialized fit-out expertise for Category-A delivery.
Within the sovereign-linked tier, Qatari Diar and Msheireb Properties exemplify state-backed master developers with integrated project pipelines spanning Lusail City and heritage-sensitive downtown districts. Alfardan Properties and Barwa Real Estate Company occupy positions among premium-focused and diversified private operators respectively, with the former sustaining concentrated West Bay asset ownership and the latter anchoring industrial and logistics land holdings near Hamad Port infrastructure.
| Leading Market Players |
|---|
| Qatari Diar |
| Alfardan Properties |
| Barwa Real Estate Company |
| Al Asmakh Real Estate |
| Msheireb Properties |
| Ezdan Holding Group |
| Mazaya Real Estate Development |
| JMJ Group Holding |
| United Development Company |
| Others |
Value Network & Pricing Analysis
Long-lease covenant structures with government-linked tenants lock in supply access to premium Grade-A office stock while anchoring price visibility across Doha's central business district and Lusail City developments. These contractual frameworks insulate institutional landlords from spot-market volatility while embedding escalation clauses tied to Qatar Central Bank lending benchmarks.
Pricing Analysis
Qatar's Ministry of Municipality and Environment building energy codes dictate the pricing tier structure across commercial property segments. Three-tier pricing structure across premium, standard, and economy levels stratifies assets by GSAS certification status and MEP system integration depth. Price differentiation centers on thermal efficiency compliance costs and long-lease covenant quality. Cost compression in standard-grade inventory is intensifying because green certification timeline extensions strain developer carry capacity. SMEs and co-working operators exhibit highest price sensitivity, while energy sector headquarters demonstrate lowest sensitivity due to operational criticality of specification thresholds.
Supply Chain Analysis
Strait of Hormuz transit underwrites cement and steel import dependencies for Qatar's reinforced concrete construction backbone. Supply concentration centers on UAE, Saudi Arabia, and Oman for structural materials, with MEP systems sourcing from Germany, Japan, and South Korea. Raw material dependencies include Portland cement, rebar, and HVAC chillers. Single-source vulnerability persists in specialized Category-A fit-out contractor pools. Distribution runs through sovereign-linked developer procurement frameworks that filter private vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
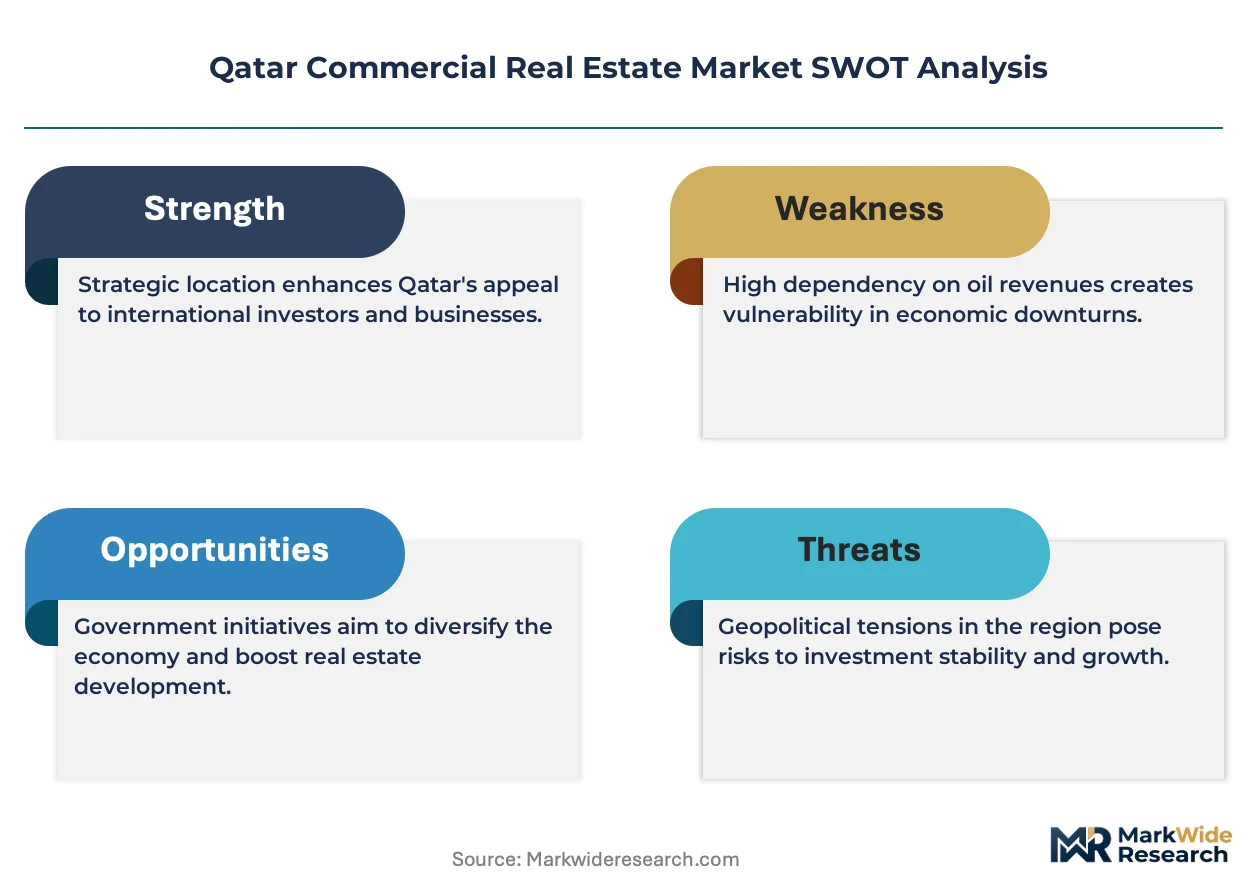
Qatar's commercial real estate market functions as a defensive-moat story anchored in regulatory entrenchment. Sovereign-linked land release schedules and Qatar Financial Centre ownership frameworks create structural barriers that external capital cannot replicate.
For Market Incumbents: Consolidate around Msheireb Downtown and Lusail City mixed-use pipelines where zoning experiments create captive demand. Deepen backward integration into specialized fit-out capability to offset contractor scarcity threatening project timelines. Acquire distressed West Bay inventory facing functional obsolescence from Grade-A specification thresholds.
For New Entrants and Emerging Players: Differentiate on smart building convergence and IoT-enabled asset management services that institutional landlords lack in-house. Target Hamad Port logistics corridor warehouse development where e-commerce fulfillment demand outpaces sovereign developer capacity. Pursue joint venture structures with Qatari Diar or Msheireb Properties to access controlled land pipelines.
For Investors and Strategic Acquirers: Capital is best deployed toward stabilized office assets with energy sector covenants and GSAS certification pathways that trade at yield premiums reflecting covenant quality. Long-term viability hinges on foreign ownership liberalization trajectory across Lusail freehold experiments. Monitor Qatar Central Bank real estate lending guideline revisions as inflection indicator for institutional capital flow velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Program | GSAS compliance pathways differentiate premium stock from functionally obsolete inventory in West Bay. |
| Joint Venture Structure | Partnerships with Qatari Diar unlock access to Lusail master-planned development pipelines. |
| Smart Building Integration | IoT-enabled MEP monitoring creates rental premium differentiation in Grade-A office assets. |
| Logistics Capacity Expansion | High-bay distribution center development near Hamad Port captures e-commerce fulfillment demand. |
| Freehold Title Experimentation | Lusail foreign ownership templates expand investor access beyond traditional leasehold restrictions. |
Research Methodology
Desk research of Qatar Central Bank regulatory filings, Ministry of Municipality and Environment building code documentation, and Qatar Financial Centre ownership framework precedents preceded structured interviews with sovereign developer project directors, institutional asset managers, energy sector real estate procurement leads, and specialized fit-out contractors. Secondary validation drew from customs trade data, sovereign wealth fund real estate allocation disclosures, and regional construction cost indices. Bottom-up project pipeline enumeration triangulated against top-down capital flow estimates from institutional investor allocation surveys.
Variance decomposition across asset type, property ownership structure, investment stage, and end-user segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to documented absorption rates and pre-commitment activity. Forecast inputs incorporated Qatar's building energy code compliance cost trajectories and foreign ownership liberalization scenario weights.
Material uncertainties — construction input cost volatility, green certification timeline slippage, and sovereign land release schedule adjustments — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as Lusail freehold title experiments and Msheireb Downtown zoning templates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
China Commercial Real Estate Market