
 Brazil Commercial Real Estate Market | 2026-2036
Brazil Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Commercial Real Estate Market Insights
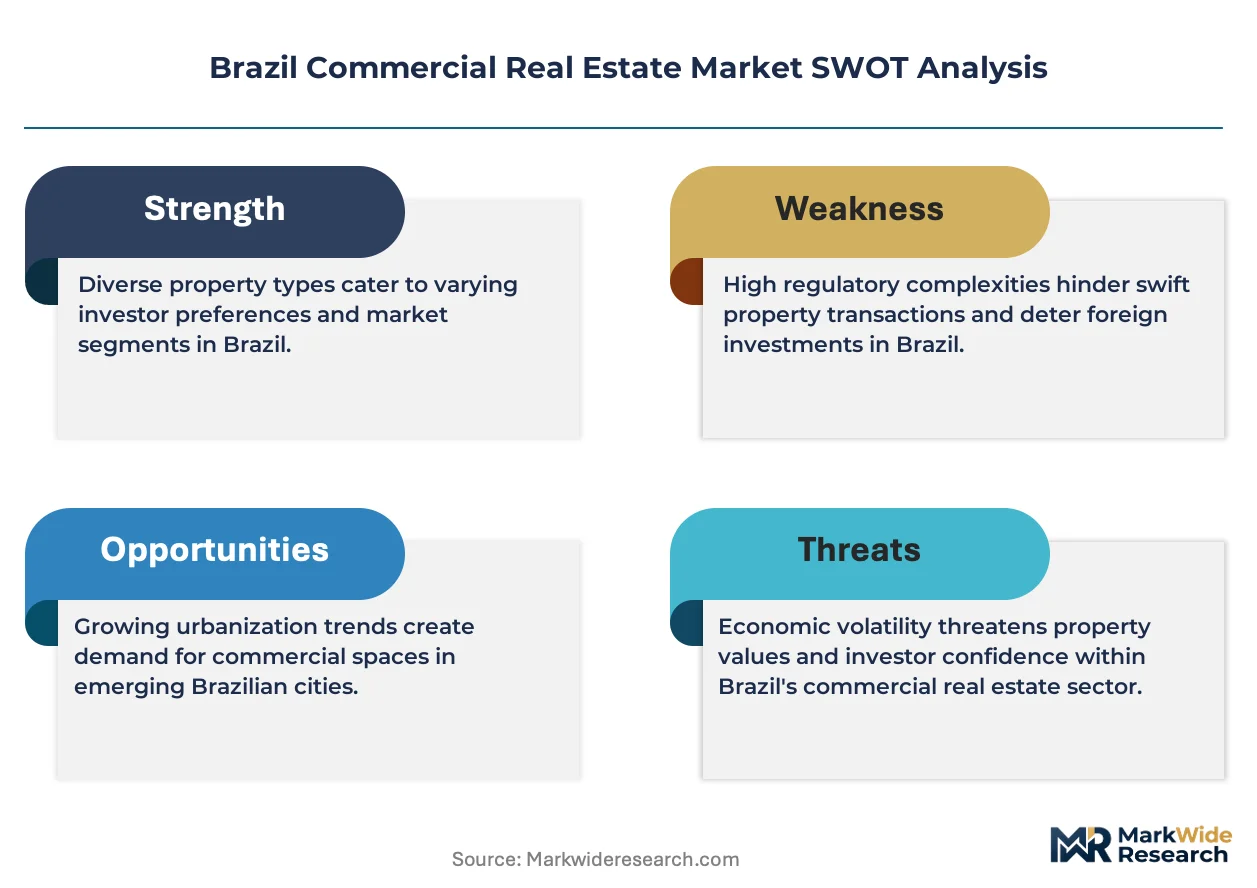
Multi-source capital deployment is broadening across Brazil's commercial property sector as domestic and cross-border investors diversify financing structures. BR Properties leverages its logistics-focused portfolio to capture institutional inflows into industrial assets. JHSF Participações anchors premium retail and mixed-use developments in São Paulo's prime corridors. Brookfield Brasil sustains scale advantages through integrated asset management and development platforms.
Brazil commercial real estate encompasses income-producing properties including office towers, retail centers, industrial warehouses, and mixed-use complexes, typically constructed with reinforced concrete frames, curtain wall glazing systems, and floor plates ranging from 500 to 2,500 square meters to accommodate diverse tenant configurations. These assets generate returns through lease contracts, capital appreciation, and development margins, serving corporations seeking operational headquarters, retailers requiring consumer-facing space, and logistics operators demanding high-clearance distribution facilities. Office and industrial segments attract the deepest institutional capital pools, with logistics assets commanding yield compression due to supply constraints in São Paulo's last-mile zones. Retail properties face structural repositioning as experiential formats and omnichannel integration reshape tenant demand, while mixed-use developments gain preference from municipalities seeking denser, transit-adjacent zoning outcomes.
ANVISA regulates health and safety standards in commercial buildings with medical or pharmaceutical tenant occupancy, while municipal zoning codes and the federal Statute of Cities shape permissible density, use mixing, and environmental compliance across metropolitan regions. The Central Bank of Brazil's monetary policy and foreign investment frameworks directly influence debt availability and cross-border equity participation in property acquisitions. Stakeholders must monitor how interest rate trajectories and municipal infrastructure commitments alter return thresholds across property types and investment strategies.
Market Dynamics
Institutional capital inflows into São Paulo's logistics corridor are compressing industrial yields and accelerating development timelines for last-mile distribution centers. This capital concentration is restructuring competitive positioning across Brazil's commercial property sector.
Growth Catalysts
- Statute of Cities:Brazil's updated federal zoning framework accelerates mixed-use project approvals in metropolitan regions. Municipalities now grant denser entitlements for transit-adjacent developments.
- E-commerce fulfillment:Online retail operators demand high-clearance warehouses with automated sorting capabilities. This tenant category absorbs speculative industrial supply within 90 days of completion.
- Reinforced concrete framing:Local construction material availability supports rapid vertical delivery of office towers. Developers achieve 18-month construction cycles for standardized floor plates.
Market Restraints
- Cement price volatility:Input cost swings for reinforced concrete frames compress development margins. Projects face 8-12 month procurement hedging requirements.
- Central Bank rate trajectory:Brazil's monetary policy tightening elevates debt service coverage thresholds. Acquisition financing now requires 35-40% equity contributions versus 25% historically.
- Curtain wall supply:Glazing system fabrication concentrates among three domestic suppliers. Lead times extend to 20 weeks during peak construction windows.
Strategic Opportunities
- Secondary São Paulo corridors:Sorocaba and Jundiaí submarkets offer yield premiums of 150-200 basis points over central zones. Institutional capital remains underweight in these radii.
- Experiential retail formats:Entertainment-anchored mixed-use developments capture municipal density bonuses. ANVISA-compliant medical office components diversify tenant mix.
- Green building certification:Municipalities increasingly mandate LEED or GBCI standards for zoning incentives. Early certification adopters secure faster entitlement timelines.
Industry Challenges
- Construction labor scarcity:Specialized curtain wall installation crews command 40% wage premiums. Project delays accumulate during peak demand quarters.
- Legacy system integration:Automated warehouse tenants require building management system upgrades incompatible with 1990s-era industrial stock. Retrofit capex runs 15-20% of replacement cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Commercial Real Estate Market |
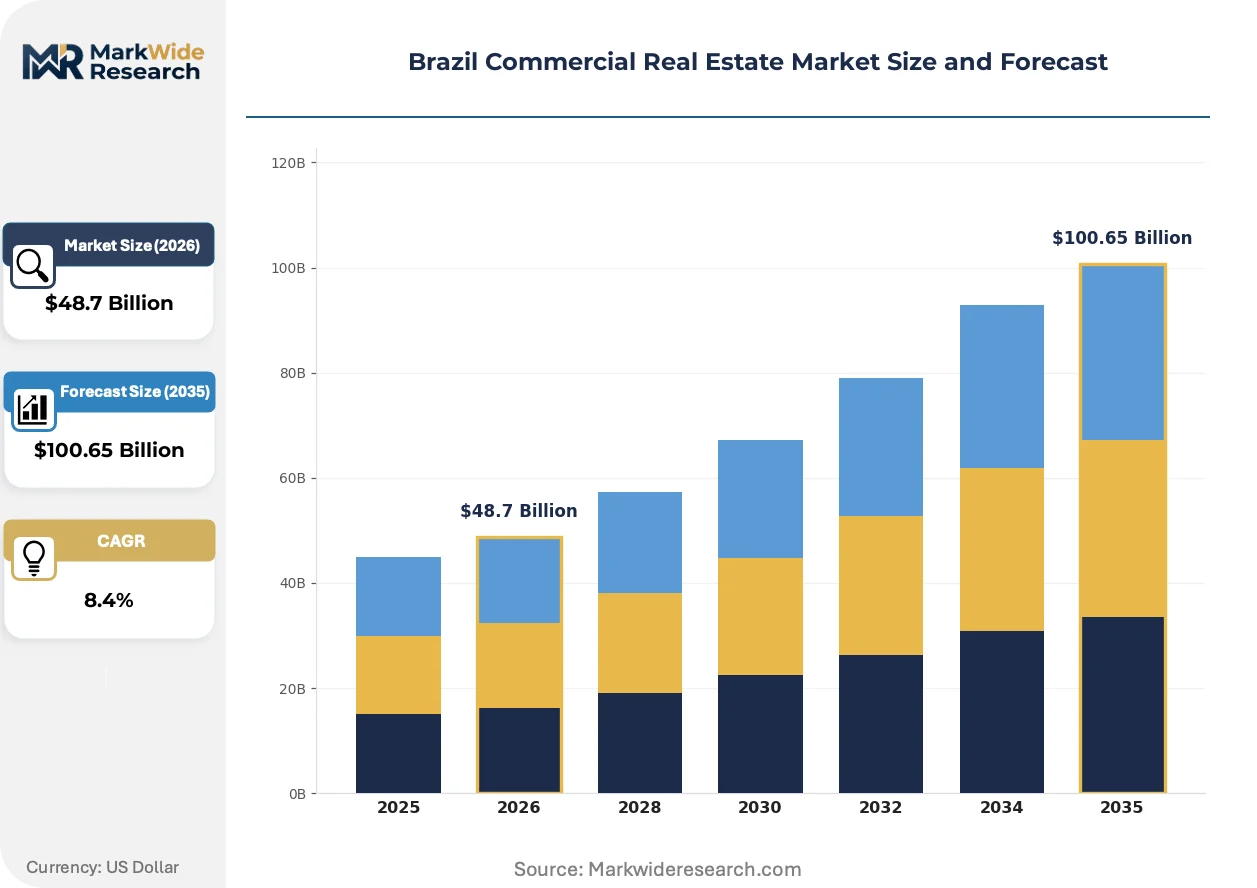
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Strategy: Core, Value-Add, Opportunistic, Development End User: Corporations, Investors, Government, Occupiers Financing Source: Equity, Debt, Institutional, Private |
| Companies Covered | BR Properties, JHSF Participações, Cyrela Commercial Properties, Brookfield Brasil, Iguatemi, LOG Commercial Properties, Aliansce Sonae, CBRE Brasil, Multiplan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Commercial Real Estate Market Trends and Innovations
Digital infrastructure and regulatory modernization are converging to reshape Brazil's commercial property development and leasing models. These shifts compress decision cycles and alter capital deployment patterns across asset classes.
Smart building management systems is converging with IoT sensor networks to enable real-time energy optimization and predictive maintenance protocols. Logistics operators and Class A office tenants now mandate these capabilities as standard lease requirements. This technology convergence is compressing operating expense ratios and extending asset competitive lifecycles in São Paulo's prime submarkets.
ANVISA's updated health facility standards now mandate specific HVAC filtration and spatial configuration for medical office tenants. Property owners must certify compliance before executing leases with pharmaceutical or clinical operators. The medical office segment faces accelerated obsolescence risk for pre-2010 stock unable to achieve certification without structural retrofit.
Omnichannel retailers now consolidate previously fragmented warehousing and showroom functions into unified experiential distribution centers. This format displaces traditional street-front retail in São Paulo's affluent corridors. The behavioral shift is most visible in Pinheiros and Vila Madalena, where converted industrial assets command rents exceeding conventional retail benchmarks.
Brazil Commercial Real Estate Market Segmentation
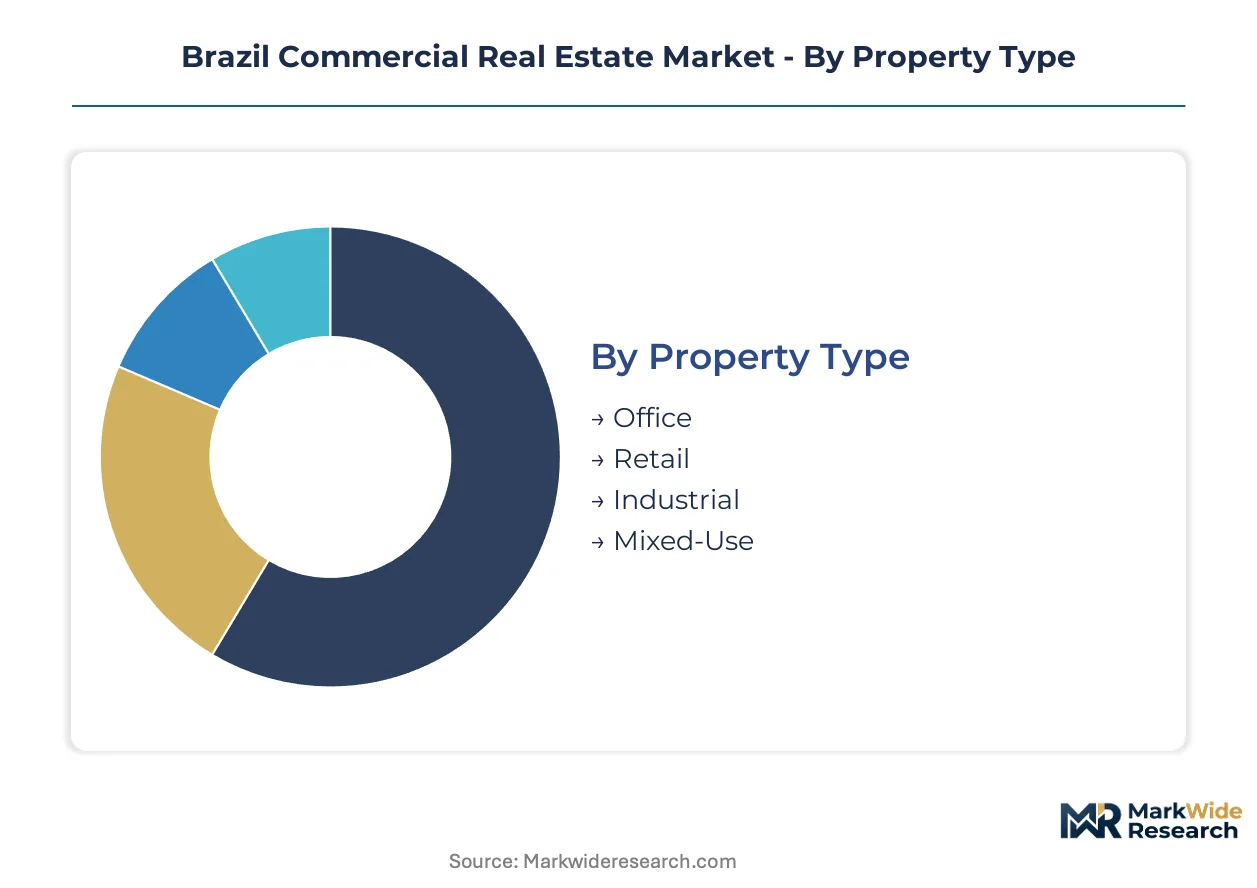
Segmentation reveals how capital flows diverge across property types and risk profiles in Brazil's commercial real estate sector. Investment strategies and financing structures determine which developments attract institutional commitment versus speculative capital.
Property Type:
Capital intensity varies dramatically across property categories, with industrial and mixed-use developments commanding the highest upfront commitments.
- Office:Reinforced concrete framing with curtain wall glazing systems supports 500-2,500 square meter floor plates. São Paulo's prime corridors attract institutional capital seeking stable lease terms from corporate headquarters tenants, though vacancy pressures persist in legacy stock.
- Industrial:High-clearance warehouses with automated sorting capabilities absorb speculative supply within 90 days of completion. E-commerce logistics operators in Greater São Paulo drive yield compression through concentrated demand for last-mile distribution centers.
- Retail:Experiential formats and omnichannel integration reshape tenant requirements. Entertainment-anchored developments capture municipal density bonuses under the Statute of Cities framework.
- Mixed-Use:Transit-adjacent projects benefit from accelerated entitlement timelines under updated federal zoning. ANVISA-compliant medical office components diversify revenue streams within unified developments.
Most installed capacity flows through Office. Expansion is steepest in Industrial.
Investment Strategy:
Risk-return profiles segment capital deployment between stabilized income and development margin capture.
- Core:Stabilized assets with long-lease tenants in São Paulo's established submarkets. Central Bank rate tightening elevates equity requirements to 35-40% for acquisition financing.
- Value-Add:Repositioning of 1990s-era industrial stock requires building management system upgrades. Retrofit capital expenditures run 15-20% of replacement cost for automated warehouse compatibility.
- Opportunistic:Distressed or undermanaged assets in secondary São Paulo corridors. Sorocaba and Jundiaí submarkets offer yield premiums of 150-200 basis points over central zones.
- Development:Ground-up construction faces 8-12 month procurement hedging requirements due to cement price volatility. 18-month delivery cycles apply for standardized office towers.
Core strategies dominate institutional allocation. Development approaches are gaining share fastest among cross-border investors.
End User:
Tenant and owner-occupier requirements shape design specifications and location decisions.
- Corporations:Class A office tenants mandate smart building management systems and IoT sensor networks as standard lease requirements. Operating expense compression drives technology adoption.
- Investors:Yield-focused buyers target logistics assets facing supply constraints in São Paulo's last-mile zones. Green building certification accelerates entitlement timelines for certified portfolios.
- Government:Municipal infrastructure commitments influence return thresholds across property types. Public sector leases provide credit-stable income streams.
- Occupiers:Omnichannel retailers consolidate warehousing and showroom functions into unified experiential distribution centers. Converted industrial assets in Pinheiros and Vila Madalena command premium rents.
Corporations anchor leasing volume. Investor acquisitions are climbing the fastest.
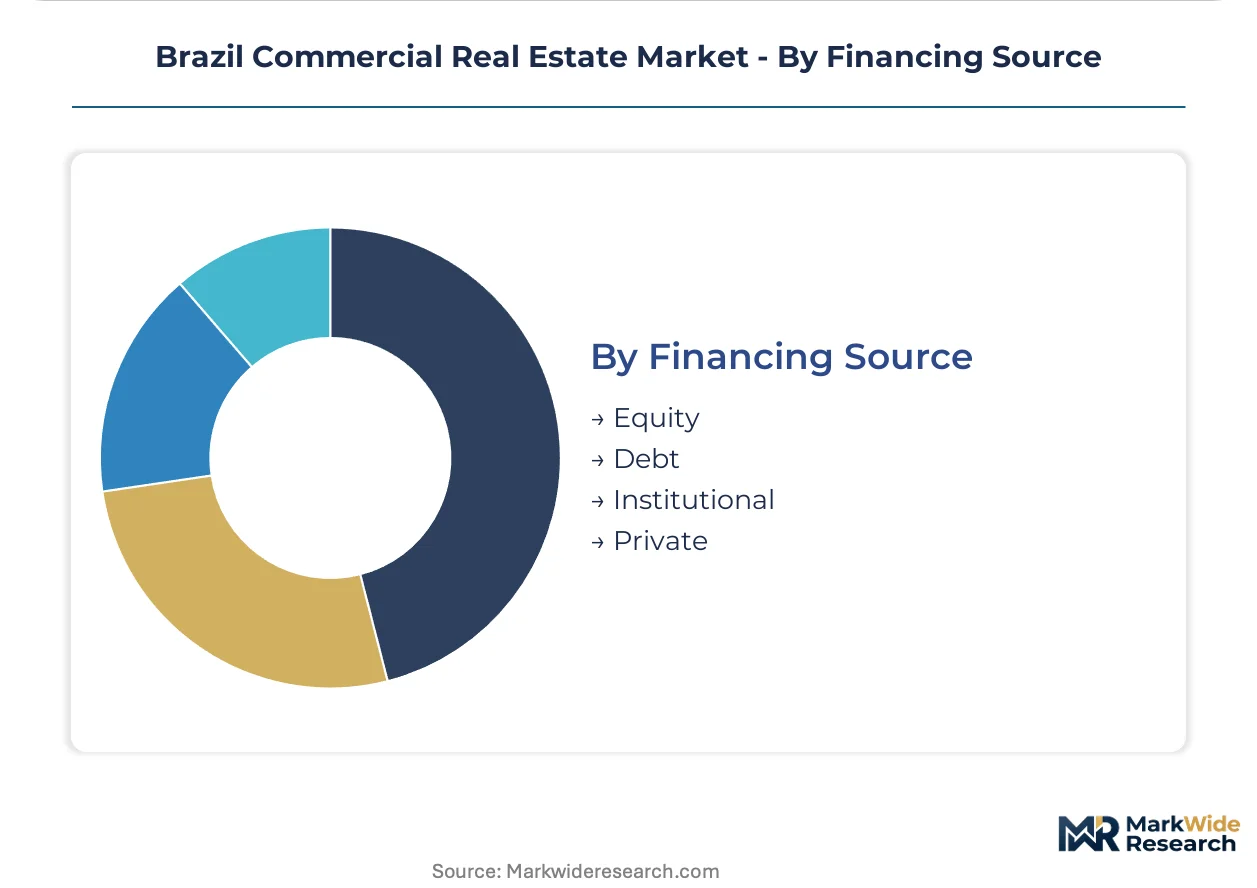
Financing Source:
Capital structure composition determines project feasibility and return distribution.
- Equity:Domestic and cross-border investors diversify financing structures through direct asset ownership. Higher equity contributions now required due to monetary policy tightening.
- Debt:Central Bank of Brazil policy directly influences debt availability and coverage thresholds. Foreign investment frameworks shape cross-border participation in leveraged acquisitions.
- Institutional:Pension funds and insurance companies concentrate deployment in São Paulo's logistics corridor. Capital inflows compress industrial yields and accelerate development timelines.
- Private:Family offices and high-net-worth individuals target secondary corridor yield premiums. Specialized capital fills gaps left by institutional underweight positions.
Institutional sources command the largest deployment volumes. Private capital is expanding most quickly into underserved submarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater São Paulo anchors Brazil's commercial real estate investment flows, concentrating institutional capital deployment across logistics corridors and modern office submarkets. The metropolitan region's infrastructure density and tenant liquidity attract cross-border equity participation at scale unmatched elsewhere in the country.
São Paulo
E-commerce logistics operators and corporate headquarters tenants drive absorption in the central business district and last-mile distribution zones. ANVISA's health facility standards shape medical office development specifications in Pinheiros and Vila Madalena. Sorocaba and Jundiaí submarkets offer yield premiums of 150-200 basis points as institutional capital remains underweight in these radii.
Rio de Janeiro
Port-adjacent industrial assets and premium retail repositioning attract value-add capital targeting experiential formats. Municipal zoning under the Statute of Cities framework accelerates mixed-use entitlements in transit-accessible corridors. Barra da Tijuca and Porto Maravilha concentrate development activity as developers capture density bonuses for integrated projects.
Minas Gerais
Belo Horizonte's administrative and mining services sectors sustain Class B office demand in the Savassi and Lourdes submarkets. The Central Bank of Brazil's monetary policy tightening elevates equity requirements for acquisition financing statewide. Confins airport corridor logistics facilities capture distribution network expansion from São Paulo-based operators.
Rio Grande do Sul
Porto Alegre's industrial park network and Mercosur trade positioning attract logistics developers targeting cross-border freight flows. State-level environmental compliance protocols extend entitlement timelines for greenfield warehouse construction. Canoas and São Leopoldo cluster automated distribution center development near the Salgado Filho airport zone.
Paraná
Curitiba's planned urbanism legacy supports transit-oriented mixed-use development under updated federal zoning. Agricultural commodity trading and food processing tenants drive specialized cold storage warehouse demand. The Londrina and Maringá corridors attract secondary market capital seeking yield spreads over São Paulo benchmarks.
Brazil Commercial Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue secondary corridor logistics and experiential retail repositioning. The market structures around three tiers: integrated asset managers with development platforms, specialized logistics-focused portfolios, and diversified retail-mixed-use operators. Competitive positioning depends on entitlement velocity under the Statute of Cities and capital structure flexibility amid Central Bank rate tightening. Consolidation pressures favor scale advantages in procurement and tenant relationship management.
Within the integrated asset management tier, Brookfield Brasil exemplifies cross-border capital deployment at institutional scale. BR Properties and JHSF Participações anchor distinct strategic positions—BR Properties concentrating logistics-focused portfolios to capture industrial yield compression, while JHSF Participações occupies premium mixed-use development in São Paulo's prime corridors. These three entities represent the dominant capital formation archetypes shaping competitive dynamics.
| Leading Market Players |
|---|
| BR Properties |
| JHSF Participações |
| Cyrela Commercial Properties |
| Brookfield Brasil |
| Iguatemi |
| LOG Commercial Properties |
| Aliansce Sonae |
| CBRE Brasil |
| Multiplan |
| Others |
Pricing and Supply Chain Analysis
E-commerce logistics operators in Greater São Paulo drive contract-based pricing structures for industrial assets, with lease rates tethered to construction input indices and municipal entitlement velocity. This buyer concentration amplifies developer pricing power in last-mile zones while compressing margins in secondary corridors where speculative supply outpaces absorption.
Pricing Analysis
Input-cost pass-through dominates lease negotiations, with cement price volatility and curtain wall procurement premiums flowing directly to tenant rates. Price differentiation hinges on ANVISA certification status for medical office components and LEED/GBCI green building tiers for entitlement acceleration. Pricing pressure stems from Central Bank monetary tightening, which elevates equity requirements and debt service coverage thresholds. Institutional investors exhibit lowest price sensitivity, absorbing yield compression in São Paulo's prime logistics corridor, while private capital in Sorocaba and Jundiaí submarkets negotiates harder on entry multiples.
Supply Chain Analysis
Local-content rules under Brazil's federal procurement frameworks and municipal construction codes reshape sourcing patterns for reinforced concrete and glazing systems. Supply draws from domestic cement producers, regional steel fabricators, and three concentrated curtain wall suppliers. Raw material dependencies center on Portland cement, structural steel, and low-emissivity glass. Single-source vulnerability concentrates in glazing system fabrication, where 20-week lead times extend project timelines. Distribution runs through developer-procurement direct contracts and specialized contractor networks serving São Paulo's construction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's commercial real estate market functions as a regulatory compounder, with the Statute of Cities framework accelerating entitlement timelines and reshaping competitive returns across metropolitan regions.
For Market Incumbents: Deepen vertical control over curtain wall supply chains through captive procurement agreements or equity stakes in fabrication capacity. Anchor logistics portfolio positions in São Paulo's last-mile zones against emerging entrant competition from cross-border capital. Prioritize ANVISA pre-certification for medical office components to capture tenant switching costs as health facility standards tighten. For New Entrants and Emerging Players: Enter via secondary São Paulo corridor logistics development, where Sorocaba and Jundiaí submarkets offer yield premiums of 150-200 basis points with limited institutional competition. Target experiential retail repositioning in Rio de Janeiro's Barra da Tijuca and Porto Maravilha districts, where municipal density bonuses reduce effective land costs. Deploy green building certification as a go-to-market wedge to accelerate entitlement timelines against uncertified competitors. For Investors and Strategic Acquirers: Pension funds and insurance companies are the most active acquirers in this space, concentrating deployment in stabilized logistics assets with long-lease e-commerce tenants. Long-term viability rests on entitlement velocity advantages and construction cost discipline across the next market cycle. Monitor Central Bank rate trajectory as the primary inflection signal for acquisition financing feasibility and equity return thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification | LEED and GBCI standards unlock faster municipal entitlements under Statute of Cities zoning incentives. |
| Last-Mile Logistics Development | High-clearance warehouses in São Paulo's distribution corridors capture e-commerce tenant demand within 90 days. |
| Medical Office ANVISA Compliance | Pre-certified health facility specifications attract pharmaceutical and clinical operators facing accelerated obsolescence risk. |
| Secondary Corridor Expansion | Sorocaba and Jundiaí submarkets offer yield spreads over central São Paulo with underweight institutional presence. |
| Smart Building Technology Integration | IoT sensor networks and predictive maintenance protocols compress operating expenses for Class A office tenants. |
Research Methodology
Bottom-up tenant demand modeling reconciled against top-down construction pipeline tracking forms the analytical core of this study. Primary interviews with commercial real estate developers, institutional investment officers, municipal zoning administrators, and logistics operator facility managers were validated against secondary sources including Central Bank of Brazil monetary policy reports, ANVISA health facility standards filings, municipal entitlement databases under the Statute of Cities framework, and construction material price indices. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of absorption rates, vacancy levels, and yield compression patterns informs the projection framework across the analysis window. Segmentation dimensions include property type, investment strategy, end-user category, and financing source, with geographic clustering at metropolitan and submarket levels. CAGRs derive from regression-adjusted trend extrapolation incorporating construction cost inflation, regulatory entitlement velocity, and capital flow shifts. Industry-specific forecast inputs capture e-commerce fulfillment demand curves and municipal infrastructure commitment schedules.
Inputs from developer pipeline disclosures and institutional investor allocation surveys were available through the study window; gaps in private capital transaction pricing introduce uncertainty bands around secondary corridor yield estimates. Forecasts reflect documented assumptions regarding Central Bank policy trajectory and federal zoning implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Canada Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Qatar Commercial Real Estate Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market