
 South Africa Commercial Real Estate Market | 2026-2036
South Africa Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Commercial Real Estate Market Outlook
Grade-A specification upgrades is rotating demand toward premium office and logistics assets with superior energy performance and tenant amenities. Growthpoint Properties anchors institutional capital deployment through its diversified REIT platform across major metros. Redefine Properties competes through value-add repositioning of underperforming retail and office assets. Attacq Ltd dominates Waterfall City, South Africa's largest mixed-use development, leveraging integrated precinct planning.
South Africa commercial real estate encompasses income-producing property assets including office towers, retail centres, industrial warehouses, and mixed-use developments, typically evaluated through net operating income capitalization and lease covenant quality. The primary commercial purpose centers on generating risk-adjusted returns through rental yield and capital appreciation while managing tenant credit exposure and vacancy risk. Industrial and logistics assets lead structural growth, fueled by e-commerce supply chain expansion and port modernization around Durban and Cape Town. Retail remains the most mature segment with compressed yields in super-regional malls, while mixed-use precincts attract the fastest-growing capital allocation as developers blend residential, office, and experiential retail in single-title environments.
The National Regulator for Compulsory Specifications enforces SANS 10400 energy efficiency standards that elevate construction costs but differentiate compliant assets in tenant procurement. The Financial Sector Conduct Authority and Johannesburg Stock Exchange listing requirements govern REIT disclosure and distribution obligations, shaping institutional investment flows. Green Building Council South Africa certification now filters sovereign wealth and pension fund mandates, restricting capital access for non-rated developments. Stakeholders must monitor land use reform legislation and municipal rates restructuring as these policy vectors will redistribute development feasibility across provincial nodes.
Market Dynamics
The National Building Regulations and Building Standards Act energy efficiency amendments are compressing development timelines while elevating capital requirements for new commercial stock. Developers must now front-load compliance costs into project feasibility models, fundamentally altering site selection and tenant pre-commitment strategies.
Growth Catalysts
- E-commerce fulfillment networks:Third-party logistics operators are absorbing industrial space in Gauteng and KwaZulu-Natal at accelerated lease velocities, tightening vacancy rates in prime logistics nodes.
- SANS 10400-XA energy standards:The National Regulator for Compulsory Specifications mandates thermal performance benchmarks that differentiate green-certified assets in tenant procurement processes.
- Port modernization:Durban and Cape Town harbor infrastructure upgrades are repositioning last-mile distribution networks toward coastal industrial corridors.
Market Restraints
- Construction input cost volatility:Steel and cement price fluctuations are eroding development margins on speculative commercial projects in secondary metros.
- Municipal rates restructuring:Local government property valuation methodologies are creating assessment unpredictability that complicates long-term lease underwriting.
- Grid reliability constraints:Eskom load-shedding frequency is forcing capital diversion into captive power generation, inflating all-in occupancy costs.
Strategic Opportunities
- Green Building Council South Africa certification:GBCSA ratings are unlocking pension fund and sovereign wealth capital mandates that exclude non-compliant assets from investment universes.
- Mixed-use precinct development:Integrated residential-office-retail environments in Johannesburg's northern corridor are capturing premium effective rents through amenity bundling.
- Waterfall City model replication:Large-scale master-planned districts demonstrate how consolidated land control enables infrastructure cost recovery across phased development cycles.
Industry Challenges
- Green building skills scarcity:Certified energy modeling and sustainable construction management expertise remains concentrated among a limited pool of professional services firms.
- Land use reform uncertainty:Expropriation legislation debates are freezing site assembly timelines as landowners defer disposition decisions pending policy clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Commercial Real Estate Market |
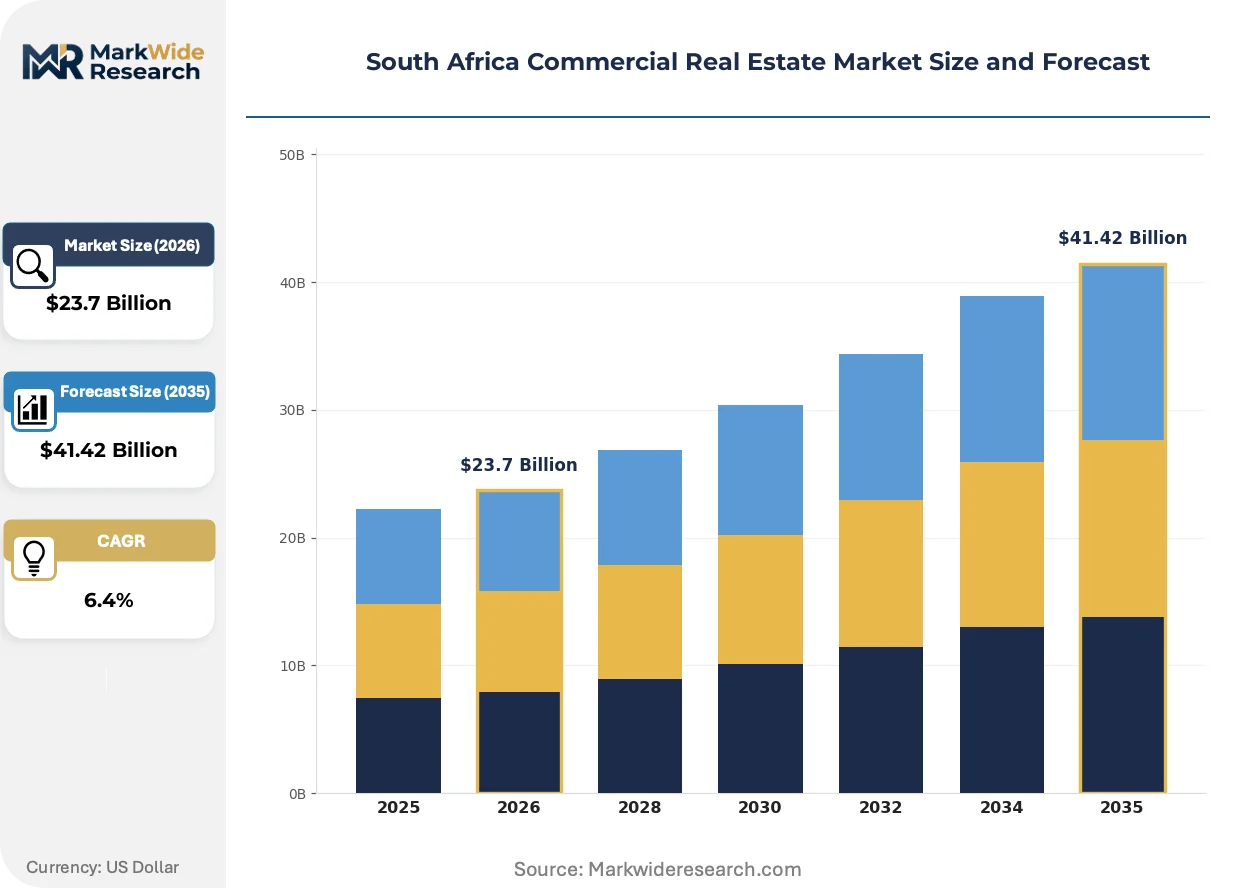
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Client Type: Investors, Developers, Tenants, Brokers Investment Strategy: Value-Add, Core, Opportunistic, Income-Generating Funding Source: Institutional Investors, Private Equity, REITs, Crowdfunding |
| Companies Covered | Growthpoint Properties, Amdec Group, Redefine Properties, Fortress REIT, Excellerate JHI, PAM Golding Properties, Attacq Ltd, Broll Property Group, Liberty Two Degrees, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Commercial Real Estate Market Strategic Shifts
Digital infrastructure integration and regulatory compliance automation are converging to reshape asset management protocols. These forces are compressing operational response cycles while elevating data transparency requirements across the property lifecycle.
Smart building management systems are decomposing traditional facilities management cost structures. Institutional landlords in Johannesburg's premium office nodes are deploying IoT-enabled energy optimization platforms to reduce utility pass-through volatility. This technology is decomposing the landlord-tenant information asymmetry that historically obscured actual consumption patterns.
The National Building Regulations energy efficiency amendments are mandating passive design and renewable integration in new commercial construction. SANS 10400-XA compliance is elevating professional indemnity exposure for architects and engineers. Retail developments in coastal metros are responding through solar PV pre-installation and thermal envelope specification upgrades.
Tenant covenant scrutiny is intensifying as institutional capital prioritizes lease duration and counterparty credit quality. Long-term gross leases with fixed escalations are yielding to shorter-term structures with turnover-linked components. This recalibration is most visible in Cape Town's Atlantic Seaboard office submarket where tech and professional services tenants dominate absorption.
South Africa Commercial Real Estate Market Segmentation
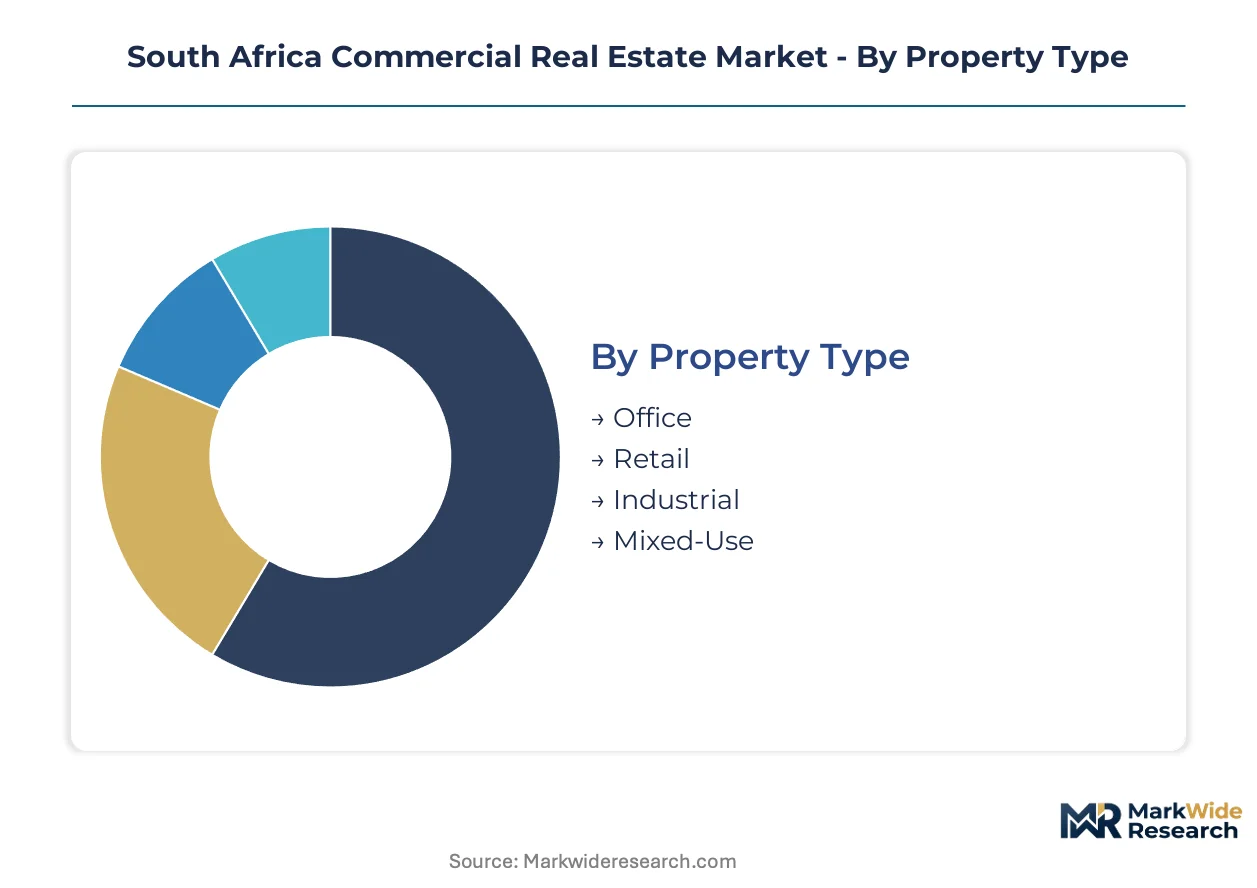
Segmentation in South African commercial real estate reveals how capital flows, tenant demand, and regulatory compliance intersect across distinct asset classes and stakeholder categories. Understanding these divisions enables precise targeting of development pipelines and investment mandates.
Property Type:
Margin pools concentrate in logistics assets where e-commerce fulfillment demand outstrips supply, while office compression creates value-add repositioning opportunities.
- Office:Grade-A buildings in Johannesburg's northern corridor and Cape Town's Atlantic Seaboard command premium rents through superior energy performance and tenant amenities. SANS 10400-XA compliance is filtering institutional capital toward certified stock, leaving secondary assets exposed to vacancy risk.
- Industrial:Warehouse and distribution facilities in Gauteng and KwaZulu-Natal absorb accelerated leasing from third-party logistics operators. Port modernization around Durban and Cape Town is repositioning last-mile networks toward coastal corridors with superior freight connectivity.
- Retail:Super-regional malls face yield compression as experiential retail and convenience formats displace traditional department store anchors.
- Mixed-Use:Integrated residential-office-retail precincts capture premium effective rents through amenity bundling and consolidated land control.
Industrial holds installed capacity. Mixed-Use is rotating up the share rankings.
Client Type:
Volume concentrates with institutional investors deploying patient capital through REIT platforms, while developers front-load compliance costs into feasibility models.
- Investors:Pension funds and sovereign wealth mandates now exclude non-GBCSA-rated assets, restricting capital access for uncertified developments. These entities prioritize lease duration and counterparty credit quality over speculative yield.
- Developers:Site assembly timelines freeze amid land use reform uncertainty, compressing development windows for speculative commercial projects. Front-loaded SANS 10400 compliance costs alter tenant pre-commitment strategies.
- Tenants:Tech and professional services firms in Cape Town's Atlantic Seaboard drive absorption of shorter-term, turnover-linked lease structures.
- Brokers:Advisory fees compress as data transparency from smart building systems reduces information asymmetry between landlords and occupiers.
Investors hold installed capacity. Developers is rotating up the share rankings.
Investment Strategy:
Cost tiers separate core income stability from opportunistic repositioning plays requiring active asset management.
- Core:Stabilized, fully-leased assets in prime nodes generate predictable distributions for risk-averse institutional mandates. These properties trade at tight cap rates reflecting covenant quality and lease duration.
- Value-Add:Underperforming retail and office assets compete for capital through energy retrofit programs and tenant mix reconfiguration. Redefine Properties anchors this segment through active repositioning.
- Opportunistic:Distressed or development-stage projects in secondary metros attract private equity seeking outsized returns through construction completion or lease-up risk.
- Income-Generating:Long-term gross leases with fixed escalations yield to shorter structures with turnover-linked components, recalibrating risk-return profiles.
Core holds installed capacity. Value-Add is rotating up the share rankings.
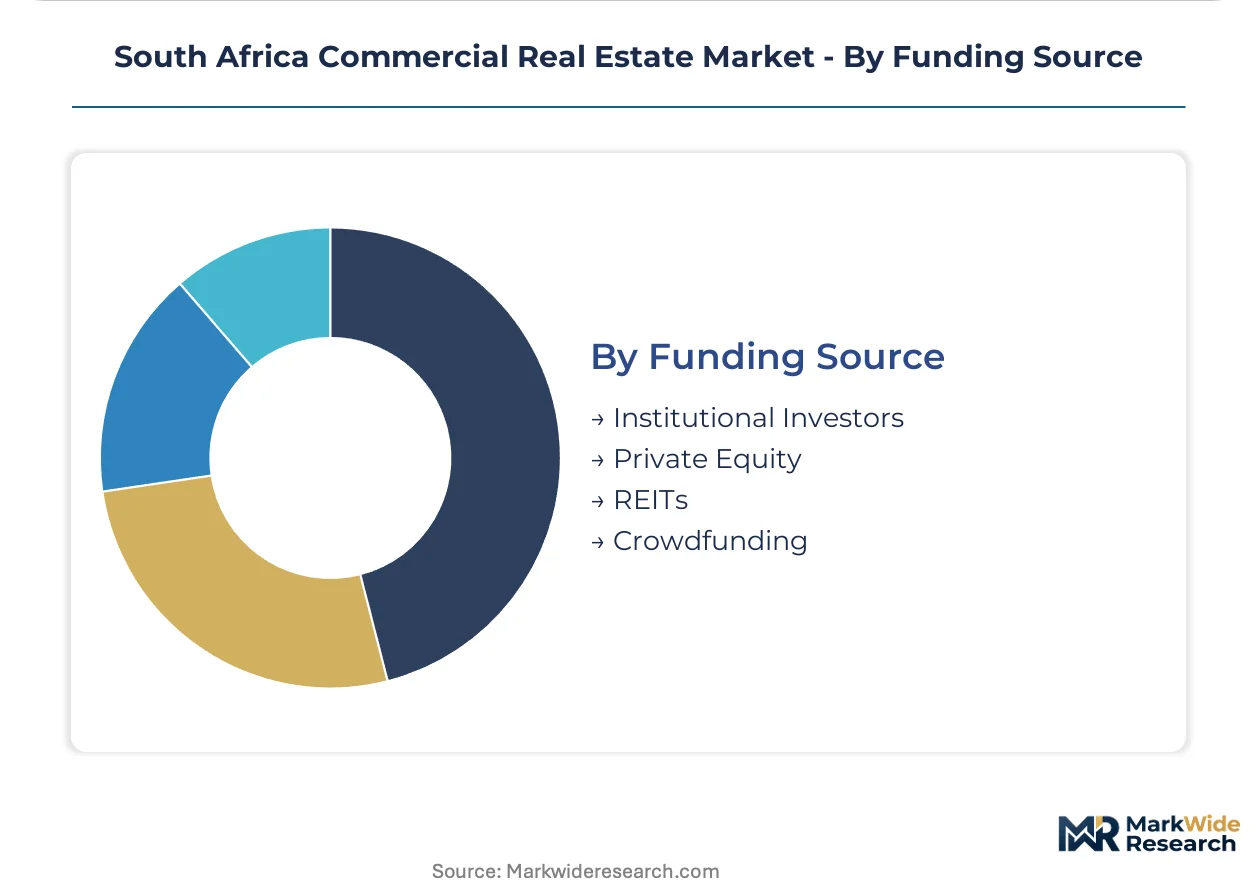
Funding Source:
Supply concentration sits with REITs and institutional investors, while crowdfunding fragments retail capital participation.
- Institutional Investors:Pension funds and sovereign wealth vehicles deploy through Growthpoint Properties' diversified platform across major metros. GBCSA certification filters now govern mandate eligibility.
- REITs:Johannesburg Stock Exchange listing requirements govern disclosure and distribution obligations, shaping capital access for compliant platforms. Attacq Ltd dominates Waterfall City through integrated precinct planning.
- Private Equity:Value-add and opportunistic strategies attract capital for distressed asset repositioning and development completion risk in secondary nodes.
- Crowdfunding:Retail participation fragments across digital platforms, concentrating in small-ticket mixed-use and residential components rather than institutional-grade commercial assets.
Institutional Investors hold installed capacity. REITs is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's commercial real estate market exhibits pronounced internal trade dynamics, with Gauteng functioning as the primary capital import hub while Western Cape and KwaZulu-Natal concentrate export-oriented logistics and coastal development flows.
Gauteng Province
Johannesburg's northern corridor anchors premium office absorption, driven by financial services and professional services tenant demand. The National Building Regulations and Building Standards Act energy efficiency amendments mandate SANS 10400-XA compliance for new construction in Tshwane and Johannesburg metros. Waterfall City in Midrand demonstrates integrated precinct planning at scale, consolidating mixed-use development under single-land-control mechanisms.
Western Cape
Cape Town's Atlantic Seaboard commands the highest effective rents for Grade-A office stock, attracting tech sector tenants and professional services firms. Green Building Council South Africa certification filters institutional capital mandates, restricting pension fund deployment to GBCSA-rated assets in Cape Town and Stellenbosch. The port modernization program around Table Bay harbor repositions last-mile distribution networks toward coastal industrial corridors.
KwaZulu-Natal
Durban harbor infrastructure upgrades drive accelerated warehouse absorption from third-party logistics operators serving import-export trade lanes. The National Regulator for Compulsory Specifications enforces thermal performance benchmarks that elevate construction costs but differentiate compliant assets in tenant procurement. Pinetown and Durban's industrial nodes tighten vacancy rates as e-commerce fulfillment networks expand port-proximate capacity.
Eastern Cape
Port Elizabeth and East London industrial zones benefit from automotive sector supply chain requirements, though development activity lags primary metros. Coega Special Economic Zone incentives attract manufacturing-linked commercial development, with the Eastern Cape Development Corporation facilitating land assembly for speculative projects. Gqeberha's port expansion plans signal future logistics capacity growth.
South Africa Commercial Real Estate Market Competitive Environment
Concentration sits with diversified REIT platforms and integrated precinct developers controlling land assembly at scale. Institutional capital deployment flows through Johannesburg Stock Exchange-listed vehicles with compliant disclosure and distribution obligations. Three archetypes dominate: diversified REITs with multi-asset portfolios, specialized precinct developers with consolidated land control, and value-add repositioning specialists targeting underperforming retail and office assets. Competitive dynamics center on green certification acquisition and tenant pre-commitment securing ahead of construction completion.
Among diversified REIT platforms, Growthpoint Properties anchors institutional capital deployment across major metros, while Redefine Properties occupies a position within the value-add repositioning tier. Attacq Ltd exemplifies the integrated precinct developer archetype through its dominant position in Waterfall City, South Africa's largest mixed-use development.
| Leading Market Players |
|---|
| Growthpoint Properties |
| Amdec Group |
| Redefine Properties |
| Fortress REIT |
| Excellerate JHI |
| PAM Golding Properties |
| Attacq Ltd |
| Broll Property Group |
| Liberty Two Degrees |
| Others |
Value Chain & Pricing Dynamics
Solar PV and thermal envelope upgrades replacing conventional building shells are compressing development margins while elevating asset premiums, simultaneously shifting procurement geography toward certified component suppliers and bifurcating rental economics between compliant and non-compliant stock.
Pricing Analysis
Industrial OEM buyers anchor lease rate negotiations through long-term gross lease structures with fixed escalations, though shorter turnover-linked terms are displacing these in Cape Town's Atlantic Seaboard. Pricing stratifies across GBCSA-certified premium stock, SANS 10400-XA compliant standard assets, and uncertified secondary inventory with vacancy exposure. Cost compression in speculative development is intensifying because steel and cement input volatility erodes feasibility margins. Third-party logistics operators show least price sensitivity due to supply chain criticality, while retail tenants in super-regional malls face highest renegotiation pressure.
Supply Chain Analysis
Durban harbor capacity constraints and Cape Town port modernization timelines underwrite delivery unpredictability for imported building materials and MEP equipment. China, Germany, and India anchor supply for solar PV modules, high-performance glazing, and HVAC systems respectively. Raw material dependencies center on steel reinforcement, Portland cement, and copper electrical cabling. Single-source vulnerability concentrates in certified energy modeling software and specialized green building consultancy services. Distribution runs through developer-procured direct contracts with tier-one contractors rather than merchant distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management and energy optimization services attach to physical assets faster than base rental growth, as institutional landlords deploy IoT-enabled platforms to capture recurring revenue streams beyond lease escalations.
For Market Incumbents: Secure tenant pre-commitments ahead of SANS 10400-XA compliance cost front-loading, locking in lease duration before construction cost inflation. Anchor defensive positioning through backward integration into captive solar PV installation capacity, reducing third-party EPC exposure and utility pass-through volatility. For New Entrants and Emerging Players: Lead with green building certification consultancy and energy modeling services, white-space segments where certified professional expertise concentrates among limited incumbent firms. Target secondary metro industrial development in Eastern Cape and KwaZulu-Natal coastal corridors, penetrating nodes where institutional capital deployment lags Gauteng and Western Cape saturation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed value-add specialists holding underperforming retail and office stock ripe for energy retrofit repositioning. Long-term viability hinges on lease covenant quality and GBCSA certification acquisition ahead of pension fund mandate exclusion thresholds. Monitor Eskom grid reliability announcements as the critical inflection signal for captive power generation capex cycles and associated tenant cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Acquisition | GBCSA ratings unlock pension fund and sovereign wealth capital mandates that exclude non-compliant assets. |
| Integrated Precinct Development | Waterfall City demonstrates how consolidated land control enables infrastructure cost recovery across phased cycles. |
| Energy Retrofit Program | SANS 10400-XA compliance differentiates repositioned assets in tenant procurement against secondary stock. |
| Last-Mile Logistics Capacity Buildout | Durban and Cape Town port modernization repositions distribution networks toward coastal industrial corridors. |
| Smart Building Management Platform Deployment | IoT-enabled energy optimization reduces utility pass-through volatility and decomposes landlord-tenant information asymmetry. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with REIT portfolio managers, commercial development directors, tenant representation brokers, facilities management executives, and municipal planning officers. Secondary validation drew from Johannesburg Stock Exchange REIT disclosure filings, National Regulator for Compulsory Specifications enforcement bulletins, Green Building Council South Africa certification databases, and municipal rates restructuring policy documents. Bottom-up lease transaction aggregation and top-down capital flow triangulation converged on segment-level estimates.
Across the analysis window, forecasts incorporate property type segmentation by office, industrial, retail, and mixed-use; investment strategy tiering across core, value-add, and opportunistic; and funding source disaggregation by institutional, REIT, private equity, and crowdfunding channels. CAGRs were derived from historical absorption velocity trends, development pipeline tracking, and regulatory compliance cost trajectory modeling. Forecast inputs include e-commerce fulfillment network expansion rates, port modernization completion schedules, and land use reform legislative progression.
The analysis sits within stated boundaries; outcomes outside sustained institutional capital deployment, grid reliability stabilization, and municipal rates policy continuity would require recalibration. Practitioners should keep alternative scenarios live as expropriation legislation debates and Eskom generation capacity announcements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
China Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
UK Commercial Real Estate Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Israel Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
United States Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
Qatar Commercial Real Estate Market