
 Canada Commercial Real Estate Market | 2026-2036
Canada Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Commercial Real Estate Market Analysis
Property-as-a-service models are decoupling physical ownership from tenant utility, shifting revenue toward subscription-based maintenance and software-defined space management. Brookfield Properties leverages its global platform to sustain premium pricing across core office portfolios. Ivanhoé Cambridge anchors Quebec's institutional investment landscape through concentrated Montreal holdings. Dream Unlimited Corp. differentiates via mixed-use development expertise in Western Canada.
Canada commercial real estate encompasses income-producing properties including office towers, retail centers, industrial warehouses, and hospitality assets, typically structured through limited partnerships or REIT vehicles with leverage ratios governed by provincial securities regulators. The primary commercial purpose centers on generating risk-adjusted returns through rental yield and capital appreciation for institutional and private capital pools. Industrial properties lead transaction velocity as e-commerce fulfillment requirements reshape last-mile logistics demand across the Property Type dimension. Core strategies dominate institutional capital deployment within the Investment Strategy taxonomy, while value-add approaches capture widening bid-ask spreads in secondary office markets.
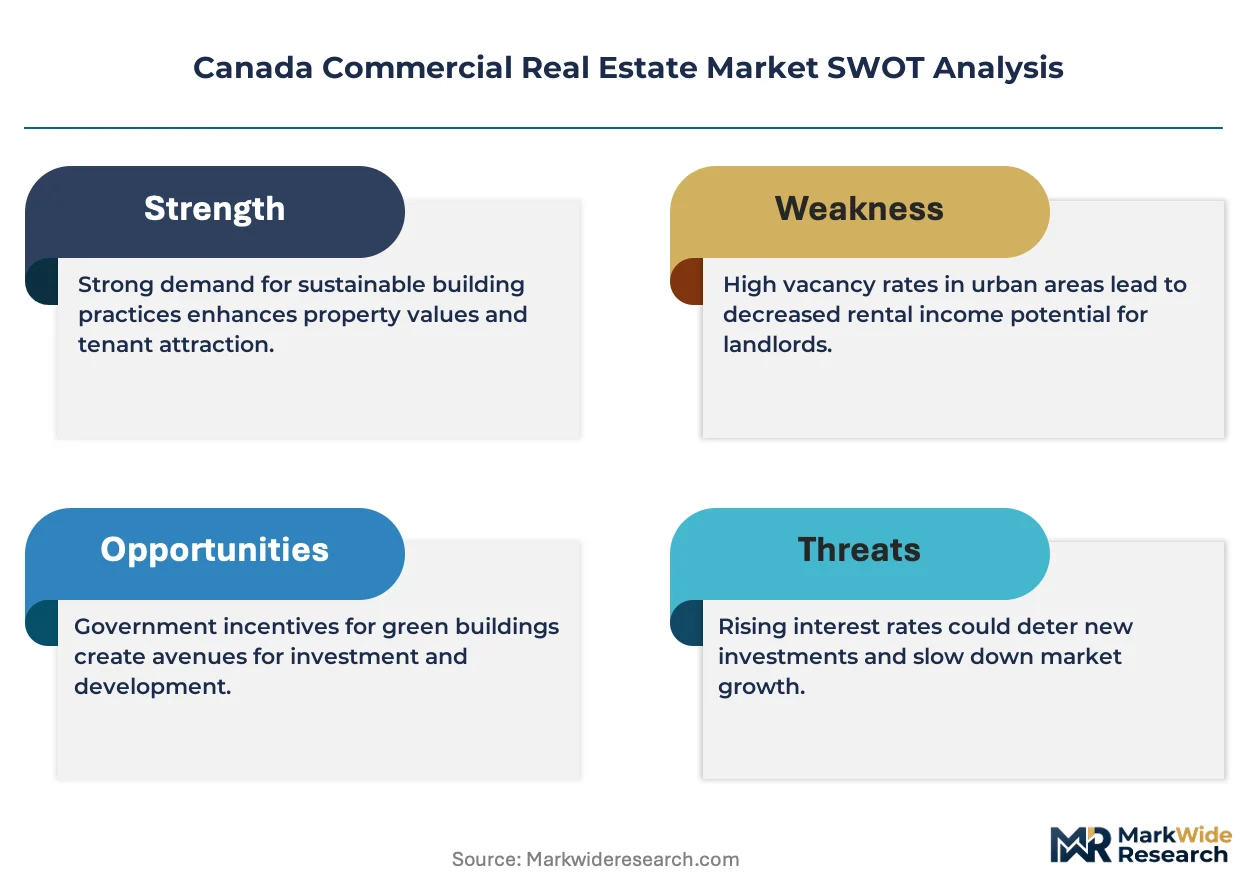
Health Canada and provincial regulators including Ontario's TSSA enforce building safety standards that mandate elevator modernization and fire system upgrades, directly triggering capital expenditure cycles across aging office stock. CMHC underwriting guidelines and OSFI B-20 mortgage rules constrain debt availability, filtering speculative development and favoring equity-heavy capital structures. Stakeholders must monitor interest rate trajectory sensitivity embedded in refinancing walls and assess whether industrial rent growth can sustain current yield compression.
Market Dynamics
OSFI's B-20 mortgage underwriting guidelines and CMHC debt service coverage requirements are compressing leverage ratios across development pipelines, forcing institutional sponsors toward equity-heavy capitalization structures and joint-venture formations.
Growth Catalysts
- Industrial Absorption Surge:E-commerce fulfillment networks are consuming Greater Toronto Area warehouse stock faster than new supply delivers, tightening vacancy to sub-3% levels across the 401 corridor.
- Green Building Retrofit Mandates:Vancouver's Zero Emissions Building Plan and Toronto's Net Zero Existing Buildings Strategy are mandating deep energy retrofits, unlocking capital deployment into building electrification and envelope upgrades.
- Life-Science Facility Demand:Health Canada and provincial health authorities are expanding biomanufacturing capacity targets, pulling specialized laboratory and cold-chain logistics space into development pipelines.
Market Restraints
- Construction Input Cost Volatility:Steel and concrete price swings from disrupted global supply chains are eroding pro forma yields on speculative industrial starts in Calgary and Edmonton submarkets.
- Secondary Office Bid-Ask Spreads:Institutional sellers and private equity buyers remain price-disconnected on 1980s-vintage office towers in Ottawa and Winnipeg, freezing price discovery.
- Interest Rate Sensitivity:Five-year Government of Canada bond yield movements directly compress cap rate expansion assumptions embedded in 2025-2027 refinancing walls.
Strategic Opportunities
- Quebec Life-Science Corridor:Montreal's Quartier de l'Innovation and Laval biotech cluster present underdeveloped laboratory inventory relative to announced provincial biomanufacturing incentives.
- Property-as-a-Service Convergence:Integration of IoT building management platforms with flexible lease structures allows landlords to capture recurring software revenue alongside base rent.
- Last-Mile Infill Positioning:Vancouver's constrained industrial land base and Toronto's Greenbelt protection are elevating redevelopment premiums on obsolete retail pads into micro-fulfillment facilities.
Industry Challenges
- Skilled Trade Shortage:Elevator modernization and fire system upgrade mandates from Ontario's TSSA and municipal property standards divisions are outpacing certified technician availability.
- Legacy System Integration:1970s-era building automation infrastructure in Calgary's downtown office core requires costly middleware development to interface with modern energy management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Commercial Real Estate Market |
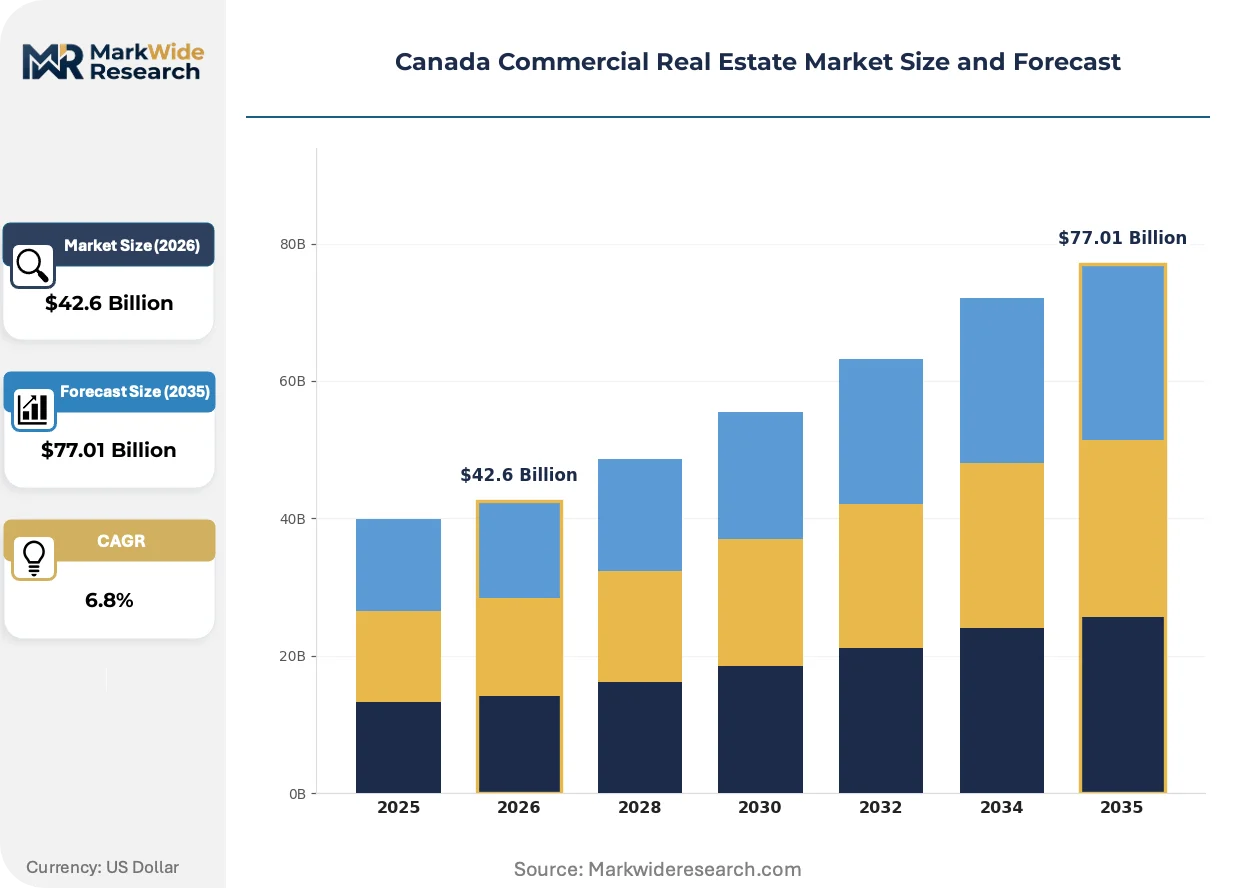
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $77.01 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Hospitality Investment Strategy: Core, Value-Add, Opportunistic, Development End User: Corporate, Government, Institutional, Non-Profit Financing Type: Equity, Debt, Joint Venture, Mezzanine |
| Companies Covered | Manulife Investment Management, Dream Unlimited Corp., Brookfield Properties, BentallGreenOak, H&R Real Estate Investment Trust, Cadillac Fairview, RioCan Real Estate Investment Trust, Panattoni Development, Ivanhoé Cambridge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Commercial Real Estate Market Emerging Trajectories
Digitization of asset management and tenant experience platforms is compressing operating expense ratios while enabling new revenue streams from data monetization and dynamic space allocation.
Smart building sensor networks are decentralizing energy load management away from centralized HVAC control toward zone-level optimization. Pension fund landlords including Oxford Properties and QuadReal are deploying these systems across Toronto and Vancouver office portfolios. This technology is decentralizing landlord-tenant power dynamics by giving occupants real-time visibility into their consumption and carbon footprint.
Canada's National Building Code 2020 updates and provincial adoption schedules are mandating step-code energy performance tiers that escalate through 2030. British Columbia and Ontario have accelerated their timelines ahead of federal minimums. Developers in Vancouver's Broadway Corridor and Toronto's Port Lands are pre-wiring projects to exceed Tier 4 standards to avoid stranded asset risk.
Tenant retention strategies now center on experience-layer services rather than base rent concessions. Landlords are unbundling amenities into subscription tiers covering fitness, conferencing, and logistics support. This shift is most pronounced in Toronto's Financial District and Montreal's downtown core where flight-to-quality competition is intense.
Canada Commercial Real Estate Market Segmentation
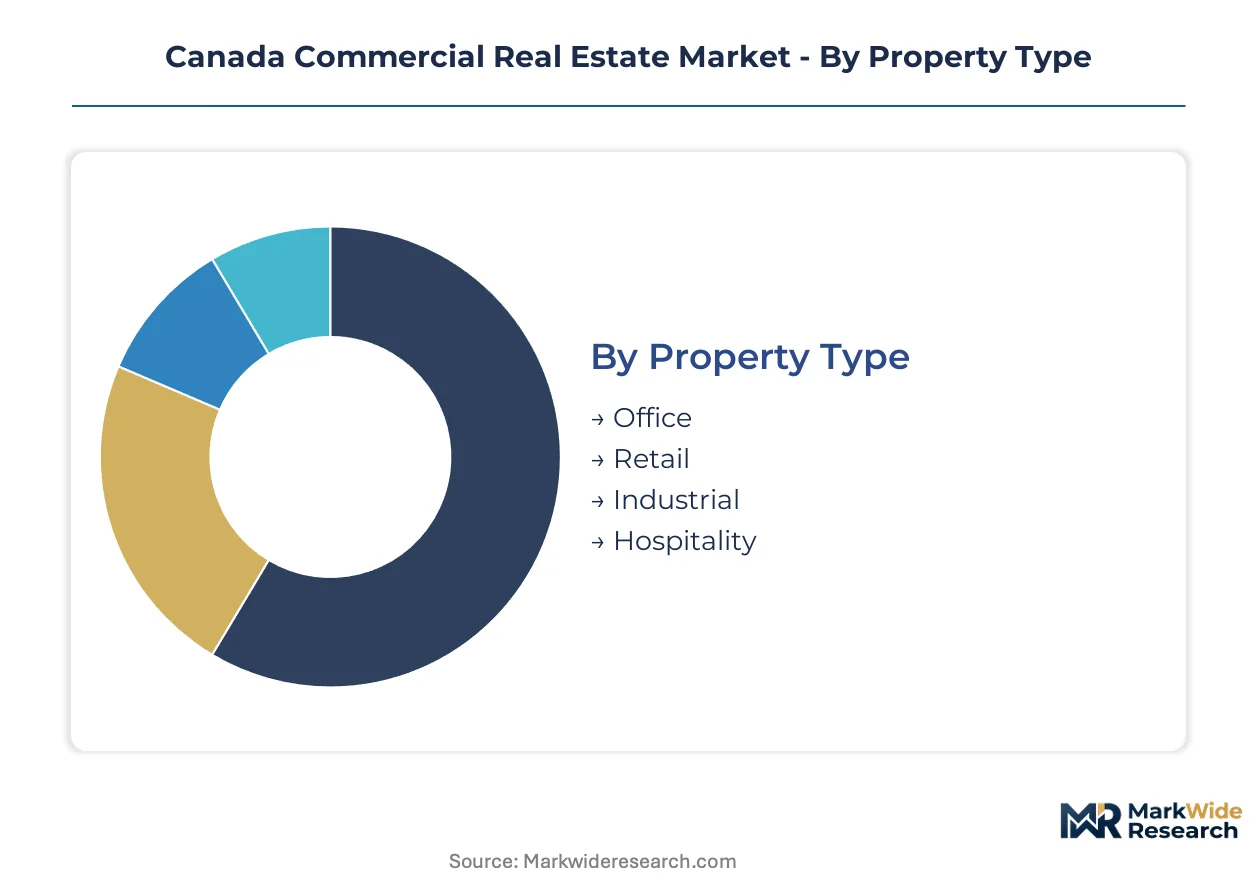
Segmentation in Canadian commercial real estate reveals how capital allocation, risk tolerance, and tenant demand intersect across property types and financing structures. Understanding these divisions allows investors to match deployment strategies with regulatory constraints and regional supply-demand imbalances.
Property Type:
Standalone assets dominate institutional portfolios, while embedded mixed-use configurations require integrated management platforms and layered tenant structures.
- Industrial:Warehouses and logistics facilities with clear-height specifications above 32 feet and loading dock density optimized for e-commerce fulfillment. Demand concentrates in the Greater Toronto Area's 401 corridor where vacancy rates have compressed below 3% and land scarcity is accelerating rent growth.
- Office:Class A towers with floor plates exceeding 25,000 square feet and centralized HVAC systems, alongside secondary vintage stock requiring elevator modernization under Ontario's TSSA mandates. Flight-to-quality dynamics in Toronto's Financial District and Montreal's downtown core are bifurcating performance between premium and commodity assets.
- Retail:Enclosed shopping centers and strip configurations with varying anchor tenant dependency, increasingly repositioned toward last-mile fulfillment or mixed-use redevelopment in Vancouver's constrained land markets.
- Hospitality:Full-service hotels and limited-service properties with revenue per available room sensitivity to business travel recovery and seasonal tourism flows.
Volume placements concentrate in Industrial; the faster expansion belongs to Hospitality as business travel normalizes and conference demand rebounds.
Investment Strategy:
Risk-return profiles stratify across capital preservation mandates and value creation horizons, with fee structures and promote waterfalls reflecting deployment complexity.
- Core:Stabilized assets in primary markets with long-term leases to investment-grade tenants and minimal capital expenditure requirements. Pension funds and life insurers dominate this category, targeting Toronto and Vancouver office towers with defensive cash flow characteristics.
- Value-Add:Properties requiring active management interventions—lease-up, renovation, or repositioning—to unlock yield expansion. Secondary office markets in Ottawa and Winnipeg exhibit widened bid-ask spreads as institutional sellers and private equity buyers remain price-disconnected.
- Opportunistic:Distressed or development-stage assets with higher leverage tolerance and shorter hold periods, capturing structural dislocation in Calgary's downtown office core.
- Development:Ground-up construction or major redevelopment with entitlement risk and construction input cost volatility from disrupted steel and concrete supply chains.
Capital commitments concentrate in Core; the steepest expansion trajectory belongs to Value-Add as yield compression in stabilized assets pushes investors toward active management strategies.
End User:
Tenant credit quality and lease structure durability vary significantly across user categories, influencing lender underwriting and investor due diligence intensity.
- Corporate:Private sector occupiers with lease terms tied to employment density and hybrid work policies, driving space efficiency metrics and amenity demands.
- Government:Federal and provincial tenants with sovereign credit backing and long-dated lease commitments, concentrated in Ottawa-Gatineau and provincial capital markets.
- Institutional:Universities, hospitals, and crown corporations with mission-driven real estate requirements and specialized facility needs.
- Non-Profit:Charitable and social service organizations with constrained rent capacity and reliance on grant funding cycles.
Lease volume concentrates in Corporate; the fastest share gains belong to Institutional as health authorities expand biomanufacturing capacity targets.
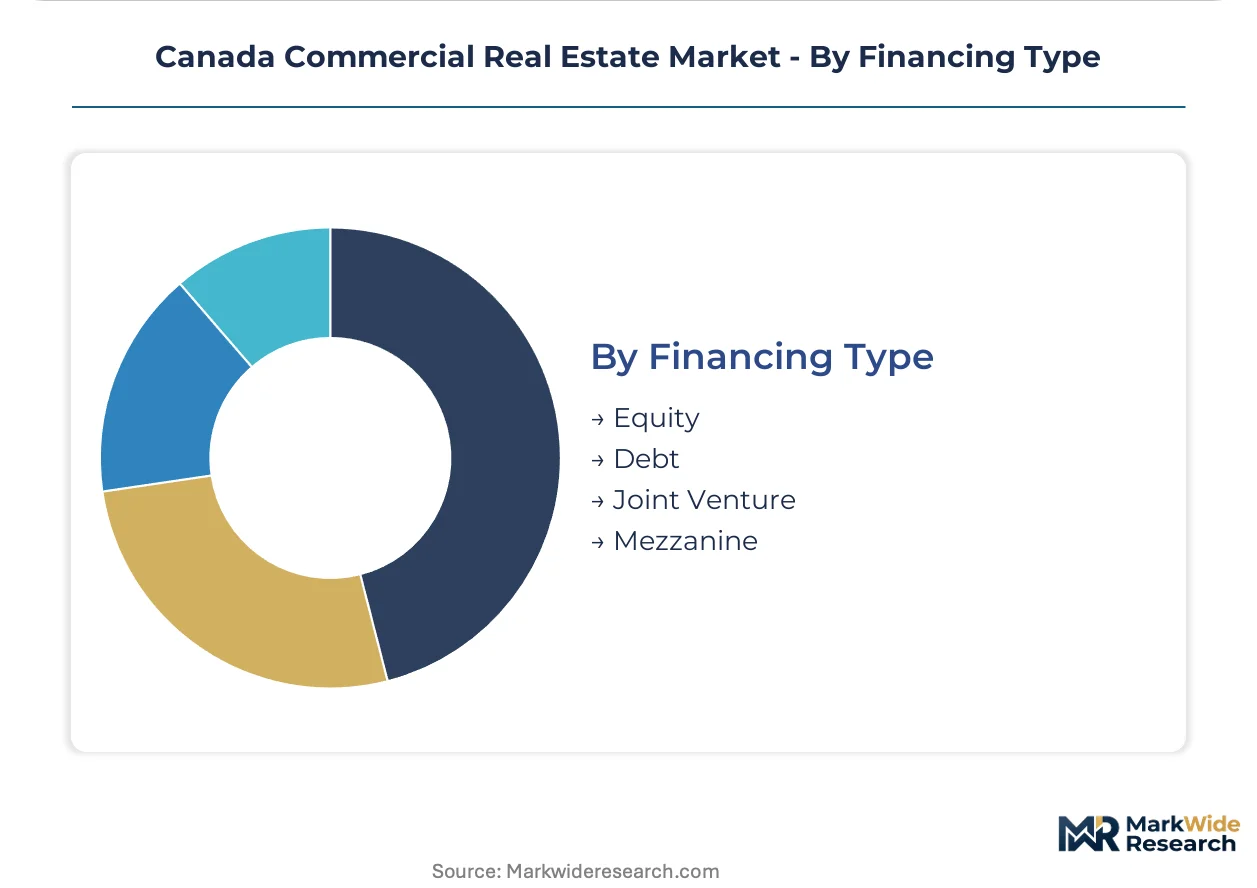
Financing Type:
Capital stack composition reflects regulatory constraints from OSFI's B-20 guidelines and CMHC underwriting standards, filtering speculative development toward equity-heavy structures.
- Equity:Common and preferred equity contributions from pension funds, REITs, and private capital pools, absorbing first-loss risk and capturing residual value.
- Debt:Senior mortgages and construction financing governed by debt service coverage ratios and loan-to-value limits, with availability tightening as Government of Canada bond yields pressure refinancing assumptions.
- Joint Venture:Partnership structures combining capital providers with operating expertise, prevalent in large-scale mixed-use developments where risk sharing aligns sponsor incentives.
- Mezzanine:Subordinated debt with equity participation features, filling gaps between senior loan proceeds and required equity in value-add and opportunistic strategies.
Deployment volume concentrates in Equity; the most rapid structural shift belongs to Joint Venture as leverage constraints force institutional sponsors toward collaborative capitalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's commercial real estate production concentrates in Toronto and Vancouver development corridors, while consumption spreads across provincial capitals and resource-dependent secondary markets. This geographic split creates divergent rent trajectories and capital availability across sub-national regions.
Ontario
E-commerce fulfillment networks and life-science manufacturing expansion drive industrial absorption in the Greater Toronto Area. Health Canada's biomanufacturing capacity targets pull specialized laboratory space into development pipelines around Toronto's Pearson corridor. The 401 industrial corridor reports sub-3% vacancy as warehouse demand outpaces new supply delivery.
Quebec
Montreal's Quartier de l'Innovation anchors institutional investment concentration in laboratory and cold-chain logistics facilities. Provincial biomanufacturing incentives from Quebec's economic development agencies are accelerating specialized inventory development. Laval's biotech cluster presents underdeveloped laboratory inventory relative to announced capacity targets.
British Columbia
Vancouver's constrained industrial land base elevates redevelopment premiums on obsolete retail pads into micro-fulfillment facilities. The city's Zero Emissions Building Plan mandates deep energy retrofits that unlock capital deployment into building electrification. Broadway Corridor developers pre-wire projects to exceed National Building Code Tier 4 standards.
Alberta
Calgary's downtown office core exhibits flight-to-quality dynamics that bifurcate performance between premium and commodity assets. Construction input cost volatility from disrupted steel and concrete supply chains erodes pro forma yields on speculative industrial starts. Edmonton submarkets face similar pressure from global supply chain disruptions affecting development economics.
Atlantic Canada
Halifax and Moncton logistics facilities capture overflow demand from constrained Ontario and Quebec industrial markets. Federal government tenant concentration in Ottawa-Gatineau provides sovereign credit-backed lease durability distinct from private sector cyclicality. Secondary office markets in the region exhibit widened bid-ask spreads as institutional sellers and private equity buyers remain price-disconnected.
Canada Commercial Real Estate Market Vendor Landscape
Top-tier vendors anchor institutional capital deployment, while mid-tier developers and specialized REITs occupy fragmented submarket niches. Pension fund landlords and global asset managers concentrate ownership of stabilized core assets in Toronto and Vancouver. Three archetypes dominate: integrated platform operators with cross-asset management capabilities, regional specialists with concentrated geographic expertise, and income-focused REITs with defensive yield mandates. Competitive intensity centers on portfolio diversification into life-science and logistics verticals, alongside joint-venture formations that distribute entitlement risk.
Among Toronto-based platform operators, Brookfield Properties exemplifies global scale deployment across core office and alternative asset classes. Dream Unlimited Corp. occupies a position within the mixed-use development specialist tier, with Western Canada concentration distinguishing its project pipeline. Ivanhoé Cambridge anchors Quebec's institutional investment landscape through Montreal holdings that concentrate laboratory and downtown office exposure. These three entities represent divergent capitalization strategies: global platform leverage, regional development expertise, and provincial pension fund sponsorship.
| Leading Market Players |
|---|
| Manulife Investment Management |
| Dream Unlimited Corp. |
| Brookfield Properties |
| BentallGreenOak |
| H&R Real Estate Investment Trust |
| Cadillac Fairview |
| RioCan Real Estate Investment Trust |
| Panattoni Development |
| Ivanhoé Cambridge |
| Others |
Supply Flow & Price Mechanics
Pension fund landlords and institutional asset managers concentrate procurement of construction materials and building systems, anchoring contract-based long-term offtake pricing for steel, concrete, and MEP components across Canadian development pipelines.
Pricing Analysis
Cost-down pressure on speculative industrial starts accelerates because global supply chain disruptions in steel and concrete feed directly into pro forma yield erosion. Three-tier pricing structure across premium, standard, and economy levels separates Class A downtown Toronto office towers from secondary vintage stock in Ottawa and Winnipeg from commodity suburban assets. Price differentiation traces to certification level under Canada's National Building Code energy tiers and geographic delivery cost from Asian steel mills to Vancouver versus domestic Eastern Canadian suppliers. Value-add investors exhibit highest price sensitivity as widening bid-ask spreads freeze price discovery, while core pension fund buyers absorb premium pricing for stabilized Toronto and Vancouver assets with minimal negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Chinese steel producers and South Korean elevator component manufacturers feeding Canadian construction markets. Raw material dependencies center on structural steel, Portland cement, and copper wiring for building electrification retrofits. Supply chain risk traces to tariff exposure on imported construction inputs as trade policy shifts disrupt landed cost assumptions. Distribution runs through regional building material distributors with just-in-time delivery contracts to Toronto, Vancouver, and Montreal construction sites, supplemented by direct procurement relationships for large-scale mixed-use developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property-as-a-service platforms and IoT building management systems are displacing legacy centralized HVAC controls and static lease structures across Canadian commercial portfolios.
For Market Incumbents: Deploy backward integration into proprietary building technology stacks to capture recurring software revenue alongside base rent. Brookfield Properties and Ivanhoé Cambridge should accelerate IoT sensor network deployment across Toronto and Montreal office portfolios before tenant experience platforms commoditize. Defensive consolidation into life-science and logistics verticals protects against office obsolescence risk from hybrid work permanence. For New Entrants and Emerging Players: Mid-market corporate occupiers in Calgary and Edmonton secondary office submarkets present underserved demand for flexible lease structures with embedded amenity subscriptions. Niche positioning in Quebec life-science laboratory development exploits underbuilt inventory relative to provincial biomanufacturing targets. Go-to-market execution should emphasize joint-venture formations with pension fund capital partners to distribute entitlement risk on ground-up projects. For Investors and Strategic Acquirers: The window for entry favors value-add specialists with active management capabilities in secondary office repositioning. Long-term viability hinges on industrial rent growth sustainability across the Greater Toronto Area's 401 corridor. Monitor Government of Canada five-year bond yield movements as the inflection signal for refinancing wall stress and cap rate expansion assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Building Electrification Retrofit Program | Toronto's Net Zero Existing Buildings Strategy mandates deep energy upgrades, unlocking capital deployment into envelope and HVAC electrification. |
| Life-Science Facility Development | Health Canada biomanufacturing targets pull specialized laboratory and cold-chain logistics space into Montreal and Toronto development pipelines. |
| Property-as-a-Service Platform Integration | IoT building management systems enable landlords to capture recurring software revenue alongside traditional base rent streams. |
| Last-Mile Infill Repositioning | Vancouver's constrained industrial land base elevates redevelopment premiums on obsolete retail pads into micro-fulfillment facilities. |
| Joint Venture Capital Formation | OSFI B-20 leverage constraints force institutional sponsors toward collaborative equity-heavy structures for large-scale mixed-use developments. |
Methodological Framework
Document review covered CMHC market outlook reports, OSFI regulatory filings, municipal green building bylaws from Vancouver, Toronto, and Montreal, and REIT financial disclosures, complemented by interviews with pension fund real estate directors, commercial mortgage underwriters, development project managers, and building systems procurement leads. Secondary validation drew from National Building Code adoption schedules, provincial energy step-code timelines, and industrial vacancy data from brokerage market reports. Bottom-up project pipeline analysis triangulated against top-down institutional capital flow estimates.
Market size and growth trajectory outputs reflect econometric modeling across property type, investment strategy, and regional segmentation dimensions, with rent growth assumptions and absorption forecasts feeding into valuation projections across the analysis window. CAGRs derive from historical transaction velocity, supply pipeline tracking, and demographic-driven demand elasticity for logistics and laboratory space. Forecast inputs incorporate interest rate sensitivity embedded in refinancing walls and construction input cost volatility from disrupted global supply chains.
Revisions become necessary when Government of Canada bond yield movements exceed modeled sensitivity bands, when municipal green building mandates accelerate ahead of federal timelines, or when biomanufacturing capacity targets shift provincial incentive structures. Forecasts reflect documented assumptions about e-commerce fulfillment demand persistence and hybrid work stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Canada Co-Working Office Spaces Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
North America Coworking Spaces Market
Commercial Real Estate
Vietnam Commercial Real Estate Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Oman Commercial Real Estate Market
Commercial Real Estate
Brazil Commercial Real Estate Market
Commercial Real Estate
Malaysia Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Europe Commercial Real Estate Market
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Global Shared Office Spaces Market