
 Africa Oilfield Services Market | 2026-2036
Africa Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Oilfield Services Market Outlook
Local content legislation across Nigeria, Angola, and Ghana is repositioning the cost-of-entry calculus for international oilfield service providers. Schlumberger Limited leverages its integrated project management capabilities to sustain long-term drilling contracts in Nigerian deepwater blocks. Baker Hughes Company anchors its competitive stance through specialized turbomachinery and artificial lift systems tailored to mature West African fields. Halliburton Company differentiates via directional drilling and logging-while-drilling technologies deployed across multiple African basins.
Africa oilfield services encompass the technical support, equipment provision, and engineering execution required to drill, complete, maintain, and enhance hydrocarbon wells across onshore and offshore environments, typically involving pressure ratings exceeding 10,000 psi and high-temperature reservoir conditions. These services enable exploration companies and production operators to extract crude oil and natural gas from complex geological formations spanning continental shelves and deepwater provinces. Drilling services command the largest current revenue pool given sustained capital allocation to deepwater projects in Nigeria and Angola, while enhanced oil recovery represents the fastest-growing technology segment as mature fields require pressure maintenance and tertiary extraction methods. Well intervention activity is accelerating fastest among application categories as operators prioritize production optimization over greenfield exploration in capital-constrained environments.
Nigeria's Department of Petroleum Resources enforces local content mandates that reshape procurement patterns and joint venture structures for international service contractors. Angola's petroleum regulator imposes strict technical standards and environmental compliance protocols for offshore drilling and well completion operations. Stakeholders must monitor how evolving fiscal terms and local content enforcement across African petroleum jurisdictions determine which service technologies and partnership models secure contract renewals in the decade ahead.
Market Dynamics
Deepwater exploration economics and local content enforcement across West African petroleum jurisdictions are restructuring how international oilfield service providers configure joint ventures, technology transfer agreements, and local partnership hierarchies to maintain contract access.
Growth Catalysts
- Nigerian Local Content Act:Mandates minimum thresholds for indigenous workforce participation and domestic equipment sourcing, compelling foreign contractors to establish fabrication yards and training centers in-country.
- Enhanced Oil Recovery:Mature fields in Angola and Nigeria require pressure maintenance and tertiary extraction methods, generating sustained demand for artificial lift systems and chemical injection services.
- Senegal-Mauritania Basin Development:Independent operators advancing deepwater projects in these emerging provinces are procuring integrated drilling packages and subsea installation services from established supply chains.
Market Restraints
- Specialized Equipment Lead Times:High-specification blowout preventers and managed pressure drilling systems face 12-18 month manufacturing backlogs concentrated among North American and European suppliers.
- Deepwater Rig Availability:Ultra-deepwater drillship supply remains tight globally, constraining West African operators' ability to accelerate exploration timelines even with capital allocated.
- Fiscal Regime Uncertainty:Pending petroleum industry bill revisions in Nigeria create investment hesitation among service providers considering long-term facility commitments.
Strategic Opportunities
- Gas Monetization Infrastructure:Associated gas utilization requirements under Nigerian environmental regulations are opening demand for gas processing modules and flare elimination technologies.
- Digital Twin Integration:Convergence of subsea sensor networks with predictive analytics platforms enables remote monitoring contracts for offshore production facilities.
- Ghanaian Independent Producers:New entrant operators lacking integrated service capabilities present white space for bundled drilling and completion packages with embedded local content compliance.
Industry Challenges
- Deepwater Technical Specialist Shortages:Subsea engineering and high-pressure high-temperature well design expertise remains concentrated among expatriate workforces, complicating local content fulfillment.
- Legacy Contract Migration:Transitioning from traditional day-rate service models to integrated performance-based agreements requires restructuring risk allocation and margin recognition across multi-year frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Oilfield Services Market |
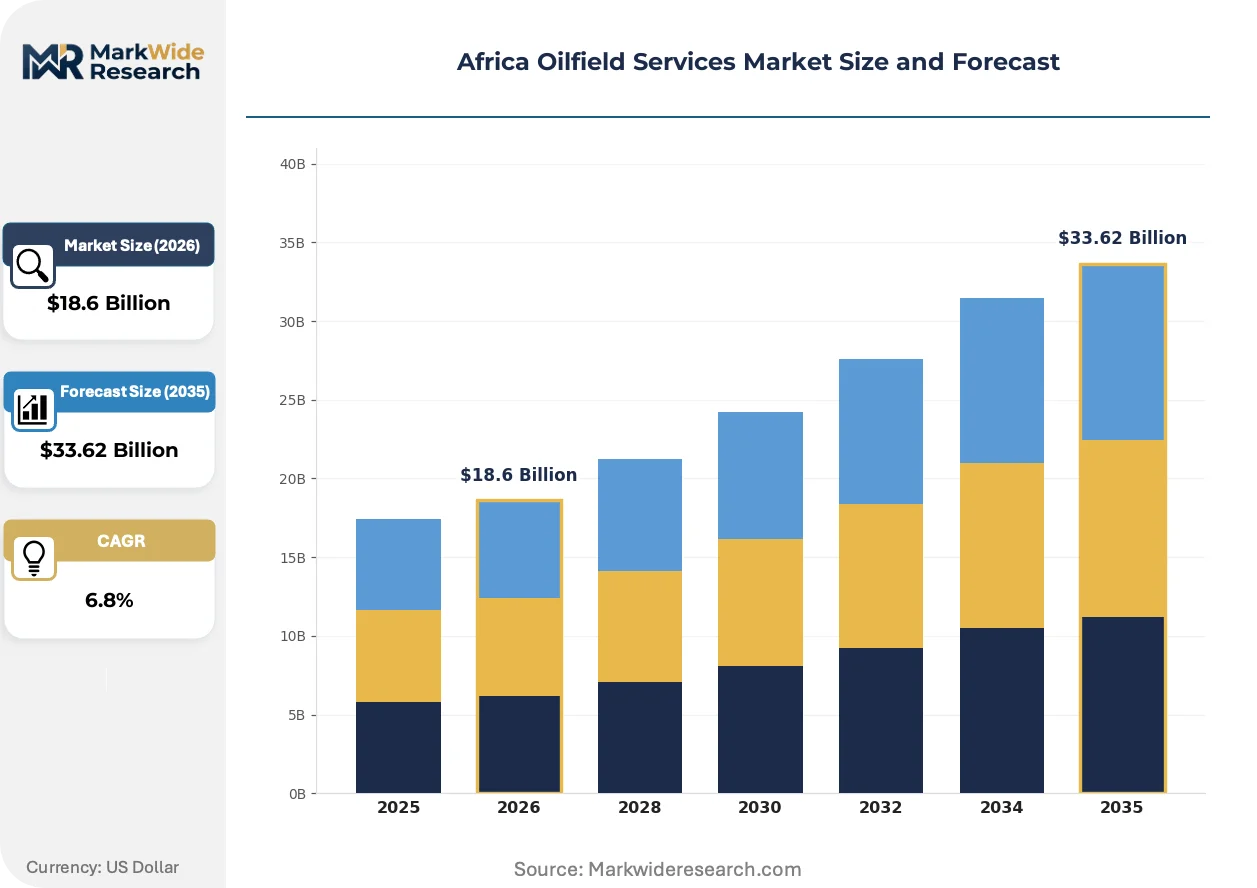
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Production Services, Well Completion, Well Intervention Technology: Seismic, Directional Drilling, Hydraulic Fracturing, Enhanced Oil Recovery End User: Exploration Companies, Production Companies, Oilfield Operators, Independent Producers Application: Onshore Operations, Offshore Operations, Oil Exploration, Gas Exploration |
| Companies Covered | Schlumberger Limited, Weatherford International PLC, Baker Hughes Company, Halliburton Company, TechnipFMC plc, Petrofac Ltd, China Oilfield Services Limited, Transocean Ltd, Nabors Industries, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Oilfield Services Market Strategic Shifts
Automation of rig floor operations and remote monitoring capabilities is compressing crew requirements and redefining competitive differentiation among service tiers. Three developments are restructuring how value is captured and delivered.
Managed pressure drilling systems are automating kick detection and annular pressure control in deepwater environments where narrow drilling windows challenge conventional techniques. Nigerian and Angolan operators deploying these systems on high-pressure wells are reducing non-productive time and enabling access to previously undrillable reservoir sections. The technology is automating real-time decision loops that previously required manual intervention, compressing the skill premium attached to veteran drilling crews.
Angola's petroleum regulator has tightened environmental compliance protocols for offshore drilling waste discharge and marine ecosystem protection. Service contractors must now demonstrate closed-loop mud systems and zero-discharge capabilities to secure exploration licenses. Deepwater drilling segments are absorbing the highest compliance costs, with operators passing through capital expenditure for upgraded solids control equipment and waste processing vessels.
Integrated service contracting is displacing fragmented procurement of discrete drilling, completion, and intervention services among capital-constrained African independents. Bundled performance agreements with single-point accountability are replacing multi-vendor project management structures. Ghanaian and Senegalese operators with limited technical staffing are driving this consolidation, preferring fixed-fee arrangements that transfer subsurface risk to service providers with established basin experience.
Africa Oilfield Services Market Segmentation
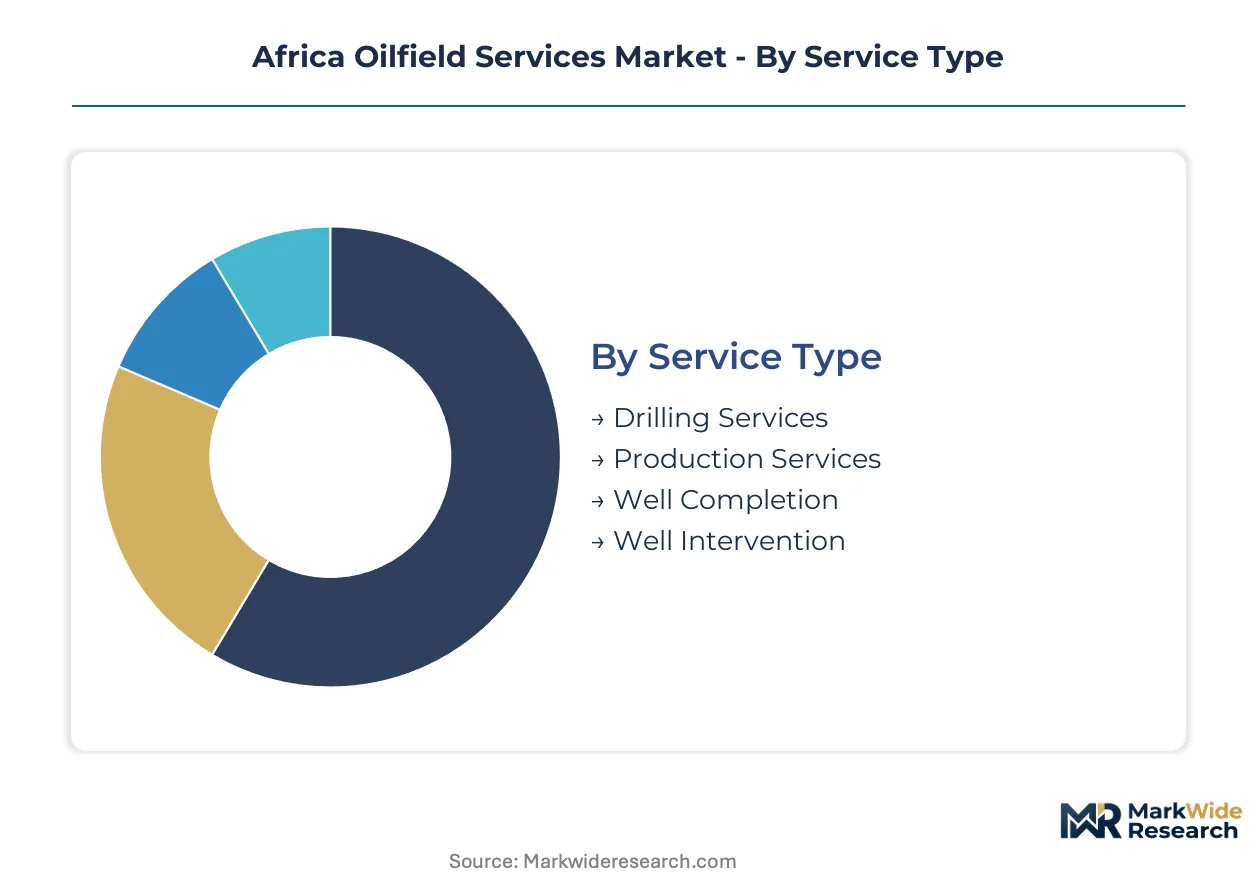
Oilfield services in Africa fragment across technical capabilities, reservoir conditions, and operator sophistication. Understanding how procurement patterns diverge across these dimensions reveals where contract value concentrates and which service tiers face margin compression.
Service Type:
Drilling commands volume share while intervention captures premium pricing expansion.
- Drilling Services:Directional drilling, managed pressure systems, and rig mobilization for high-pressure high-temperature wells. Nigerian deepwater blocks and Angolan pre-salt developments absorb the majority of contracted rig days, with local content mandates forcing joint venture structures on international contractors.
- Production Services:Artificial lift installation, surface facility maintenance, and production chemistry management. Mature fields across the Niger Delta and Cabinda province sustain recurring revenue streams, though day-rate pressure intensifies as operators prioritize opex reduction over technical upgrades.
- Well Completion:Casing design, cementing operations, and intelligent completion deployment for multizone reservoirs.
- Well Intervention:Workover rigs, coiled tubing, and wireline services for production optimization without new drilling.
Today's leader: Drilling Services. Tomorrow's challenger: Well Intervention.
Technology:
Seismic and directional drilling anchor current procurement budgets while enhanced recovery methods reshape long-term technology roadmaps.
- Seismic:3D and 4D seismic acquisition, processing, and interpretation for subsurface imaging. West African licensing rounds in Senegal, Mauritania, and Namibia drive survey contracting, with independent operators lacking in-house geoscience capabilities outsourcing entire exploration workflows.
- Enhanced Oil Recovery:Chemical flooding, gas injection, and thermal methods for tertiary extraction. Angola's mature offshore fields and Nigeria's onshore stripper wells generate demand for pressure maintenance technologies as natural reservoir drive depletes.
- Directional Drilling:Geosteering, rotary steerable systems, and logging-while-drilling for complex wellbore trajectories.
- Hydraulic Fracturing:Stimulation design, proppant placement, and fracture diagnostics for tight formations.
Seismic retains the largest revenue pool. Enhanced Oil Recovery is climbing the fastest as basin maturity advances.
End User:
National oil companies and majors dominate contract value while independents fragment procurement across bundled service tiers.
- Production Companies:Field development planning, facility engineering, and reservoir management for producing assets. Nigerian joint venture partners and Angolan concession holders sustain long-term service agreements, with technical standards enforced by national petroleum regulators shaping contractor qualification requirements.
- Independent Producers:New entrants in Ghana, Senegal, and Mauritania lacking integrated technical capabilities. These operators favor single-point accountability and fixed-fee structures that transfer subsurface risk to established service providers with proven basin experience.
- Exploration Companies:Wildcat drilling, appraisal programs, and frontier basin entry for unproven provinces.
- Oilfield Operators:Lease operators and production management contractors for third-party asset stewardship.
Production Companies command the deepest contract backlogs. Independent Producers are expanding their share of negotiated service days.
Application:
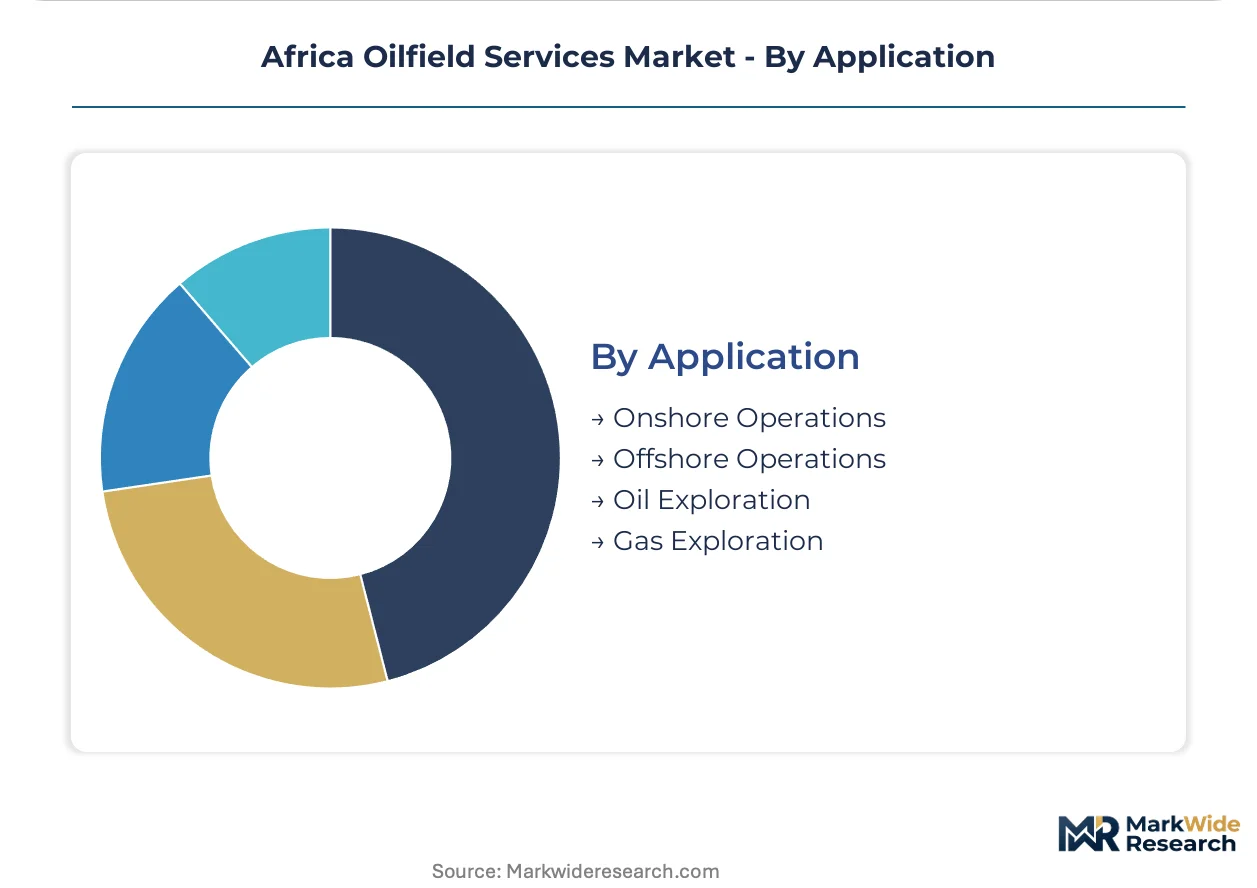
Offshore operations absorb capital-intensive service tiers while onshore activity accelerates in response to security and infrastructure constraints.
- Offshore Operations:Subsea installation, platform maintenance, and deepwater drilling support. Nigerian and Angolan ultra-deepwater provinces require high-specification equipment and specialist crews, with environmental compliance protocols for drilling waste discharge adding cost layers to project economics.
- Onshore Operations:Land rig mobilization, workover programs, and pipeline integrity management. Niger Delta security challenges and infrastructure degradation compress activity levels, though smaller independents pursue marginal field developments with modular equipment packages.
- Oil Exploration:Wildcat drilling, appraisal well testing, and reserve certification for liquid hydrocarbons.
- Gas Exploration:Deep gas targeting, associated gas appraisal, and gas-condensate evaluation for monetization projects.
Offshore Operations retain the highest contract values. Onshore Operations are gaining share as marginal field frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized subsea engineers and deepwater drilling crews concentrate along West African coastal corridors, anchoring service demand in Nigeria, Angola, and emerging basins offshore Senegal and Ghana.
Nigeria
Deepwater exploration in the Bonga and Egina fields sustains demand for high-pressure drilling systems and intelligent completion technologies. The Nigerian Content Development and Monitoring Board enforces indigenous workforce quotas and domestic fabrication requirements for all offshore contracts. Port Harcourt and Lagos host the primary service yards where international contractors partner with local firms to meet joint venture mandates.
Angola
Mature pre-salt fields require artificial lift upgrades and enhanced oil recovery packages to maintain plateau production rates. The national petroleum agency imposes strict environmental compliance protocols for drilling waste discharge and marine ecosystem protection. Luanda serves as the logistics hub for ultra-deepwater operations in Block 17 and Block 32, with specialized crews rotating through Soyo and Cabinda supply bases.
Ghana
Independent producers developing the Jubilee and TEN fields procure bundled drilling and completion services lacking in-house technical capabilities. The Petroleum Commission regulates local content thresholds for offshore service contracts and operator procurement decisions. Takoradi's emerging fabrication cluster attracts joint venture investments as operators establish in-country maintenance capabilities.
Senegal
Frontier basin development in the Sangomar and GTA projects drives demand for integrated project management and subsea installation services. The national oil company partners with international operators to transfer technical capabilities through structured local content frameworks. Dakar functions as the coordination center for Mauritania-Senegal cross-border developments, with service vessels staging from the Port of Dakar.
Mauritania
First-phase production from the Greater Tortue Ahmeyim gas project creates demand for offshore construction and commissioning services. The hydrocarbons regulator oversees environmental impact assessments and technical standards for deepwater infrastructure deployment. Nouakchott's limited industrial base forces operators to rely on Senegalese and international supply chains for specialized equipment and personnel.
Africa Oilfield Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale-driven integrated project managers capture deepwater megaprojects while regional boutiques serve marginal field independents. The vendor base organizes around three archetypes: full-service integrated providers, equipment-focused technology licensors, and local-content-compliant joint ventures. Consolidation pressure intensifies as operators consolidate procurement under single-point accountability frameworks, while partnership mandates force foreign contractors into equity-sharing arrangements with indigenous firms.
Among the integrated service tier, Schlumberger Limited and Baker Hughes Company exemplify archetypes of technology-anchored project managers with established West African operational histories. Halliburton Company occupies a position within the directional drilling and logging-while-drilling specialization tier, representing the focused technical capability model that competes through basin-specific expertise rather than bundled service breadth.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Weatherford International PLC |
| Baker Hughes Company |
| Halliburton Company |
| TechnipFMC plc |
| Petrofac Ltd |
| China Oilfield Services Limited |
| Transocean Ltd |
| Nabors Industries |
| Others |
Value Chain & Pricing Dynamics
Subsea engineering specialists concentrated in Luanda and Port Harcourt command wage premiums that compress margins for standard-tier service providers while widening spreads between integrated project managers and commodity rig operators. Labor-cost differentials between expatriate technical crews and indigenous workforce development programs feed directly into three-tier pricing structures that separate premium HPHT-capable contractors from standard offshore service tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated project management contracts from discrete day-rate procurement. Premium-mid-economy pricing differentiation rests on certification grade for high-pressure well capabilities and volume scale of multi-year framework agreements. Pricing pressure stems from capital-constrained independents consolidating procurement under single-point accountability. National oil companies exhibit lowest price sensitivity given joint venture cost recovery mechanisms, while Ghanaian and Senegalese independents drive hardest bargain for fixed-fee structures.
Supply Chain Analysis
Certification and qualification gating for blowout preventers and managed pressure drilling systems concentrates manufacturing capacity in the United States, Norway, and Singapore. Raw material dependencies include high-grade steel forgings, synthetic drilling fluids, and subsea electronics packages. Single-source vulnerability runs through North American suppliers of critical well control equipment. Distribution runs through Luanda, Lagos, and Takoradi as regional logistics hubs serving deepwater provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where mature field intervention and enhanced recovery specifications favor contractors with proven HPHT track records over price-competitive entrants. The shift toward intelligent completions and automated managed pressure systems elevates technical certification thresholds that reward incumbent specialization.
For Market Incumbents: Deepen backward integration into fabrication yards and training centers to satisfy Nigerian Content Development and Monitoring Board mandates while insulating margins from joint venture dilution. Prioritize certification investment for ultra-deepwater HPHT capabilities as Angolan environmental compliance protocols tighten. Anchor capacity in Port Harcourt and Luanda to defend against emerging Senegalese competitors. For New Entrants and Emerging Players: Begin with marginal field independents in Ghana and Mauritania lacking integrated technical capabilities and in-house geoscience staffing. Target bundled drilling-completion packages with embedded local content compliance as the most penetrable white space. Pursue fixed-fee performance contracts that transfer subsurface risk to establish basin credibility. For Investors and Strategic Acquirers: National oil companies and majors with stranded deepwater reserves are the most active acquirer in this space, seeking service capabilities to accelerate project timelines. Long-term viability hinges on positioning for the intervention-heavy phase of West African basin maturity. Watch rig availability constraints as the inflection signal indicating pricing power restoration for high-specification contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Joint Venture Formation | Nigerian Content Development and Monitoring Board mandates force equity-sharing with indigenous fabrication and training partners. |
| HPHT Certification Investment | Angolan environmental compliance protocols require closed-loop mud systems and zero-discharge capabilities for license access. |
| Digital Twin Platform Deployment | Subsea sensor convergence with predictive analytics enables remote monitoring contracts for offshore production facilities. |
| Artificial Lift Technology Licensing | Mature pre-salt fields in Angola require pressure maintenance and tertiary extraction method expertise. |
| Integrated Project Management Capability Buildout | Ghanaian and Senegalese independents prefer single-point accountability over fragmented multi-vendor procurement. |
Study Parameters
Direct dialogue with drilling contractors, petroleum regulator technical standards officers, national oil company procurement managers, and independent producer engineering directors grounds qualitative assessment in operational reality. Secondary validation draws from Nigerian Department of Petroleum Resources filings, Angolan national petroleum agency environmental compliance records, Ghana Petroleum Commission contract registries, and offshore rig utilization databases. Bottom-up and top-down triangulation reconciles project-level contract values with aggregate basin expenditure patterns.
Bottom-up modeling segments revenue pools across drilling, production, completion, and intervention service types while cross-referencing against technology adoption curves and end-user procurement sophistication. Top-down constraints incorporate hydrocarbon price scenarios, licensing round schedules, and local content enforcement intensity across the projection horizon. CAGRs derive from rig day-rate trajectories, equipment utilization assumptions, and basin maturity phase transitions.
Caveats apply where Nigerian petroleum industry bill revisions, Angolan fiscal term adjustments, or Senegalese regulatory framework evolution could materially shift the outlook for contractor qualification requirements and contract renewal probability. Forecasts reflect assumptions regarding deepwater exploration economics and local content enforcement consistency. A model refresh is warranted upon material change in ultra-deepwater rig supply availability or local content penalty structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
North America Shale Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Well Completion Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Frac Stack Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Copper Mining Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
APAC Oil and Gas Automation Market