
 Oil and Gas Midstream Market | 2026-2036
Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Midstream Market Outlook
Modular terminal configurations and unbundled storage contracts are shifting how refineries procure midstream services. Kinder Morgan, Inc. leverages its interstate pipeline network to anchor gas transmission capacity across North American corridors. Energy Transfer LP competes through integrated NGL fractionation and export terminal control. Enbridge Inc. specializes in crude oil mainline systems that sustain heavy throughput between Alberta and US Midwest markets.
Oil and gas midstream encompasses the transportation, storage, processing, and distribution infrastructure that bridges upstream production with downstream refining and consumption, operating through pipelines typically rated at pressures between 200 and 1,440 psi, cryogenic LNG terminals maintaining minus 162 degrees Celsius, and gas processing plants removing contaminants to meet pipeline quality specifications. The transportation segment dominates value capture through long-haul crude and natural gas pipelines that generate stable tariff revenues under regulated or contracted rate structures. Processing is expanding fastest as associated gas from shale oil production requires treatment before pipeline injection, while LNG terminals command premium returns where export demand outpaces liquefaction capacity.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces integrity management rules that mandate inline inspection and pressure testing cycles, while the Federal Energy Regulatory Commission governs interstate rate structures and certificate approvals for new construction. The EPA's New Source Performance Standards and methane emissions guidelines impose leak detection and repair protocols that increase operational compliance costs. Stakeholders must monitor how evolving federal infrastructure permitting timelines and state-level environmental review processes affect project economics and capital deployment sequencing.
Market Dynamics
Permian Basin production growth is straining existing takeaway capacity, forcing operators to commit to long-term pipeline contracts before infrastructure completion. This supply compression is accelerating capital deployment into gas processing and NGL fractionation assets.
Growth Catalysts
- US EPA methane regulations:Leak detection mandates are retrofitting compressor stations with continuous monitoring systems, expanding service contracts for integrity management providers.
- Associated gas from shale oil:Permian operators require gas processing plants to handle rising gas-to-oil ratios, driving buildout of cryogenic fractionation capacity.
- Gulf Coast export corridor:LNG terminal expansions at Corpus Christi and Sabine Pass are pulling NGL feedstock through new pipeline laterals.
Market Restraints
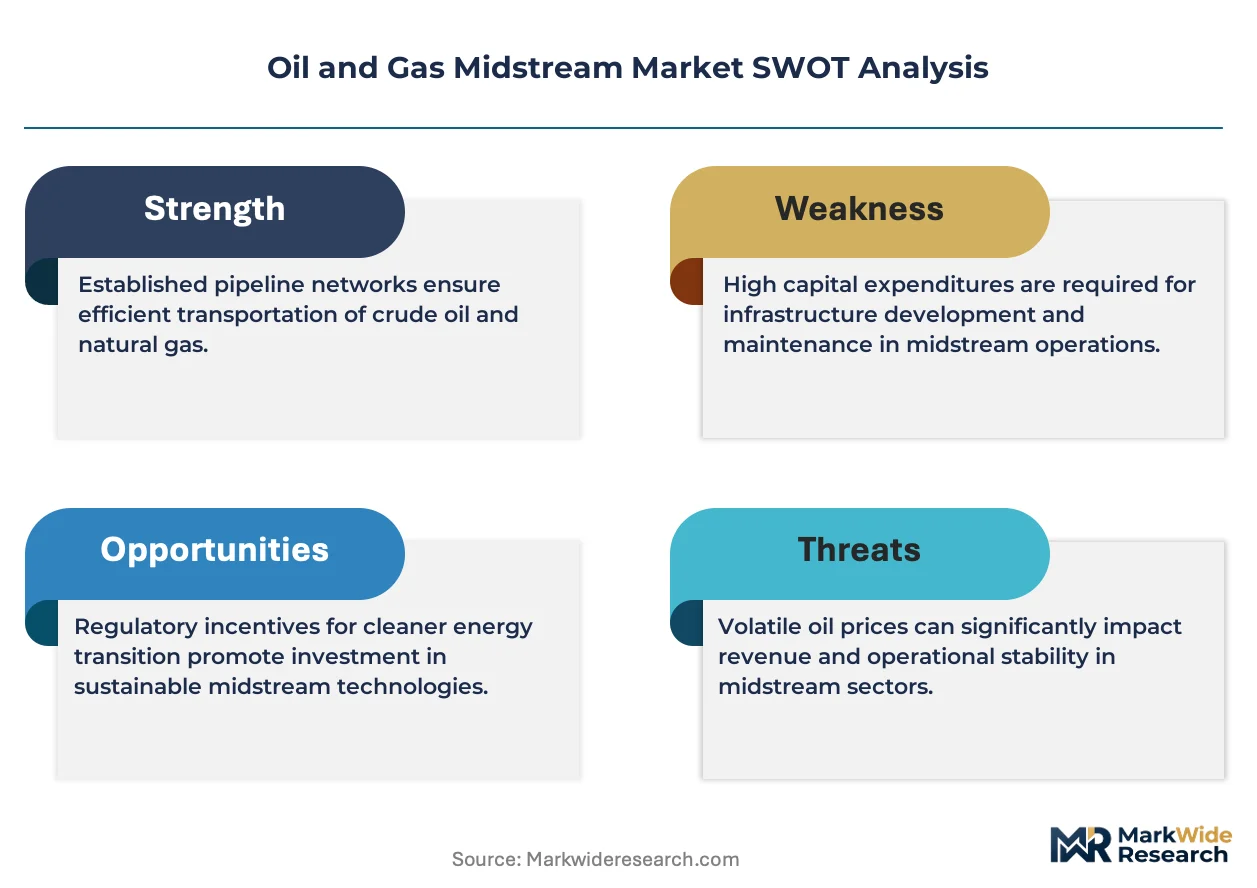
- Steel input cost volatility:Pipeline grade steel prices fluctuate with scrap metal and alloy surcharges, compressing fabrication margins on newbuild projects.
- FERC certificate delays:Interstate pipeline approvals now stretch across multiple federal review cycles, extending project timelines and inflating carrying costs.
- Electrification substitution:Grid-scale battery storage and renewable generation are displacing gas-fired peaking capacity in certain load centers.
Strategic Opportunities
- Carbon capture retrofit:Processing plants can bolt on amine-based CO2 capture to monetize 45Q tax credits and produce low-carbon hydrogen.
- Texas-Louisiana hydrogen hub:Gulf Coast pipeline corridors are being repurposed for hydrogen blending, leveraging existing right-of-way and compressor infrastructure.
- Modular liquefaction:Small-scale LNG trains are reaching stranded gas fields in the Rocky Mountain states, opening markets previously uneconomical for pipeline connection.
Industry Challenges
- Inline inspection technician shortage:Pipeline operators compete for certified ILI analysts capable of interpreting magnetic flux leakage data from smart pig runs.
- Legacy SCADA integration:Decades-old control systems at tank farms require cybersecurity hardening without disrupting real-time operational visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Midstream Market |
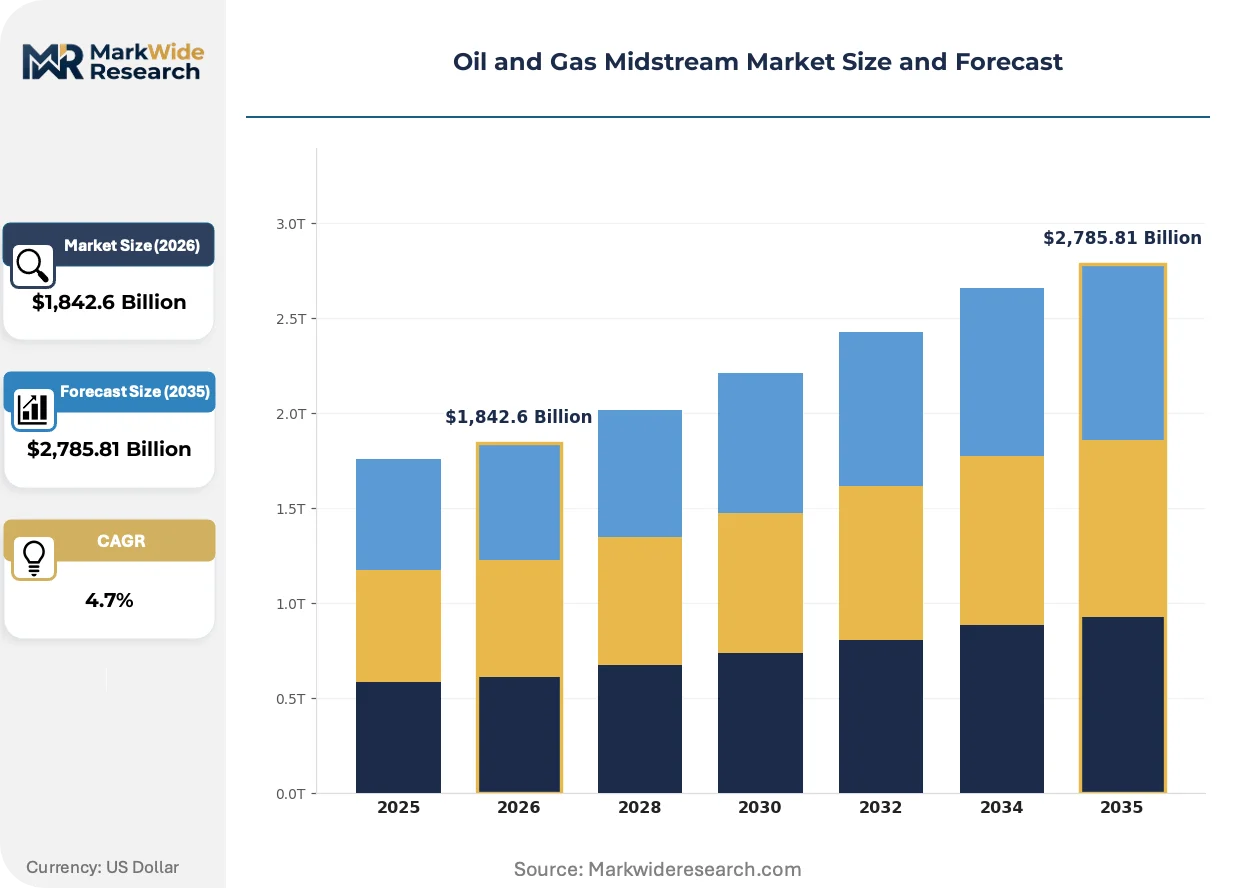
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $2,785.81 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Processing, Distribution Technology: Pipelines, LNG Terminals, Pumps, Compressors End User: Refineries, Utilities, Chemical Manufacturers, Oil Producers Asset Class: Natural Gas, Crude Oil, Liquids, Others |
| Companies Covered | Kinder Morgan, Inc., Energy Transfer LP, Enbridge Inc., ONEOK, Inc., MPLX LP, The Williams Companies, Inc., TC Energy Corporation, Cheniere Energy, Inc., Enterprise Products Partners L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Midstream Market Strategic Shifts
Digital twin deployment is compressing commissioning timelines for complex processing facilities. Operators now simulate thermal hydraulic behavior before physical construction, reducing startup risks and capital at risk.
Advanced composite pipe materials are rewriting pressure containment economics for corrosive gathering systems. Sour gas producers in the Delaware Basin are specifying fiberglass-reinforced thermoplastic lines to eliminate internal corrosion monitoring programs. This material transition is collapsing cathodic protection budgets and extending asset life cycles beyond steel alternatives.
The EPA's updated methane performance standards are forcing compressor station rebuilds across interstate corridors. Operators must replace pneumatic controllers with electric alternatives and install continuous emissions monitoring at major facilities. The gathering and boosting segment faces the steepest retrofit burden, with smaller producers selling assets rather than funding compliance upgrades.
Refinery procurement teams are unbundling storage from transportation in contract negotiations. Merchants now seek standalone tankage commitments at Houston Ship Channel terminals, separate from pipeline nomination rights. This disaggregation is fragmenting service provider revenue streams and pressuring integrated midstream operators to price components separately. The shift is most pronounced among Gulf Coast chemical manufacturers securing feedstock flexibility.
Oil and Gas Midstream Market Segmentation
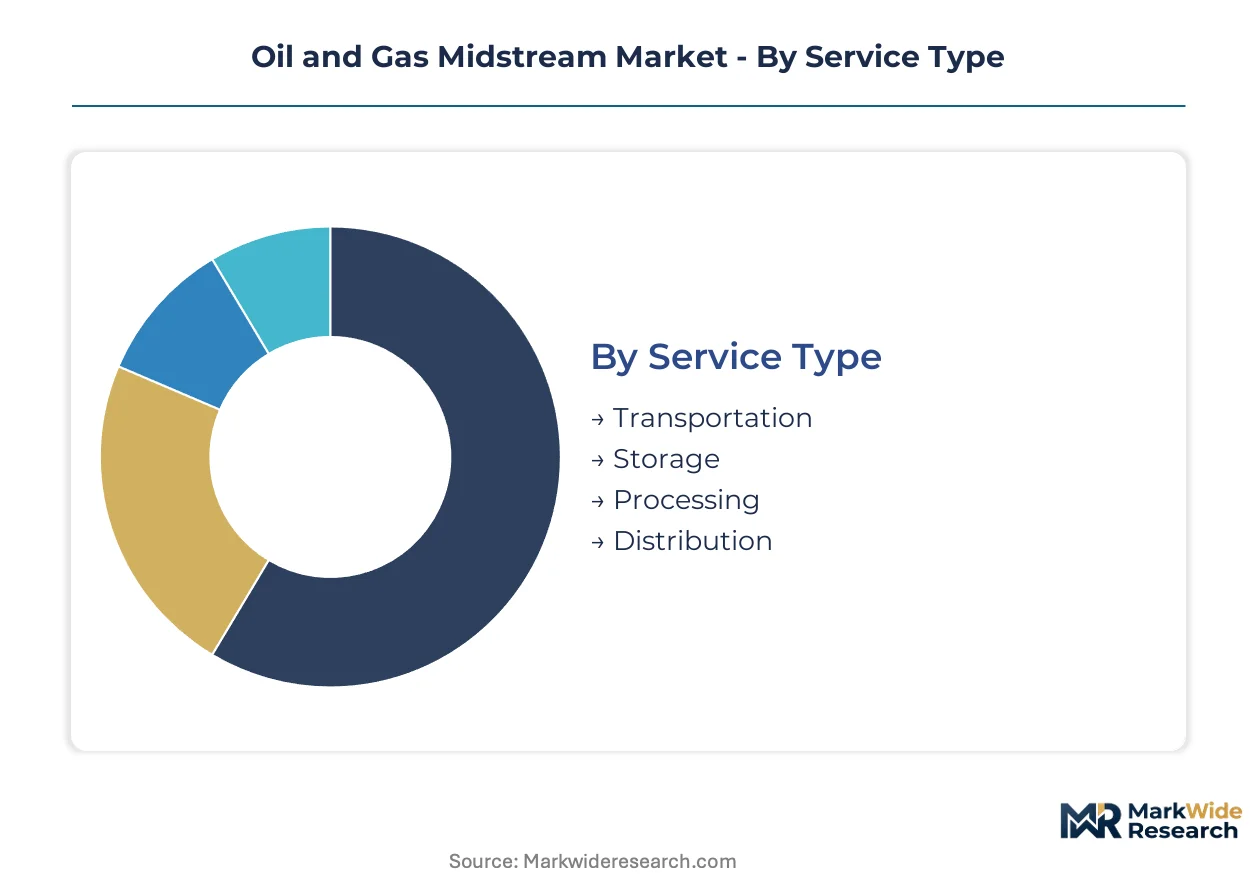
Midstream operators configure infrastructure investments around distinct service capabilities, technology platforms, and customer risk profiles. Each segmentation axis reveals where capital deployment concentrates and which contract structures command premium economics.
Service Type:
Replacement cycles for aging compression and tankage assets are accelerating as EPA methane rules and PHMSA integrity mandates force systematic upgrades across the installed base.
- Transportation:Long-haul pipelines rated between 200 and 1,440 psi generate stable tariff revenues under FERC-regulated interstate rate structures or negotiated contract carriage. Permian Basin production growth is straining existing takeaway capacity, forcing operators to commit to long-term contracts before infrastructure completion.
- Storage:Underground salt caverns and above-ground tank farms provide inventory buffering against supply disruptions and seasonal demand swings. Gulf Coast chemical manufacturers are unbundling storage from transportation contracts, seeking standalone tankage commitments at Houston Ship Channel terminals for feedstock flexibility.
- Processing:Gas treatment plants remove contaminants including CO2, H2S, and water vapor to meet pipeline quality specifications. Associated gas from shale oil production requires cryogenic fractionation capacity expansion, particularly across the Permian and Delaware Basins.
- Distribution:Last-mile delivery networks connect interstate transmission to local distribution companies and industrial offtakers. Urban load centers in the Texas-Louisiana corridor are seeing infrastructure repurposing for hydrogen blending trials.
Volume placements concentrate in Transportation; the faster expansion belongs to Processing.
Technology:
Capital intensity varies sharply across technology categories, with liquefaction assets requiring multibillion-dollar commitments while compression equipment follows more modular procurement patterns.
- Pipelines:Steel transmission lines with cathodic protection systems form the backbone of continental energy logistics. Inline inspection mandates under PHMSA rules are creating technician shortages for interpreting smart pig data from magnetic flux leakage surveys.
- LNG Terminals:Cryogenic facilities maintaining minus 162 degrees Celsius enable intercontinental gas trade through liquefaction and regasification. Corpus Christi and Sabine Pass expansions are pulling NGL feedstock through new pipeline laterals.
- Pumps:Centrifugal and positive displacement units maintain flow assurance across gathering and transmission networks. Advanced composite materials are displacing steel in corrosive sour gas applications.
- Compressors:Reciprocating and turbine-driven units maintain pressure gradients across extended pipeline corridors. EPA methane regulations are retrofitting stations with continuous monitoring systems and electric pneumatic controllers.
Capital deployment clusters on Pipelines; steepest expansion trajectory is occurring in LNG Terminals.
End User:
Contract duration and creditworthiness diverge significantly across customer types, with integrated oil producers offering volume commitments while merchant refiners prioritize flexibility.
- Refineries:Downstream processors require reliable crude delivery and product offtake infrastructure to maintain utilization rates. Midwest refineries depend on Enbridge mainline systems for heavy Canadian crude supply.
- Utilities:Local distribution companies and power generators seek firm transportation capacity to serve heating and electricity demand. Grid-scale battery storage is displacing gas-fired peaking capacity in certain load centers.
- Chemical Manufacturers:Ethylene and ammonia producers require dedicated NGL and hydrogen feedstock logistics. Expanding offtake commitments are securing feedstock reliability against infrastructure bottlenecks.
- Oil Producers:Upstream operators need gathering systems and gas processing to monetize associated production. Smaller Permian producers are selling midstream assets rather than funding methane compliance upgrades.
Contract volumes concentrate with Refineries; chemical offtake is climbing the fastest.
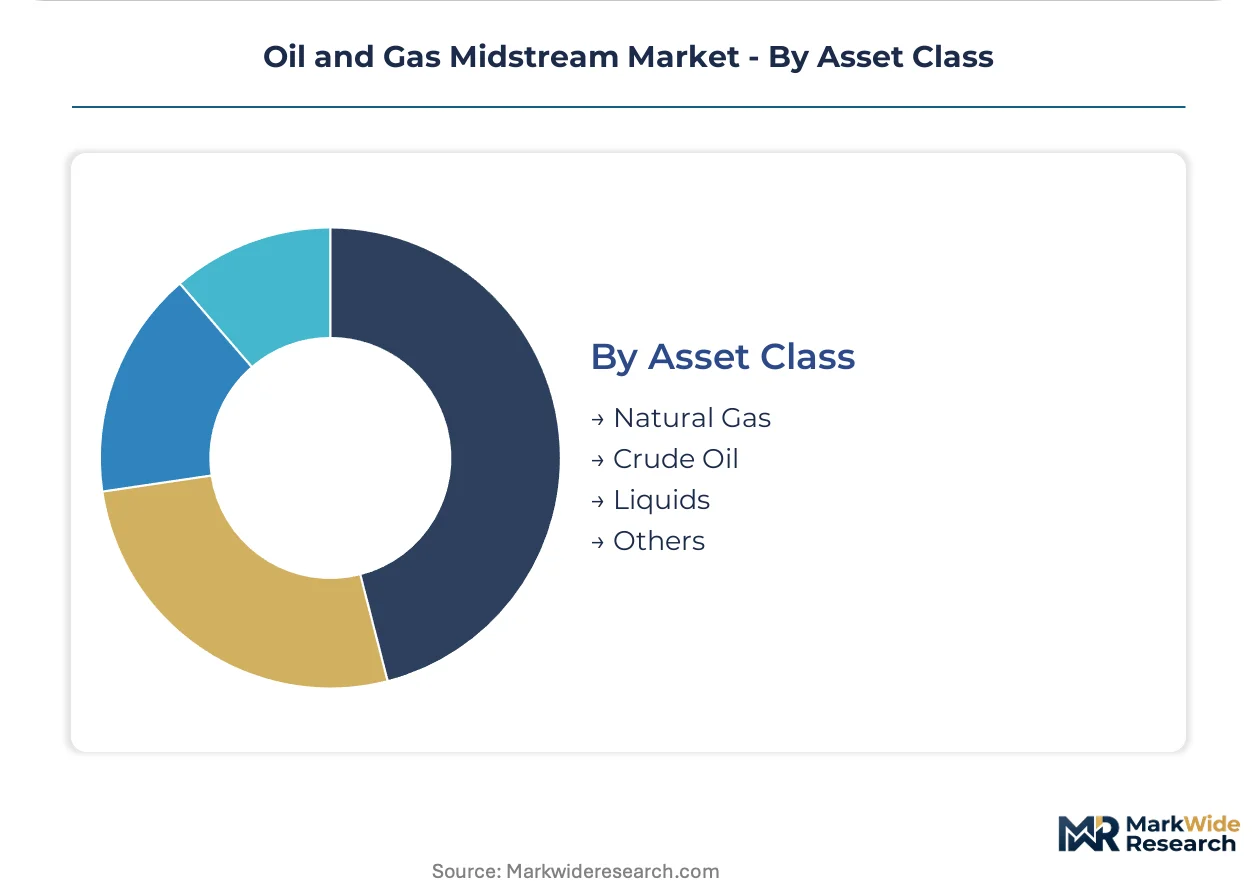
Asset Class:
Commodity-specific infrastructure exhibits diverging utilization economics, with natural gas assets benefiting from export demand while crude systems face longer-term electrification headwinds.
- Natural Gas:Methane-focused infrastructure spans transmission, storage, and liquefaction assets serving power generation and industrial heat. Gulf Coast hydrogen hub development is repurposing existing pipeline corridors.
- Crude Oil:Petroleum logistics systems connect production basins to refineries and marine export terminals. Alberta-to-Midwest mainline systems sustain heavy throughput despite pipeline capacity constraints.
- Liquids:NGL fractionation and petrochemical feedstock handling require specialized cryogenic and pressurized infrastructure. Rising gas-to-oil ratios are expanding fractionation demand.
- Others:Carbon dioxide, hydrogen, and helium handling infrastructure represents emerging service categories. Carbon capture retrofits are bolting amine-based systems onto processing plants to monetize 45Q tax credits.
Throughput volumes concentrate in Natural Gas; hydrogen and CO2 infrastructure is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces more associated gas than its processing capacity can currently handle, while Asian import demand pulls LNG cargoes through Gulf Coast terminals. This production-consumption divide is reshaping infrastructure investment patterns across multiple continents.
United States
Permian Basin operators face gas-to-oil ratios exceeding six thousand cubic feet per barrel, forcing commitments to new cryogenic fractionation plants. The EPA's methane performance standards mandate electric pneumatic controller replacements at compressor stations by 2026. Corpus Christi and Sabine Pass anchor the Gulf Coast export corridor where Cheniere Energy operates liquefaction trains serving Asian offtakers.
Canada
Alberta oil sands producers require diluted bitumen pipeline capacity to reach US Midwest refineries and Asian export markets. The Canada Energy Regulator oversees tolling disputes on the Trans Mountain expansion while enforcing pipeline integrity standards. Edmonton and Calgary house the engineering headquarters for mainline system operators managing throughput to Superior, Wisconsin.
Germany
Industrial gas demand from chemical manufacturers BASF and Covestro requires diversified LNG import capacity following Russian pipeline supply disruptions. The Federal Network Agency regulates third-party access to new floating storage and regasification units at Wilhelmshaven and Lubmin. The Rhine-Ruhr corridor remains Europe's largest petrochemical cluster despite feedstock cost pressures.
China
Shale gas production in Sichuan Basin requires gathering system buildout to reach coastal demand centers. The Ministry of Ecology and Environment enforces methane intensity targets under national dual carbon commitments. Ningbo and Zhoushan host independent LNG terminals serving provincial distribution companies bypassing pipeline monopolies.
Australia
Coal seam gas from Queensland's Surat Basin feeds Curtis Island liquefaction trains serving Japanese and Korean utility contracts. The National Offshore Petroleum Safety and Environmental Management Authority regulates subsea pipeline integrity for Browse Basin developments. Karratha anchors the Pilbara LNG precinct where Woodside operates Pluto and North West Shelf facilities.
Oil and Gas Midstream Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the midstream value chain. The market structure concentrates around interstate pipeline operators with FERC-regulated rate bases and independent fractionation providers serving merchant chemical demand. Three archetypes dominate: integrated majors with captive upstream supply, pure-play MLPs with fee-based contract profiles, and utility-affiliated gas distributors with regulated local monopoly positions. Competitive moves center on long-term take-or-pay contract anchoring and strategic pipeline lateral expansions into production growth zones.
Within the large-scale infrastructure tier, Kinder Morgan, Inc. and Energy Transfer LP exemplify the integrated pipeline-and-terminal model. Enbridge Inc. occupies a position as the dominant cross-border crude oil logistics provider. These three operators anchor the competitive landscape through their control of continental corridor capacity and their ability to bundle transportation, storage, and processing services under unified contract structures.
| Leading Market Players |
|---|
| Kinder Morgan, Inc. |
| Energy Transfer LP |
| Enbridge Inc. |
| ONEOK, Inc. |
| MPLX LP |
| The Williams Companies, Inc. |
| TC Energy Corporation |
| Cheniere Energy, Inc. |
| Enterprise Products Partners L.P. |
| Others |
Value Chain & Pricing Dynamics
Horizontal consolidation among interstate pipeline operators anchors both supply security and tariff-setting power across North American corridors. Kinder Morgan and Energy Transfer leverage contiguous right-of-way networks to bundle transportation, storage, and fractionation services under unified rate structures that resist margin erosion.
Pricing Analysis
Margin tightening in gas processing reflects steel alloy surcharges and extended FERC certificate timelines inflating project carrying costs. Take-or-pay contracts with minimum volume commitments dominate, with price differentiation across premium firm transportation, standard interruptible service, and economy spot nominations. Chemical manufacturers at Houston Ship Channel terminals exhibit highest price sensitivity, seeking unbundled tankage commitments separate from pipeline nomination rights.
Supply Chain Analysis
Regional distribution centers for pipeline-grade steel and compression equipment cluster in Houston, Calgary, and Dusseldorf. Fabrication draws from specialized alloy mills, cathodic protection systems, and cryogenic component suppliers. Single-source vulnerability concentrates in large-diameter pipe forging capacity. Distribution runs through EPC contractor networks with long-term master service agreements to midstream developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US EPA methane performance standards and PHMSA integrity mandates erect compliance moats that favor capital-rich incumbents with retrofit execution capability.
For Market Incumbents: Hedge against electrification substitution by repurposing Gulf Coast pipeline corridors for hydrogen blending trials. Secure backward integration into carbon capture retrofit services at gas processing plants. Threat: Grid-scale battery storage displacing gas-fired peaking capacity in Texas load centers. For New Entrants and Emerging Players: The premium-economy price-point gap in modular liquefaction equipment opens white-space at stranded Rocky Mountain gas fields. Target cryogenic fractionation buildout in the Delaware Basin where smaller producers sell midstream assets rather than fund methane compliance. Go-to-market angle: Lease-operate contracts with continuous emissions monitoring bundled. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure REIT conversions and utility-affiliated roll-ups. Long-term viability favors operators with FERC-regulated rate bases and contracted throughput across the projection horizon. Acquisition target archetype: Pure-play gas processors with 45Q-eligible carbon capture retrofit potential. Signal to watch: FERC certificate approval velocity as inflection indicator for capital deployment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Amine-based bolt-ons at Permian processing plants monetize 45Q tax credits for low-carbon hydrogen output. |
| Hydrogen Hub Development | Texas-Louisiana corridor repurposes existing compressor stations and right-of-way for blending trials. |
| Modular Liquefaction Deployment | Small-scale LNG trains reach stranded Rocky Mountain gas fields previously uneconomical for pipeline connection. |
| Digital Twin Commissioning | Thermal hydraulic simulation before physical construction reduces startup risks at complex fractionation facilities. |
| Composite Material Transition | Fiberglass-reinforced thermoplastic lines eliminate internal corrosion monitoring for sour gas producers in the Delaware Basin. |
Study Parameters
FERC filings, EIA production databases, and EPA enforcement records formed the secondary backbone, cross-referenced with PHMSA incident reports and interstate pipeline tariff schedules. Primary interviews with gas processing plant managers, pipeline integrity engineers, and chemical manufacturer procurement leads validated capacity utilization assumptions and contract structure evolution. Bottom-up project-level capacity buildout estimates triangulated against top-down midstream infrastructure spending forecasts.
Historical trendline analysis of pipeline mileage additions, gas processing plant commissioning rates, and LNG export terminal capacity utilization informed the projection framework. Segmentation dimensions modeled include service type, technology platform, end-user contract profile, and asset class commodity exposure. CAGRs derived from fitted trend extrapolation adjusted for regulatory implementation timelines and feedstock availability constraints.
Inputs from FERC certificate databases and EPC contractor backlogs were available through the study window; gaps in real-time methane emissions verification introduce uncertainty bands around compliance cost estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Sidetracking Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Injection Well Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Oil and Gas Pipe Market