
 Libya Oil and Gas Upstream Market | 2026-2036
Libya Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Libya Oil and Gas Upstream Market Foresight
Libyan upstream operators is restructuring field development priorities after years of intermittent output disruptions. National Oil Corporation anchors domestic production scale through direct field ownership and joint venture governance. Eni S.p.A. leverages deepwater exploration expertise across Mediterranean offshore concessions. TotalEnergies SE sustains long-dated positions in Saharan and offshore blocks through phased investment commitments.
Libya Oil and Gas Upstream encompasses exploration, drilling, and production activities extracting hydrocarbons from subsurface reservoirs, with crude oil typically characterized by API gravities ranging from 26° to 42° across Libyan fields. The primary purpose centers on supplying feedstock to refineries and LNG export terminals serving Mediterranean and European markets. Crude Oil dominates value generation through light sweet grades commanding premium pricing against Brent benchmarks. Enhanced Oil Recovery represents the fastest-expanding technology segment as mature Sirte Basin fields require pressure maintenance and thermal stimulation to sustain plateau rates. Seismic Imaging absorbs substantial capital allocation for pre-drilling risk reduction in underexplored offshore blocks.
Libya's Ministry of Oil and Gas oversees concession terms and production sharing agreements, while the National Oil Corporation implements operational directives and international partnership frameworks. Environmental compliance with the country's petroleum regulator shapes water disposal standards and flare minimization requirements for new field approvals. Stakeholders must monitor political transition timelines and force majeure declarations that abruptly alter offtake commitments and capital deployment schedules.
Market Dynamics
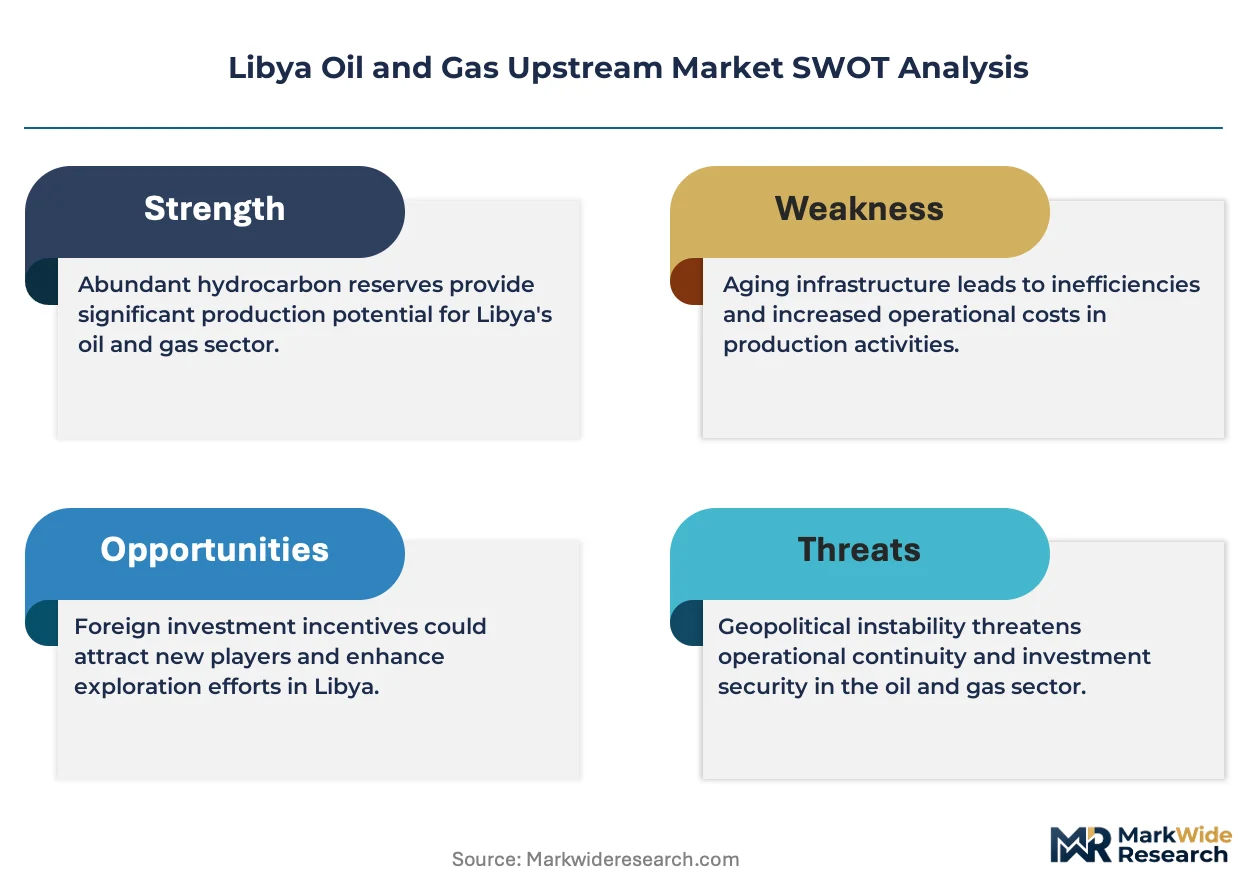
Libya's upstream sector operates under persistent force majeure risk as political transition timelines repeatedly disrupt production sharing agreement enforcement and field development schedules. The National Oil Corporation's dual mandate as operator and regulator creates governance friction that shapes capital deployment patterns.
Growth Catalysts
- Mediterranean Offshore Licensing:Unawarded deepwater blocks in the Sirte Basin and Gulf of Sidra attract seismic investment from European majors seeking light sweet crude alternatives to declining North Sea output.
- Enhanced Oil Recovery Mandates:Libya's Ministry of Oil and Gas now requires pressure maintenance schemes for mature fields, driving thermal stimulation and gas injection technology procurement.
- European Refinery Feedstock Demand:Italian and German refiners prioritize Libyan Es Sider and Sarir grades for their low sulfur content and favorable distillation yields.
Market Restraints
- Capital Flight Volatility:International oil companies suspend drilling programs during armed conflict episodes, creating multi-year investment gaps that degrade reservoir pressure maintenance.
- Export Infrastructure Concentration:Crude loading terminals at Ras Lanuf and Zueitina remain vulnerable to blockades by paramilitary groups controlling Libya's coastal strip.
- Service Provider Scarcity:Schlumberger and Halliburton maintain skeleton crews in Tripoli, limiting availability of directional drilling and wireline logging expertise.
Strategic Opportunities
- Sirte Basin Brownfield Redevelopment:Maturing fields at Intisar and Nafoora await tertiary recovery investments that could restore plateau production through polymer flooding.
- Flare Gas Monetization:Libya's petroleum regulator is drafting capture requirements that would feed stranded gas to planned LNG export facilities at Mellitah.
- Digital Twin Adoption:National Oil Corporation joint ventures are piloting real-time reservoir simulation to optimize waterflood patterns and reduce unplanned downtime.
Industry Challenges
- Petroleum Engineering Talent Drain:Decades of conflict drove Libyan geoscientists and drilling engineers to UAE and Qatar, creating knowledge gaps in subsurface characterization.
- PSA Renegotiation Complexity:Existing production sharing agreements signed under Gaddafi-era terms require legal arbitration to align fiscal terms with current Brent pricing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Libya Oil and Gas Upstream Market |
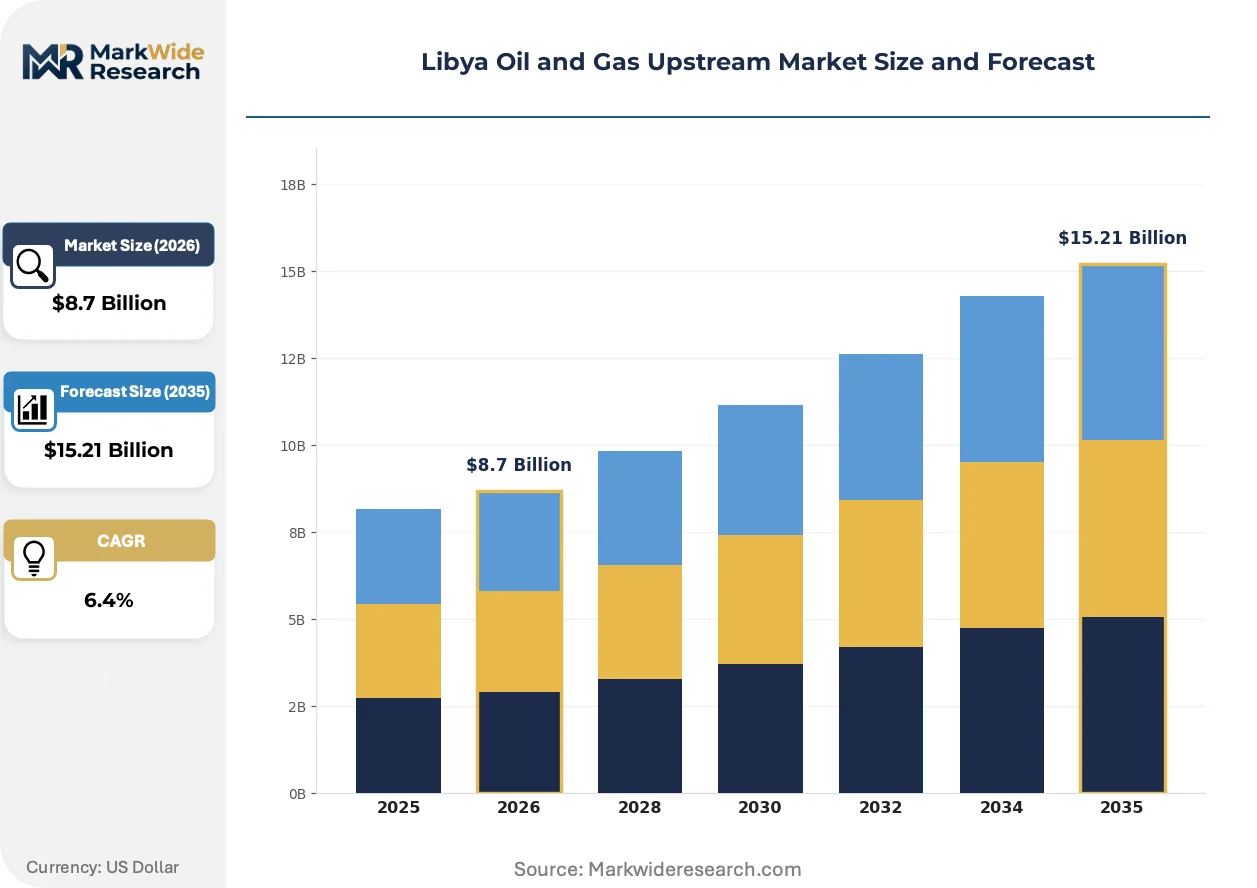
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, NGL, Oil Sands Application: Exploration, Production, Drilling, Refining Technology: Seismic Imaging, Drilling Technology, Enhanced Oil Recovery, Hydraulic Fracturing End User: Oil Companies, Government Entities, Contractors, Service Providers |
| Companies Covered | National Oil Corporation, Eni S.p.A., TotalEnergies SE, BP plc, Repsol S.A., Wintershall Dea AG, PJSC Gazprom, Polskie Górnictwo Naftowe i Gazownictwo S.A., Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Libya Oil and Gas Upstream Market Shifts & Advancements
Upstream technology deployment in Libya is pivoting toward reservoir intelligence systems that mitigate operational uncertainty. Field operators now prioritize predictive maintenance and automated well control to sustain output during workforce disruptions.
4D seismic monitoring is integrating time-lapse reservoir imaging with production data streams to track fluid movement in carbonate formations. Eni S.p.A. and TotalEnergies SE deploy these surveys across offshore concessions to optimize infill drilling locations. The technology is compressing exploration cycle times and reducing dry-hole risk in underexplored Mediterranean blocks.
Libya's Ministry of Oil and Gas is tightening flare minimization standards through amendments to petroleum environmental regulations. New field development plans must now incorporate gas conservation infrastructure or face permit delays. Offshore projects in the Bouri field complex bear the highest compliance burden as shallow-water platforms retrofit vapor recovery units.
European refiners are consolidating procurement through term contracts with National Oil Corporation rather than spot market purchases. This shift reflects risk aversion to supply disruptions and preference for predictable feedstock quality. Italian processors at Milazzo and Taranto lead this behavioral change, locking in multi-year offtake agreements with destination flexibility clauses.
Libya Oil and Gas Upstream Market Segmentation
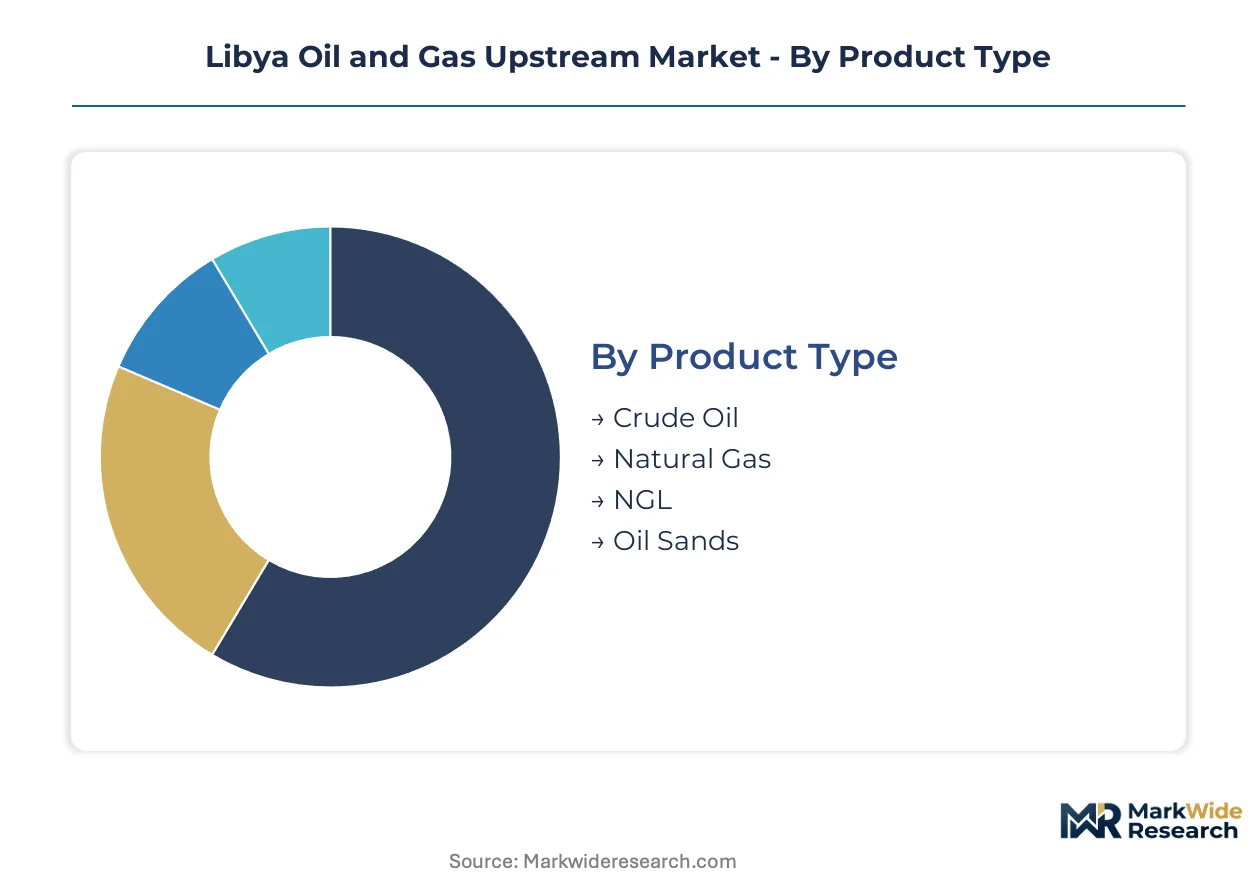
Upstream segmentation in Libya reflects the National Oil Corporation's dual priorities: maximizing recovery from mature Sirte Basin fields while attracting investment to underexplored Mediterranean blocks. Distinct technology and end-user profiles shape capital allocation across each category.
Product Type:
Supply concentrates in light sweet crude grades that command premium pricing at European refineries, with natural gas gaining strategic importance for domestic power generation and export monetization.
- Crude Oil:Libyan crudes span API gravities from 26° to 42°, with Es Sider and Sarir grades prized by Italian and German refiners for low sulfur content and high middle-distillate yields. European offtake agreements now favor term contracts over spot purchases to mitigate supply disruption risk.
- Natural Gas:Associated gas from offshore fields and non-associated reserves in the Ghadames Basin feeds domestic power plants and planned LNG export capacity at Mellitah. Flare capture mandates from Libya's petroleum regulator are accelerating infrastructure investment.
- NGL:Condensate and liquefied petroleum gas production accompanies crude extraction at Mellitah and Bouri field complexes, supplying petrochemical feedstock to regional markets.
- Oil Sands:Heavy oil deposits in the southern Sirte Basin remain undeveloped due to high thermal extraction costs and infrastructure distance from coastal export terminals.
Today's leader: Crude Oil. Tomorrow's challenger: Natural Gas.
Application:
Cost tier differentiation separates capital-intensive exploration from operational production activities, with drilling services commanding premium rates during licensing round cycles.
- Exploration:Seismic surveying and wildcat drilling concentrate in Mediterranean offshore blocks licensed to Eni and TotalEnergies, where water depths exceed 500 meters and reservoir characterization demands 4D imaging technology.
- Production:Mature field operations at Intisar, Nafoora, and Sarir dominate volume, requiring continuous artificial lift and waterflood management to sustain plateau rates.
- Drilling:Directional and horizontal drilling programs face service provider scarcity as Schlumberger and Halliburton maintain reduced Tripoli-based crews, extending rig mobilization timelines.
- Refining:Upstream-refining integration remains limited; Ras Lanuf and Zawiya refineries process domestic crude for local product supply rather than export-oriented upgrading.
Production absorbs the majority of operating expenditure. Exploration offers the steepest expansion trajectory if political stability permits licensing round acceleration.
Technology:
Volume concentration in mature fields drives Enhanced Oil Recovery procurement, while frontier exploration depends on seismic imaging advances to reduce pre-drilling risk.
- Enhanced Oil Recovery:Thermal stimulation, gas injection, and polymer flooding are now mandatory for Sirte Basin fields under Ministry of Oil and Gas pressure maintenance directives. Tertiary recovery investments could restore plateau production at aging Intisar and Nafoora assets.
- Seismic Imaging:4D time-lapse surveys track fluid movement in carbonate formations across offshore concessions, compressing exploration cycle times and optimizing infill drilling locations for European operators.
- Drilling Technology:Automated well control and predictive maintenance systems are piloted in National Oil Corporation joint ventures to sustain output during workforce disruptions.
- Hydraulic Fracturing:Limited application in Libya's conventional carbonate reservoirs; tight gas formations in the Ghadames Basin represent potential future deployment if fracturing fluid supply chains stabilize.
Enhanced Oil Recovery dominates technology procurement today. Seismic Imaging will determine tomorrow's reserve replacement success in deepwater blocks.
End User:
Customer type fragmentation splits operational control between state-owned National Oil Corporation and international joint venture partners, with service providers capturing specialized technology contracts.
- Oil Companies:Eni and TotalEnergies operate through production sharing agreements signed under legacy fiscal terms, requiring legal arbitration to align with current Brent pricing environments.
- Government Entities:The National Oil Corporation exercises direct field ownership and regulatory oversight, creating governance friction that shapes capital deployment patterns and partnership terms.
- Contractors:Engineering and construction firms execute brownfield redevelopment at Sirte Basin mature fields, facing payment delays and security constraints that extend project timelines.
- Service Providers:Directional drilling, wireline logging, and reservoir simulation expertise concentrates with reduced international crew presence, limiting availability during production restoration campaigns.
Government Entities anchor procurement volume today. Oil Companies represent tomorrow's investment catalyst if PSA renegotiation succeeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where force majeure risk and fiscal instability create lower cost-of-compliance thresholds for upstream operators. Libya's National Oil Corporation governance structure offers regulatory arbitrage against stricter North African neighbors, though intermittent blockades erode this advantage.
Tripolitania
Mellitah and Bouri field complexes anchor offshore gas production feeding planned LNG export capacity. Libya's Ministry of Oil and Gas flare minimization amendments impose vapor recovery retrofit obligations on shallow-water platforms. The coastal corridor between Tripoli and Zawiya concentrates associated gas processing infrastructure serving domestic power generation.
Cyrenaica
Es Sider and Sarir crude grades command premium pricing at Italian refineries for low sulfur content and high middle-distillate yields. The National Oil Corporation's production restoration roadmap prioritizes pressure maintenance schemes at aging Intisar and Nafoora assets. Benghazi serves as the operational hub for Sirte Basin brownfield redevelopment engineering.
Fezzan
Non-associated gas reserves in the Ghadames Basin await infrastructure connection to coastal export terminals. Libya's petroleum regulator requires environmental impact assessments for new field approvals in this underexplored southern region. Sabha functions as the logistics coordination point for desert exploration campaigns targeting tight gas formations.
Gulf of Sidra
Deepwater exploration blocks licensed to European majors attract seismic investment seeking light sweet crude alternatives to declining North Sea output. 4D time-lapse surveys track fluid movement in carbonate formations across offshore concessions held by Eni and TotalEnergies. Ras Lanuf crude loading terminals remain vulnerable to paramilitary blockades disrupting offtake commitments.
Libya Oil and Gas Upstream Market Competitive Landscape
European majors anchor one tier through production sharing agreements signed under legacy fiscal terms; state-owned National Oil Corporation operators hold direct field ownership and regulatory oversight. The vendor base splits between international joint venture partners and domestic entities with governance friction shaping capital deployment patterns. Two strategic archetypes dominate: integrated supermajors with deepwater exploration expertise, and national oil companies exercising operational control through direct equity stakes. Competitive moves center on PSA renegotiation arbitration and tertiary recovery technology procurement to align with current Brent pricing environments.
Within the integrated supermajor tier, Eni S.p.A. and TotalEnergies SE exemplify European operators sustaining long-dated positions across Mediterranean offshore concessions. National Oil Corporation occupies the state-operator archetype, exercising dual mandate as field owner and sector regulator. BP plc represents the major holding legacy positions pending fiscal term alignment. These entities collectively illustrate how political transition timelines and force majeure declarations abruptly alter partnership structures and capital deployment schedules.
| Leading Market Players |
|---|
| National Oil Corporation |
| Eni S.p.A. |
| TotalEnergies SE |
| BP plc |
| Repsol S.A. |
| Wintershall Dea AG |
| PJSC Gazprom |
| Polskie Górnictwo Naftowe i Gazownictwo S.A. |
| Shell plc |
| Others |
Supply & Pricing Matrix
Seismic surveying costs from Mediterranean offshore blocks flow through to term contract premiums that European refiners pay for Es Sider and Sarir crude grades. Libya's Ministry of Oil and Gas flare capture mandates add infrastructure recovery surcharges to lifting costs, compressing margins for operators without integrated gas processing.
Pricing Analysis
Direct-to-refinery term contracts handle the majority of European offtake, bypassing spot market volatility. Three-tier pricing structure across premium light sweet grades, standard medium crudes, and heavy sour alternatives tracks API gravity and sulfur content differentials. Pricing pressure stems from force majeure declarations that trigger destination flexibility clauses and discount renegotiation. National Oil Corporation joint ventures show least price sensitivity due to captive domestic offtake, while independent traders exhibit highest sensitivity to loading terminal disruptions.
Supply Chain Analysis
Direct-to-refinery channels handle European term contract volumes, with Italian and German processors maintaining dedicated tanker fleets. Supply concentrates in Libya's coastal loading terminals at Ras Lanuf, Zueitina, and Mellitah, with secondary dependencies on Egyptian Suez transit for Asian-bound cargoes. Raw material inputs draw from Schlumberger and Halliburton directional drilling services, seismic vessel charters from WesternGeco, and specialized thermal stimulation chemicals. Single-source vulnerability runs through the Sirte Basin pipeline corridor where paramilitary blockades halt flows for weeks. Distribution runs through National Oil Corporation scheduling offices that allocate export quotas among joint venture partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Libya's upstream sector functions as a regulatory-arbitrage destination where National Oil Corporation governance friction creates lower compliance costs than Algeria's Sonatrach or Egypt's EGPC, though intermittent force majeure erodes this differential.
For Market Incumbents: Anticipate PSA renegotiation arbitration demands from European majors seeking fiscal term alignment with current Brent environments. Consolidate field service partnerships with reduced-crew providers like Schlumberger to lock in directional drilling capacity before licensing round cycles intensify competition. Pressure maintenance technology procurement represents the priority defensive lever against reserve decline at Intisar and Nafoora.
For New Entrants and Emerging Players: Capture tertiary recovery service contracts at Sirte Basin mature fields where National Oil Corporation mandates pressure maintenance schemes. Digital twin implementation for real-time reservoir simulation offers the most penetrable white-space, with Mellitah and Bouri complexes piloting adoption. Go-to-market positioning should emphasize automated well control systems that sustain output during workforce disruptions.
For Investors and Strategic Acquirers: Consolidation pressure builds where European majors seek exit from legacy PSA positions amid fiscal term disputes. Long-term viability hinges on political transition stabilization that permits sustained production restoration campaigns. Acquisition targets with integrated gas processing infrastructure signal inflection readiness for LNG export monetization at Mellitah.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Deployment | Thermal stimulation and gas injection restore plateau rates at aging Sirte Basin fields under Ministry mandates. |
| Offshore Licensing Round Participation | Deepwater block awards to Eni and TotalEnergies secure light sweet crude alternatives for European refiners. |
| Flare Gas Capture Infrastructure | Vapor recovery retrofits at Bouri platforms satisfy Libya's petroleum regulator environmental amendments. |
| Digital Twin Pilot Implementation | Real-time reservoir simulation optimizes waterflood patterns and reduces unplanned downtime for joint ventures. |
| PSA Fiscal Term Renegotiation | Legal arbitration aligns Gaddafi-era production sharing agreements with current Brent pricing environments. |
Research Methodology
Multiple input streams — production data from National Oil Corporation field reports, European refinery offtake records, and seismic investment disclosures from Mediterranean licensing rounds — were reconciled through bottom-up and top-down triangulation. Primary interviews with upstream project managers at Eni and TotalEnergies, petroleum engineering directors at service providers, and procurement leads at Italian refineries informed operational assumptions. Secondary validation drew from Libya's Ministry of Oil and Gas regulatory filings, OPEC monthly oil market reports, and Lloyd's List tanker tracking data.
Historical production trajectories were cross-referenced against panel input from reservoir engineers and exploration geoscientists to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application tier, technology deployment, and end-user control structure. CAGRs were derived from supply-demand balance projections incorporating field decline curves and greenfield development timelines. Forecast inputs incorporated force majeure frequency assumptions and European refinery run rate sensitivity.
Political transition instability, paramilitary blockade recurrence, and petroleum engineering talent migration are the dominant revision risks that could alter field development schedules and export capacity assumptions. Forecasts reflect documented assumptions about licensing round acceleration and PSA enforcement continuity. Periodic stress-testing of base assumptions against force majeure declarations and fiscal term arbitration outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Well Abandonment Services Market