
 Qatar Oil and Gas Market | 2026-2036
Qatar Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Oil and Gas Market Outlook
The capital-intensity divergence between integrated national champions and international portfolio players is rotating Qatar's upstream investment calendar toward fewer, larger-scale commitments. QatarEnergy anchors the North Field expansion with sovereign-backed financing that sustains multi-decade production visibility. Exxon Mobil Corporation leverages its technical partnership in the North Field West development to extend operational expertise into Qatar's offshore frontier. Shell plc competes through integrated LNG trading positions that control offtake flexibility across Asian term contracts.
Qatar oil and gas encompasses hydrocarbon extraction, processing, and liquefaction operations centered on the world's third-largest proven natural gas reserve base, where reservoir depths exceed 10,000 feet and CO2 content challenges conventional separation design. The primary commercial purpose centers on converting subsurface gas into supercooled LNG cargo for maritime export to power-deficient economies. Natural gas and LNG product categories dominate revenue generation given Qatar's deliberate production moratorium on crude oil volumes since the early 2000s. Extraction technology and processing technology segments attract disproportionate capital allocation as operators tackle sour gas treatment and carbon capture integration at North Field scale. Drilling technology remains a specialized margin pool where advanced directional capabilities unlock reservoir sections inaccessible through conventional vertical approaches.
QatarEnergy's project governance functions as a de facto regulatory framework, setting local content requirements and environmental performance benchmarks that shape contractor qualification and technology selection. The Ministry of Environment and Climate Change enforces air emission standards and marine protection protocols that condition offshore development permits and LNG plant licensing. International Maritime Organization bunker fuel regulations and EU methane emission monitoring frameworks are reshaping cargo specifications and measurement transparency for Qatari exporters. Stakeholders must monitor how carbon border adjustments in buyer jurisdictions reconfigure the premium attached to certified lower-carbon LNG cargoes.
Market Dynamics
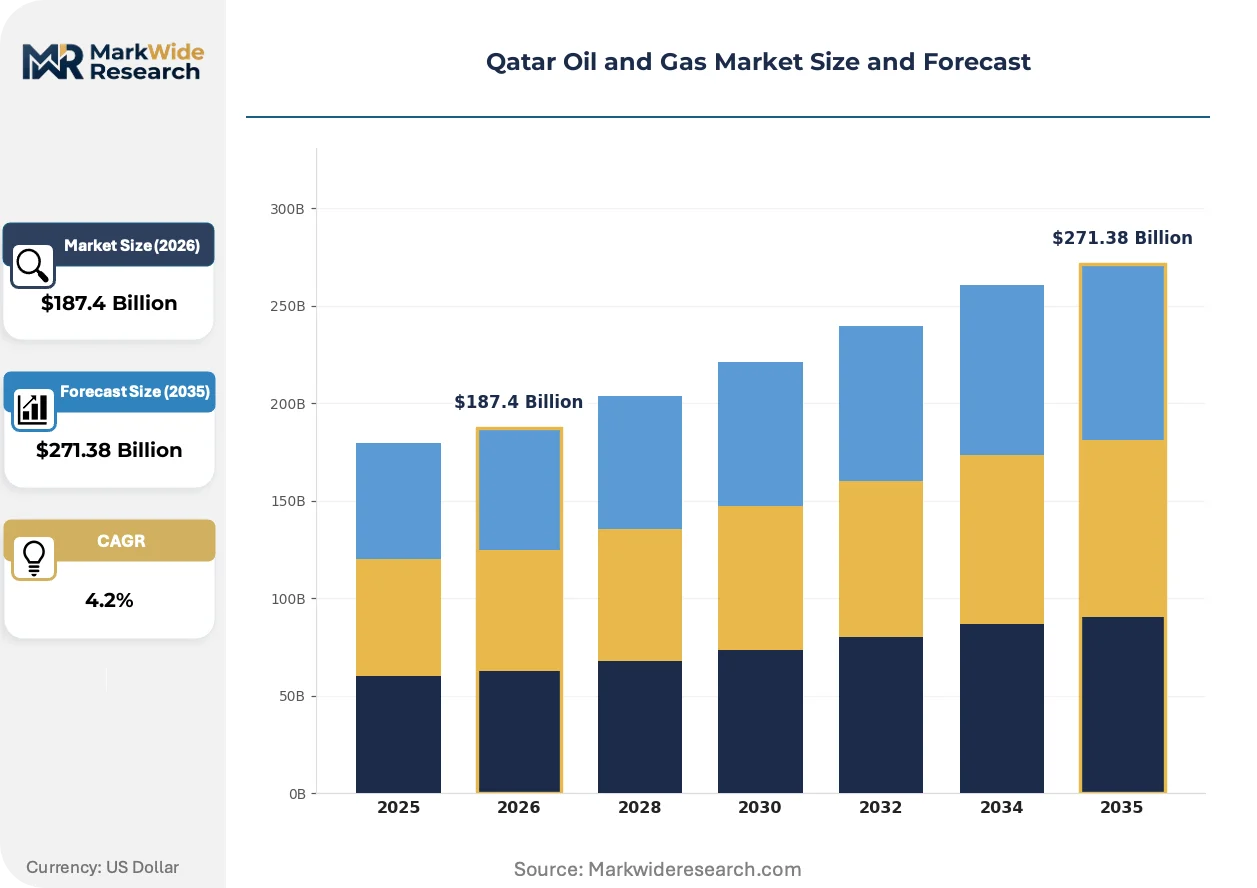
Qatar's North Field expansion is compressing capital deployment timelines as QatarEnergy consolidates megaproject governance around fewer, larger-scale commitments that reshape contractor qualification thresholds and technology selection criteria.
Growth Catalysts
- North Field East Megaproject:Sovereign-backed financing sustains multi-decade production visibility and anchors upstream investment calendars toward integrated national champions.
- EU Carbon Border Adjustment Mechanism:Certified lower-carbon LNG cargoes command premium positioning as European utilities reconfigure procurement specifications around emission transparency.
- Asian Utility Diversification:Japanese, South Korean, and Indian power generators are rotating term contracts away from pipeline dependencies toward maritime LNG flexibility.
Market Restraints
- CO2 Content Processing:Reservoir depths exceeding 10,000 feet with sour gas composition challenge conventional separation design and inflate extraction technology capital requirements.
- Specialized Drilling Capacity:Advanced directional capability scarcity concentrates among limited service providers, creating bottleneck risk for reservoir sections inaccessible through vertical approaches.
- International Maritime Organization Bunker Standards:Evolving marine fuel regulations reshape cargo specifications and measurement protocols, conditioning LNG plant licensing timelines.
Strategic Opportunities
- Carbon Capture Integration:North Field scale enables deployment of integrated carbon capture systems that align with EU methane monitoring frameworks and lower-carbon certification demand.
- Indian Power Sector Expansion:Underpenetrated long-term contract penetration in India's coastal generation corridor offers volume growth outside established Northeast Asian term markets.
- Ministry of Environment Marine Protocols:Stringent offshore development permit conditions create first-mover advantage for contractors with demonstrated environmental performance benchmarking.
Industry Challenges
- Directional Drilling Expertise Scarcity:Advanced reservoir navigation capabilities remain concentrated among specialized service providers, compressing project execution timelines.
- Legacy Processing System Integration:Sour gas treatment retrofits at existing facilities must interface with carbon capture architectures without disrupting continuous liquefaction operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Oil and Gas Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Liquefied Natural Gas, Petrochemicals Technology: Extraction Technology, Refining Technology, Processing Technology, Drilling Technology Application: Energy Production, Industrial Usage, Transportation, Residential Heating End User: Power Plants, Manufacturing Facilities, Shipping Companies, Residential Consumers |
| Companies Covered | TotalEnergies SE, Chevron Corporation, QatarEnergy, Sinopec, China National Petroleum Corporation, Exxon Mobil Corporation, ConocoPhillips Company, Eni S.p.A., Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Oil and Gas Market Strategic Shifts
Technological deployment across Qatar's offshore frontier is accelerating as reservoir complexity demands advanced extraction capabilities and emission monitoring systems reshape operational specifications.
Subsea compression technology is fragmenting conventional platform-based gas processing architectures. QatarEnergy is deploying seabed boosting systems at North Field West to maintain reservoir pressure without surface facility expansion. This compression approach is fragmenting capital allocation between brownfield upgrades and greenfield platform investments.
EU methane emission monitoring frameworks are tightening cargo measurement transparency requirements. The European Commission's delegated acts under the Methane Regulation impose granular reporting standards on imported LNG. Qatari exporters are responding by deploying continuous emission monitoring systems at liquefaction trains to preserve term contract access.
Asian utility procurement is consolidating around long-term offtake flexibility. Japanese and South Korean power generators are unbundling destination clauses from traditional take-or-pay structures. This contractual evolution is compressing spot market participation and concentrating volume planning around integrated trading positions.
Qatar Oil and Gas Market Segmentation
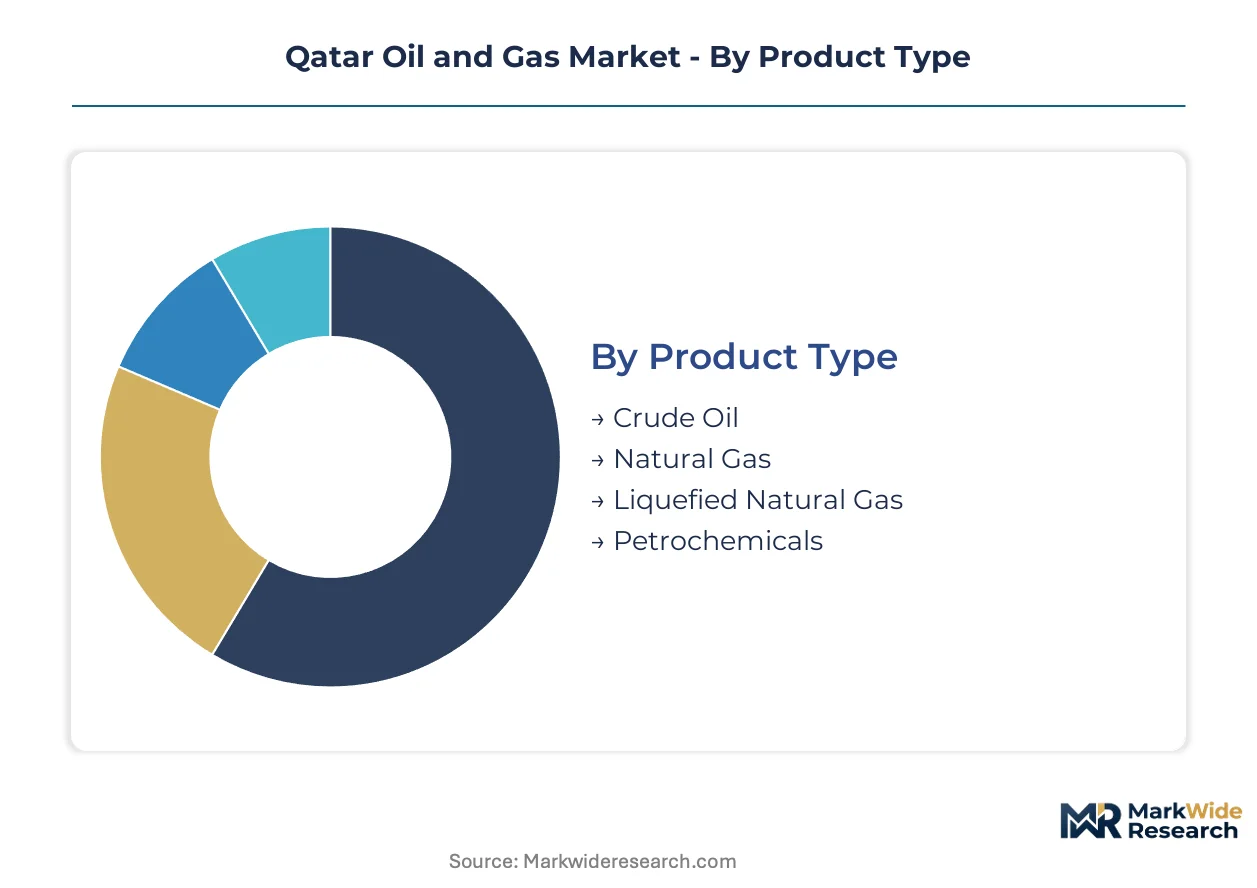
Qatar's hydrocarbon segmentation reflects deliberate production specialization around gas-centric output rather than crude diversification. Regulatory frameworks from QatarEnergy and the Ministry of Environment and Climate Change condition technology selection and end-use certification across each category.
Product Type:
The Ministry of Environment and Climate Change enforces marine protection protocols that differentiate LNG cargo specifications from crude handling permits.
- Natural Gas:Sour gas composition at reservoir depths exceeding 10,000 feet requires advanced CO2 separation infrastructure. Power Plants in Japan and South Korea drive term contract demand as utilities diversify from pipeline dependencies toward maritime flexibility.
- Liquefied Natural Gas:Supercooled cargo conversion enables maritime export to power-deficient Asian economies. Indian coastal generation corridors represent underpenetrated long-term contract growth outside established Northeast Asian markets.
- Crude Oil:Production moratorium since early 2000s limits volumes to marginal legacy fields.
- Petrochemicals:Downstream derivatives leverage feedstock integration with North Field gas processing.
Natural Gas handles the majority of throughput; Liquefied Natural Gas is gaining share fastest on export volume expansion.
Technology:
Cost tier stratification separates capital-intensive extraction systems from operational maintenance technologies.
- Extraction Technology:Reservoir pressure maintenance and sour gas treatment dominate capital allocation. North Field East megaproject deployment concentrates demand for subsea compression and carbon capture integration.
- Processing Technology:Liquefaction train efficiency determines cargo certification for EU methane monitoring frameworks. Ras Laffan Industrial City facilities deploy continuous emission monitoring to preserve European term contract access.
- Drilling Technology:Advanced directional capabilities unlock reservoir sections inaccessible through vertical approaches.
- Refining Technology:Limited application scope given crude production moratorium constraints.
Processing Technology commands the dominant capital share; Extraction Technology is expanding most quickly on North Field West development timelines.
Application:
Customer type segmentation separates utility-scale procurement from distributed consumption patterns.
- Energy Production:Utility-scale power generation absorbs the dominant volume share. Japanese and South Korean power generators unbundle destination clauses from traditional take-or-pay structures.
- Industrial Usage:Manufacturing feedstock demand concentrates in Ras Laffan petrochemical complexes.
- Transportation:Bunker fuel specifications evolve under International Maritime Organization regulations.
- Residential Heating:Minimal domestic penetration given Qatar's climate and infrastructure configuration.
Energy Production absorbs the dominant contract volume; Industrial Usage is climbing the fastest on petrochemical capacity expansion.
End User:
Supply concentration patterns align with infrastructure proximity to liquefaction and loading terminals.
- Power Plants:Coastal generation facilities in India, Japan, and South Korea anchor term offtake. Procurement specifications increasingly weight certified lower-carbon cargo premiums under EU Carbon Border Adjustment Mechanism.
- Shipping Companies:LNG carrier operators and bunker fuel consumers face evolving International Maritime Organization measurement protocols.
- Manufacturing Facilities:Petrochemical and fertilizer producers leverage Qatar's feedstock cost position.
- Residential Consumers:Negligible direct engagement given utility-mediated distribution architecture.
Power Plants command the dominant procurement volume; Shipping Companies are expanding fastest on maritime fuel regulation transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese utilities demonstrate the lowest price elasticity among Asian LNG buyers, locking in term contracts regardless of spot volatility, while Indian coastal generators exhibit the highest sensitivity, arbitraging between spot cargoes and long-term commitments based on landed cost spreads.
Japan
Power utilities JERA and Tokyo Gas anchor Northeast Asian term contract demand as nuclear restarts lag behind thermal generation requirements. METI's GX League initiative imposes carbon intensity disclosure on fuel procurement, reshaping supplier qualification toward certified lower-carbon cargoes. Chubu Electric's Kawagoe terminal expansion concentrates new regasification capacity in the industrial corridor between Nagoya and Tokyo.
South Korea
KOGAS and five private generators rotate procurement away from Middle Eastern pipeline dependencies toward Qatari maritime flexibility under the Hydrogen Economy Roadmap. The Ministry of Trade, Industry and Energy enforces power sector emission caps that tighten annually through 2030, conditioning LNG import licenses on methane leakage certification. The Incheon-Boryeong coastal generation belt absorbs expanding Qatari volumes for combined-cycle baseload replacement.
India
Petronet LNG and Gujarat State Petroleum Corporation drive contract renegotiations as spot price collapses expose legacy oil-indexed term structures. The Petroleum and Natural Gas Regulatory Board mandates unified tariff access for third-party terminal users, fragmenting incumbent monopoly positions. The Dahej-Hazira pipeline corridor on Gujarat's western coast concentrates new FSRU deployment for Qatari cargo receipt.
China
Sinopec and CNOOC diversify term contract portfolios beyond Australian and Russian pipeline dependencies toward Qatari supply security under the 14th Five-Year Plan energy diversification targets. The National Development and Reform Commission enforces city-gate pricing reforms that pass through international volatility to end-users, compressing importer margin buffers. The Yangtze River Delta LNG receiving cluster around Shanghai and Jiangsu anchors premium pricing for winter peak-shaving supply.
Germany
Uniper and RWE accelerate Qatari term contracting as Russian pipeline flows terminate, rebuilding baseload generation capacity around LNG-fired combined-cycle plants. The Federal Network Agency enforces storage filling mandates that front-load procurement into summer injection seasons, reshaping cargo delivery timing requirements. The Wilhelmshaven-Brunsbüttel coastal terminal corridor concentrates new regasification infrastructure for direct Qatari vessel access.
Qatar Oil and Gas Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in Qatar's upstream sector, with integrated national champions commanding sovereign financing scale while international portfolio operators contribute specialized extraction capabilities. Market structure concentrates around QatarEnergy's governance function, which sets contractor qualification thresholds and local content requirements that reshape competitive access. Three archetypes dominate: state-backed integrated champions, international majors with technical partnerships, and specialized service providers with directional drilling scarcity. Dominant competitive moves center on strategic partnerships for North Field access and carbon capture integration to preserve European term contract positioning.
Within the state-backed tier, QatarEnergy anchors sovereign production visibility through direct megaproject governance. Among international majors with technical partnerships, Exxon Mobil Corporation and Shell plc occupy positions where operational expertise transfers into offshore frontier access. TotalEnergies SE and ConocoPhillips Company exemplify the partnership archetype through North Field West participation structures. These named entities represent competitive positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Chevron Corporation |
| QatarEnergy |
| Sinopec |
| China National Petroleum Corporation |
| Exxon Mobil Corporation |
| ConocoPhillips Company |
| Eni S.p.A. |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
North Field East's 32 million tonnes per annum liquefaction capacity anchors supply-side concentration that compresses marginal cost floors across Asian term markets. QatarEnergy's sovereign-backed financing sustains multi-decade production visibility while conditioning price formation around long-term offtake security rather than spot volatility.
Pricing Analysis
After-sales service revenue from liquefaction train maintenance and carbon capture system operations drives lifetime contract value for integrated service providers. Long-term offtake agreements with oil-indexed price floors dominate Qatar's LNG export pricing structure, with certified lower-carbon cargo premiums differentiating EU-bound shipments from standard Asian term volumes. Pricing pressure stems from spot market softness as Indian coastal generators arbitrage between short-term cargoes and legacy contract commitments. Japanese utilities demonstrate the lowest price sensitivity, locking in term structures regardless of spot volatility, while Indian power generators exhibit the highest elasticity.
Supply Chain Analysis
Strategic stockpiling preferences dominate Asian utility procurement as Japan's METI enforces storage filling mandates and South Korea's Ministry of Trade conditions import licenses on supply security metrics. Qatar, South Korea, and Japan concentrate specialized LNG carrier construction and subsea compression manufacturing capacity. Raw material dependencies center on nickel-alloy cryogenic steel, advanced composite insulation systems, and high-pressure turbine components. Single-source vulnerability concentrates in directional drilling service providers with North Field West-class reservoir navigation capabilities. Distribution runs through Ras Laffan Industrial City's liquefaction trains to dedicated Q-Flex and Q-Max vessel loading terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced directional drilling expertise scarcity concentrates among limited service providers, compressing project execution timelines and inflating contractor qualification thresholds for North Field West development.
For Market Incumbents: Secure long-term partnerships with QatarEnergy's local content framework to defend position against emerging Asian EPC contractors. Anchor carbon capture integration capabilities to preserve European term contract access under EU methane monitoring frameworks. Prioritize Ras Laffan facility upgrade contracts that interface legacy sour gas treatment with new emission monitoring architectures. For New Entrants and Emerging Players: EU Carbon Border Adjustment Mechanism certification fast-track offers entry pathway for lower-carbon cargo verification specialists. Target India's underpenetrated coastal generation corridor where spot price arbitrage has fragmented incumbent monopoly positions. Position through Gujarat State Petroleum Corporation's third-party terminal access mandates as unified tariff regulations fragment legacy contract structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with multi-decade QatarEnergy maintenance contracts and carbon capture technology licensing. Long-term viability centers on contractors with demonstrated subsea compression deployment and continuous emission monitoring system integration. Acquisition focus should target directional drilling specialists with North Field-class reservoir navigation capabilities. Watch EU methane regulation delegated acts as inflection indicator for certified cargo premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Preserves European term contract access under EU methane monitoring frameworks. |
| Subsea Compression Deployment | Enables North Field West reservoir pressure maintenance without surface facility expansion. |
| Long-term Offtake Restructuring | Aligns Qatari supply security with Indian coastal generator spot arbitrage preferences. |
| Specialized Drilling Capacity Expansion | Addresses bottleneck risk for reservoir sections inaccessible through vertical approaches. |
| EU Certification Program | Commands premium positioning as European utilities reconfigure procurement specifications. |
Study Parameters
Cross-validation between primary interviews with LNG trading desk heads, EPC project directors, and utility procurement officers and secondary validation through IEA gas market reports, EIA LNG export databases, and QatarEnergy project disclosure filings anchors the qualitative findings. Bottom-up triangulation across liquefaction train capacity announcements and top-down reconciliation through customs trade flow data ensures volume integrity. Primary fieldwork with Ras Laffan Industrial City contractors and Asian utility fuel planning departments informs operational benchmark calibration.
Sensitivity analysis around carbon border adjustment implementation timelines and North Field East commissioning schedules tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, extraction versus processing technology intensity, application by customer scale, and end-user infrastructure proximity. CAGRs derive from production capacity buildout trajectories, term contract renewal patterns, and spot-to-term price spread elasticity estimates. Industry-specific inputs incorporate IMO bunker fuel regulation phase-in schedules and EU methane delegated act compliance cost curves.
Decision-makers should treat outputs as directional under sustained Asian LNG demand growth and QatarEnergy megaproject execution timelines; material deviation would warrant model refresh. Forecasts incorporate assumptions around carbon certification premium persistence and specialized drilling service provider capacity expansion. Revision becomes warranted when EU Carbon Border Adjustment Mechanism coverage thresholds cross implementation phases or North Field West subsea compression deployment encounters technical delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil Hose Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Drilling Services Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Sudan Oil and Gas Market