
 Downhole Drilling Tools Market | 2026-2036
Downhole Drilling Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Downhole Drilling Tools Market Analysis
Modular toolstring configurations is rebalancing procurement patterns across exploration portfolios. Schlumberger leverages integrated drilling and evaluation packages to anchor premium positions in directional services. Halliburton sustains manufacturing scale across polycrystalline diamond compact bit lines. NOV Inc. competes through vertical control over top-drive and downhole motor supply chains.
Downhole drilling tools encompass drill bits, reamers, positive displacement motors, and measurement-while-drilling assemblies engineered to withstand bottom-hole temperatures exceeding 150°C and pressures above 20,000 psi, primarily serving hydrocarbon extraction and mineral resource recovery. Drilling bits generates the deepest margin pools given material intensity in matrix-body and steel-body PDC designs. Directional drilling technology leads adoption curves as operators push lateral extensions beyond 15,000 feet in unconventional reservoirs. Smart technology integration represents the fastest-expanding segment, embedding real-time vibration sensing and automated weight-on-bit modulation.
API Specification Q2 and ISO 13628-7 govern material traceability and pressure-containing performance for tools deployed in subsea and high-pressure high-temperature environments, directly shaping supplier qualification timelines and capital allocation. The EPA's methane emissions standards under the Inflation Reduction Act intensify scrutiny of drilling efficiency, rewarding tools that reduce non-productive time and repeated tripping. Stakeholders must monitor how rotary steerable system patents expire and whether mining applications in copper and lithium pegmatites absorb excess directional drilling capacity from hydrocarbon slowdowns.
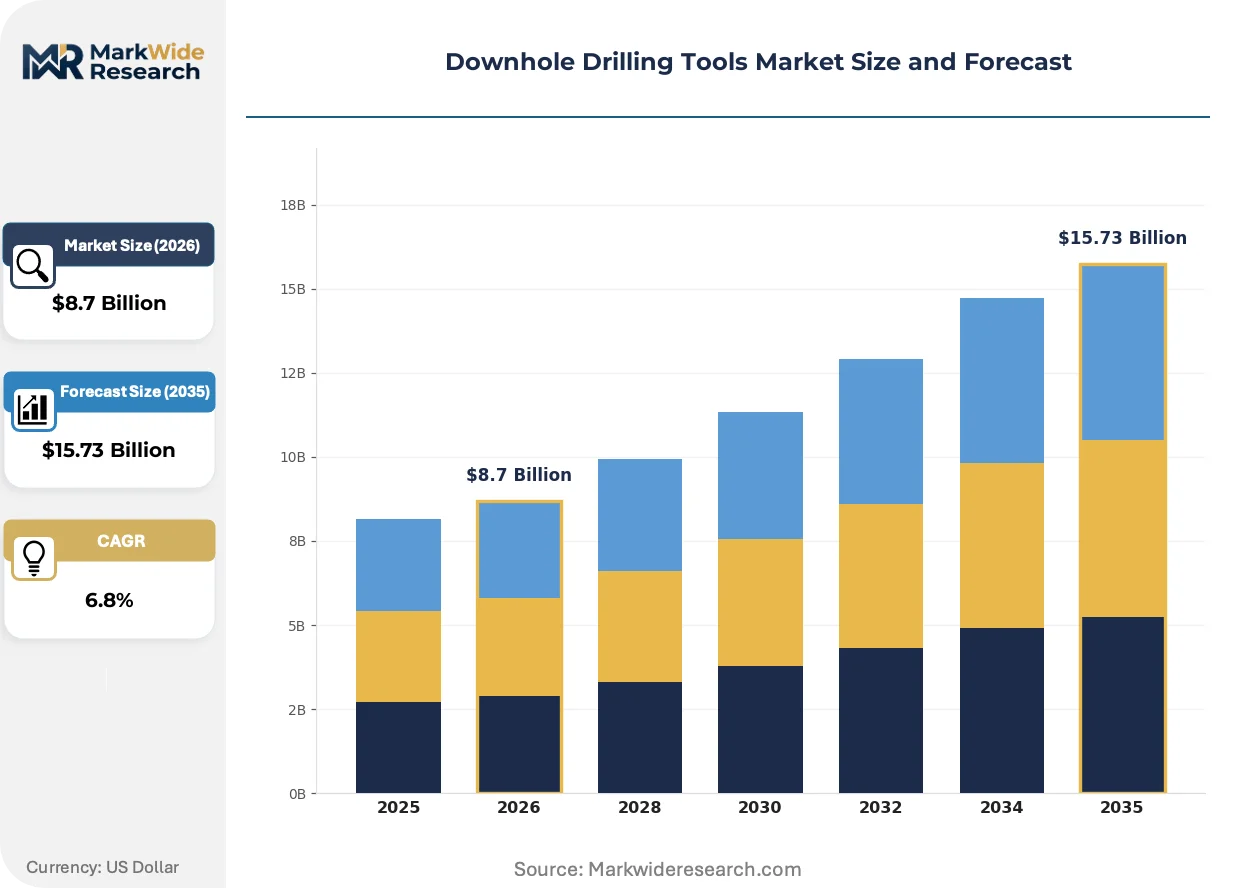
Market Dynamics
Rotary steerable system patents are expiring, breaking Schlumberger's and Halliburton's two-decade duopoly on closed-loop directional drilling and forcing incumbents to defend premium positions through integrated service bundling rather than proprietary hardware lock-in.
Growth Catalysts
- Permian Basin lateral extension:West Texas and southeastern New Mexico operators now drill laterals exceeding 15,000 feet, creating demand for drill bits and motors rated beyond 300 rotating hours.
- EPA methane regulations:The Inflation Reduction Act's emissions standards reward tools that cut non-productive time and reduce repeated tripping, directly favoring automated weight-on-bit modulation systems.
- Deepwater basin reactivation:Unconventional operators in Brazil's pre-salt and Guyana's Stabroek block are expanding rotary steerable adoption for high-angle wells in salt-laden formations.
Market Restraints
- Tungsten carbide supply concentration:Over 70% of matrix-body PDC substrate material originates from Chinese processors, exposing bit manufacturers to export restriction volatility.
- API Q2 certification timelines:The 18-24 month qualification protocol for subsea completion equipment delays new entrant commercialization and locks procurement to incumbent suppliers.
- Geothermal drilling substitution:Closed-loop binary systems and enhanced geothermal projects compete for directional drilling capacity, diverting motor and RSS manufacturing lines from hydrocarbon applications.
Strategic Opportunities
- Copper and lithium pegmatite mining:Hard-rock mineral extraction in Chile's Atacama and Australia's Pilbara requires directional steering tools originally developed for shale, absorbing excess oilfield capacity.
- Real-time vibration sensing convergence:Integration of MEMS accelerometers with mud-pulse telemetry creates predictive maintenance revenue streams independent of day-rate drilling contracts.
- ISO 13628-7 compliance services:Pressure-containing performance verification for high-pressure high-temperature environments opens consulting and recertification revenue adjacent to hardware sales.
Industry Challenges
- Measurement-while-drilling firmware integration:Legacy toolstrings from 2015-2019 vintage lack API-compatible data protocols, forcing operators into costly fleet standardization or hybrid telemetry architectures.
- Polycrystalline diamond cutter bonding expertise:The specialized metallurgy required for 150°C+ thermal stability faces a generational knowledge gap as senior materials scientists exit the workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Downhole Drilling Tools Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Bits, Reamers, Motors, Tools Technology: Directional Drilling, Rotary Steerable, Managed Pressure, Smart Technology End User: Oil & Gas, Mining, Construction, Geothermal Application: Exploratory Drilling, Production Drilling, Wellbore Cleanup, Workover |
| Companies Covered | Schlumberger, Boart Longyear, Sandvik AB, Halco Rock Tools, Rockmore International, Epiroc AB, Halliburton, NOV Inc., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Downhole Drilling Tools Market Emerging Trajectories
Digital thread architectures are collapsing the traditional separation between downhole sensing and surface analytics, embedding machine learning at the bit to compress decision cycles from hours to seconds.
High-temperature electronics packaging is electrifying measurement-while-drilling reliability in geothermal and deep gas applications. Operators in Indonesia's Java basin and Turkey's Aydin province now deploy these systems at 200°C bottom-hole conditions. The technology is electrifying competitive differentiation away from mechanical durability toward silicon thermal tolerance.
The EPA's methane emissions standards under the Inflation Reduction Act now tie drilling efficiency metrics to federal lease eligibility. Operators must demonstrate reduced venting through automated kick detection and managed pressure drilling. Deepwater Gulf of Mexico projects face the steepest compliance ramps, with majors rewriting tool specifications to embed continuous flow monitoring.
Integrated drilling and evaluation packages are displacing standalone tool procurement in North American unconventional plays. E&P companies now contract for guaranteed rate-of-penetration outcomes rather than renting equipment. This reconfiguration concentrates buying power with supermajors in the Permian and Bakken, squeezing independent directional drilling providers into niche geothermal or mining verticals.
Downhole Drilling Tools Market Segmentation
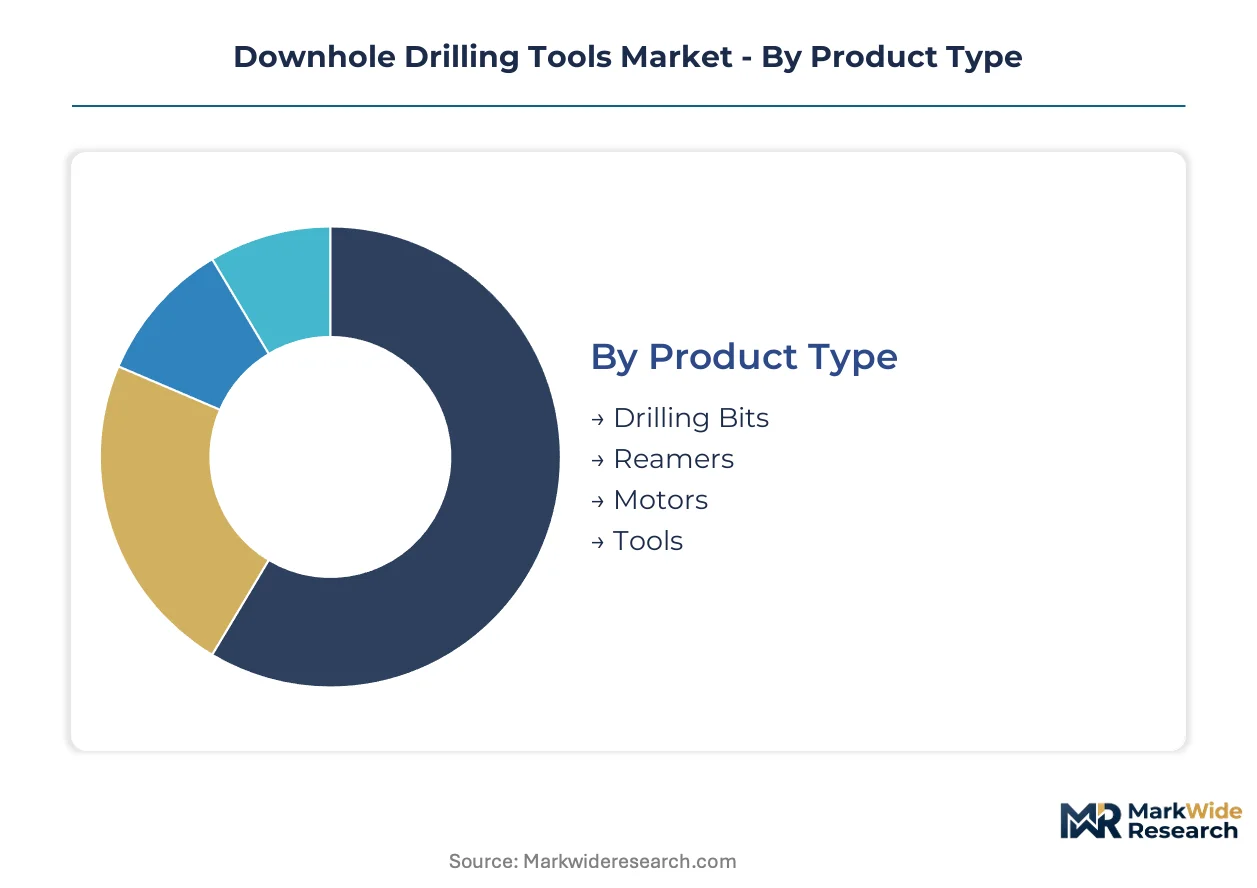
Downhole drilling tools fragment across four dimensions that reshape procurement economics. Product type determines capital intensity and replacement cadence. Technology tier separates premium service bundling from commodity rental rates.
Product Type:
Buyers differentiate by wear-part replacement frequency versus capital asset longevity.
- Drilling Bits:Matrix-body and steel-body PDC designs dominate unconventional plays. Permian Basin operators now specify 300+ rotating hour ratings for 15,000-foot laterals, with tungsten carbide substrate sourcing concentrated among Chinese processors.
- Motors:Positive displacement motors and turbodrills convert hydraulic energy to mechanical rotation. Deepwater Brazil pre-salt deployments favor high-torque configurations for salt-laden formations, with power sections requiring elastomer compounds rated beyond 150°C.
- Reamers:Underreamer and hole opener tools stabilize wellbore gauge in extended-reach applications.
- Tools:Jar mechanisms, shock subs, and stabilizers complete the bottom-hole assembly.
Drilling bits generate the deepest margin pools; motors are gaining share fastest in directional service bundles.
Technology:
Patent expiration status now governs competitive access and pricing power.
- Directional Drilling:Conventional mud motors with bent-housing adjustable kickoff points serve standard lateral applications. Bakken operators still deploy these for sub-10,000 foot laterals where rotary steerable economics fail.
- Rotary Steerable:Closed-loop systems eliminate sliding mode inefficiencies. Guyana Stabroek block developments specify these for high-angle wells in unconsolidated sands, though patent expirations are eroding incumbent lock-in.
- Managed Pressure:Annular pressure control systems mitigate kick risks in narrow margin drilling.
- Smart Technology:Real-time vibration sensing and automated weight-on-bit modulation compress decision cycles from hours to seconds.
Directional drilling anchors volume today; smart technology is expanding most quickly as EPA methane regulations reward efficiency gains.
End User:
Resource extraction economics determine tool specification tolerance and service intensity.
- Oil & Gas:Hydrocarbon operators consume the majority of premium tool hours. West Texas independents now contract for guaranteed rate-of-penetration outcomes rather than equipment rental, concentrating buying power with supermajors.
- Mining:Hard-rock mineral extraction in Chile's Atacama and Australia's Pilbara absorbs excess directional drilling capacity. Copper and lithium pegmatite projects repurpose shale-optimized steering tools for vertical crater retreat and longhole stoping.
- Geothermal:Closed-loop binary and enhanced geothermal systems compete for manufacturing line capacity.
- Construction:Foundation drilling and tunnel boring applications utilize simplified toolstring configurations.
Oil and gas commands premium pricing today; mining is climbing the fastest as hydrocarbon investment cycles soften.
Application:
Well lifecycle stage dictates tool reliability requirements and non-productive time penalties.
- Exploratory Drilling:Wildcat and appraisal wells demand maximum directional flexibility. Deepwater Gulf of Mexico projects face steep EPA methane compliance ramps, rewriting tool specifications to embed continuous flow monitoring.
- Production Drilling:Development well programs prioritize repeatability and fleet standardization. Legacy 2015-2019 vintage measurement-while-drilling toolstrings lack API-compatible data protocols, forcing costly hybrid telemetry architectures.
- Wellbore Cleanup:Scrapers, magnets, and junk baskets remove debris prior to completion.
- Workover:Intervention tools restore or enhance production from existing wells.
Production drilling leads volumes today; exploratory drilling shows the steepest expansion trajectory as pre-salt and pre-salt analog basins reactivate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The downhole drilling tools industry traces its modern scale to the Permian Basin of West Texas, where extended-reach horizontal drilling first demanded purpose-built directional systems. Today, demand clusters follow unconventional hydrocarbon geology and mining frontiers rather than manufacturing geography.
United States
West Texas and southeastern New Mexico operators drill laterals exceeding 15,000 feet, consuming drill bits rated for 300+ rotating hours. The EPA's methane emissions standards under the Inflation Reduction Act now tie drilling efficiency to federal lease eligibility. Midland-Odessa anchors the densest concentration of directional drilling service capacity worldwide.
Brazil
Pre-salt basin reactivation drives rotary steerable adoption for high-angle wells through salt-laden formations. The national petroleum regulator, ANP, mandates local content thresholds that reshape procurement toward domestic assembly partnerships. Macaé and Rio de Janeiro host the primary service contractor clusters supporting deepwater fleet operations.
China
Shale gas development in Sichuan-Chongqing and tight oil pilots in Xinjiang absorb polycrystalline diamond compact imports despite domestic bit manufacturing scale. The Ministry of Ecology and Environment enforces dual carbon goals that constrain drilling permit issuance in high-emission provinces. Chongqing's manufacturing corridor supplies tungsten carbide substrates for matrix-body PDC designs.
Canada
Montney and Duvernay shale plays in Alberta and British Columbia require high-torque motors for extended-reach gas wells. The Canadian Environmental Protection Act governs venting and fugitive emissions standards that accelerate automated weight-on-bit system deployment. Calgary concentrates headquarters functions for North American unconventional service divisions.
Australia
Pilbara iron ore and Atacama-adjacent lithium exploration repurposes shale-optimized directional tools for hard-rock mining. The Therapeutic Goods Administration does not regulate drilling equipment; state-level mining safety authorities govern tool certification. Perth anchors Asia-Pacific service coordination for geothermal and mining diversion projects.
Downhole Drilling Tools Market Vendor Landscape
The competitive structure tilts toward integrated service bundling rather than standalone hardware provision. Patent expiration on rotary steerable systems has eroded two-decade duopoly protections, forcing incumbents to defend premium positions through outcome-based contracts and guaranteed rate-of-penetration commitments. Three archetypes dominate: full-service oilfield conglomerates with captive manufacturing, specialized directional drilling contractors, and mining-focused hard-rock tool fabricators. Consolidation pressure intensifies as supermajors concentrate procurement power in the Permian, while technology licensing agreements proliferate among second-tier motor and bit specialists.
Within the integrated service tier, Schlumberger, Halliburton, and NOV Inc. occupy positions that exemplify contrasting strategic postures. Schlumberger anchors premium directional services through integrated drilling and evaluation packaging. Halliburton sustains manufacturing scale across polycrystalline diamond compact bit lines. NOV Inc. competes through upstream control over top-drive and downhole motor supply chains. Among mining-specialized fabricators, Boart Longyear and Epiroc AB represent hard-rock extraction expertise repurposed from hydrocarbon tool heritage.
| Leading Market Players |
|---|
| Schlumberger |
| Boart Longyear |
| Sandvik AB |
| Halco Rock Tools |
| Rockmore International |
| Epiroc AB |
| Halliburton |
| NOV Inc. |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Tungsten carbide powder indices cascade through matrix-body PDC bit manufacturing into three distinct procurement tiers: API Q2-certified subsea systems command premium day-rate multiples, standard directional packages serve Permian Basin independents on fixed-term contracts, and economy-grade motors compete for spot-market mining redeployment. Cost compression in the standard tier intensifies as Chinese substrate processors consolidate pricing power, forcing North American fabricators to absorb margin erosion or surrender volume to integrated service bundlers.
Pricing Analysis
Outcome-based drilling contracts with guaranteed rate-of-penetration commitments now dominate North American unconventional plays, displacing traditional equipment rental models. Price differentiation rests on certification grade—ISO 13628-7 and API Q2 tiers separate subsea-qualified suppliers from land-only competitors—and vertical integration depth, with captive tungsten carbide sourcing insulating integrated conglomerates from spot volatility. Pricing pressure stems from patent expiration on rotary steerable systems, eroding two-decade hardware lock-in premiums. Supermajors in West Texas exhibit lowest price sensitivity, while Bakken independents and Australian mining contractors remain most exposed to spot-rate fluctuations.
Supply Chain Analysis
ANP local-content mandates in Brazil and analogous domestic-assembly requirements in China's Sichuan-Chongqing shale corridor are reshaping sourcing toward in-country fabrication partnerships. Manufacturing gravity centers on China for tungsten carbide substrates, the United States for elastomer-compound power sections, and Norway for high-pressure subsea control systems. Raw material dependencies draw from Chilean copper for electrical windings, Saudi petrochemical feedstocks for specialized polymers, and Australian rare earth elements for high-temperature magnet assemblies. Single-source vulnerability concentrates in Chinese tungsten carbide processing, where export permit volatility exposes bit manufacturers to supply interruption. Distribution runs through integrated oilfield service conglomerates that bundle hardware with directional engineering, compressing standalone tool distributors into aftermarket niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The downhole drilling tools market functions as a stable compounder anchored by irreplaceable capital intensity in extended-reach hydrocarbon extraction, with replacement demand for 300-hour-rated bits and high-torque motors generating predictable revenue streams regardless of commodity cycle positioning.
For Market Incumbents: Anticipate rotary steerable patent expiration by defending premium positions through integrated service bundling rather than proprietary hardware lock-in. Incumbents should deepen backward integration into tungsten carbide substrate processing to neutralize Chinese supply concentration risk, while accelerating API Q2 certification investments to extend qualification timelines that delay new entrant commercialization. The priority lever sits in outcome-based contract structuring that ties pricing to guaranteed rate-of-penetration performance, displacing commoditized equipment rental. For New Entrants and Emerging Players: Direct-to-mining sales channels offer the most penetrable route for directional drilling capacity diversion, with Chilean copper and Australian lithium pegmatite projects absorbing excess oilfield manufacturing lines. White-space targets concentrate in geothermal drilling applications for Indonesia's Java basin and Turkey's Aydin province, where high-temperature electronics packaging requirements favor specialized entrants over legacy hydrocarbon-optimized portfolios. A go-to-market angle through ISO 13628-7 compliance consulting services opens revenue adjacent to hardware sales without requiring full manufacturing scale. For Investors and Strategic Acquirers: Asymmetric upside sits with hard-rock mining tool fabricators repurposing shale-optimized directional heritage for copper and lithium extraction, as hydrocarbon investment cycles soften while mineral electrification demand accelerates. Long-term viability favors acquisition targets with captive tungsten carbide sourcing or established API Q2 certification pipelines rather than pure-play directional service contractors exposed to supermajor procurement concentration. The signal to watch is rotary steerable system licensing agreement proliferation, which indicates patent cliff transition velocity and margin compression timing for hardware-centric incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Processing | Neutralizes Chinese substrate concentration risk for matrix-body PDC bit manufacturers. |
| API Q2 Certification Pipeline Investment | Extends 18-24 month qualification timelines that lock procurement to incumbent suppliers. |
| Outcome-Based Drilling Contract Expansion | Concentrates buying power with supermajors while squeezing independent directional providers. |
| Geothermal and Mining Capacity Diversion | Absorbs excess oilfield manufacturing lines as hydrocarbon investment cycles soften. |
| Real-Time Vibration Sensing Platform Development | Creates predictive maintenance revenue streams independent of day-rate drilling contracts. |
Methodological Framework
Multiple input streams—structured interviews with directional drilling service executives, procurement leads at Permian Basin operators, and regulatory affairs specialists at ANP and EPA—were reconciled against secondary validation from API certification databases, ISO standard revision records, and customs trade data for tungsten carbide substrate flows. Primary fieldwork captured bottom-up perspective from rig-site engineers and maintenance directors at extended-reach operations, while top-down triangulation incorporated SEC filings from integrated oilfield conglomerates and capital expenditure disclosures from supermajor E&P divisions. The synthesis anchored quantitative modeling in operational reality rather than reported financials alone.
Cross-referencing historical replacement rates for 300-hour-rated bit classifications against panel-based input from drilling contractors and mining equipment procurement teams shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user industry, and well lifecycle stage, with regional regulatory clusters capturing EPA methane compliance ramps and ANP local-content thresholds. CAGRs were derived from equipment replacement cadence curves and directional drilling intensity metrics per lateral foot, incorporating patent expiration velocity for rotary steerable systems and geothermal project pipeline development as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for closed-loop automated weight-on-bit modulation or enhanced geothermal system scaling would alter the outlook for motor and RSS manufacturing line allocation. Forecasts reflect assumptions regarding Chinese tungsten carbide export policy continuity, API Q2 certification timeline stability, and supermajor procurement consolidation in West Texas. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sucker Rod Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Natural Gas Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Sidetracking Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Oil and Gas Data Management Market