
 United States Automotive Service Market | 2026-2036
United States Automotive Service Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Service Market Outlook
The capital-intensity divergence between national quick-lube networks and neighborhood repair garages is reorganizing competitive dynamics across the United States automotive service landscape. Jiffy Lube International, Inc. leverages standardized bay designs and captive supply agreements to sustain throughput rates above independent benchmarks. Monro Inc. anchors its Northeast footprint through tire-installation capacity and brake-service specialization. Christian Brothers Automotive differentiates via customer-facing transparency protocols and fleet-account development in Sun Belt metros.
United States automotive service encompasses mechanical and electrical interventions performed on in-use vehicles to restore operational safety, emissions compliance, or comfort specifications, spanning oil changes, brake replacement, diagnostic scanning, and ADAS recalibration with torque tolerances and software versioning as critical quality parameters. Scheduled maintenance occupies the largest revenue pool due to manufacturer-prescribed intervals and warranty retention requirements, while mobile units represent the fastest-expanding channel as fleet operators prioritize uptime over facility visits. Independent garages compete on labor-rate arbitrage but face margin compression from proprietary scan-tool costs and OEM parts-program restrictions.
NHTSA recall enforcement, EPA emissions-testing protocols, and state-level safety inspection regimes collectively expand the addressable service base by mandating corrective action before registration renewal. The FTC's aftermarket parts guidelines and right-to-repair legislative momentum in multiple states are reshaping parts-channel access and diagnostic-data availability for non-dealership technicians. Stakeholders must monitor state-level right-to-repair enactments and OEM telematics subscription models to anticipate whether independent channels retain diagnostic parity with authorized service centers.
Market Dynamics
NHTSA recall mandates and EPA emissions compliance obligations are expanding mandatory service volumes across the United States, while telematics-enabled predictive maintenance is compressing traditional scheduled service intervals for fleet operators.
Growth Catalysts
- Fleet Preventive Maintenance Expansion:Commercial vehicle operators in Texas, California, and Florida are lengthening service contracts to minimize downtime and extend asset lifecycles.
- Right-to-Repair Legislative Momentum:State-level enactments in multiple jurisdictions are expanding diagnostic-data access for independent technicians beyond dealership restrictions.
- ADAS Recalibration Mandates:Windshield replacement and collision repair now require camera and sensor recalibration, creating incremental service pull-through.
Market Restraints
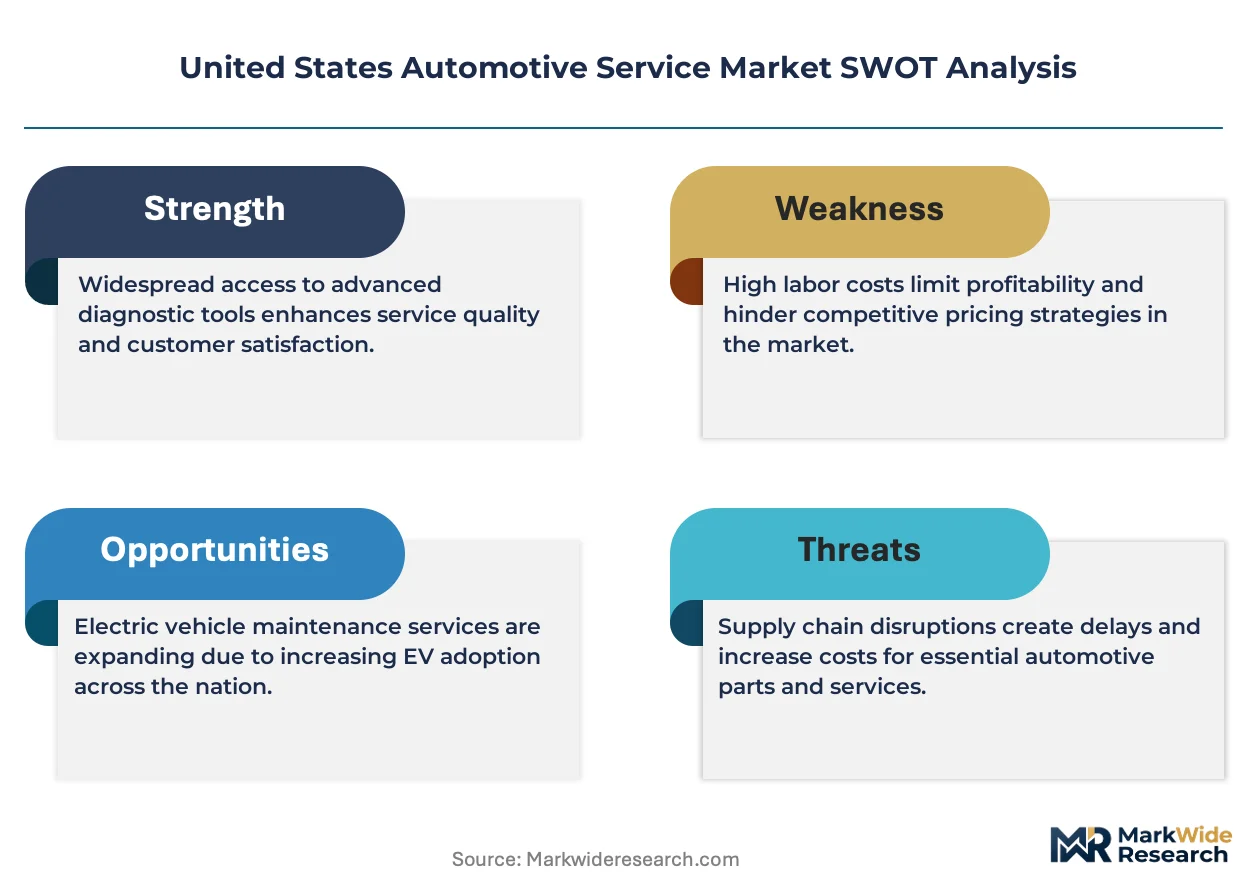
- Proprietary Scan-Tool Cost Burden:OEM-specific diagnostic equipment and software subscriptions compress margins for independent garages.
- Parts-Program Restrictions:Manufacturer-authorized parts channels limit sourcing flexibility for non-affiliated service centers.
- Technician Labor Pool Constraints:Diesel and high-voltage powertrain specializations face acute training pipeline gaps.
Strategic Opportunities
- Mobile Service Channel Development:On-location maintenance units address fleet uptime priorities without facility throughput limits.
- Telematics-Subscription Integration:OEM connected-vehicle platforms offer predictive service alerts that independent channels can capture through data partnerships.
- Sun Belt Metro Concentration:Vehicle registration density in Florida and Texas metros supports scaled fleet-account development.
Industry Challenges
- High-Voltage Certification Timelines:EV battery and powertrain service requires specialized technician credentials that training programs have not scaled.
- ADAS Calibration Infrastructure:Dynamic testing bays and target alignment systems demand capital outlays that smaller operators struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Service Market |
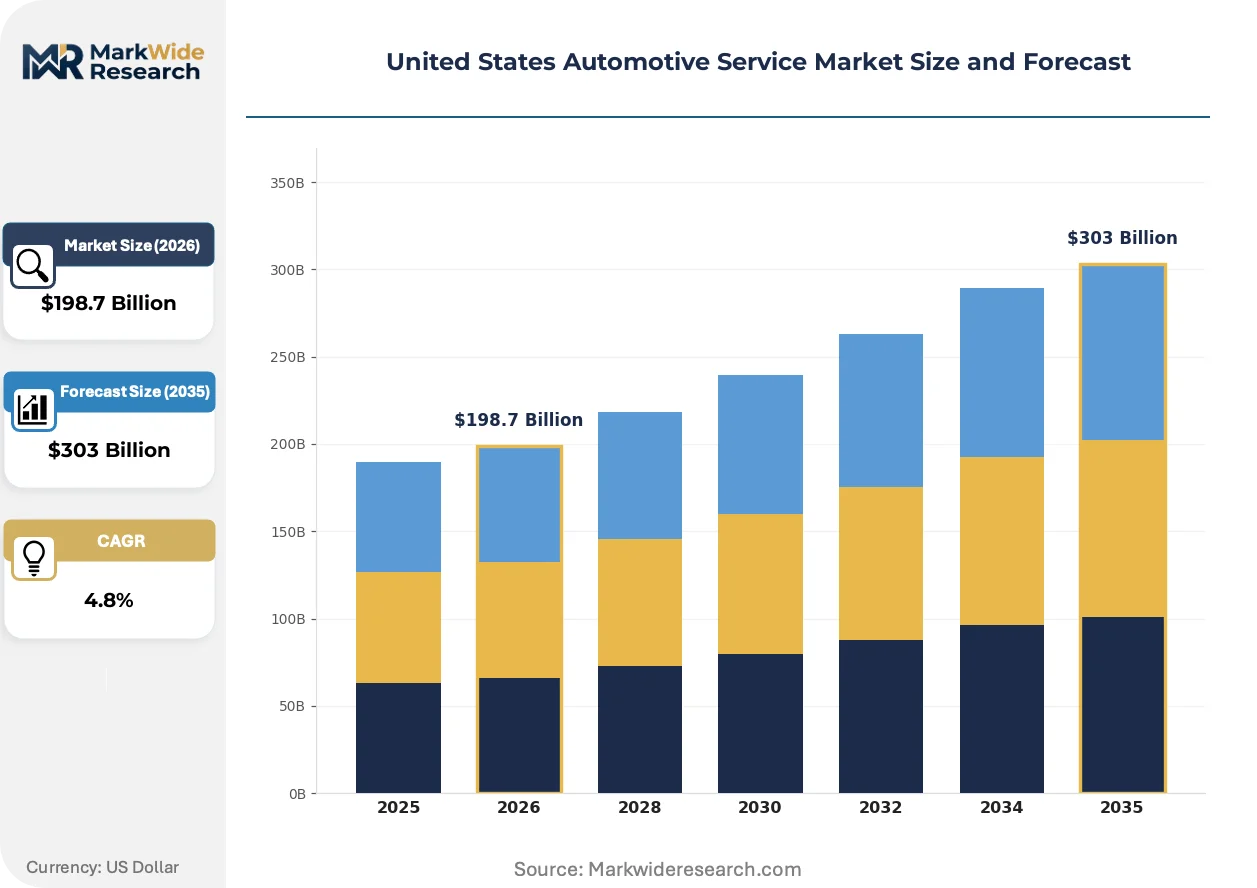
| Market Size in 2026 | $198.7 Billion |
| Market Size in 2035 | $303 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Scheduled Maintenance, Repair Services, Tire Services, Electrical Services End User: Individual Consumers, Fleet Operators, Dealerships, Insurance Companies Vehicle Type: Passenger Cars, Light Trucks, Heavy-Duty Vehicles, Motorcycles Service Channel: Authorized Service Centers, Independent Garages, Mobile Units, Online Platforms |
| Companies Covered | Midas International, LLC, Safelite Group, Firestone Complete Auto Care, Valvoline Instant Oil Change, Pep Boys, Jiffy Lube International, Inc., Monro Inc., Christian Brothers Automotive, Meineke Car Care Centers, LLC., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Service Market Strategic Shifts
Diagnostic and maintenance workflows are splitting between connected-vehicle predictive platforms and traditional interval-based service models, forcing channel operators to recalibrate capacity planning and customer retention strategies.
Over-the-air software updates and remote diagnostic capabilities are bifurcating the service market into telematics-enabled predictive interventions and physical bay-based repairs. Fleet operators with centralized maintenance management systems are adopting remote monitoring fastest, compressing demand for routine fluid and filter services while expanding specialized electrical and calibration work.
NHTSA safety recall enforcement protocols and EPA emissions-testing requirements are mandating corrective action before registration renewal, expanding the addressable service base. These obligations fall heaviest on older vehicle populations in states with inspection regimes, pushing independent garages to invest in emissions-testing equipment and recall-parts inventory.
Service procurement is consolidating through fleet-management companies and commercial lessors that negotiate national maintenance contracts. This channel shift displaces transactional retail service for commercial vehicles, concentrating volume with operators capable of multi-location reporting and standardized quality protocols across Sun Belt metros.
United States Automotive Service Market Segmentation
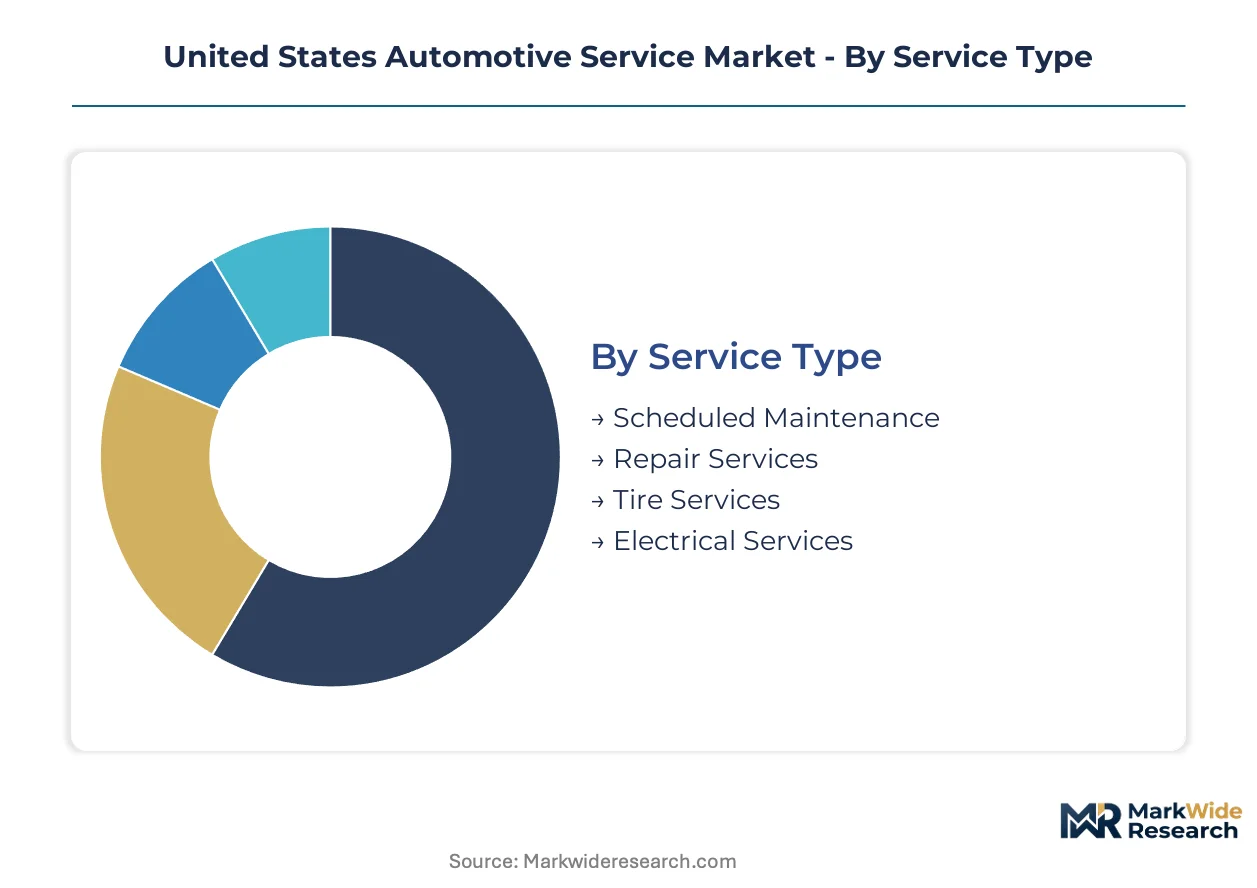
Service segmentation in the United States automotive market reveals divergent margin structures and substitution vulnerabilities across maintenance modalities. Fleet procurement centralization and telematics-enabled predictive platforms are compressing demand for traditional scheduled services while elevating specialized electrical and calibration segments.
Service Type:
Substitution pressure from connected-vehicle diagnostics and over-the-air updates weighs most heavily on fluid-based maintenance categories, while sensor-dependent services gain defensive positioning.
- Scheduled Maintenance:Oil changes, fluid exchanges, and filter replacements follow manufacturer-prescribed intervals tied to warranty retention requirements. Texas, California, and Florida fleet operators are compressing traditional service windows through telematics-enabled condition monitoring.
- Repair Services:Mechanical interventions address component failures, wear items, and collision damage with torque specifications and OEM parts compliance as critical quality gates. Independent garages compete on labor-rate arbitrage but face margin pressure from proprietary scan-tool costs and recall-parts inventory obligations.
- Tire Services:Installation, rotation, balancing, and alignment work concentrates with operators possessing mount/dismount capacity and road-force balancing equipment.
- Electrical Services:Battery replacement, alternator repair, and wiring harness diagnostics address escalating electronic content in modern vehicle architectures.
Scheduled Maintenance retains volume leadership; Electrical Services holds the steepest expansion curve.
End User:
Customer-type segmentation maps directly to contract structure complexity and price sensitivity dispersion across the United States market.
- Individual Consumers:Retail service demand concentrates on convenience proximity and transparent pricing protocols, with Sun Belt metros showing highest per-capita service frequency due to climate-induced wear factors.
- Fleet Operators:Commercial vehicle lessors and logistics companies negotiate national maintenance contracts requiring multi-location reporting, standardized quality protocols, and uptime guarantees. NHTSA recall mandates and EPA emissions compliance obligations expand mandatory service volumes for aging fleet assets.
- Dealerships:Authorized service centers leverage warranty retention requirements and proprietary diagnostic access to capture high-margin electrical and ADAS calibration work.
- Insurance Companies:Claims-driven service procurement directs collision repair and total-loss assessments through approved shop networks with direct billing arrangements.
Fleet Operators command the largest contract values; Individual Consumers represent the most fragmented acquisition channel.
Vehicle Type:
Powertrain electrification and ADAS penetration rates vary sharply across vehicle classes, reshaping service mix requirements.
- Passenger Cars:Sedans and hatchbacks face accelerating service interval compression as hybrid powertrains reduce fluid-change frequency while expanding high-voltage system maintenance needs.
- Light Trucks:Pickups and SUVs dominate Texas and Florida registrations, supporting scaled tire-installation and brake-service capacity in these markets.
- Heavy-Duty Vehicles:Commercial trucks and buses require specialized diesel and high-voltage technician credentials that training programs have not scaled to meet demand.
- Motorcycles:Two- and three-wheeled vehicles occupy a niche service channel with seasonal demand concentration and limited proprietary diagnostic barriers.
Light Trucks anchor regional revenue concentration; Heavy-Duty Vehicles face the most acute technician certification gaps.
Service Channel:
Channel selection determines diagnostic-data access, parts-program flexibility, and capital-intensity requirements for United States operators.
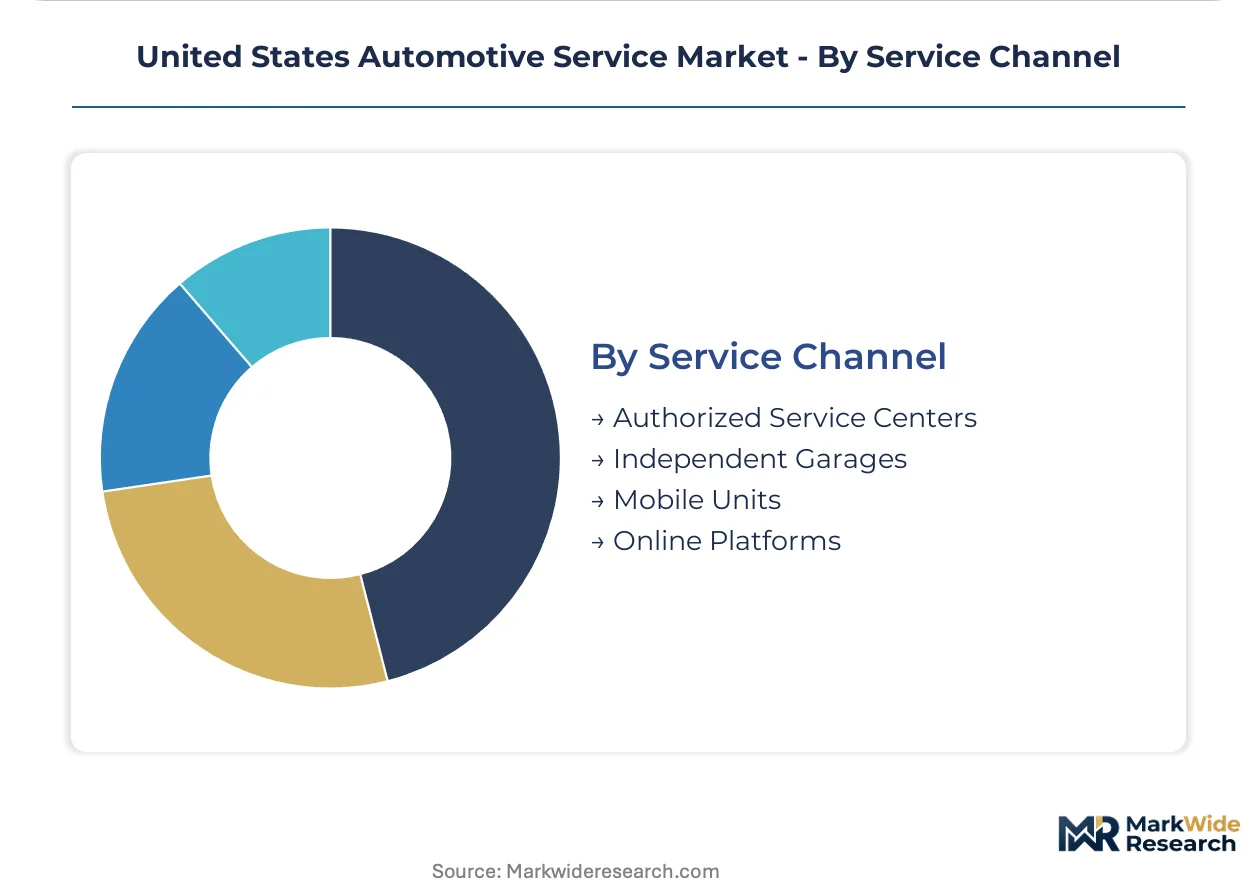
- Authorized Service Centers:Dealership-affiliated facilities retain exclusive access to OEM software updates, warranty reimbursement, and recall-parts allocation under manufacturer service agreements.
- Independent Garages:Neighborhood repair shops compete on labor-rate arbitrage and relationship-based customer retention, though FTC aftermarket parts guidelines and state-level right-to-repair enactments are reshaping diagnostic-data parity.
- Mobile Units:On-location maintenance addresses fleet uptime priorities without facility throughput limits, expanding fastest in Texas and California metro corridors with dense commercial vehicle registration.
- Online Platforms:Digital service marketplaces and telematics-subscription integrations offer predictive maintenance alerts, appointment scheduling, and remote diagnostic triage.
Authorized Service Centers maintain diagnostic parity; Mobile Units are expanding most quickly among fleet-facing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service consumption patterns across the United States diverge sharply between Sun Belt metros prioritizing fleet uptime and Rust Belt corridors managing aging vehicle populations through emissions compliance regimes.
Texas
Light truck registrations and oilfield fleet density drive preventive maintenance contract expansion. NHTSA recall mandates for heavy-duty vehicles apply stringent corrective timelines before commercial registration renewal. Dallas-Fort Worth and Houston anchor multi-location service networks serving logistics operators with standardized brake and tire protocols.
California
Zero-emission vehicle adoption and ADAS penetration elevate electrical service and sensor recalibration demand. EPA emissions-testing protocols and CARB compliance requirements mandate corrective action for older fleets. Los Angeles and San Francisco Bay Area metros concentrate mobile service units addressing fleet uptime priorities without facility constraints.
Florida
Climate-induced wear accelerates tire and brake service frequency among individual consumers and rental fleets. State safety inspection regimes expand mandatory service volumes for registration renewal. Miami and Tampa corridors support scaled fleet-account development through telematics-integrated maintenance management.
Michigan
Automotive manufacturing heritage sustains specialized powertrain service expertise for domestic OEM platforms. EPA emissions-testing obligations apply to aging vehicle populations in Detroit and Grand Rapids metro areas. Independent garages compete with dealership-affiliated centers for warranty-retention work on hybrid and emerging EV architectures.
Ohio
Interstate logistics corridors generate heavy-duty diesel service demand with acute technician certification gaps. NHTSA commercial vehicle safety mandates enforce brake and tire maintenance intervals. Cleveland and Columbus host regional fleet maintenance hubs negotiating national contracts with centralized reporting requirements.
United States Automotive Service Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the United States automotive service market. National quick-lube networks leverage standardized bay designs and captive supply agreements to sustain throughput advantages. Independent neighborhood garages compete on labor-rate arbitrage but face margin compression from proprietary diagnostic equipment costs. Dominant competitive moves include fleet-account consolidation through multi-location reporting capabilities and telematics-subscription partnerships for predictive maintenance alerts.
Within the national network tier, Jiffy Lube International, Inc. and Monro Inc. exemplify scale-driven operators with standardized protocols across dispersed footprints. Christian Brothers Automotive represents the transparency-focused archetype developing fleet relationships in Sun Belt metros. These entities anchor competitive positioning through diagnostic-data access negotiations and mobile service channel expansion rather than pure facility count.
| Leading Market Players |
|---|
| Midas International, LLC |
| Safelite Group |
| Firestone Complete Auto Care |
| Valvoline Instant Oil Change |
| Pep Boys |
| Jiffy Lube International, Inc. |
| Monro Inc. |
| Christian Brothers Automotive |
| Meineke Car Care Centers, LLC. |
| Others |
Value Chain & Pricing Dynamics
Long-term fleet service contracts lock in both parts allocation priority and labor-rate visibility across multi-year maintenance agreements. NHTSA recall mandates and EPA compliance obligations create non-discretionary demand that insulates pricing from cyclical softness.
Pricing Analysis
Extended service contracts generate the highest lifetime value through recurring revenue streams and captive parts consumption. Pricing stratifies across OEM-authorized, certified independent, and economy tiers based on diagnostic-data access and warranty backing. Cost compression in the independent tier is intensifying because proprietary scan-tool subscriptions and software licensing fees erode margin. Fleet operators show lowest price sensitivity due to uptime guarantees, while individual consumers drive the most aggressive labor-rate arbitrage.
Supply Chain Analysis
OEM-authorized parts distribution channels concentrate supply access for safety-critical components and ADAS calibration equipment. The United States aftermarket draws from Mexico for brake and exhaust components, Taiwan for electronic modules, and domestic remanufacturing for powertrain assemblies. Single-source vulnerability sits with telematics-enabled diagnostic platforms controlled by vehicle manufacturers. Distribution runs through national warehouse distributors, direct OEM programs, and captive supply agreements at quick-lube networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States automotive service market tracks a cyclical recovery pattern as fleet renewal cycles and aging vehicle populations expand mandatory maintenance obligations under federal safety mandates.
For Market Incumbents: Consolidate fleet-account relationships through multi-location reporting capabilities and standardized quality protocols across Sun Belt metros. Deepen diagnostic-data partnerships with telematics providers to maintain parity with OEM service centers. Acquire mobile service operators in Texas and California to capture uptime-prioritized commercial demand without facility throughput constraints. For New Entrants and Emerging Players: Anchor in high-voltage certification training programs to address acute EV power technician gaps before incumbent scale advantages harden. Target independent garage consolidation in Rust Belt corridors where emissions-testing mandates create captive service demand. Launch telematics-integrated maintenance management platforms that aggregate predictive alerts for fleet operators. For Investors and Strategic Acquirers: Capital is best deployed toward regional multi-location operators with fleet-contract density and ADAS calibration infrastructure already in place. Five-to-ten year viability hinges on diagnostic-data access parity with authorized channels. Monitor state-level right-to-repair enactments as the inflection signal for independent channel margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Service Channel Expansion | Captures fleet uptime priorities without facility throughput limits in Texas and California corridors. |
| ADAS Calibration Infrastructure Investment | Creates mandatory service pull-through from windshield replacement and collision repair mandates. |
| Telematics-Subscription Integration | Enables predictive maintenance alerts through data partnerships with OEM connected-vehicle platforms. |
| High-Voltage Technician Certification Programs | Addresses acute training pipeline gaps for EV battery and powertrain service demand. |
| Fleet-Account Consolidation | Concentrates volume with operators capable of multi-location reporting across Sun Belt metros. |
Study Parameters
The analysis maps scheduled maintenance, repair services, tire installation, and electrical diagnostics, each validated through fleet operations managers, independent garage owners, OEM service directors, and aftermarket parts distributors. Primary interviews triangulate with NHTSA recall databases, EPA emissions compliance filings, state vehicle registration records, and IHS Markit production data. Bottom-up service-volume estimates reconcile against top-down market sizing through expenditure-flow analysis.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework segments by service type, end-user category, vehicle class, and channel structure, with propulsion architecture and ADAS penetration as cross-cutting dimensions. CAGRs derive from trend-line extrapolation moderated by regulatory mandate timelines and fleet renewal cycle phasing. Forecast inputs incorporate technician certification scaling rates and telematics adoption curves by vehicle age cohort.
Material uncertainties — NHTSA rulemaking acceleration, state right-to-repair enactment timing, EV service interval compression — sit outside the modeled envelope. Forecasts reflect assumptions about diagnostic-data access continuity and recall-parts inventory availability. Practitioners should keep alternative scenarios live as OEM telematics subscription models and independent channel diagnostic parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Driver's License Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Retail Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
GCC Car Wash Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Car Subscription Market
Automotive Services
Global Car Wash Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Car Rental Business Market