
 Automotive Quality Service Market | 2026-2036
Automotive Quality Service Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Quality Service Market Analysis
Franchise service networks is rewriting competitive access across North America. Midas International leverages its company-owned and franchised locations to sustain coast-to-coast coverage. Caliber Collision anchors its position through specialized collision repair scale. Monro Inc. competes via tire and brake service concentration in the Northeast and Midwest corridors.
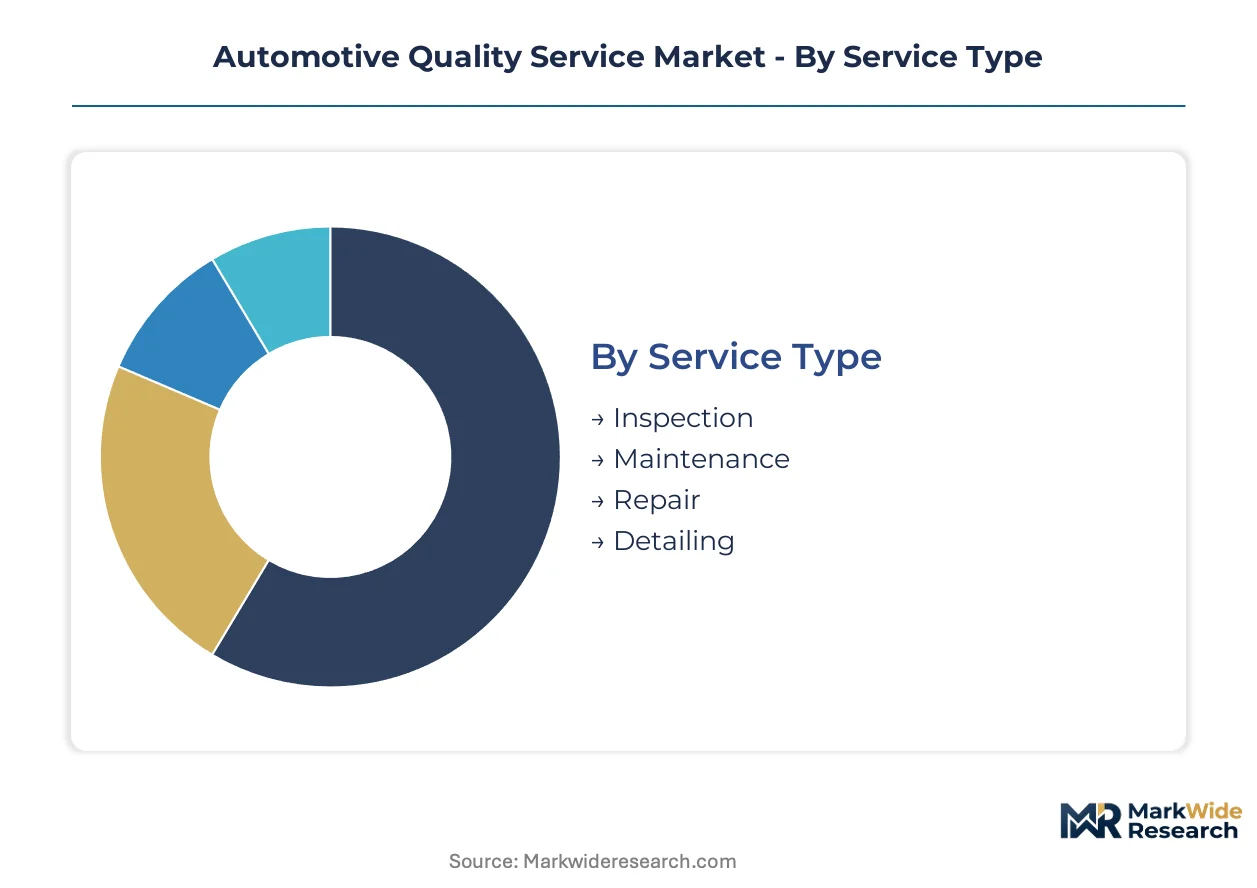
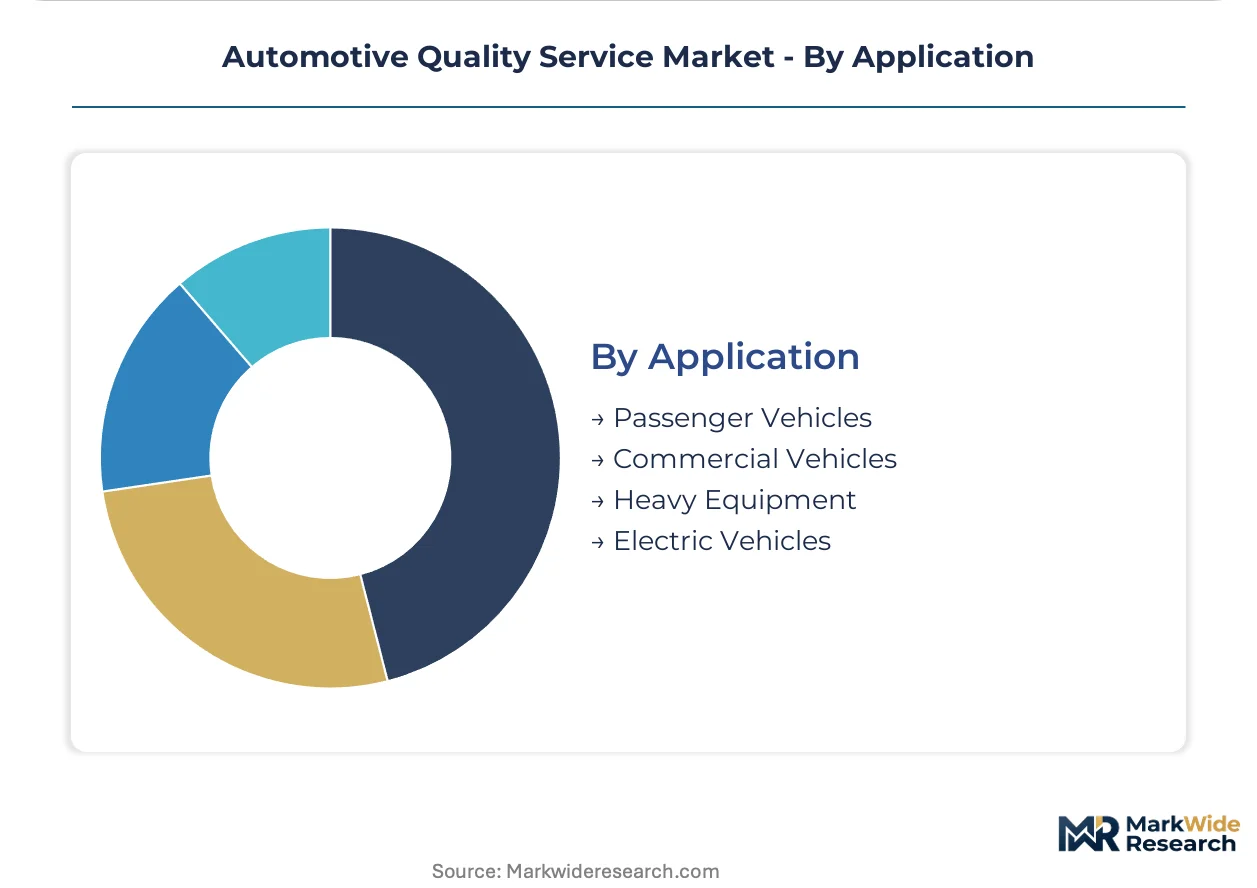
Automotive quality service encompasses inspection, maintenance, repair, and detailing performed to OEM or regulatory standards, typically involving diagnostic scanning, parts traceability, and technician certification protocols that ensure vehicle safety and performance compliance. Its primary purpose is to extend vehicle operational life and uphold manufacturer warranty conditions while meeting roadworthiness mandates. Maintenance commands the largest share of service-type revenue as fleet operators prioritize predictive scheduling over reactive breakdowns. Electric vehicle application segments are expanding fastest as battery system diagnostics and thermal management services require specialized tooling beyond conventional internal combustion skill sets. Diagnostics tools within the technology dimension carry elevated margins due to software licensing dependencies and continuous calibration requirements.
The EPA enforces emission testing protocols that drive demand for certified diagnostic equipment and technician training across US service centers. The EU's F-Gas Regulation and CE marking requirements restrict refrigerant handling practices and mandate specific recovery equipment standards for climate system servicing in Europe. Stakeholders must monitor how battery-electric vehicle penetration reshapes technician certification pathways and capital allocation across inspection, maintenance, and repair infrastructure.
Market Dynamics
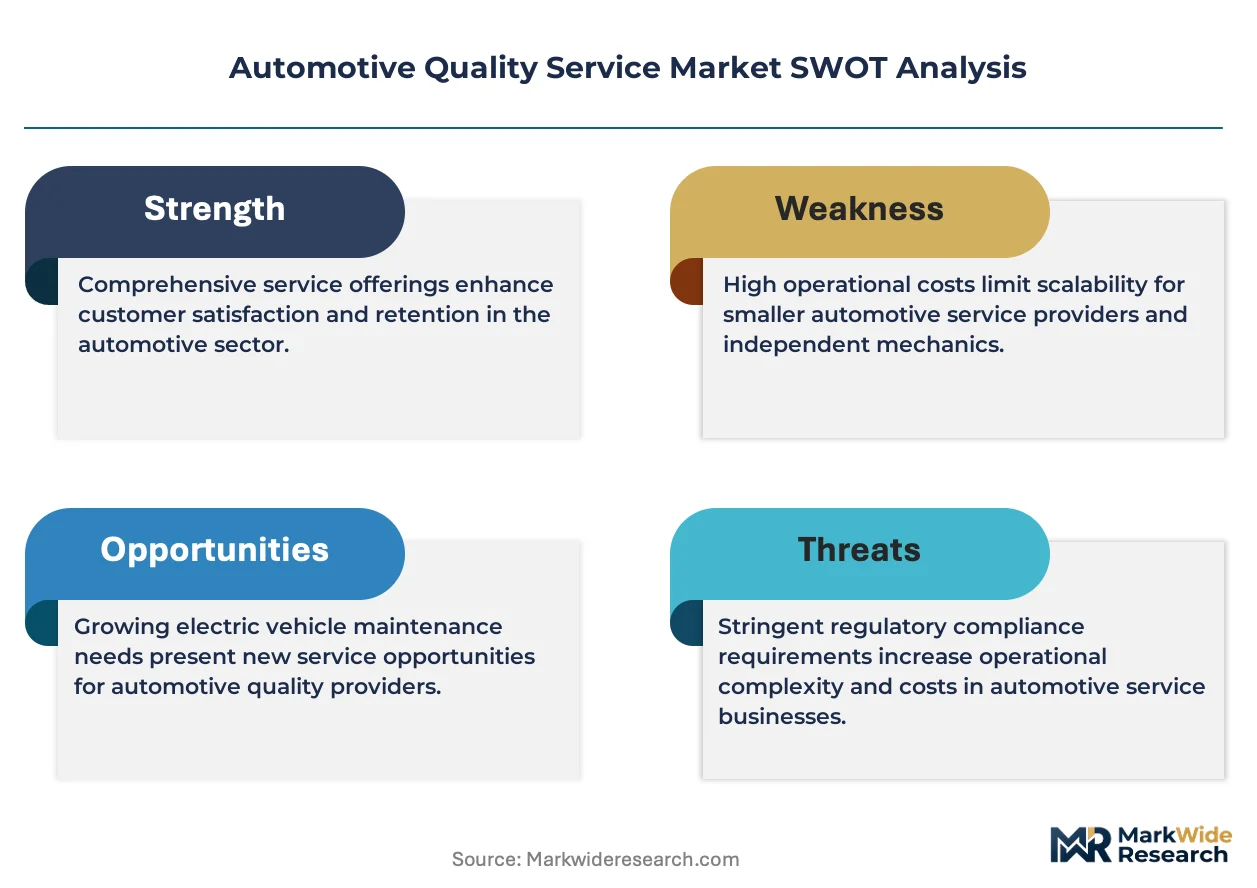
Fleet electrification is forcing service providers to reallocate capital from internal combustion tooling toward battery diagnostics and thermal management infrastructure. This technology pivot compresses margins for traditional brake and exhaust specialists while creating certification barriers for independent shops.
Growth Catalysts
- EPA emission testing mandates:The EPA's vehicle emission standards require certified diagnostic equipment and technician training across US service centers. This drives recurring revenue streams for calibration services and software licensing.
- Fleet predictive scheduling:Commercial fleet operators are expanding scheduled maintenance programs to minimize vehicle downtime. This shifts revenue from reactive repairs toward contracted preventive service agreements.
- Germany's TÜV inspection regime:The country's dense OEM supplier network and mandatory roadworthiness inspections sustain premium service volumes for certified providers.
Market Restraints
- Specialized tooling capital requirements:Battery-electric vehicle servicing demands thermal imaging equipment and high-voltage safety apparatus that independent shops cannot finance.
- EU F-Gas compliance friction:The EU's F-Gas Regulation restricts refrigerant handling practices and mandates specific recovery equipment standards, raising fixed costs for climate system servicing.
- Technician certification scarcity:Electric powertrain diagnostics require credentials that existing vocational pathways do not supply, creating a bottleneck for service expansion.
Strategic Opportunities
- India's aftermarket formalization:The country's Bureau of Indian Standards is expanding automotive service certification schemes, creating first-mover advantages for organized chains entering tier-2 cities.
- Telematics-integrated maintenance:Connected vehicle platforms enable condition-based service triggering. This convergence of IoT data streams with workshop management systems opens subscription revenue models.
- Battery second-life assessment:End-of-vehicle-life battery grading for stationary storage applications requires diagnostic protocols that service centers can monetize beyond traditional repair.
Industry Challenges
- High-voltage safety credentialing timelines:Electric vehicle technician certification involves extended training periods that delay workforce deployment during demand surges.
- Legacy diagnostic equipment stranded value:Existing internal combustion scan tools face accelerated obsolescence as OEMs restrict access to battery management system data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Quality Service Market |
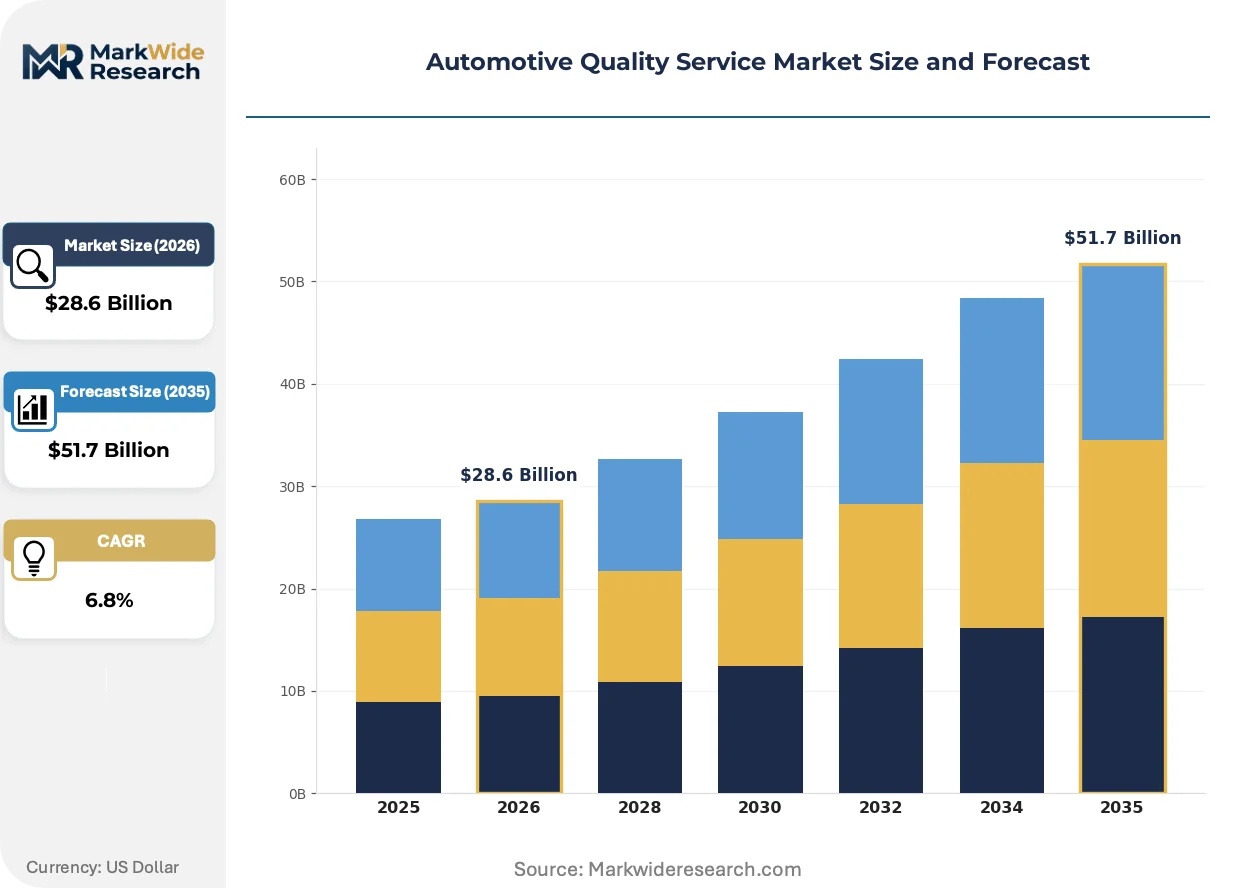
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Repair, Detailing End User: Fleet Operators, Vehicle Owners, Dealerships, Aftermarket Providers Technology: Diagnostics Tools, Repair Equipment, Software Solutions, Telemetry Systems Application: Passenger Vehicles, Commercial Vehicles, Heavy Equipment, Electric Vehicles |
| Companies Covered | Midas International, LLC, Caliber Collision, Firestone Complete Auto Care, Pep Boys, Safelite Group, Jiffy Lube International, Inc., Monro Inc., Valvoline Instant Oil Change, Meineke Car Care Centers, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Quality Service Market Emerging Trajectories
Service delivery models are fragmenting across three vectors: diagnostic technology integration, regulatory compliance automation, and procurement relationship restructuring. These shifts favor capitalized networks over independent operators.
Artificial intelligence-driven predictive maintenance is hybridizing conventional scheduled service with real-time component monitoring. Fleet managers are adopting these platforms fastest, compressing traditional oil-change intervals while expanding brake and battery thermal inspections. This convergence is hybridizing workshop revenue mix away from fluid services toward electronic system analysis.
The EU's F-Gas Regulation is tightening recovery equipment standards and technician certification requirements for refrigerant handling. Service centers must retrofit vacuum stations and purchase certified recovery units to maintain climate system service authorization. Germany and France are seeing the steepest compliance cost increases as national regulators align enforcement with the 2024 amendment timeline.
Long-term service contracts are displacing transactional repair relationships among commercial fleet operators. These agreements bundle preventive maintenance, roadside assistance, and residual value guarantees into fixed monthly payments. The model is spreading fastest among last-mile delivery fleets in urban corridors where vehicle uptime directly determines contract profitability.
Automotive Quality Service Market Segmentation
Service intensity varies sharply across customer workflows in the automotive quality service market. Fleet operators demand predictive scheduling with telematics integration, while independent owners prioritize warranty preservation through OEM-certified procedures.
Service Type:
After-sales service intensity determines how providers allocate technician hours and bay capacity across revenue streams.
- Maintenance:Scheduled fluid changes, filter replacements, and wear-item inspections follow manufacturer-prescribed intervals. Fleet operators in Germany leverage TÜV inspection mandates to bundle preventive work into compliance-driven contracts, compressing reactive repair volumes.
- Repair:Component replacement and mechanical restoration address failure modes from collision damage or system degradation. Caliber Collision anchors specialized scale here, while independent shops face margin pressure from OEM parts pricing protocols.
- Inspection:Roadworthiness verification and diagnostic scanning ensure regulatory compliance. EPA emission testing mandates in the US and TÜV regimes in Germany sustain certified provider volumes.
- Detailing:Interior refurbishment and exterior reconditioning preserve residual values for lease returns and fleet remarketing. Premium service centers in urban corridors monetize this through fixed-menu pricing.
Maintenance holds the largest share; momentum sits with inspection as regulatory compliance tightens across jurisdictions.
End User:
Procurement scale and contract structure separate high-volume fleet relationships from transactional retail service.
- Fleet Operators:Commercial vehicle owners contract preventive maintenance through long-term service agreements with uptime guarantees. Last-mile delivery fleets in dense urban corridors adopt these fastest, linking payment to vehicle availability metrics.
- Vehicle Owners:Individual consumers seek warranty preservation and safety compliance through OEM networks or certified independents. Price sensitivity here drives tiered service packaging across premium, standard, and economy levels.
- Dealerships:Authorized service centers monetize warranty work and factory-trained technician access. Their captive parts supply and diagnostic tool licensing create defensible positioning for complex powertrain repairs.
- Aftermarket Providers:Independent chains and franchise networks compete on convenience and geographic density. Monro Inc. concentrates tire and brake service in the Northeast and Midwest corridors to capture drive-by demand.
Fleet operators command the highest contract values; vehicle owners represent the broadest addressable base.
Technology:
Capital allocation tilts toward diagnostic capability as vehicle systems integrate electronic control modules and battery management systems.
- Diagnostics Tools:Scan equipment and software platforms interface with OEM data protocols to isolate fault conditions. Continuous calibration requirements and licensing dependencies sustain elevated margins for tool vendors.
- Software Solutions:Workshop management systems and customer relationship platforms streamline scheduling, parts procurement, and billing. Cloud-based architectures enable remote diagnostic support and fleet telematics integration.
- Repair Equipment:Lifts, alignment racks, and specialized fixtures support mechanical service workflows. High-voltage safety apparatus for electric vehicle battery service demands capital investments beyond traditional internal combustion tooling.
- Telemetry Systems:Connected vehicle platforms transmit real-time condition data to trigger condition-based maintenance. IoT convergence with workshop management systems opens subscription revenue models for proactive service providers.
Diagnostics tools capture premium margins; telemetry systems are climbing the fastest as fleet telematics penetration deepens.
Application:
Powertrain technology divergence is fragmenting service protocols and technician certification pathways.
- Passenger Vehicles:Light-duty cars and SUVs generate the highest service frequency through oil-change intervals and brake wear cycles. Urban density in Germany and the US Northeast sustains premium service center volumes.
- Electric Vehicles:Battery system diagnostics and thermal management require specialized tooling beyond conventional skill sets. High-voltage safety credentialing timelines create technician scarcity that constrains service expansion.
- Commercial Vehicles:Heavy-duty trucks and vans operate under severe-duty cycles that accelerate maintenance intervals. Fleet predictive scheduling concentrates revenue among contracted providers with national coverage.
- Heavy Equipment:Construction and agricultural machinery demand field service capability and extended component lifecycles. Remote location servicing favors mobile diagnostic units over fixed bay operations.
Passenger vehicles dominate service volume; electric vehicles are gaining share fastest as battery-electric penetration reshapes technician training and capital requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's emission testing mandates and the EU's F-Gas Regulation are reshaping compliance requirements for service procedures across major automotive markets. Fleet operators in Germany and the United States are expanding scheduled maintenance programs to minimize vehicle downtime. Dense OEM supplier networks in specific industrial clusters sustain premium service volumes for certified providers.
Germany
TÜV inspection mandates drive predictable demand for roadworthiness verification and diagnostic scanning. The F-Gas Regulation restricts refrigerant handling practices and mandates certified recovery equipment for climate system servicing. Stuttgart's automotive engineering cluster anchors specialized service capacity for OEM-certified procedures.
United States
Fleet electrification is reallocating capital from internal combustion tooling toward battery diagnostics infrastructure. EPA emission standards require certified diagnostic equipment and technician training across service centers. Michigan's automotive corridor concentrates legacy powertrain expertise while California leads electric vehicle service protocol development.
China
MIIT standards for new energy vehicles are accelerating technician certification requirements for high-voltage battery systems. The country's dual carbon goals are tightening compliance frameworks for vehicle maintenance emissions. Shanghai's Pudong district hosts concentrated aftermarket service chains targeting premium electric vehicle segments.
India
The Bureau of Indian Standards is expanding automotive service certification schemes to formalize the fragmented aftermarket. Commercial fleet operators in tier-2 cities are adopting predictive maintenance platforms to reduce downtime. Tamil Nadu's automotive belt around Chennai anchors organized service chain expansion for both passenger and commercial vehicles.
Japan
METI guidelines for battery-electric vehicle servicing are creating credential pathways that existing vocational training does not supply. JIS standards for diagnostic equipment calibration sustain elevated margins for tool vendors. The Nagoya-Toyota industrial corridor concentrates specialized thermal management service capacity for hybrid and electric powertrains.
Automotive Quality Service Market Vendor Landscape
On the supply side, the industry is tiered between capitalized franchise networks, specialized collision repair operators, and regional tire and brake specialists. Consolidation pressure favors multi-location operators with coast-to-coast coverage over single-point independents. Three archetypes dominate: franchise service networks with standardized protocols, collision repair scale players, and convenience-focused maintenance specialists. M&A activity targets geographic white-space filling, while technology licensing agreements secure diagnostic tool access.
Within the franchise network tier, Midas International exemplifies company-owned and franchised location strategies that sustain national coverage. Caliber Collision occupies a specialized position in collision repair scale. Monro Inc. anchors tire and brake service concentration in the Northeast and Midwest corridors. These three represent distinct competitive vectors: standardized protocol replication, damage restoration specialization, and drive-by convenience capture.
| Leading Market Players |
|---|
| Midas International, LLC |
| Caliber Collision |
| Firestone Complete Auto Care |
| Pep Boys |
| Safelite Group |
| Jiffy Lube International, Inc. |
| Monro Inc. |
| Valvoline Instant Oil Change |
| Meineke Car Care Centers, LLC. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Germany's TÜV-certified service network compresses pricing power for premium maintenance providers while forcing independent shops toward volume-based brake and tire packages. Utilization rates below 70 percent in Stuttgart's automotive cluster push organized chains to consolidate bay capacity and renegotiate OEM parts supply terms.
Pricing Analysis
Volume-discount tiering separates fleet operators with contracted preventive agreements from transactional retail customers seeking single-service appointments. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade: OEM-authorized centers command premium rates for warranty-preserving procedures, while uncertified independents compete on fluid-change commoditization. Cost compression in standard-tier maintenance intensifies as telematics-integrated platforms enable condition-based triggering that extends oil-change intervals. Fleet operators exhibit lowest price sensitivity due to uptime-guarantee contracts; individual vehicle owners drive hardest bargain on brake and exhaust services.
Supply Chain Analysis
Export-control restrictions on high-voltage diagnostic software limit cross-border flows of battery management system calibration tools from Germany and Japan into emerging service markets. Component sourcing concentrates in Germany for precision scan equipment, China for thermal imaging hardware, and the United States for EPA-certified emission testing apparatus. Critical dependencies include lithium-ion battery cells for electric vehicle servicing, refrigerant recovery units for F-Gas compliance, and continuous software licenses for OEM protocol access. Single-source vulnerability runs through proprietary diagnostic data subscriptions controlled by vehicle manufacturers. Distribution runs through authorized distributor networks for certified equipment and direct-to-shop e-commerce for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as telematics-integrated maintenance contracts bundle hardware, software, and service into recurring revenue architectures. Interoperability between fleet management systems and workshop management platforms determines provider selection.
For Market Incumbents: Insulate core fleet relationships by embedding predictive maintenance algorithms into long-term service agreements before battery-electric vehicle penetration accelerates technician scarcity. Acquire high-voltage certification capacity in Michigan and California corridors to preempt independent shops from capturing electric vehicle service volumes. Lock exclusive diagnostic data licensing with OEMs to strand competitor scan tool investments.
For New Entrants and Emerging Players: Build out mobile diagnostic units targeting heavy equipment and commercial vehicle field service in India's tier-2 cities where fixed bay infrastructure remains underdeveloped. India's Bureau of Indian Standards certification schemes create first-mover formalization advantages for organized chains entering Tamil Nadu's automotive belt. Partner with telematics platform providers to offer condition-based triggering as a bundled subscription rather than competing on transactional repair pricing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric vehicle service infrastructure as thermal management equipment and high-voltage safety apparatus displace conventional tooling. Target acquisition archetypes include regional chains with dense bay networks in Germany or the US Northeast that can absorb certification upgrade costs. Monitor technician certification completion rates as the inflection signal: sustained shortfalls in high-voltage credentialing would compress service capacity expansion and shift pricing power toward capitalized networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Connected vehicle data streams enable condition-based maintenance triggering for fleet operators. |
| High-Voltage Technician Certification Investment | EPA and TÜV-aligned credentialing creates defensible capacity as electric vehicle penetration accelerates. |
| Geographic Consolidation in Tier-2 Cities | India's BIS formalization schemes reward first-mover organized chains with certified network scale. |
| Diagnostic Data Licensing Agreements | OEM protocol access determines scan tool functionality and strands independent competitor equipment. |
| Battery Second-Life Assessment Capability | End-of-vehicle-life grading protocols open stationary storage revenue beyond traditional repair services. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork spanning fleet maintenance directors, OEM service network managers, aftermarket distributor procurement leads, and high-voltage technician training providers. Secondary validation drew from EPA enforcement databases, EU F-Gas Regulation implementation reports, TÜV inspection statistics, and vehicle registration data from national transport authorities. Bottom-up service center capacity modeling triangulated against top-down fleet expenditure surveys.
Calibration across the analysis window employed segmented growth attribution by service type, end-user contract structure, technology licensing tier, and powertrain application. Propulsion architecture divergence between internal combustion and battery-electric vehicle fleets shaped technician hour allocation assumptions. CAGRs derived from installed base projections and service interval compression factors tied to telematics penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-integrated entrants or rapid OEM data protocol closures would shift outcomes. Material shifts in EPA emission testing mandates, EU F-Gas amendment timelines, or battery-electric vehicle technician certification throughput would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Cab Services Market
Automotive Services
Car Rental Business Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
North America Car Wash Market