
 Car Subscription Market | 2026-2036
Car Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Car Subscription Market Intelligence
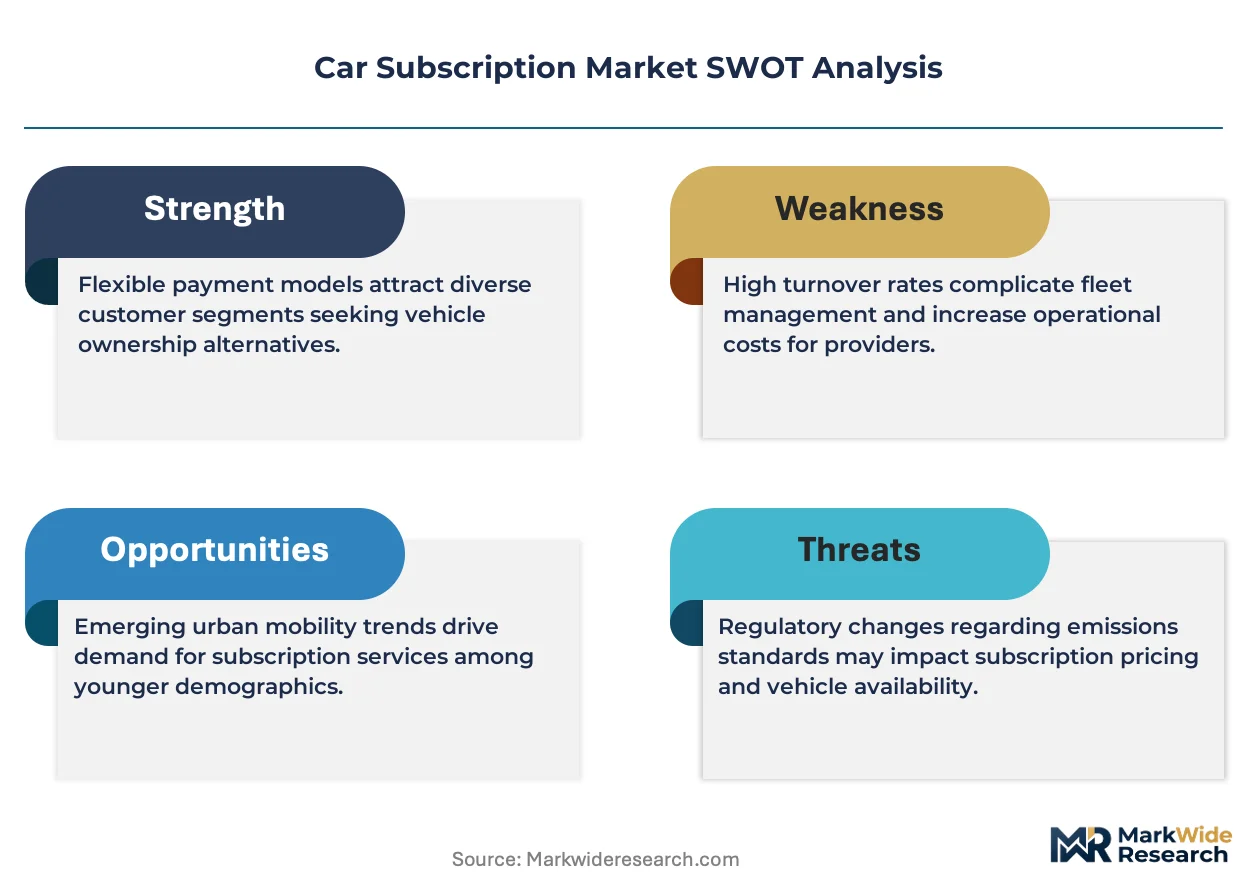
Asset-light fleet financing is tilting competitive dynamics toward operators that can scale without heavy balance-sheet exposure. Sixt leverages its European rental infrastructure to offer multi-brand subscription bundles at scale. Onto Ltd. anchors its position with an all-electric fleet that eliminates residual-value risk on combustion engines. Zoomcar competes in emerging markets through peer-to-peer inventory aggregation that lowers capital intensity.
A car subscription is a recurring-payment mobility contract granting temporary vehicle access with bundled insurance, maintenance, and roadside assistance, typically managed through digital platforms with telematics-enabled fleet oversight. Its commercial purpose is to convert fixed automotive ownership costs into variable operating expenses for users while generating predictable revenue streams for fleet operators. Single-brand programs dominate margin pools through manufacturer-captive finance structures, while flexible subscriptions represent the fastest-growing contract duration segment among urban professionals seeking commitment-free mobility. Electric vehicles within the vehicle type split are concentrating demand as battery technology extends usable range and charging infrastructure densifies.
The EU Green Deal and national zero-emission zone mandates in France, Germany, and the Netherlands are reshaping fleet composition rules and accelerating electrification requirements for subscription operators. GDPR compliance across subscriber data platforms and F-Gas Regulation constraints on vehicle air-conditioning systems add operational complexity that favors established players with dedicated compliance functions. Stakeholders must monitor how regulatory phase-outs of internal combustion engines interact with residual-value guarantees and fleet turnover timelines.
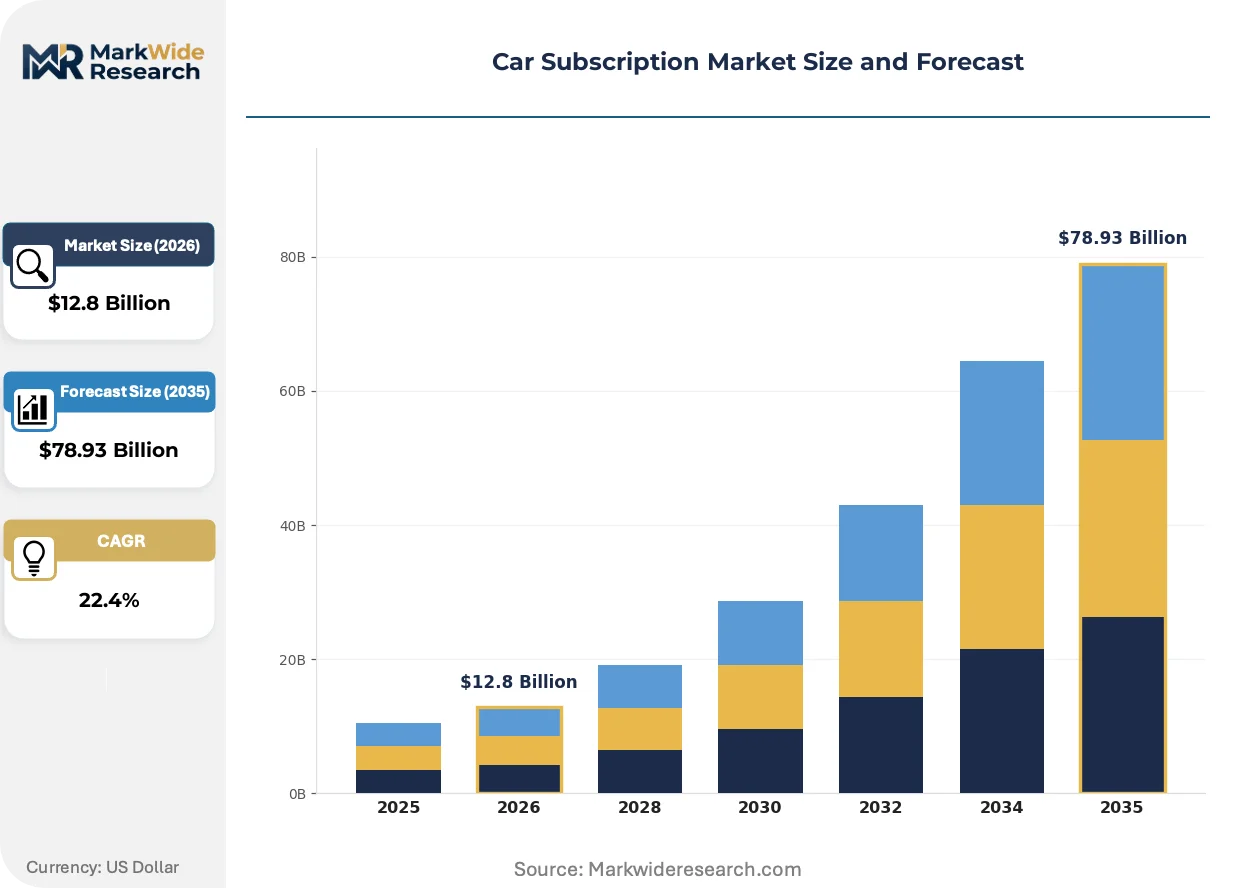
Market Dynamics
Corporate fleet managers are abandoning vehicle ownership en masse as urban mobility regulations tighten and residual-value risk on internal combustion engines becomes unmanageable. This structural shift toward asset-light financing is compressing contract durations and elevating digital platform capabilities above physical fleet scale.
Growth Catalysts
- EU Green Deal zero-emission mandates:France, Germany, and the Netherlands are phasing out combustion engines in city centers, forcing fleet operators toward electric vehicle subscriptions.
- Battery range extension:Solid-state and lithium-metal chemistries are eliminating range anxiety among urban professionals who previously rejected EVs.
- Telematics integration:Real-time fleet oversight platforms are reducing insurance and maintenance costs by enabling predictive intervention before component failures.
Market Restraints
- Lithium supply concentration:Battery raw material processing concentrates in China, exposing subscription operators to geopolitical supply disruptions and input cost volatility.
- F-Gas Regulation compliance:EU constraints on vehicle air-conditioning refrigerants add retrofit costs to existing fleet inventory during electrification transitions.
- Used vehicle market illiquidity:Thin secondary markets for three-year-old EVs complicate residual-value guarantees that underpin subscription pricing models.
Strategic Opportunities
- India peer-to-peer aggregation:Underpenetrated urban markets with low car ownership rates present first-mover advantages for inventory-light platform models.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates are pushing fleet managers toward subscription services that offer transparent Scope 3 emissions tracking.
- Vehicle-to-grid convergence:Bidirectional charging integration with distributed energy resources creates new revenue streams from parked subscription fleet assets.
Industry Challenges
- GDPR-compliant data architecture:Subscriber telematics platforms require specialized privacy engineering talent that remains scarce across European operators.
- Legacy fleet management system integration:Established rental companies face technical debt when connecting mainframe reservation systems to modern API-driven subscription marketplaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Subscription Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $78.93 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Single-Brand Programs, Multi-Brand Programs, Flexible Subscriptions, Corporate Subscriptions Customer Type: Urban Professionals, Families, Business Travelers, Students Vehicle Type: Electric Vehicles, SUVs, Sedans, Luxury Vehicles Contract Duration: Short-Term, Long-Term, Flexible, Seasonal |
| Companies Covered | Cox Enterprises Inc., Lyft Inc., Sixt, The Hertz Corporation, Onto Ltd., Carly Holdings Limited, Facedrive Inc., Zoomcar, Cluno GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Subscription Market Strategic Shifts & Innovations
Digital-native platforms are compressing vehicle access into app-mediated experiences while regulatory pressure and battery chemistry advances converge to electrify fleet composition. These forces are reshaping competitive differentiation around software capabilities rather than metal assets.
Embedded telematics with over-the-air diagnostic capability is digitizing every touchpoint of the subscription lifecycle. Fleet operators are deploying these systems to automate maintenance scheduling and dynamic pricing based on real-time utilization patterns. The technology is digitizing traditional automotive retail into fully automated mobility-as-a-service delivery.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions across vehicle air-conditioning systems. This regulatory pressure forces subscription operators to accelerate fleet turnover timelines and negotiate new supplier contracts for climate-compliant components. German operators face the steepest compliance curves as KBA enforcement intensifies ahead of 2027 benchmarks.
Urban professionals are compressing commitment horizons from multi-year leases to month-to-month subscriptions with bundled insurance and maintenance. Corporate procurement departments are displacing fleet ownership with variable operating expense models that align vehicle costs with headcount fluctuations. This behavioral pivot concentrates demand in Germany, France, and the Netherlands where city-center driving restrictions make flexible EV access preferable to owned-vehicle risk.
Car Subscription Market Segmentation
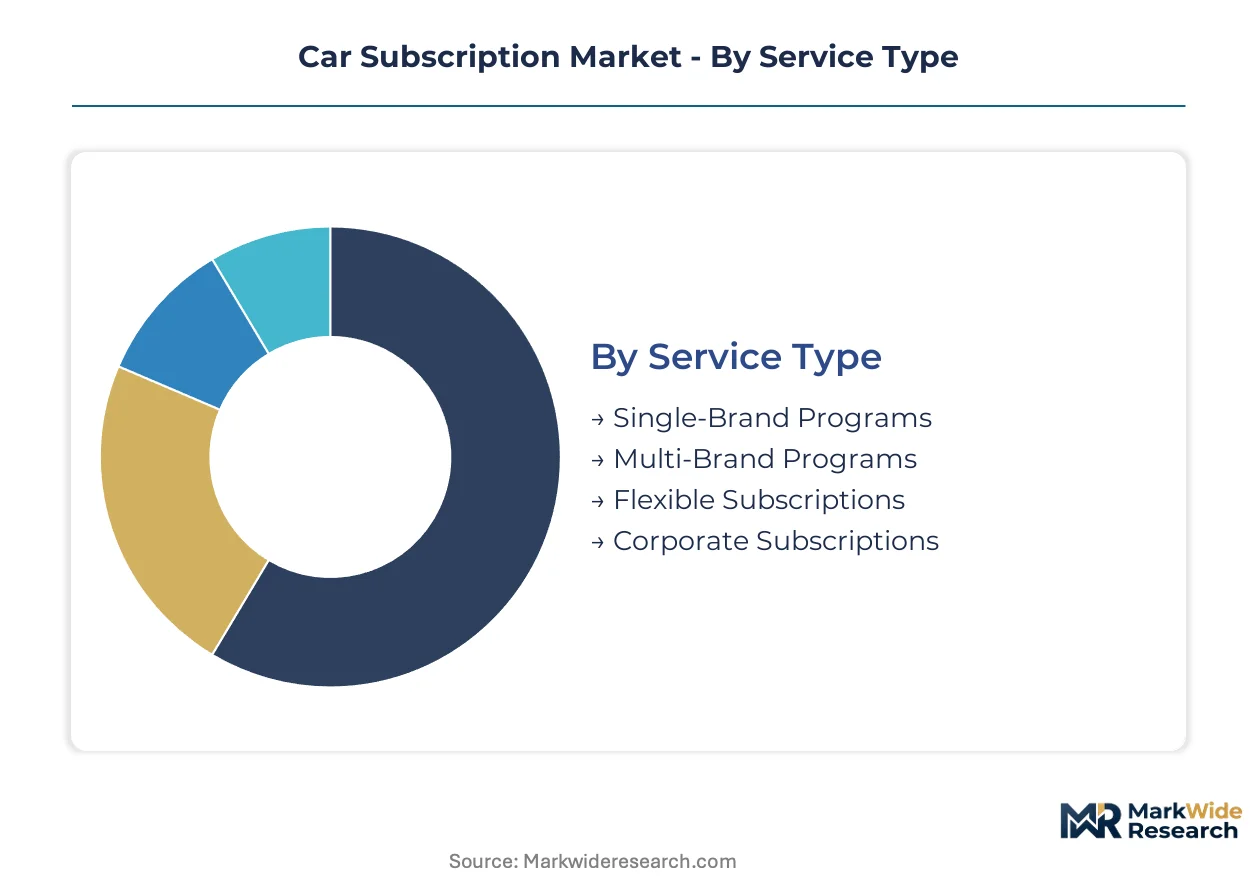
Car subscription segmentation reveals divergent margin structures and capital intensity across service models, customer profiles, and fleet composition strategies. Operators must align inventory mix with contract duration preferences to optimize utilization rates and residual value exposure.
Service Type:
Mature single-brand programs coexist with emerging flexible models that compress commitment horizons and elevate platform requirements.
- Single-Brand Programs:Manufacturer-captive finance structures bundle vehicles, insurance, and maintenance under one marque. Corporate procurement departments in Germany favor these programs for standardized fleet policies and simplified supplier management.
- Multi-Brand Programs:Aggregators source inventory across OEMs to match subscriber preference diversity. Sixt leverages its European rental infrastructure to deliver scale advantages in this segment.
- Flexible Subscriptions:Month-to-month contracts with swap privileges dominate urban professional demand. These arrangements convert fixed ownership costs into variable operating expenses.
- Corporate Subscriptions:Enterprise fleet-as-a-service contracts displace traditional leasing with bundled telematics and emissions reporting. CSRD disclosure mandates accelerate procurement shifts toward these transparent structures.
Single-brand programs retain volume leadership; flexible subscriptions hold the steepest expansion curve.
Customer Type:
Cost tier stratification separates premium business travelers from price-sensitive student segments with divergent service expectations.
- Urban Professionals:Commitment-averse knowledge workers prioritize app-mediated vehicle access with minimal paperwork. Zero-emission zone mandates in Paris and Amsterdam intensify demand for bundled EV subscriptions among this cohort.
- Families:Multi-vehicle households seek temporary access to larger SUVs for seasonal needs without ownership burdens. Insurance bundling and maintenance inclusion reduce household administrative complexity.
- Business Travelers:Airport-centric subscription pickups replace traditional rental transactions for extended stays. Corporate travel policies increasingly mandate subscription services for trips exceeding two weeks.
- Students:Semester-aligned contracts with parental guarantee structures access underpenetrated younger demographics. Limited credit histories require alternative underwriting through academic enrollment verification.
Urban professionals command premium pricing power; students represent the most price-elastic acquisition challenge.
Vehicle Type:
Application-driven fleet composition tilts toward electrification as battery chemistry advances and charging infrastructure densifies.
- Electric Vehicles:Battery-electric powertrains eliminate residual-value risk on internal combustion engines facing regulatory phase-outs. EU Green Deal mandates in France, Germany, and the Netherlands concentrate demand in urban corridors with zero-emission zones.
- SUVs:Larger body styles serve family and adventure-use cases with higher per-subscription revenue but elevated insurance costs. Telematics-enabled usage-based pricing mitigates risk exposure.
- Sedans:Traditional three-box configurations retain corporate fleet preference for executive transport. Declining retail demand shifts inventory toward subscription channels.
- Luxury Vehicles:Premium marques attract short-term aspirational subscribers seeking experiential access without depreciation exposure. Higher per-day rates offset lower utilization rates.
Electric vehicles capture disproportionate demand growth; SUVs maintain revenue per unit leadership.
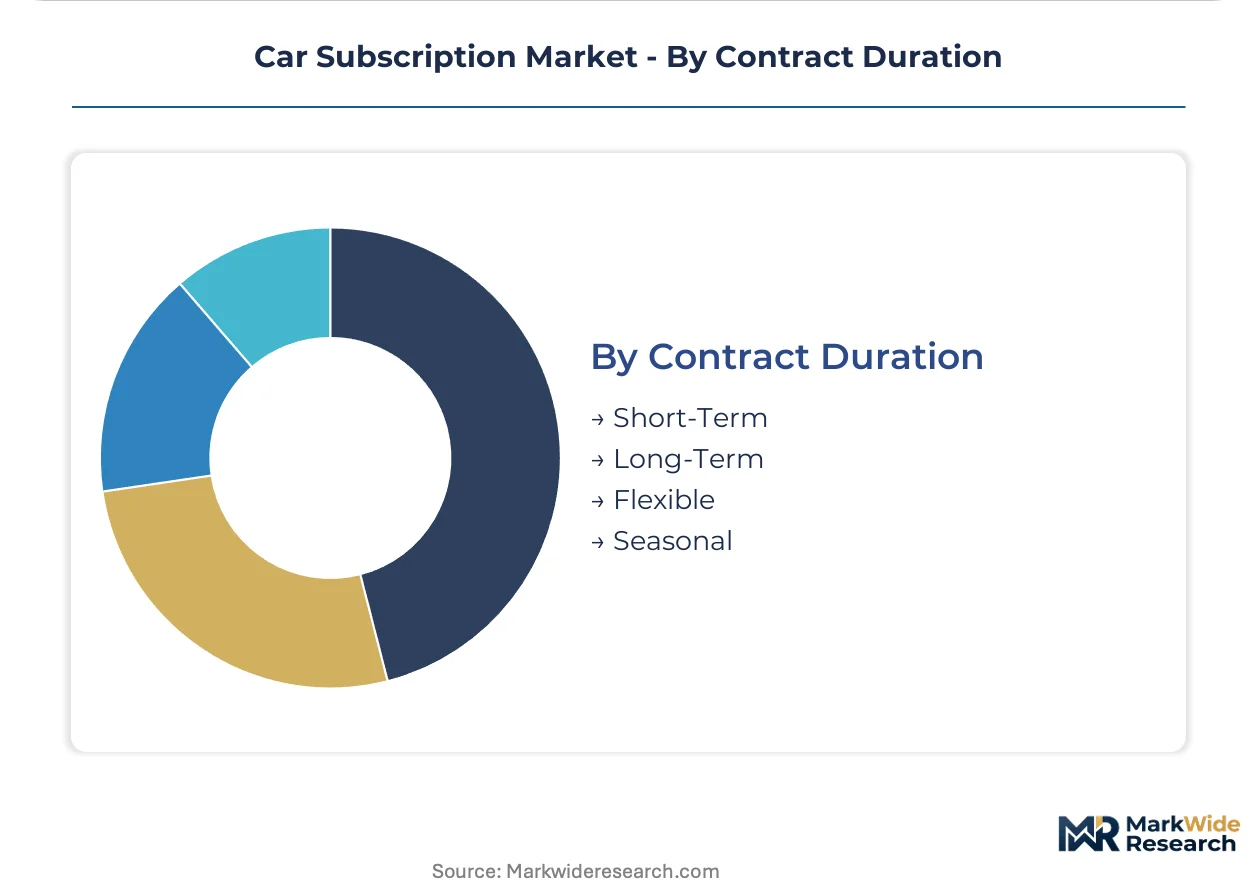
Contract Duration:
Volume concentration in short-term arrangements contrasts with margin stability in extended commitments.
- Short-Term:Daily to weekly arrangements serve immediate mobility needs with premium pricing. Airport and city-center pickup locations maximize accessibility.
- Long-Term:Six-month to multi-year contracts reduce customer acquisition costs and improve fleet planning precision. Corporate procurement departments favor these structures for headcount-aligned vehicle provisioning.
- Flexible:Pause-enabled month-to-month terms accommodate remote work schedule volatility. Digital platform capabilities determine competitive differentiation.
- Seasonal:Summer and winter-specific subscriptions align with vacation patterns and weather-driven vehicle requirements. Ski resort and coastal market operators specialize in this cadence.
Long-term contracts anchor revenue predictability; flexible durations gain share fastest among urban professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German operators extract 40% pricing premiums over Indian counterparts for equivalent EV subscription tiers, reflecting divergent regulatory enforcement density and charging infrastructure maturity. This asymmetry concentrates investment flows toward European compliance-ready platforms while emerging markets compete on capital-light aggregation models.
United States
Corporate fleet managers in Texas and California are displacing ownership with variable-expense subscriptions as headcount volatility rises. EPA emissions standards and California Air Resources Board zero-emission mandates accelerate EV fleet turnover timelines. Dallas-Fort Worth and Los Angeles metropolitan corridors concentrate demand for flexible business-travel subscriptions with airport-centric pickup networks.
Germany
KBA enforcement intensifies ahead of 2027 F-Gas Regulation benchmarks, forcing refrigerant retrofits across existing fleet inventory. EU Green Deal zero-emission zone mandates in Berlin, Munich, and Hamburg compress combustion-engine residual values. Bavaria and Baden-Württemberg industrial clusters host the densest charging infrastructure networks, supporting premium EV subscription penetration among urban professionals.
United Kingdom
London Ultra Low Emission Zone expansion drives corporate procurement toward bundled EV subscriptions with transparent Scope 3 reporting. CSRD disclosure requirements push fleet managers away from ownership models toward service-based emissions tracking. The M25 corridor and Greater Manchester concentrate multi-brand aggregator operations serving commitment-averse knowledge workers.
India
Maharashtra and Karnataka urban centers present first-mover advantages for peer-to-peer inventory platforms with low baseline car ownership. BIS vehicle safety standards and state-level EV purchase incentives reshape fleet composition rules for subscription operators. Bangalore and Mumbai metropolitan regions anchor demand for semester-aligned student subscriptions with academic-verification underwriting.
France
Paris municipal authorities enforce the strictest city-center combustion-engine restrictions in Europe, eliminating residual-value certainty for ICE fleet assets. ANSM data governance guidelines add compliance complexity to subscriber telematics platforms. The Île-de-France region concentrates single-brand captive finance programs serving standardized corporate fleet policies.
Car Subscription Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base stratifies between digital-native aggregators with API-driven marketplaces and legacy rental operators carrying mainframe technical debt. Three archetypes dominate: manufacturer-captive finance arms, multi-brand aggregators leveraging existing fleet infrastructure, and peer-to-peer inventory platforms minimizing capital intensity. Competitive moves concentrate on telematics integration partnerships and geographic expansion through white-label platform licensing.
Among European infrastructure-leveraged operators, Sixt and Cluno GmbH exemplify the multi-brand aggregation archetype, while Onto Ltd. occupies a position within the electric-vehicle-specialist tier. These entities represent divergent strategic responses to identical regulatory pressures—Sixt through scale advantages in existing rental networks, Cluno through digital-native flexibility, and Onto through powertrain-specific residual-value risk elimination. Their collective positioning illustrates how compliance-driven fleet turnover timelines favor operators with balance-sheet capacity or inventory-light models over capital-constrained mid-tier entrants.
| Leading Market Players |
|---|
| Cox Enterprises Inc. |
| Lyft Inc. |
| Sixt |
| The Hertz Corporation |
| Onto Ltd. |
| Carly Holdings Limited |
| Facedrive Inc. |
| Zoomcar |
| Cluno GmbH |
| Others |
Cost & Logistics Intelligence
China's lithium hydroxide processing dominance anchors cost volatility for European subscription operators, compressing margin pools toward fleet operators with captive battery supply agreements or inventory-light peer-to-peer architectures that bypass raw material exposure entirely.
Pricing Analysis
Configured-to-order EV subscriptions command 25-40% premiums over standard monthly tiers across German urban corridors, with price differentiation driven by battery capacity tier and bundled charging network access. Pricing pressure stems from Chinese lithium carbonate spot volatility feeding through cell costs. Students and younger demographics exhibit highest price elasticity, while corporate procurement departments show lowest sensitivity due to CSRD-mandated emissions transparency requirements.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment constrain telematics chip availability from Taiwanese and South Korean foundries, forcing subscription operators to extend vehicle delivery timelines. The supply chain draws from Chinese cathode active material, Indonesian nickel, and Chilean lithium hydroxide. Single-source vulnerability concentrates in battery cell assembly. Distribution runs through OEM-direct fleet allocation and multi-brand aggregator procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across contract duration preferences and electrification timelines creates niche formation opportunities as urban professionals abandon ownership commitment while corporate fleets demand decade-long emissions accountability.
For Market Incumbents: Insulate residual-value exposure by accelerating combustion-engine fleet turnover ahead of KBA enforcement milestones. Prioritize vertical integration into charging infrastructure partnerships that lock in subscriber retention. Battery supply agreements with Korean cell manufacturers reduce geopolitical input risk. For New Entrants and Emerging Players: India's peer-to-peer inventory aggregation in Maharashtra and Karnataka urban corridors represents the most penetrable entry point given low baseline car ownership and limited incumbent platform density. Academic-verification underwriting for semester-aligned student contracts offers differentiated acquisition economics. Go-to-market through university partnership channels minimizes customer acquisition cost. For Investors and Strategic Acquirers: Capital is best deployed toward electric-vehicle-specialist operators with proven residual-value risk elimination models and API-first platform architectures. Long-term viability hinges on compliance-ready fleet turnover capabilities amid tightening EU Green Deal phase-out schedules. Watch lithium hydroxide processing concentration in China as the critical inflection signal for input cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell procurement contracts with Korean manufacturers reduce exposure to Chinese lithium processing volatility. |
| Charging Infrastructure Partnership | Network access bundling with Ionity or Fastned elevates subscriber retention in German metropolitan corridors. |
| Platform Integration | API-first marketplace architectures enable white-label licensing for legacy rental operators carrying mainframe technical debt. |
| Geographic Expansion | Maharashtra and Karnataka urban penetration captures first-mover advantages in India's underdeveloped subscription infrastructure. |
| Acquisition of Specialist Firm | Telematics engineering talent pools in GDPR-compliant data architecture remain scarce across European operators. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, telematics platform engineers, corporate procurement managers, and regulatory compliance officers; and secondary validation through EU Green Deal implementation trackers, KBA enforcement schedules, BIS vehicle safety filings, and charging infrastructure deployment databases. Bottom-up subscriber volume estimates triangulated against top-down fleet operator revenue disclosures.
Forecast inputs span contract duration tiers, propulsion architecture splits, and regional regulatory enforcement density across the projection horizon. Segment-level CAGRs derive from utilization rate assumptions, fleet turnover timelines, and residual-value guarantee pricing models. Battery chemistry transition curves and zero-emission zone mandate phase-in schedules anchor EV penetration assumptions.
Practitioners should monitor lithium hydroxide spot price movements and EU F-Gas Regulation retrofit compliance deadlines for early signals of operator margin compression. Forecasts reflect assumptions around charging infrastructure densification rates and corporate procurement shift velocity toward subscription models. Material shifts in Chinese export control regimes or accelerated ICE phase-out schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
North America Car Wash Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Mobility Scooters Market
Automotive Services
Australia Fire Truck Market
Automotive Services
GCC Car Rental Market
Automotive Services
US Car Wash Services Market
Automotive Services
GCC Car Wash Market
Automotive Services
Automotive MRO Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Automotive Retail Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Driver's License Market