
 United States Tire Market | 2026-2036
United States Tire Market Size, Share, and Industry Trends Forecast 2026-2036
United States Tire Market Intelligence
Direct-to-fleet digital procurement is rewriting how volume tire contracts are negotiated in the United States. Goodyear Tire & Rubber Company leverages its commercial service network to sustain long-haul fleet relationships. Bridgestone Corporation anchors its position through captive retail and wholesale distributor control. Michelin differentiates via premium material science and sustained original equipment supply agreements with domestic automakers.
United States tires are composite structures of natural and synthetic rubber reinforced with steel belts and textile plies, manufactured through calendering, extrusion, and vulcanization to provide load-bearing, shock-absorbing contact between vehicles and road surfaces. Passenger car tires occupy the largest volume position while carrying thinner margins, whereas truck tires command higher per-unit value and longer replacement cycles. Fleet operators represent the fastest-growing end user segment as logistics companies centralize procurement and demand predictable lifecycle costing.
NHTSA enforces Federal Motor Vehicle Safety Standards for tire performance, while EPA regulations on corporate average fuel economy push manufacturers toward silica-enhanced tread compounds. The Department of Transportation's tire fuel efficiency grading system shapes consumer comparison shopping and retail channel inventory priorities. Stakeholders must monitor how California's Advanced Clean Trucks rule and pending federal greenhouse gas standards for heavy-duty vehicles recalibrate commercial tire specifications and replacement timing.
Market Dynamics
Fleet digitization and EPA fuel economy mandates are compressing replacement cycles and forcing compound reformulation across the United States tire supply base. NHTSA rollover resistance standards simultaneously reshape sidewall construction priorities for original equipment manufacturers.
Growth Catalysts
- Commercial Fleet Utilization:Logistics operators are extending vehicle duty cycles to meet e-commerce delivery windows. This accelerates tread wear and compresses replacement intervals for long-haul truck tires.
- EPA Corporate Average Fuel Economy Standards:Mandates for reduced rolling resistance push manufacturers toward silica-enhanced tread compounds. Domestic automakers now specify low-resistance tires as standard fitment.
- Great Lakes Manufacturing Corridor:Production clusters anchored by Detroit, Akron, and South Carolina concentrate skilled vulcanization labor and steel belt supply. Proximity to domestic automakers reduces inbound logistics costs.
Market Restraints
- Natural Rubber Price Volatility:Southeast Asian supply disruptions and currency fluctuations create input cost instability. Tire manufacturers lack short-term pricing power to pass through commodity swings.
- Steel Belt Supply Concentration:Domestic steel cord production concentrates among a limited supplier base. Any mill capacity reduction immediately constrains radial tire output.
- Retread Substitution:Commercial fleet operators increasingly specify casing retreads for drive axle positions. This displaces new tire volume in the highest-margin truck segment.
Strategic Opportunities
- Direct-to-Fleet Digital Platforms:National logistics companies seek centralized procurement portals with predictive lifecycle costing. Tire manufacturers can disintermediate traditional wholesale distributors.
- California Advanced Clean Trucks Rule:Zero-emission commercial vehicle mandates create demand for specialized low-rolling-resistance tires. Early specification wins with electric truck platforms yield captive replacement business.
- Sensor-Embedded Intelligent Tires:Convergence of pressure monitoring systems with tread wear algorithms enables predictive maintenance. Fleet operators pay premium pricing for downtime prevention.
Industry Challenges
- Compound Formulation Talent Scarcity:Silica dispersion chemistry and advanced polymer blending require specialized rubber technologists. Retirement waves in Akron and Detroit erode institutional knowledge.
- DOT Fuel Efficiency Certification Timelines:New tread patterns require extended laboratory testing under Department of Transportation protocols. Validation delays compress product launch windows.
- Legacy Fleet Management System Integration:Digital procurement platforms must interface with entrenched transportation management software. API standardization remains incomplete across carrier IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Tire Market |
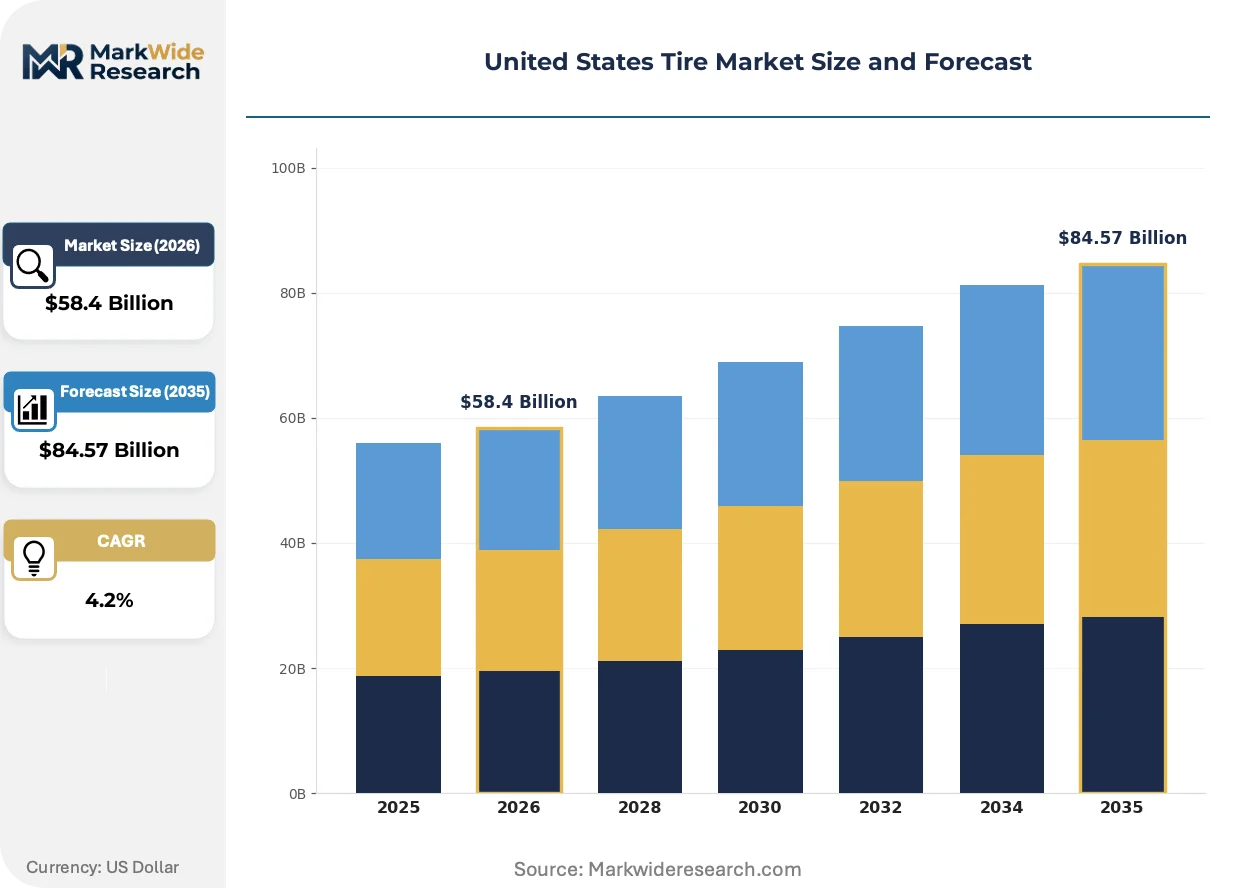
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $84.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car, Truck, Motorcycle, Bus End User: Retail Customers, Automotive OEMs, Fleet Operators, Repair Shops Material: Rubber, Steel, Fabric, Retreaded Distribution Channel: Online Sales, Tire Dealers, Wholesale Distributors, Supermarkets |
| Companies Covered | Continental AG, Firestone, Goodyear Tire & Rubber Company, Toyo Tire Group Global, Cooper Tire Company, Michelin, BF Goodrich, Yokohama Rubber Company, Bridgestone Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Tire Market Strategic Shifts & Innovations
Digital thread technologies and predictive maintenance algorithms are rewriting how tire performance data flows between manufacturers and fleet operators. Material science advances simultaneously enable lighter construction without sacrificing durability.
Tire pressure monitoring systems integrated with cloud-based fleet analytics are virtualizing traditional roadside inspection protocols. Long-haul carriers now receive real-time alerts on inflation deviations and casing temperature spikes. This compresses unscheduled downtime and shifts maintenance from reactive service calls to scheduled depot interventions.
NHTSA Federal Motor Vehicle Safety Standard 139 mandates enhanced endurance testing for light truck tires. Manufacturers must validate sidewall integrity under sustained high-load conditions. The standard most affects all-terrain and off-road product lines, forcing reformulation of polyester ply adhesion compounds.
Volume buyers now consolidate procurement through national account structures with lifecycle cost guarantees. Independent dealers lose share to manufacturer-direct service networks. This concentration is most visible among parcel and less-than-truckload carriers operating dense terminal networks across the Midwest and Southeast.
United States Tire Market Segmentation
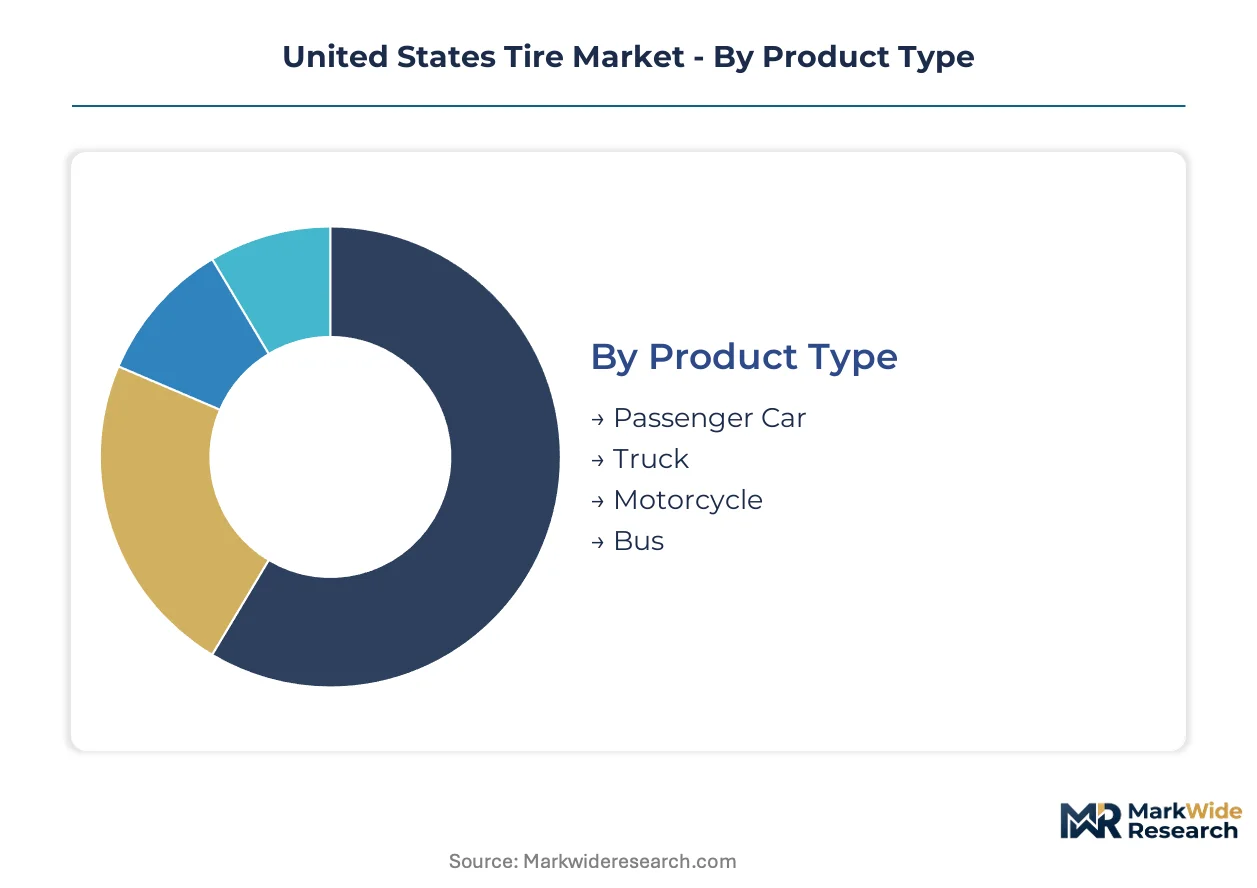
Tire procurement patterns diverge sharply across customer archetypes and material specifications. Segmentation reveals how fleet centralization, OEM fuel economy mandates, and digital channel migration reshape volume allocation across the United States.
Product Type:
Mature highway segments dominate installed base while emerging specialty categories capture specification premiums.
- Passenger Car:Radial construction with silica-enhanced tread compounds balances rolling resistance against wet grip. Detroit-area OEMs specify these as standard fitment under EPA fuel economy mandates, compressing replacement intervals as vehicle miles traveled climb.
- Truck:Heavy-duty radials with reinforced steel belt packages withstand extended duty cycles. Long-haul fleets operating across the Great Lakes corridor drive demand for predictable lifecycle costing and retreadable casings.
- Motorcycle:Bias-ply and radial sport-touring compounds serve enthusiast riders in coastal markets.
- Bus:Urban transit authorities specify all-position radials with scrub-resistant tread patterns.
Passenger car tires handle the majority of throughput; truck tires are the fastest mover on share.
End User:
Customer type determines pricing power, with volume concentration shifting toward centralized procurement entities.
- Fleet Operators:National logistics companies negotiate lifecycle cost guarantees through direct manufacturer relationships. E-commerce delivery density in the Midwest and Southeast accelerates replacement frequency for long-haul positions.
- Automotive OEMs:Domestic automakers specify low-rolling-resistance compounds to meet NHTSA rollover resistance and EPA corporate average fuel economy standards. Akron and Detroit production clusters supply just-in-time fitment programs.
- Retail Customers:Individual vehicle owners prioritize DOT fuel efficiency grades and all-season versatility.
- Repair Shops:Independent service centers source through wholesale distributors with limited inventory depth.
Fleet operators concentrate the fastest volume expansion; repair shops face margin compression from manufacturer-direct channels.
Material:
Raw material selection traces directly to performance tier and retread viability economics.
- Rubber:Natural and synthetic polymer blends form the elastomer matrix. Southeast Asian supply disruptions create input cost volatility that manufacturers struggle to pass through.
- Steel:High-tensile cord reinforces radial belts and bead bundles. Domestic mill concentration limits supply flexibility during capacity constraints.
- Fabric:Polyester and nylon plies provide casing structure for passenger and light truck applications.
- Retreaded:Casing refurbishment extends commercial tire life at 40-60% of new tire cost. Drive axle positions in regional trucking fleets show highest adoption.
Rubber compounds constitute the dominant material input; retreaded tires are gaining share fastest in commercial segments.
Distribution Channel:
Channel structure reflects the tension between traditional wholesale intermediaries and digital disintermediation.
- Tire Dealers:Captive retail networks and independent service centers handle installation and warranty administration. South Carolina and Ohio dealer groups maintain regional density.
- Wholesale Distributors:Regional warehousing operations supply independent repair shops with mixed-brand inventory. Margin pressure intensifies as fleets bypass this tier.
- Online Sales:Direct-to-consumer platforms and fleet procurement portals enable price transparency and centralized contract management. API integration with transportation management software remains incomplete.
- Supermarkets:Mass merchandisers stock economy-tier passenger tires for price-sensitive replacement demand.
Tire dealers retain the largest throughput position; online sales channels are expanding most quickly among national fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel economy mandates and NHTSA safety standards are concentrating tire procurement decisions in states with dense logistics corridors and automotive manufacturing heritage. Regional production clusters align with fleet operator density and OEM supply chain requirements.
Great Lakes Manufacturing Corridor
Detroit-area OEMs specify low-rolling-resistance compounds for standard fitment under EPA corporate average fuel economy standards. NHTSA rollover resistance testing protocols shape sidewall construction requirements for light truck platforms. Akron and Detroit production clusters concentrate vulcanization expertise and steel belt supply for just-in-time delivery to domestic automakers.
Southeast Logistics Belt
E-commerce fulfillment centers in Georgia and South Carolina accelerate replacement intervals for regional delivery fleets. The Department of Transportation's tire fuel efficiency grading system influences inventory priorities at distribution hubs. South Carolina tire manufacturing plants supply drive axle positions to parcel carriers operating dense terminal networks.
Texas-Oklahoma Energy Corridor
Oilfield service fleets consume heavy-duty all-terrain tires for off-highway extraction operations. State-level vehicle inspection requirements in Texas mandate tread depth minimums for commercial registrations. Houston and Dallas-Fort Worth logistics hubs concentrate long-haul fleet maintenance facilities with retreading capabilities.
California Clean Transportation Zone
The Advanced Clean Trucks rule creates specification demand for specialized low-rolling-resistance tires on electric commercial vehicles. California Air Resources Board zero-emission mandates accelerate replacement timing for drayage operators at Los Angeles-Long Beach port complexes. Bay Area technology fleets pilot sensor-embedded intelligent tires for predictive maintenance.
Pacific Northwest Timber and Port Operations
Logging fleets in Oregon and Washington specify severe-service traction tires for unpaved access roads. Port of Seattle and Port of Tacoma container handling equipment drives demand for radial construction with reinforced sidewalls. Seattle-area commercial vehicle inspection programs enforce DOT fuel efficiency grade visibility on replacement purchases.
United States Tire Market Key Industry Players
On the supply side, the industry is consolidated around a handful of integrated manufacturers with captive distribution networks. Three strategic archetypes dominate: premium material science specialists, scale-driven volume producers, and commercial service network operators. Competitive moves concentrate on direct-to-fleet digital platform deployment and backward integration into rubber compound formulation.
Within the premium-tier vector, Michelin exemplifies material science differentiation through sustained OEM supply relationships. Goodyear Tire & Rubber Company anchors the commercial service network archetype with long-haul fleet maintenance infrastructure. Bridgestone Corporation occupies a position emphasizing captive retail and wholesale distributor control across replacement channels.
| Leading Market Players |
|---|
| Continental AG |
| Firestone |
| Goodyear Tire & Rubber Company |
| Toyo Tire Group Global |
| Cooper Tire Company |
| Michelin |
| BF Goodrich |
| Yokohama Rubber Company |
| Bridgestone Corporation |
| Others |
Cost & Logistics Intelligence
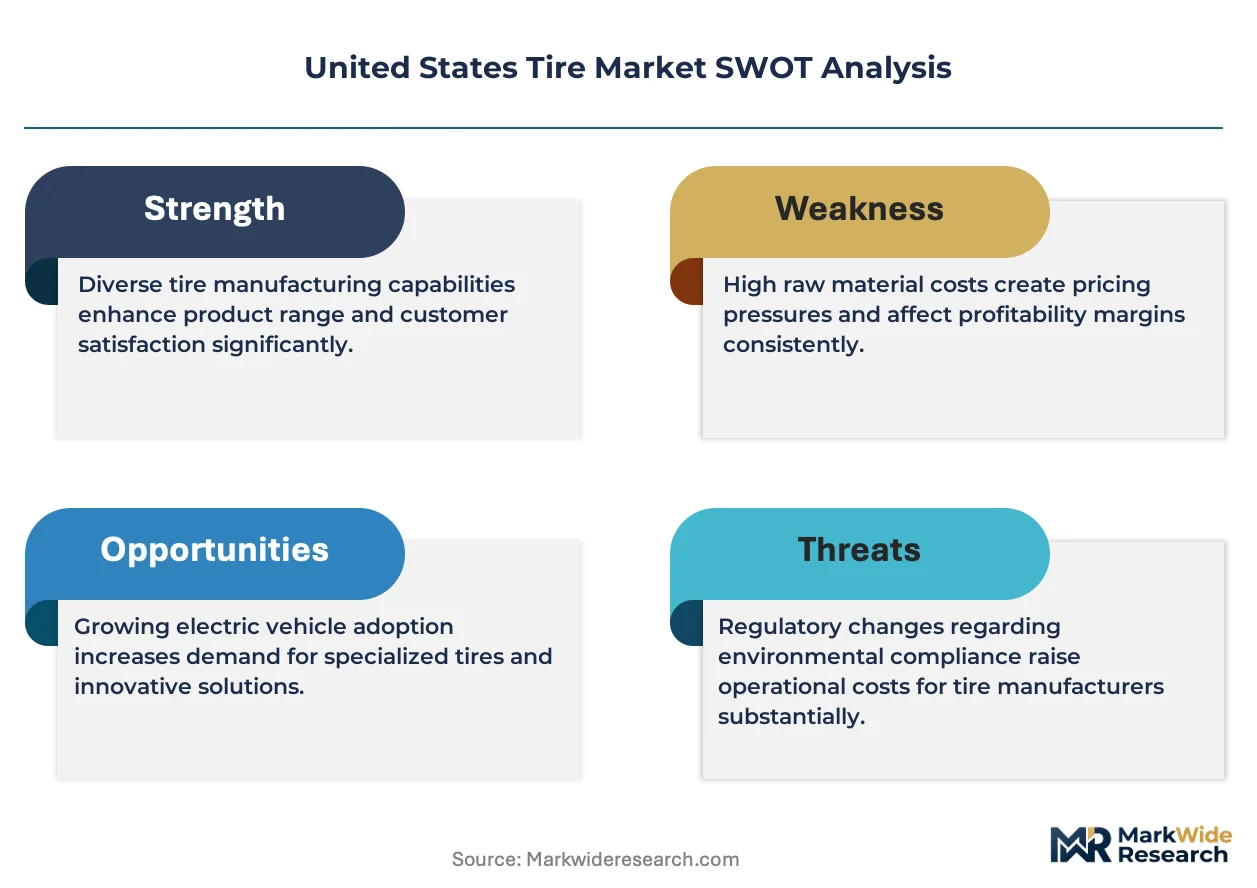
Natural rubber price volatility from Southeast Asian supply disruptions determines both the spread between economy and premium tire tiers and the geographic clustering of vulcanization capacity near domestic steel belt sources. Manufacturers absorb commodity swings through contract structures that tie fleet pricing to raw material indices, compressing margins at the economy tier while preserving premium positioning through material science differentiation.
Pricing Analysis
DOT fuel efficiency certification grade creates the primary spread between economy, standard, and premium tire tiers. Three-tier pricing structure across premium, standard, and economy levels reflects silica compound content, treadwear warranty length, and retreadability guarantees. Pricing pressure stems from retread substitution in commercial fleets, which displaces new tire volume at 40-60% of replacement cost. Independent repair shops exhibit highest price sensitivity due to wholesale distributor markups, while national fleet operators negotiate lifecycle cost guarantees that prioritize predictable total cost of ownership over per-unit acquisition price.
Supply Chain Analysis
Tariff exposure between Southeast Asian natural rubber producers and domestic steel cord mills dominates supply chain risk assessment for United States tire manufacturers. Raw material sourcing draws from Thailand, Indonesia, and Malaysia for latex and elastomers, while high-tensile steel cord production concentrates in Ohio and South Carolina. Single-source vulnerability in domestic steel belt supply constrains radial tire output during mill capacity reductions. Distribution runs through captive retail networks, regional wholesale distributors, and emerging direct-to-fleet digital platforms that disintermediate traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation into national procurement entities has shifted buyer power decisively toward volume purchasers with lifecycle cost modeling capabilities. Three logistics carriers now control the majority of long-haul tire contract negotiations in the Great Lakes and Southeast corridors.
For Market Incumbents: Harden direct-to-fleet digital platform infrastructure to defend against disintermediation by wholesale distributors. Deepen backward integration into silica dispersion chemistry and advanced polymer blending to offset compound formulation talent scarcity in Akron and Detroit. Prioritize API standardization with transportation management software to lock in fleet procurement portal relationships before competitor platform launches. For New Entrants and Emerging Players: Build out specialized low-rolling-resistance tire specifications for electric commercial vehicle platforms under California's Advanced Clean Trucks rule. Target sensor-embedded intelligent tire development for Bay Area technology fleets piloting predictive maintenance systems. Pursue specification wins with regional parcel carriers operating dense terminal networks across Georgia and South Carolina as the most penetrable entry point. For Investors and Strategic Acquirers: The market sits at a fleet-digitization acceleration phase that favors commercial service network operators with predictive maintenance capabilities. Long-term viability rests on capturing replacement tire demand from zero-emission truck platforms and intelligent tire data monetization. Watch for inflection signals in California Air Resources Board zero-emission mandate enforcement timelines at Los Angeles-Long Beach port complexes.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Fleet Digital Platform Deployment | Disintermediates wholesale distributors and captures national account procurement consolidation. |
| Silica-Enhanced Compound Formulation Investment | Meets EPA corporate average fuel economy mandates for low rolling resistance specifications. |
| Sensor-Embedded Intelligent Tire Development | Enables predictive maintenance algorithms that command premium pricing from downtime-sensitive fleets. |
| Retreadable Casing Design Optimization | Preserves replacement volume against drive axle retread substitution in regional trucking fleets. |
| California Zero-Emission Vehicle Specification Capture | Secures early platform wins with electric truck OEMs under Advanced Clean Trucks rule mandates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of NHTSA safety standard filings, EPA fuel economy compliance data, and Department of Transportation tire efficiency grading records. Primary interviews engaged fleet procurement directors, commercial tire R&D technologists, wholesale distribution executives, and OEM platform engineering leads across Detroit, Akron, and South Carolina production clusters. Secondary validation drew from SEC 10-K disclosures of integrated tire manufacturers, American Trucking Associations operational cost surveys, and California Air Resources Board regulatory dockets. Bottom-up volume estimates from segment-level replacement cycle analysis were triangulated against top-down market value reconstructions.
Forecast inputs incorporate vehicle miles traveled projections, e-commerce delivery density expansion across Midwest and Southeast logistics corridors, and NHTSA rollover resistance standard implementation timelines. Segmentation dimensions modeled include product type, end user archetype, material specification, and distribution channel migration patterns across the analysis window. CAGRs were derived from regression analysis of historical replacement volume against fleet utilization rates and regulatory compliance cost pass-through coefficients. Industry-specific forecast inputs encompass commercial fleet electrification adoption curves and retread penetration rate assumptions for drive axle positions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native tire entrants or hyperscaler logistics platforms with captive maintenance networks would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
GCC Tire Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Wheel and Tire Service Equipment Market