
 Car Rental Business Market | 2026-2036
Car Rental Business Market Size, Share, and Industry Trends Forecast 2026-2036
Car Rental Business Market Intelligence
Corporate buyer concentration is pivoting as multinational employers consolidate travel spend with fewer preferred rental suppliers. Enterprise Holdings leverages its integrated fleet management and neighborhood location density to anchor corporate accounts. Hertz Global competes through technology leadership in electric vehicle deployment and digital fleet optimization. Localiza dominates Latin American airport counters and long-term lease structures, sustaining margin pools in corporate and tourist segments.
Car rental business denotes the short-term commercial provision of motorized vehicles to consumers and organizations, typically governed by structured rental agreements specifying duration, mileage limits, insurance terms, and vehicle condition protocols. The service functions as flexible mobility infrastructure for travelers, temporary workforce transport, and fleet gap coverage across industries. SUVs and electric vehicles command expanding share as fleet composition shifts toward higher-margin categories and regulatory compliance. Corporate clients and business travelers represent the most stable demand pools, while online booking platforms and mobile apps capture disproportionate growth in reservation volume.
EPA emissions standards and NHTSA safety mandates in the United States compel fleet operators to accelerate vehicle turnover and adopt cleaner powertrains. The EU Green Deal and F-Gas Regulation in Europe impose parallel decarbonization obligations on rental fleets operating across member states. Stakeholders must monitor regulatory phase-in timelines and decide whether to front-load electrification capital or stagger compliance through leasing structures.
Market Dynamics
Fleet electrification mandates are compressing asset turnover cycles and forcing rental operators to restructure capital deployment around battery-electric vehicle procurement and charging infrastructure buildout.
Growth Catalysts
- EU Green Deal:Binding emissions targets for commercial fleets are accelerating rental operator electrification roadmaps across Germany, France, and the Netherlands.
- Corporate mobility subscriptions:Multinational employers are consolidating travel spend under flexible vehicle-as-a-service contracts rather than fixed-term leases.
- Airport hub density:Germany's concentration of international aviation gateways sustains premium rental throughput and higher-margin business traveler capture.
Market Restraints
- Battery supply concentration:Lithium-ion cell production clusters in China and South Korea expose fleet operators to raw material cost volatility and geopolitical supply risk.
- Residual value uncertainty:Accelerated EV technology cycles and battery degradation curves complicate fleet depreciation modeling and secondary market exit pricing.
- Grid infrastructure gaps:Inadequate fast-charging networks in secondary cities and rural corridors limit EV fleet deployment flexibility outside major metropolitan zones.
Strategic Opportunities
- India's underpenetrated corporate travel market:Low current rental penetration among domestic enterprises and rising business aviation traffic create whitespace for airport-counter expansion.
- Telematics-AI convergence:Real-time vehicle diagnostics combined with predictive maintenance algorithms enable usage-based insurance products and dynamic pricing models.
- US Inflation Reduction Act:Commercial clean vehicle tax credits reduce effective acquisition costs for battery-electric fleet additions through 2032.
Industry Challenges
- EV technician shortage:High-voltage battery servicing and power electronics repair require specialized certifications that remain scarce in traditional automotive maintenance labor pools.
- Legacy reservation system integration:Proprietary fleet management platforms from the 2000s resist API connectivity with modern mobility-as-a-service aggregators and corporate travel management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Rental Business Market |
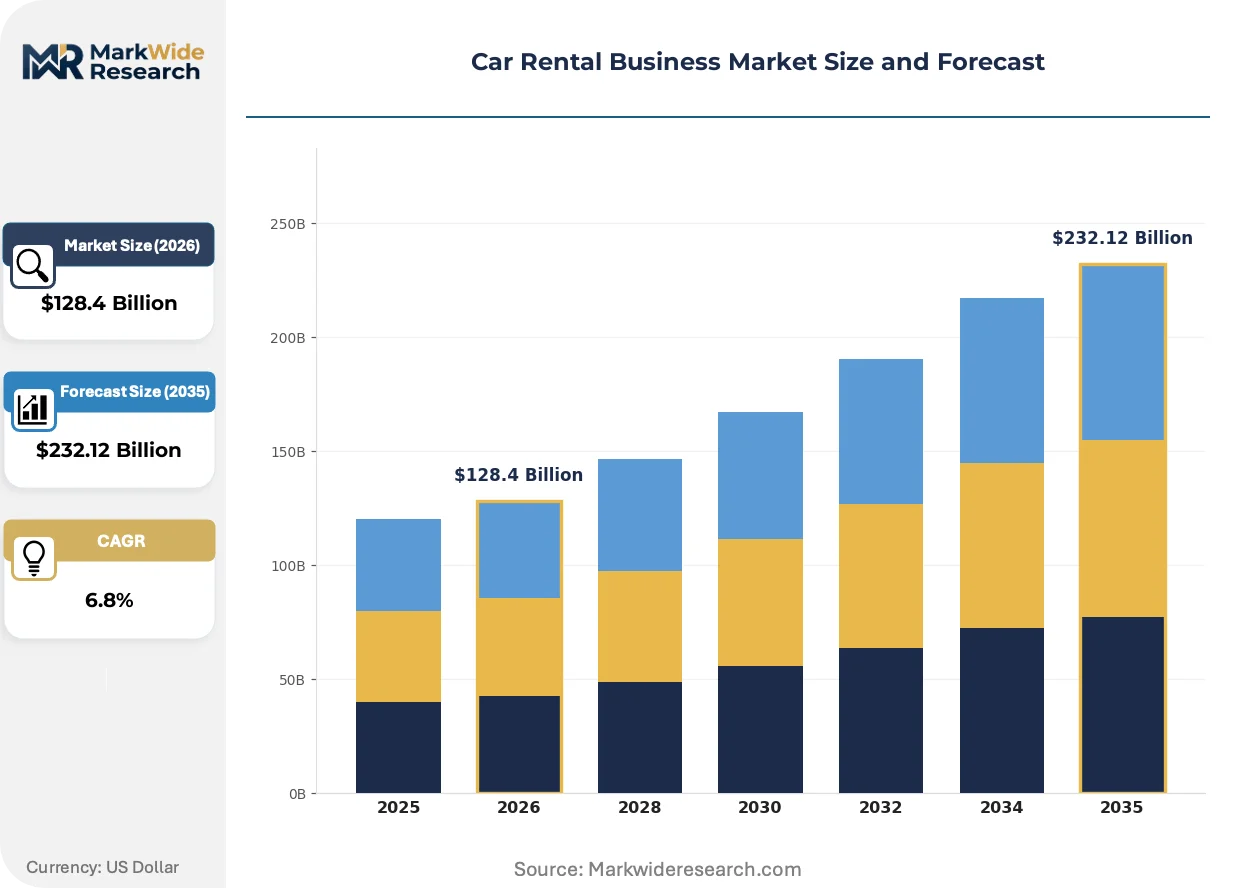
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $232.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Convertible, Minivan, Electric, Luxury Rental Duration: Hourly, Daily, Weekly, Monthly, Long-Term Lease Customer Type: Corporate Clients, Tourists, Local Residents, Business Travelers, Event Organizers Distribution Channel: Online Booking Platforms, Travel Agencies, Airport Counters, Mobile Apps, Walk-in Centers |
| Companies Covered | Sixt, Localiza, Enterprise Holdings, Getaround, Zipcar, Avis Budget Group, Europcar Group, Zoomcar, Hertz Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Rental Business Market Strategic Shifts & Innovations
Digital fleet optimization tools are displacing manual dispatch and static pricing models across the rental value chain, compressing turnaround times and enabling real-time yield management.
Connected vehicle telematics is expanding into predictive maintenance and dynamic fleet rebalancing. Airport operators and urban corporate fleets are adopting these systems fastest. The technology is expanding into usage-based insurance products and automated damage assessment workflows.
NHTSA safety mandates and EPA emissions standards are forcing accelerated vehicle turnover in US rental portfolios. Fleet operators must retire internal combustion assets faster than historical depreciation schedules. California's Advanced Clean Trucks regulation is creating the strictest compliance corridor for zero-emission commercial vehicle procurement.
Business traveler booking behavior is fragmenting across mobile-native platforms and corporate travel management system integrations. Traditional call-center and counter-based reservation capture is losing share to app-based instant booking with digital key handoff. Germany and the United Kingdom show the most advanced platform consolidation among multinational corporate accounts.
Car Rental Business Market Segmentation
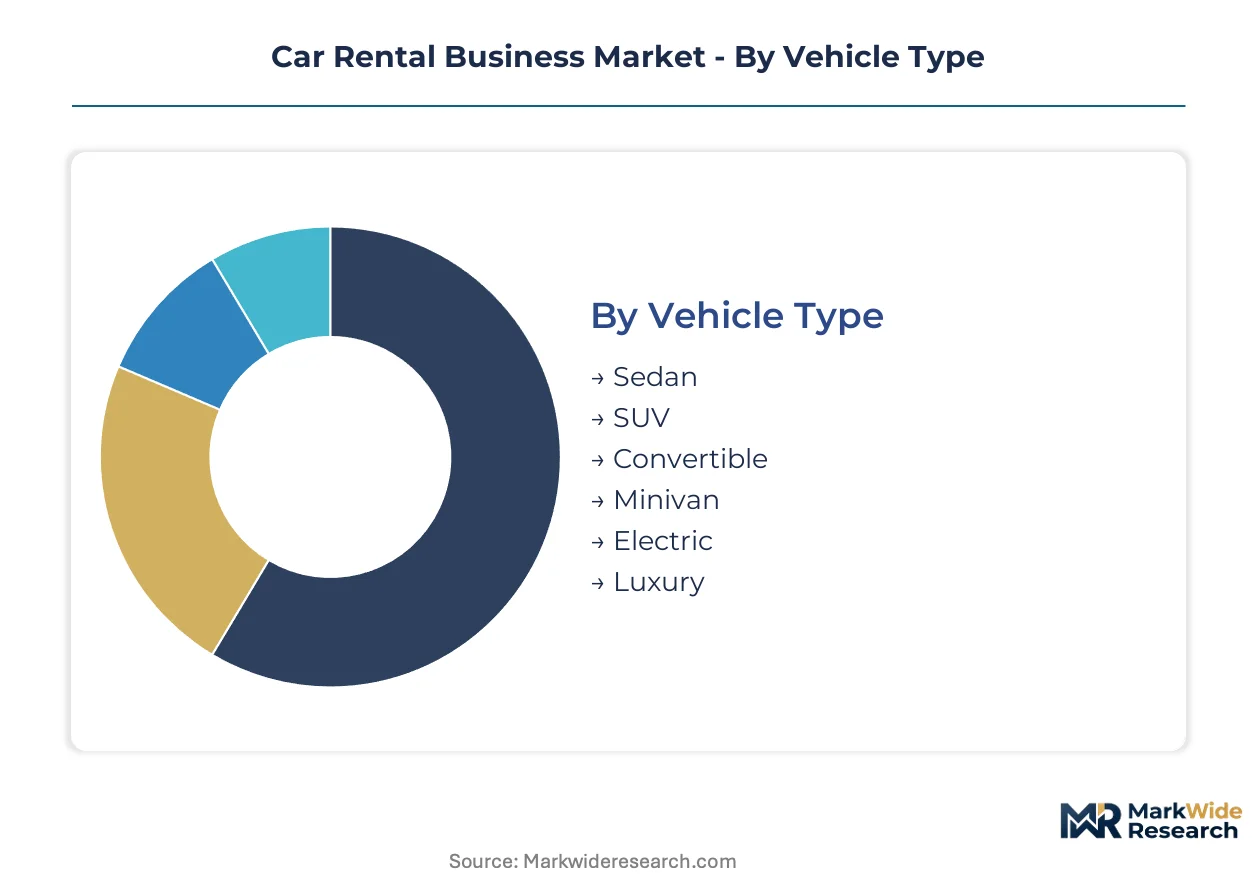
Car rental segmentation reveals how fleet composition, booking patterns, and customer economics split across distinct operational models. Each axis—vehicle specification, contract length, buyer identity, and channel—carries different margin profiles and capital intensity requirements.
Vehicle Type:
Powertrain technology and cabin architecture define depreciation curves, utilization rates, and regulatory compliance obligations across fleet portfolios.
- Sedan:Compact and mid-size four-door configurations dominate airport shuttle contracts and corporate ground transportation programs. Fleet managers in Germany and France favor sedans for their predictable residual values and established maintenance networks.
- SUV:Elevated ride height and expanded cargo capacity command rate premiums in leisure destinations and family travel corridors. Demand concentrates in Alpine tourism zones and North American suburban markets where all-weather capability justifies higher daily tariffs.
- Convertible:Seasonal deployment in Mediterranean coastal markets and Florida beach destinations drives peak-summer utilization. Operators face storage costs and weather-dependent revenue volatility.
- Minivan:Multi-passenger configurations serve group travel and film production logistics. Airport operators in Orlando and Los Angeles maintain dedicated minivan pools for family vacation segments.
- Electric:Battery-electric powertrains align with EU Green Deal fleet mandates and urban low-emission zone access. Charging infrastructure gaps in secondary cities constrain deployment flexibility outside metropolitan cores.
- Luxury:Premium marques target executive transport and high-net-worth leisure segments. Daily rate multiples of 4-6x over standard fleet justify specialized insurance and concierge handoff protocols.
Sedan leads on scale; electric gains share fastest.
Rental Duration:
Contract length determines fleet turnover velocity, pricing granularity, and customer relationship depth.
- Hourly:Micro-mobility formats serve urban errand-running and last-mile logistics. Car-sharing operators in Amsterdam and Stockholm deploy hourly billing for registered members.
- Daily:Standard vacation and business trip format with fixed 24-hour billing cycles. Airport counters capture the majority of daily volume through walk-up and pre-reserved channels.
- Weekly:Extended leisure travel and temporary workforce housing support seven-day rate discounts. Corporate travel policies often cap reimbursement at weekly rates for assignments under thirty days.
- Monthly:Interim housing transitions and project-based consulting engagements drive thirty-day contracts. Fleet operators prefer monthly structures for their reduced transaction costs and utilization visibility.
- Long-Term Lease:Multi-year vehicle-as-a-service contracts replace traditional corporate fleet ownership. Multinational employers in Germany and the Netherlands are consolidating mobility spend under flexible subscription frameworks.
Long-term lease leads on contract value; hourly climbs the fastest.
Customer Type:
Buyer identity shapes rate negotiation leverage, ancillary attachment rates, and loyalty program economics.
- Corporate Clients:Managed travel accounts with negotiated rate schedules and consolidated billing. Procurement teams at pharmaceutical and consulting firms demand telematics integration and carbon reporting.
- Tourists:Leisure travelers booking through online travel agencies and package tour operators. Seasonal demand spikes in July and December strain fleet availability at Mediterranean and Caribbean gateways.
- Local Residents:Neighborhood renters addressing vehicle repair gaps or special occasion needs. Urban operators in Berlin and Madrid maintain satellite locations for resident convenience.
- Business Travelers:Individual road warriors with employer-mandated preferred supplier relationships. Mobile app penetration is highest among this segment for instant booking and digital key retrieval.
- Event Organizers:Conference coordinators and wedding planners requiring coordinated multi-vehicle logistics. Fleet allocation complexity rises with group size and ceremony timing precision.
Corporate clients lead on revenue stability; business travelers expand most quickly.
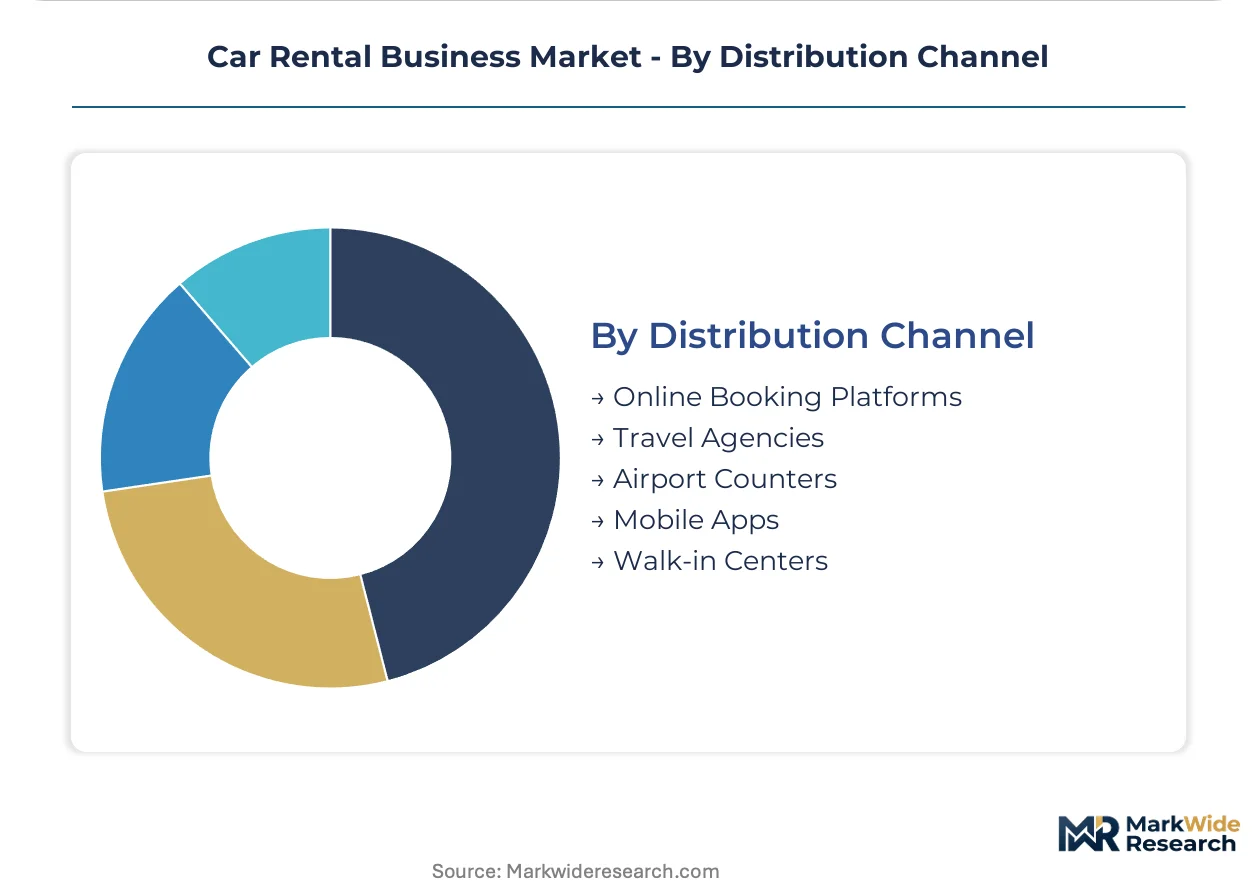
Distribution Channel:
Booking pathway determines customer acquisition cost, rate transparency, and operational integration requirements.
- Online Booking Platforms:Aggregator websites enable price comparison across multiple suppliers. Commission structures of 15-25 percent compress net revenue per transaction.
- Travel Agencies:Corporate and leisure intermediaries bundle rental with air and hotel packages. TMC integrations in London and Frankfurt maintain direct API connections to fleet management systems.
- Airport Counters:Physical presence at aviation terminals captures impulse demand and flight-disrupted travelers. Counter staffing costs and concession fees elevate breakeven thresholds.
- Mobile Apps:Native applications with digital key handoff and real-time fleet visibility. Younger demographics and urban professionals show highest adoption velocity.
- Walk-in Centers:Neighborhood locations serving local residents without advance reservation. Lower real estate costs support competitive daily rates against airport premiums.
Airport counters lead on volume concentration; mobile apps gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fleet management talent concentrates in Germany, the United States, and China, anchoring operational excellence across the three dominant rental geographies.
Germany
Business traveler density and airport hub concentration sustain premium rental throughput. The EU Green Deal mandates binding emissions reductions for commercial fleets operating across member states. Frankfurt and Munich anchor the densest corporate account networks in Europe.
United States
Corporate mobility subscriptions and airport leisure demand drive dual revenue streams. EPA emissions standards and NHTSA safety mandates accelerate fleet turnover schedules. Los Angeles and Dallas-Fort Worth host the largest consolidated rental facility footprints.
China
Urban car-sharing platforms and domestic tourism recovery expand addressable demand. MIIT new energy vehicle quotas pressure operators toward battery-electric procurement. Shanghai and Shenzhen lead charging infrastructure density and smart fleet deployment.
India
Underpenetrated corporate travel and rising business aviation create whitespace for airport-counter expansion. BIS automotive standards and state-level EV policies shape fleet composition decisions. Mumbai and Bangalore concentrate technology-enabled rental platform headquarters.
Brazil
Long-term lease structures and tourist corridor demand sustain margin pools in corporate and leisure segments. ANVISA commercial vehicle regulations and state environmental codes influence fleet specifications. São Paulo and Rio de Janeiro dominate airport rental counter presence.
Car Rental Business Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Three to five integrated holding companies anchor corporate account relationships through neighborhood location density and fleet scale. Strategic archetypes include airport-dominant operators, technology-enabled sharing platforms, and subscription-based fleet managers. Consolidation through M&A and electrification-focused fleet renewal represent the dominant competitive vectors reshaping market structure.
Among Germany-based operators, Sixt exemplifies the premium-tier airport specialist archetype through its European counter network. Enterprise Holdings occupies a position as the integrated North American conglomerate with neighborhood density advantages. Localiza anchors the Latin American long-term lease specialist tier. These three represent distinct strategic postures: premium service differentiation, integrated scale economics, and regional emerging-market penetration.
| Leading Market Players |
|---|
| Sixt |
| Localiza |
| Enterprise Holdings |
| Getaround |
| Zipcar |
| Avis Budget Group |
| Europcar Group |
| Zoomcar |
| Hertz Global |
| Others |
Cost & Logistics Intelligence
Certified fleet maintenance technicians concentrate in Germany, the United States, and Japan, where labor-cost differentials of 40-60 percent against emerging markets widen pricing-tier spreads between premium airport counters and economy neighborhood locations.
Pricing Analysis
Bundled subscription services versus unbundled transactional rentals split pricing architecture across the car rental business market. Three-tier pricing structure across premium, standard, and economy levels reflects vehicle specification, loyalty status, and ancillary attachment rates. Price differentiation rests on airport concession premiums versus neighborhood location discounts, with corporate volume contracts commanding 15-25 percent rate compression. Business travelers show lowest price sensitivity due to employer reimbursement policies, while leisure tourists and local residents drive competitive rate shopping.
Supply Chain Analysis
Manufacturer certification and fleet qualification requirements gate vehicle procurement decisions for rental operators. OEM supply concentrates in Germany, Japan, and the United States for internal combustion platforms, while China, South Korea, and Hungary anchor battery-electric vehicle sourcing. Lithium carbonate, semiconductor chips, and automotive-grade steel constitute critical input dependencies. Single-source vulnerability in battery cell production exposes fleet operators to raw material cost volatility. Distribution runs through OEM-direct fleet sales, dealer network volume programs, and remarketing auction channels for secondary vehicle disposition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car rental business market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France run 30-40 percent above equivalent fleet investments in India and Brazil, creating margin expansion opportunities for operators with multi-country footprints.
For Market Incumbents: Anticipate margin compression from mobility-as-a-service aggregators and corporate travel platform disintermediation by deepening API integrations with travel management systems and accelerating neighborhood location density in underserved metropolitan zones. Fleet electrification roadmaps must front-load charging infrastructure partnerships to defend position against pure-play EV entrants. For New Entrants and Emerging Players: Capture whitespace in India's underpenetrated corporate travel segment and Brazil's long-term lease subscription market where incumbent coverage gaps persist. Airport-counter expansion in secondary Indian cities offers lowest competitive intensity. Go-to-market positioning should emphasize telematics-enabled carbon reporting for ESG-mandated enterprise accounts. For Investors and Strategic Acquirers: Valuations sit cheapest among technology-enabled sharing platforms with fleet-light asset models relative to integrated operators with heavy vehicle ownership. Long-term viability over the next decade hinges on electrification execution and software platform differentiation. Watch battery-electric vehicle residual value performance as the critical inflection signal for fleet depreciation model sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Roadmap | EU Green Deal mandates accelerate zero-emission vehicle procurement timelines across German and French operations. |
| Charging Infrastructure Partnership | Fast-charging network access in secondary cities removes deployment constraints for battery-electric fleet expansion. |
| Telematics Platform Integration | Real-time vehicle diagnostics enable usage-based insurance products and dynamic yield management algorithms. |
| Corporate Mobility Subscription | Flexible vehicle-as-a-service contracts capture multinational employer travel spend consolidation trends. |
| Neighborhood Location Density | Urban satellite counters reduce customer acquisition costs against airport concession fee structures. |
Research Approach
Multiple input streams — fleet operator procurement directors, corporate travel managers, automotive OEM fleet sales executives, and charging infrastructure developers — were reconciled against customs vehicle import records, airport concession filings, SEC 10-K disclosures, and EU emissions registry data. Bottom-up fleet size estimates by operator combined with top-down addressable mobility spend calculations to triangulate market dimensions.
Data-stream reconciliation across primary stakeholder interviews and secondary source validation anchored the analytical framework. Segmentation modeling incorporated vehicle type, rental duration, customer archetype, and distribution channel dimensions. CAGRs were derived from fleet growth trajectories, replacement cycle compression, and electrification penetration curves. Battery-electric vehicle adoption rates and corporate subscription contract velocity served as industry-specific forecast inputs across the projection horizon.
Regulatory phase-in timeline acceleration, battery supply disruption, and corporate travel policy reversal are the dominant revision risks to modeled outcomes. Deviation in EU Green Deal enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Vehicle Subscription Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Europe Car Wash Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
France Car Rental Market
Automotive Services
Car Subscription Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
Automotive Register Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Europe MRO Distribution Market