
 Automotive Subscription Services Market | 2026-2036
Automotive Subscription Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Subscription Services Market Analysis
Modular bundling of insurance, maintenance, and charging into single monthly fees is broadening buyer choice beyond traditional financing. BMW Group leverages its captive finance arm to sustain integrated subscription-to-purchase pathways. Mercedes-Benz Mobility anchors premium tier positioning with all-inclusive EV subscription tiers. Volvo Cars differentiates through transparent pricing and flexible swap terms.
Automotive subscription services constitute contractual mobility arrangements where users pay recurring fees for vehicle access without ownership transfer, typically encompassing registration, insurance, maintenance, and roadside assistance in one bundled payment. Their primary commercial purpose is to convert fixed asset costs into variable operating expenses while capturing residual value through manufacturer-controlled remarketing. Flexible subscription models command premium positioning due to short-term commitment structures, while electric vehicle segments attract disproportionate operator investment as battery depreciation curves reshape fleet economics. Online platforms capture growing transaction share as direct digital onboarding reduces friction compared to legacy dealership workflows.
The EU Green Deal and F-Gas Regulation shape fleet composition mandates, pushing subscription operators toward zero-emission vehicle quotas. Germany's KBA enforces type-approval standards that subscription providers must navigate for multi-brand fleet registrations. Stakeholders must monitor how emissions credit trading interacts with subscription fleet turnover rates to optimize asset depreciation timing.
Market Dynamics
Fleet-as-a-service economics are compressing vehicle ownership cycles as operators exploit centralized remarketing control and modular cost bundling to displace traditional financing structures.
Growth Catalysts
- EU Green Deal fleet mandates:Zero-emission vehicle quotas force subscription operators to accelerate electrification, creating standardized EV procurement at scale.
- Digital onboarding platforms:Direct consumer interfaces eliminate dealership friction, reducing customer acquisition costs and contract turnaround time.
- Germany's infrastructure density:Dense charging networks and KBA type-approval efficiency enable multi-brand fleet registration velocity unmatched elsewhere in Europe.
Market Restraints
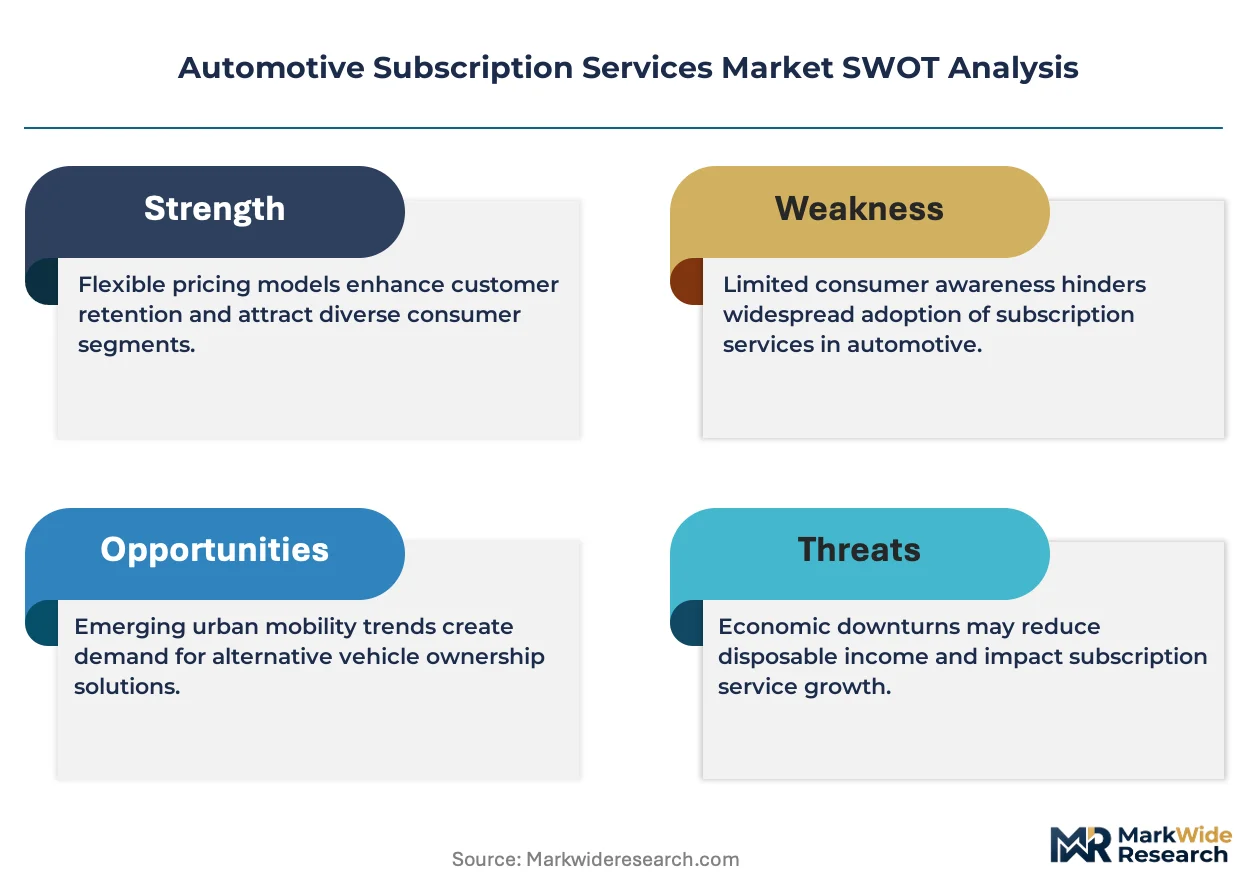
- Battery depreciation volatility:Uncertain residual value curves for lithium-ion packs constrain fleet financing terms and insurer appetite.
- KBA multi-brand registration complexity:German type-approval requirements create administrative friction for operators sourcing across OEMs.
- Used vehicle price sensitivity:Remarketing channel concentration in wholesale auctions limits pricing power during fleet turnover events.
Strategic Opportunities
- Corporate fleet electrification mandates:ESG reporting requirements under CSRD are pushing enterprises toward subscription models that outsource compliance risk.
- Telematics-insurance convergence:Real-time driving data integration enables dynamic pricing tiers that capture safer driver segments.
- France's mobility budget legislation:Employer-subsidized flexible transport allowances expand addressable subscriber pools beyond traditional lessees.
Industry Challenges
- Cross-border fleet logistics:Harmonizing vehicle registration, insurance portability, and maintenance networks across EU member states strains operational systems.
- Residual value forecasting:Battery chemistry evolution and policy-driven obsolescence risk complicate asset depreciation modeling for multi-year contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Subscription Services Market |
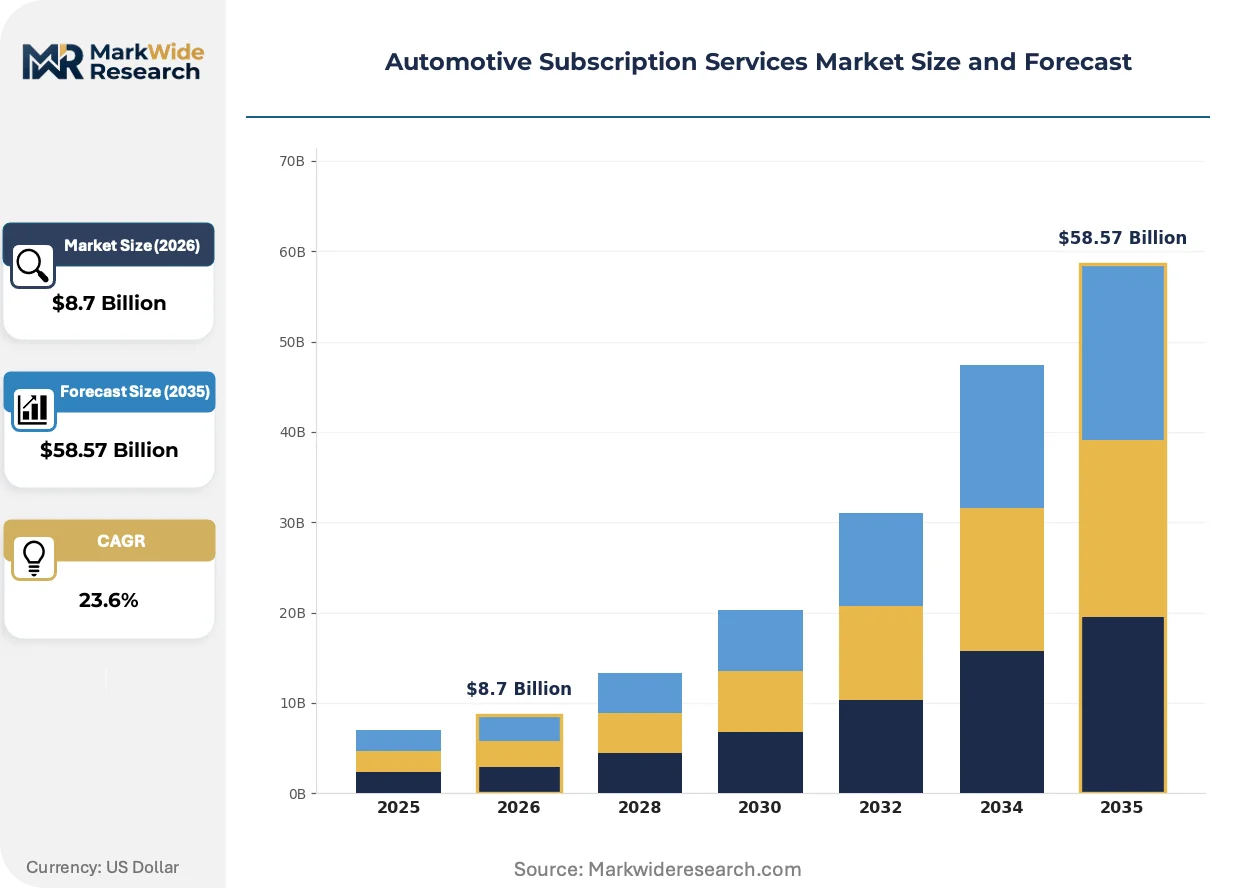
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Subscription, Flexible Subscription, Long-term Lease, Vehicle Ownership End User: Business Users, Individuals, Fleet Operators, Ride-sharing Services Vehicle Type: Luxury Cars, Electric Vehicles, SUVs, Sedans Distribution Channel: Online Platforms, Dealerships, Mobile Apps, Direct Sales |
| Companies Covered | Mercedes-Benz Mobility, Volkswagen Group, Sixt, FINN, Carvolution, Volvo Cars, BMW Group, Hertz Global Holdings, Cox Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Subscription Services Market Emerging Trajectories
Telematics integration and embedded finance architectures are restructuring how subscription operators capture customer lifetime value and manage fleet risk exposure.
Artificial intelligence-driven predictive maintenance is absorbing operational complexity across subscription fleets. Operators deploy machine learning models trained on aggregated vehicle sensor data to preempt component failures. Fleet managers are adopting these systems to compress unplanned downtime and extend service intervals. This capability is absorbing traditional maintenance cost unpredictability into fixed operational budgets.
France's ANSM-aligned mobility subsidy frameworks are accelerating employer-sponsored subscription adoption. The country's mobility budget regulations permit pre-tax salary allocation toward flexible vehicle access. Corporate HR departments are restructuring benefits packages to capture these fiscal incentives. Urban commuter segments in Paris and Lyon show highest enrollment velocity.
Usage-based contract structures are displacing fixed-term subscriptions among price-sensitive demographics. Young professionals and gig economy workers favor mileage-capped tiers with swap flexibility over traditional lease commitments. Digital-native platforms capture this demand through app-based vehicle selection and instant contract modification. Spanish and Italian metropolitan markets exhibit strongest behavioral shift toward this model.
Automotive Subscription Services Market Segmentation
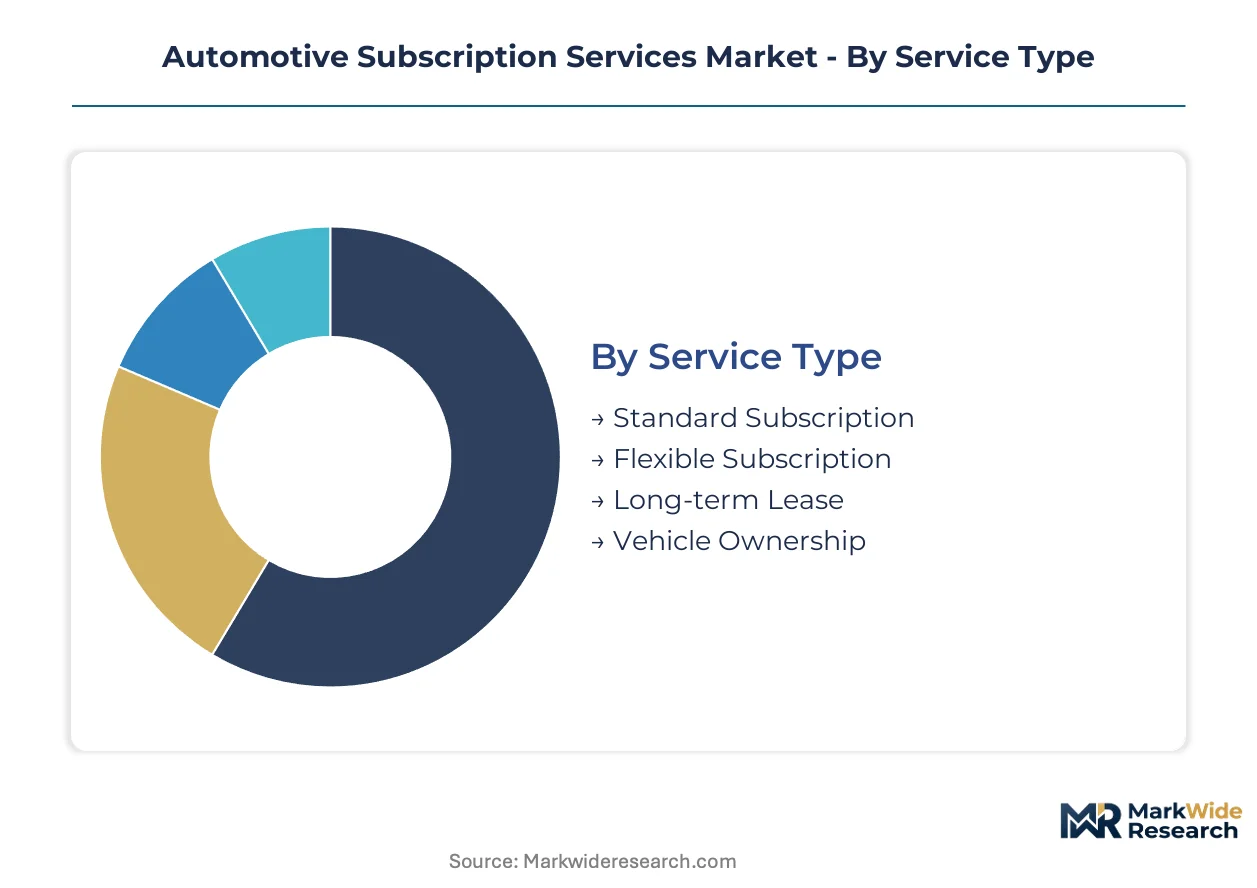
Automotive subscription segmentation reveals divergent profitability profiles across commitment structures and buyer types. Fleet operators and digital channels command disproportionate operator investment due to scale economics and customer acquisition efficiency.
Service Type:
Commitment duration and swap flexibility separate buyers seeking cost predictability from those prioritizing optionality.
- Flexible Subscription:Short-term contracts with vehicle swap rights and mileage-adjustable tiers. Corporate procurement teams in Germany favor this structure for project-based fleet needs under CSRD reporting pressure.
- Standard Subscription:Fixed monthly fees covering insurance, maintenance, and registration with 6-12 month minimum terms. Individual subscribers in French urban clusters gravitate toward this tier for budget stability under mobility budget legislation.
- Long-term Lease:Extended commitments resembling traditional financing without ownership transfer.
- Vehicle Ownership:Subscription-to-purchase pathways converting trial users into buyers.
Volume sits with Standard Subscription; growth tilts toward Flexible Subscription.
End User:
Procurement sophistication and utilization intensity determine service tier selection and contract structuring.
- Fleet Operators:Centralized procurement of multi-vehicle portfolios with unified telematics and maintenance scheduling. German logistics firms exploit fleet-as-a-service models to convert fixed asset costs into operating expenses.
- Business Users:Employer-subsidized individual subscriptions with tax-optimized salary sacrifice structures. French mobility budget frameworks accelerate enrollment among Paris-based professionals.
- Individuals:Direct consumer subscriptions without employer intermediation.
- Ride-sharing Services:High-utilization fleet partnerships with rapid vehicle rotation requirements.
Revenue concentrates with Fleet Operators; expansion accelerates fastest among Business Users.
Vehicle Type:
Depreciation curves and infrastructure readiness shape fleet composition and geographic rollout sequencing.
- Electric Vehicles:Battery-electric powertrains with bundled charging access and residual value guarantees. EU Green Deal mandates push subscription operators toward zero-emission quotas, concentrating procurement in Germany's dense charging corridor.
- Luxury Cars:Premium marques with concierge service layers and inclusive insurance. Mercedes-Benz Mobility anchors this tier through captive finance integration and all-inclusive EV offerings.
- SUVs:Family-oriented utility vehicles with elevated monthly fees reflecting higher acquisition costs.
- Sedans:Entry-level and mid-market four-door configurations for cost-conscious subscribers.
Deployment tilts toward Electric Vehicles; margin capture peaks in Luxury Cars.
Distribution Channel:
Customer acquisition cost and contract velocity separate digital-native platforms from legacy dealership networks.
- Online Platforms:Direct-to-consumer interfaces with instant credit approval and vehicle selection. Spanish and Italian metro markets show strongest behavioral shift toward app-based onboarding.
- Mobile Apps:Smartphone-native subscription management with real-time swap requests and usage tracking. Young professionals favor mileage-capped tiers with instant contract modification.
- Dealerships:Physical retail touchpoints with test drive facilitation and walk-in conversion.
- Direct Sales:OEM-captive subscription programs with integrated purchase pathways.
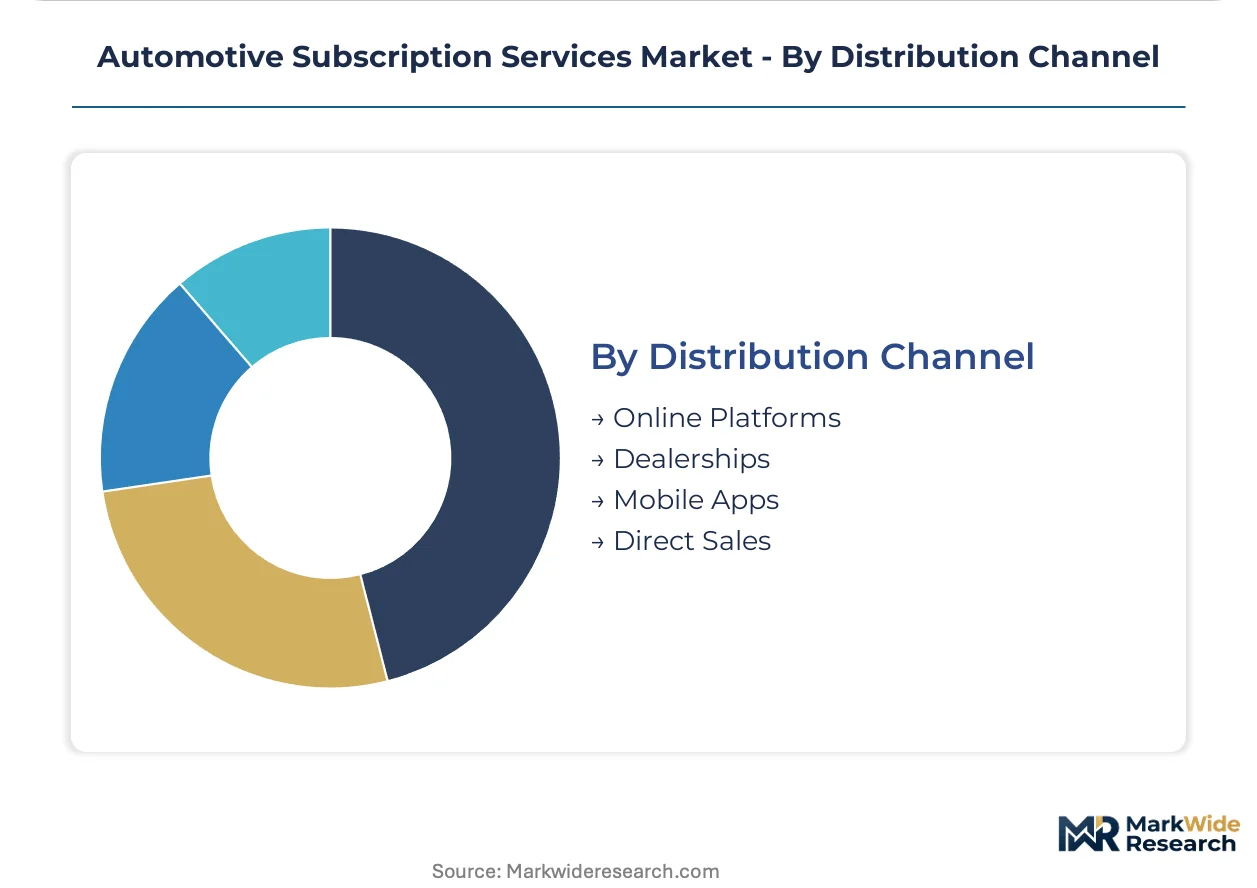
Transaction share migrates toward Online Platforms; Mobile Apps climb the fastest among under-35 demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of subscription fleet assets concentrates in Germany and the United States, while consumption clusters in European urban corridors with dense charging infrastructure and employer mobility benefit programs.
Germany
Corporate procurement teams under CSRD reporting pressure drive fleet-as-a-service adoption, converting fixed asset costs into operating expenses. KBA type-approval standards streamline multi-brand fleet registration velocity. Munich and Stuttgart host OEM-captive subscription programs with integrated purchase pathways.
France
Paris-based professionals exploit employer-subsidized mobility budget frameworks permitting pre-tax salary allocation toward flexible vehicle access. ANSM-aligned subsidy structures accelerate enrollment in corporate HR benefit restructuring. Lyon and Marseille metropolitan clusters exhibit strongest behavioral shift toward app-based onboarding.
United States
Digital-native platforms capture transaction share through direct consumer interfaces reducing customer acquisition friction compared to legacy dealership workflows. State-level emissions mandates in California and New York push subscription operators toward zero-emission fleet quotas. Los Angeles and New York City concentrate ride-sharing fleet partnerships with rapid vehicle rotation requirements.
United Kingdom
London's congestion charging zone and ultra-low emission standards reshape fleet composition toward battery-electric powertrains with bundled charging access. Corporate ESG reporting requirements under UK Sustainability Disclosure Standards push enterprises toward subscription models outsourcing compliance risk. Birmingham and Manchester logistics corridors expand fleet-as-a-service procurement for project-based commercial needs.
Spain
Barcelona and Madrid metropolitan markets demonstrate strongest behavioral shift toward usage-based contract structures with mileage-capped tiers and instant swap flexibility. Young professionals and gig economy workers favor digital-native platforms over traditional lease commitments. Iberian Peninsula charging corridor density supports electric vehicle subscription scaling.
Automotive Subscription Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning structures. OEM-captive finance arms anchor premium segments through integrated subscription-to-purchase pathways, while independent mobility platforms capture price-sensitive demographics through digital-first onboarding. Three archetypes dominate: manufacturer-controlled captives, fleet-as-a-service aggregators, and technology-enabled pure-plays. Competitive moves concentrate on telematics-insurance convergence and cross-border fleet logistics harmonization.
Among German-based OEM captives, Mercedes-Benz Mobility and BMW Group exemplify integrated finance arm structures, while Volvo Cars represents Scandinavian transparent pricing differentiation. These three occupy positions spanning premium-tier all-inclusive EV offerings through flexible swap-term positioning.
| Leading Market Players |
|---|
| Mercedes-Benz Mobility |
| Volkswagen Group |
| Sixt |
| FINN |
| Carvolution |
| Volvo Cars |
| BMW Group |
| Hertz Global Holdings |
| Cox Automotive |
| Others |
Supply Flow & Price Mechanics
EU Green Deal zero-emission vehicle quotas gate qualified supply access and premium-tier pricing power for subscription operators, concentrating procurement leverage among OEM-captive finance arms with electrified fleet portfolios while independent platforms face margin compression from battery depreciation volatility and residual value uncertainty.
Pricing Analysis
Margin tightening in flexible subscription tiers reflects battery depreciation volatility and insurer risk aversion compressing financing terms. Three-tier pricing structure across premium all-inclusive EV offerings, standard bundled maintenance tiers, and economy mileage-capped entry points separates Mercedes-Benz Mobility's concierge positioning from digital-native platform cost leadership. Cost-down pressure on economy tiers accelerates because gig economy workers and young professionals prioritize swap flexibility over brand prestige. Fleet operators show least price sensitivity due to CSRD-mandated ESG outsourcing, while individual subscribers in Spanish and Italian metro markets exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in German automotive manufacturing clusters and South Korean battery production hubs concentrate qualified technician pools for fleet maintenance and battery pack assembly. Supply draws from Germany for OEM-captive vehicle sourcing, South Korea for lithium-ion cell production, and China for charging infrastructure components. Raw material dependencies span lithium carbonate, cobalt sulfate, and semiconductor-grade silicon wafers. Single-source vulnerability in battery cell supply chains creates fleet procurement risk during contract renegotiation cycles. Distribution runs through centralized fleet hubs in Munich, Stuttgart, and Paris with last-mile digital onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive subscription services constitute a consolidation play as battery depreciation volatility and residual value forecasting complexity force capital-constrained independents toward acquisition or exit.
For Market Incumbents: Cement multi-brand fleet scale advantages through backward integration into captive charging infrastructure and telematics platforms. Deepen KBA type-approval expertise as administrative moat against cross-border entrants. Prioritize CSRD-aligned corporate procurement relationships to lock in fleet-as-a-service contracts before compliance deadlines tighten.
For New Entrants and Emerging Players: Capture mobility budget-enabled business user segments in French urban clusters where employer subsidy frameworks reduce customer acquisition friction. Target usage-based contract structures in Barcelona and Madrid metro markets where behavioral shift toward mileage-capped tiers outpaces incumbent platform adaptation. Deploy app-native onboarding with instant credit approval to outflank legacy dealership workflows.
For Investors and Strategic Acquirers: OEM-captive finance arm telematics integration announcements are the leading indicator that fleet risk management capabilities are separating viable operators from capital-burning growth stories. Five-to-ten year viability hinges on residual value forecasting sophistication and cross-border logistics harmonization. Target acquisition profiles center on digital-native platforms with proven swap-flexibility retention rates and established charging network partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Insurance Convergence | Real-time driving data integration enables dynamic pricing tiers capturing safer driver segments for Mercedes-Benz Mobility. |
| Cross-Border Fleet Logistics Harmonization | Unified vehicle registration and insurance portability across EU member states reduces operational friction for German fleet operators. |
| Battery Supply Agreement Structuring | Long-term cell offtake contracts with South Korean producers stabilize procurement costs amid lithium price volatility. |
| Charging Infrastructure Partnership | Strategic alliances with Ionity and Fastned secure bundled charging access differentiating premium EV subscription tiers. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities extend fleet asset lifecycles and enable feature subscription revenue streams for BMW Group. |
Methodological Framework
Trade association filings, EU regulatory databases, and vehicle registration statistics formed the secondary backbone, cross-referenced against primary interviews with fleet procurement directors, OEM platform engineers, captive finance strategy leads, and charging infrastructure operators. Bottom-up triangulation aggregated subscription contract volumes by service tier and propulsion type, while top-down validation referenced macro fleet electrification trajectories under EU Green Deal mandates.
Historical trendline analysis of fleet turnover rates, battery depreciation curves, and telematics adoption velocities established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type commitment structures, end-user procurement sophistication, vehicle propulsion architecture, and distribution channel friction coefficients. CAGRs derived from regression analysis of fleet-as-a-service penetration rates against CSRD compliance timelines and charging infrastructure density metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery chemistry evolution, used EV price discovery mechanisms, and cross-border regulatory harmonization progress. Forecasts reflect documented assumptions regarding EU emissions credit trading interactions with fleet turnover timing. Material deviation in lithium supply contract renegotiations or KBA multi-brand registration policy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Mobility Scooters Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Automotive Register Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
US Car Wash Services Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Tow Truck Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Cab Services Market
Automotive Services
Car Wash Services Market