
 Automotive Performance Tuning and Engine Remapping Services Market | 2026-2036
Automotive Performance Tuning and Engine Remapping Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Performance Tuning and Engine Remapping Services Market Analysis
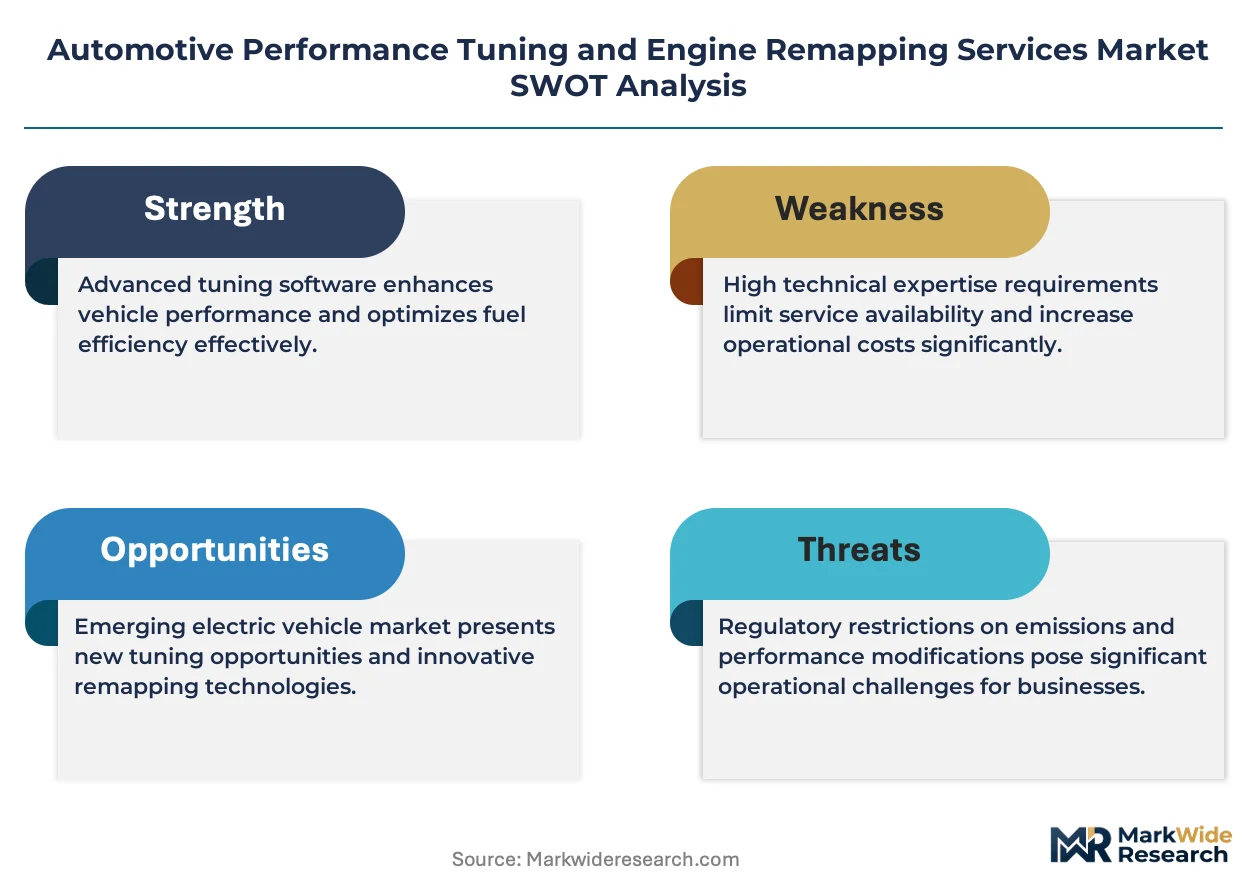
Carbon fiber is rebalancing component economics across intake and exhaust systems as tuners substitute heavier metals. Brembo leverages ceramic-composite expertise to dominate high-performance braking upgrades. COBB Tuning sustains software-led differentiation through proprietary Accessport ecosystems. Akrapovič anchors titanium exhaust specialization with controlled manufacturing scale in European and Asian supply chains.
Automotive performance tuning and engine remapping services encompass calibration of engine control unit parameters—air-fuel ratios, ignition timing, boost pressure thresholds, and torque limiters—to extract power gains or efficiency improvements without hardware replacement. Dyno testing validates wheel horsepower and torque curves against baseline manufacturer specifications, ensuring safe operational margins. Software remapping captures the largest margin pool as flash-based ECU reprogramming requires minimal physical inventory, while chip tuning retains niche demand among legacy vehicles with socketed PROM modules. Racing teams concentrate spending on custom software stacks with real-time data logging integration.
EPA enforcement actions against defeat devices shape product legality boundaries for United States operators, while EU F-Gas Regulation and CE marking requirements govern refrigerant-based performance cooling modifications in Europe. Germany's KBA type-approval framework creates compliance barriers that favor established tuners with homologation capabilities. Stakeholders must monitor evolving OBD-III mandates and emissions-test tampering penalties to calibrate R&D investment between power extraction and regulatory defensibility.
Market Dynamics
EPA enforcement actions against defeat devices and the impending OBD-III mandate are compressing product development timelines while forcing tuners to bifurcate R&D between power extraction and emissions compliance. This regulatory pressure sits at the center of market restructuring.
Growth Catalysts
- Fleet operator ECU adoption:Commercial vehicle managers deploy engine remapping to extract fuel efficiency gains from existing diesel powertrains without capital replacement cycles.
- F-Gas Regulation:EU refrigerant-based performance cooling modifications face stricter containment standards, creating upgrade demand for compliant aftermarket thermal management systems.
- Carbon fiber substitution:Intake and exhaust system fabricators replace aluminum and steel with composite architectures to reduce unsprung mass and improve throttle response.
Market Restraints
- Titanium supply concentration:Akrapovič and limited European-Asian suppliers control premium exhaust-grade titanium feedstock, constraining independent tuner scale-up.
- CE marking friction:European aftermarket cooling modifications face extended conformity assessment timelines under evolving pressure equipment directives.
- Socketed PROM obsolescence:Legacy chip tuning demand contracts as flash-reprogrammable ECU architectures displace removable memory modules in vehicles manufactured after 2010.
Strategic Opportunities
- Connected vehicle data logging:Real-time telemetry integration with OEM telematics platforms enables subscription-based calibration refinement for racing teams and track-day enthusiasts.
- German KBA homologation services:Established tuners with type-approval capabilities capture margin from compliance-hesitant competitors barred from road-legal product sales.
- Electric powertrain calibration:Battery thermal management and inverter torque mapping emerge as service categories as performance EV adoption accelerates in Norway and the Netherlands.
Industry Challenges
- Embedded software engineering scarcity:Tuning shops struggle to recruit firmware developers capable of reverse-engineering encrypted ECU protocols without triggering warranty-void detection flags.
- Dyno facility capex intensity:Accurate wheel horsepower validation requires climate-controlled test cells and eddy-current load banks that strain independent operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Performance Tuning and Engine Remapping Services Market |
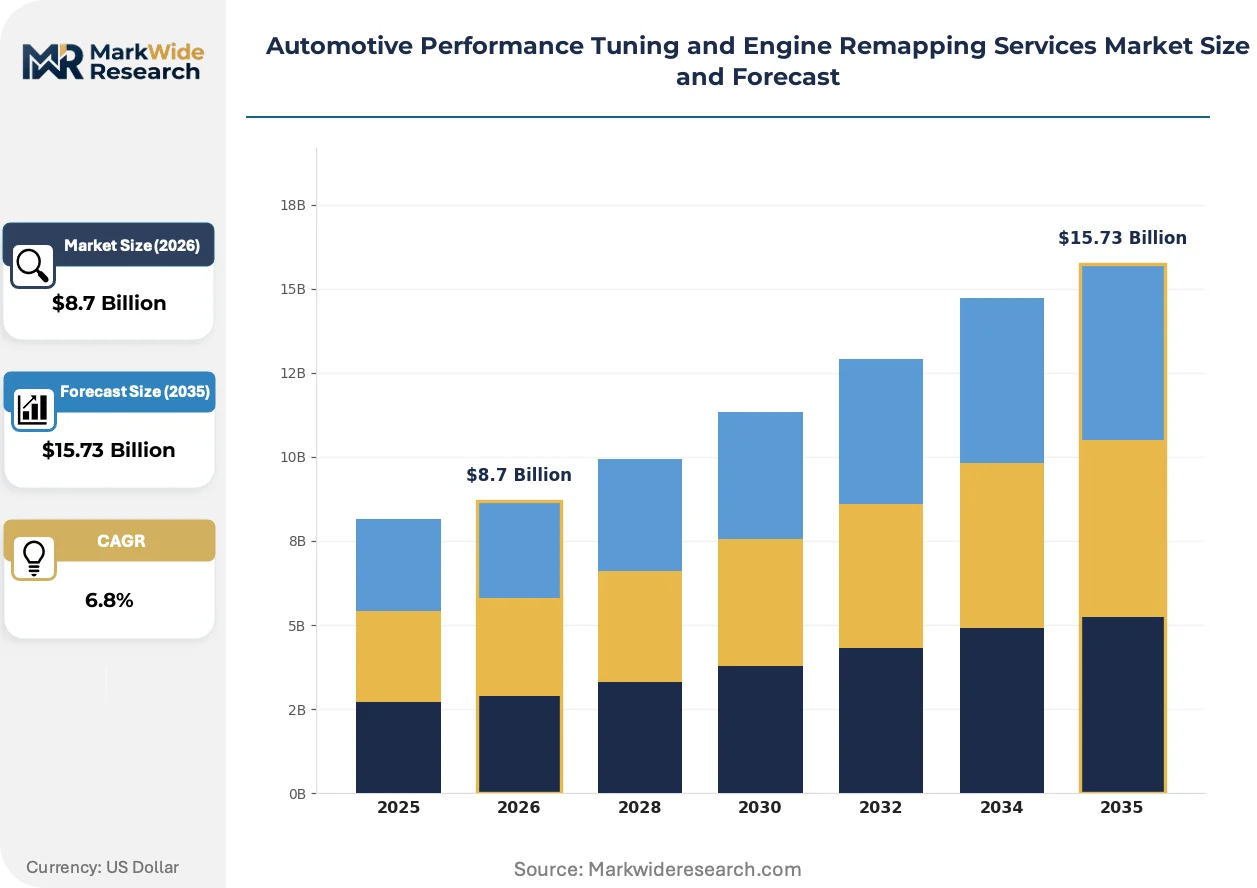
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Software Remapping, Chip Tuning, ECU Tuning, Dyno Testing Vehicle Type: Passenger Cars, Trucks, Motorcycles, Performance Vehicles End User: Car Enthusiasts, Fleet Operators, Racing Teams, Repair Shops Technology: Mapping Tools, Diagnostic Equipment, Data Logging, Custom Software |
| Companies Covered | Brembo, Luxoft, COBB Tuning, Cognizant, EPAM Systems, Akrapovič, DXC Technology, Infosys, KW Suspensions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Performance Tuning and Engine Remapping Services Market Emerging Trajectories
Software-defined calibration architectures are displacing hardware-centric tuning methodologies across the performance aftermarket. This shift compresses inventory requirements while elevating intellectual property protection as a competitive differentiator.
Cloud-based over-the-air ECU reprogramming is expanding into enthusiast segments previously served by physical flash tools. Remote calibration platforms enable tuners to serve geographically dispersed customers without workshop presence. This capability is compressing the addressable market for handheld device manufacturers while opening recurring revenue streams through map revision subscriptions.
EPA enforcement against defeat devices under the Clean Air Act is tightening product legality boundaries for United States operators. Tuners now face civil penalties exceeding manufacturing cost for emissions-test tampering hardware. The street-legal performance segment is responding by segregating product lines into track-only and compliant-road variants with distinct certification documentation.
Fleet procurement departments now specify fuel-efficiency guarantees from tuning providers rather than power metrics alone. Commercial vehicle managers in Germany negotiate outcome-based contracts tying vendor payment to documented diesel consumption reduction. This behavioral shift is most visible among long-haul operators on Autobahn-corridor routes where consistent high-speed cruising maximizes ECU calibration impact.
Automotive Performance Tuning and Engine Remapping Services Market Segmentation
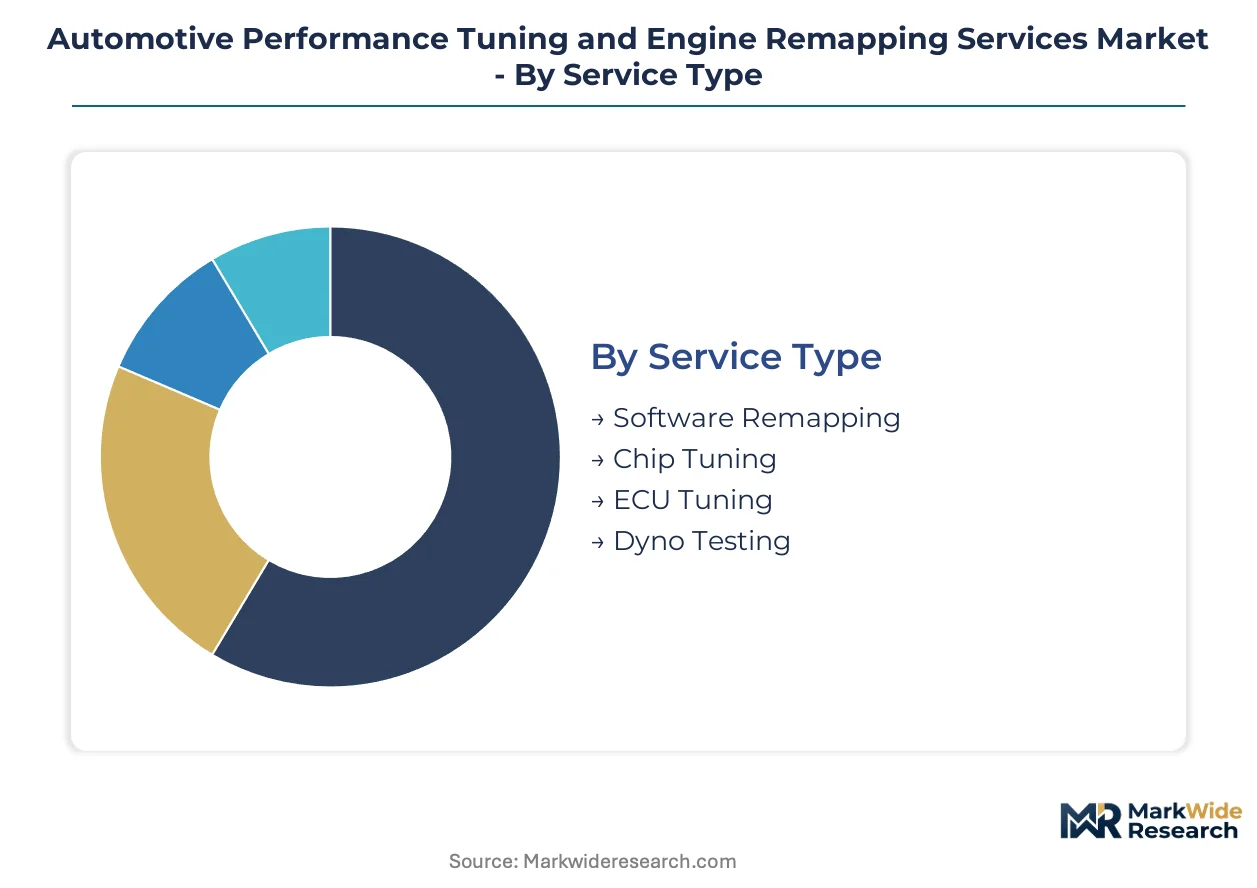
Service differentiation in automotive performance tuning hinges on calibration methodology and vehicle architecture compatibility. Segmentation reveals where margin pools concentrate across software-heavy versus hardware-dependent offerings.
Service Type:
Volume services dominate transaction counts while premium calibration commands per-unit economics.
- Software Remapping:Flash-based ECU reprogramming modifies air-fuel ratios, ignition timing, and torque limiters through OBD-II ports without physical component replacement. Fleet operators in Germany now specify fuel-efficiency guarantees from remapping providers, shifting procurement criteria from power metrics to documented consumption reduction.
- Chip Tuning:Socketed PROM module replacement for pre-2010 vehicles retains niche demand among legacy European performance models. Demand contracts as flash-reprogrammable architectures displace removable memory modules, constraining addressable vehicle population to aging installed base.
- ECU Tuning:Parameter calibration targeting boost pressure thresholds and rev limiters for turbocharged powertrains. Commercial vehicle managers deploy this service to extract efficiency gains from existing diesel engines without capital replacement cycles.
- Dyno Testing:Wheel horsepower validation using eddy-current load banks and climate-controlled test cells. Independent operators face capex intensity barriers as accurate measurement requires facility investments straining balance sheets.
Today's leader: Software Remapping. Tomorrow's challenger: ECU Tuning.
Vehicle Type:
Application intensity varies by powertrain complexity and regulatory exposure.
- Passenger Cars:Turbocharged gasoline and diesel vehicles constitute the core addressable market for street-legal calibration. EPA enforcement against defeat devices under the Clean Air Act forces tuners to bifurcate product lines into track-only and compliant-road variants.
- Performance Vehicles:Factory-tuned sports cars and supercars require specialized expertise for incremental gains without warranty-void detection. Racing teams concentrate spending here on custom software stacks with real-time data logging integration.
- Trucks:Heavy-duty diesel powertrains in commercial fleets prioritize torque curve optimization for towing and payload efficiency. Long-haul operators on German Autobahn corridors maximize ECU calibration impact through consistent high-speed cruising profiles.
- Motorcycles:Compact ECU architectures and exposed operating conditions demand weather-resistant calibration solutions. Akrapovič and specialized European suppliers control premium exhaust-grade titanium feedstock for this segment.
Performance Vehicles capture premium pricing. Trucks are climbing the fastest as fleet procurement formalizes.
End User:
Customer sophistication determines service bundling and pricing architecture.
- Fleet Operators:Commercial vehicle managers negotiate outcome-based contracts tying vendor payment to verified fuel consumption reduction. This behavioral shift is most visible among German long-haul operators where consistent high-speed cruising maximizes calibration impact.
- Racing Teams:Professional motorsport competitors demand custom software stacks with telemetry integration and subscription-based map refinement. Cloud-based over-the-air reprogramming is expanding into this segment previously served by physical flash tools.
- Car Enthusiasts:Individual owners seeking power gains or efficiency improvements represent high-volume, price-sensitive demand. Street-legal performance requirements compress margins as tuners absorb compliance documentation costs.
- Repair Shops:General automotive service providers resell tuning services as ancillary revenue without specialized calibration expertise. This channel faces margin pressure from direct-to-consumer remote calibration platforms.
Fleet Operators drive volume standardization. Racing Teams define capability frontier.
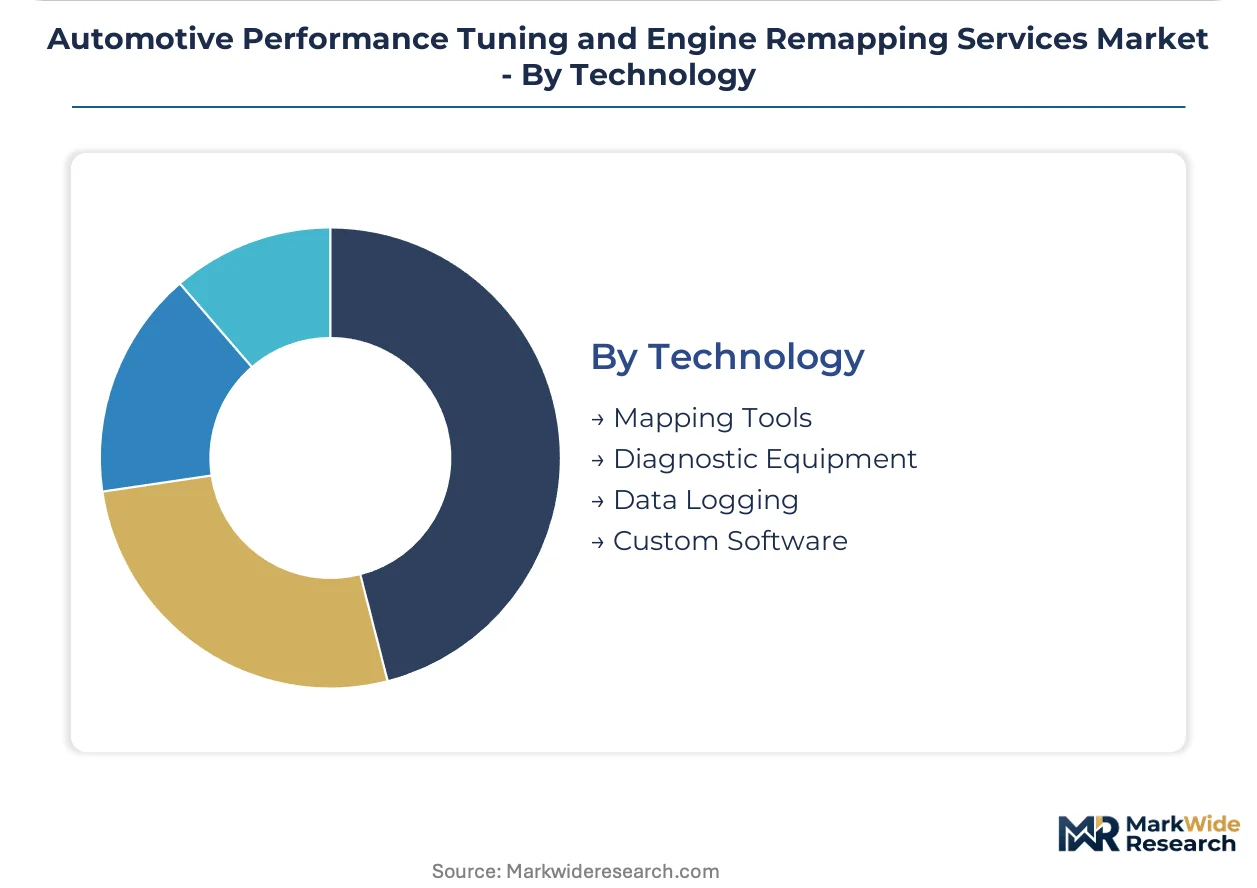
Technology:
Intellectual property protection and integration depth separate competitive tiers.
- Custom Software:Proprietary calibration maps and encrypted protocol reverse-engineering constitute core competitive differentiation. Tuning shops struggle to recruit firmware developers capable of navigating encrypted ECU architectures without triggering manufacturer detection flags.
- Data Logging:Real-time telemetry integration with OEM telematics platforms enables subscription-based refinement for track-day enthusiasts. This capability is compressing the addressable market for handheld device manufacturers while opening recurring revenue streams.
- Mapping Tools:Software-defined calibration architectures displace hardware-centric methodologies across the performance aftermarket. This shift elevates intellectual property protection as a competitive differentiator while compressing inventory requirements.
- Diagnostic Equipment:OBD-II scanners and manufacturer-specific protocol interfaces enable baseline assessment and post-calibration validation. CE marking friction extends conformity assessment timelines for European aftermarket cooling modifications under evolving pressure equipment directives.
Custom Software commands margin premiums. Data Logging is gaining share fastest through recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Autobahn-accessible performance culture sustains the densest network of specialized tuners worldwide. Fleet operators across German long-haul corridors now negotiate outcome-based fuel efficiency contracts. Regulatory frameworks in multiple jurisdictions are reshaping where and how calibration services deploy.
United States
Commercial fleet managers in Texas and California deploy ECU remapping for diesel consumption reduction in heavy-duty trucks. EPA enforcement actions against defeat devices under the Clean Air Act compress product development timelines for tuners serving street-legal segments. Detroit's automotive engineering cluster anchors aftermarket calibration R&D for domestic powertrains.
Germany
KBA type-approval requirements create compliance barriers that favor established tuners with homologation capabilities. The F-Gas Regulation governs refrigerant-based performance cooling modifications with stricter containment standards. Stuttgart and Munich host concentrated specialist workshops serving factory-tuned sports car owners seeking incremental warranty-safe gains.
United Kingdom
Track-day enthusiasts in Silverstone and Brands Hatch corridors drive demand for cloud-based over-the-air reprogramming platforms. CE marking friction extends conformity assessment timelines for cooling system modifications under evolving pressure equipment directives. Motorsport engineering clusters around Oxfordshire and the Midlands sustain custom software stack development for racing applications.
Japan
Compact ECU architectures in performance motorcycles demand weather-resistant calibration solutions from specialized suppliers. METI standards shape embedded software engineering requirements for encrypted protocol navigation. Osaka and Nagoya manufacturing belts concentrate titanium exhaust fabrication for premium two-wheeler applications.
Australia
Remote calibration platforms enable tuners to serve geographically dispersed enthusiasts across vast interstate distances without workshop presence. TGA-equivalent vehicle modification standards govern aftermarket thermal management system compliance. Melbourne and Sydney metropolitan clusters concentrate dyno testing facilities with climate-controlled validation capabilities.
Automotive Performance Tuning and Engine Remapping Services Market Vendor Landscape
Global majors compete with regional champions across software ecosystems and hardware fabrication capabilities. Market structure fragments between flash-based calibration platforms requiring minimal physical inventory and component fabricators controlling premium material feedstocks. Three archetypes dominate: proprietary software stack developers, titanium exhaust specialists, and brake system upgrade manufacturers. Consolidation pressure concentrates through M&A targeting homologation capabilities and strategic partnerships bridging OEM telematics integration.
Among software-centric developers, COBB Tuning and Luxoft occupy positions exemplifying proprietary ecosystem approaches. Brembo anchors the premium braking upgrade segment with ceramic-composite expertise. Akrapovič sits within the exhaust fabrication tier controlling European-Asian titanium supply chains for motorcycle and performance vehicle applications.
| Leading Market Players |
|---|
| Brembo |
| Luxoft |
| COBB Tuning |
| Cognizant |
| EPAM Systems |
| Akrapovič |
| DXC Technology |
| Infosys |
| KW Suspensions |
| Others |
Supply Flow & Price Mechanics
Backward integration into encrypted ECU protocol development anchors both supply security and pricing power for established tuners, as firmware engineering scarcity drives captive investment in proprietary calibration architectures. This integration choice separates margin-rich software stack developers from hardware-dependent competitors exposed to titanium and carbon fiber input volatility.
Pricing Analysis
Input-cost pass-through from titanium feedstock and climate-controlled dyno facility capex intensifies pricing pressure across hardware-dependent tiers, while flash-based software remapping retains margin resilience through minimal physical inventory requirements. Three-tier pricing structure across premium KBA-homologated, standard CE-marked, and economy track-only calibration levels reflects certification investment differentiation. Fleet operators in Germany exhibit lowest price sensitivity due to outcome-based fuel efficiency contracting, whereas individual car enthusiasts face compressed margins from compliance documentation absorption.
Supply Chain Analysis
Dual-sourcing requirements from German KBA-homologated tuners and Japanese METI-compliant motorcycle specialists mandate multi-supplier qualification for encrypted protocol interfaces and titanium exhaust feedstock. Geographic supply concentration centers on Germany for homologation-capable calibration platforms, Japan for compact ECU weather-resistant architectures, and Slovenia-Asian corridors for premium exhaust-grade titanium. Raw material dependencies encompass titanium sponge, carbon fiber prepregs, and ceramic-composite brake substrates. Single-source vulnerability concentrates in Akrapovič-controlled titanium supply chains. Distribution runs through specialized workshop networks, direct-to-consumer remote calibration platforms, and OEM telematics-integrated subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in software-defined calibration architectures where recurring subscription revenue displaces transactional hardware sales, anchored by cloud-based over-the-air reprogramming cost-down trajectories.
For Market Incumbents: Deploy proprietary data logging ecosystems to lock in racing team and fleet operator switching costs. Deepen firmware engineering benches to navigate encrypted ECU protocols without triggering manufacturer warranty-void detection flags. Consolidate regional homologation capabilities through targeted acquisition of KBA-type-approved workshops in Stuttgart and Munich corridors, defending against cloud-based remote calibration platforms eroding geographic moats. For New Entrants and Emerging Players: EPA enforcement actions against defeat devices in the United States open a window for compliant-road calibration specialists with segregated track-only product documentation. Target Australian interstate corridors where remote calibration platforms serve geographically dispersed enthusiasts without workshop presence. Pursue white-label partnerships with repair shops facing margin compression from direct-to-consumer platforms, embedding subscription-based map revision services. For Investors and Strategic Acquirers: Consolidation pressure builds where homologation capabilities and encrypted protocol expertise concentrate in founder-led specialist shops approaching generational transition. Long-term viability favors acquisition targets with established KBA type-approval frameworks and OEM telematics integration pipelines over pure hardware fabricators exposed to titanium supply concentration. Watch cloud-based calibration platform adoption rates among German fleet operators as inflection indicator for software-defined valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Accessport Ecosystem Expansion | COBB Tuning's encrypted protocol navigation secures recurring map subscription revenue from racing teams. |
| KBA Homologation Capability Acquisition | Established tuners capture margin from compliance-hesitant competitors barred from road-legal German sales. |
| Carbon Fiber Intake System Manufacturing Scale-Up | Brembo's ceramic-composite expertise transfers to lightweight thermal management component substitution. |
| Cloud-Based Over-the-Air Reprogramming Platform Launch | Remote calibration compresses handheld device addressable market while opening telemetry-integrated subscriptions. |
| Electric Powertrain Calibration Service Development | Battery thermal management and inverter torque mapping emerge as performance EV adoption accelerates in Norway. |
Methodological Framework
Bottom-up fleet operator and racing team demand modeling reconciled against top-down titanium exhaust and carbon fiber component supply tracking forms the analytical core. Primary interviews with ECU calibration engineers, KBA homologation specialists, fleet procurement managers, and aftermarket distribution channel heads combined with secondary validation from EPA enforcement action databases, KBA type-approval registries, and EU F-Gas Regulation compliance filings. Trade data from German Autobahn-corridor commercial vehicle registrations and Japanese METI embedded software standards provided cross-reference anchors.
Historical trendline analysis of software remapping adoption rates against chip tuning decline informed projection frameworks across the analysis window. Segmentation dimensions encompassed service type, vehicle architecture, end-user sophistication, and technology integration depth. CAGRs derived from weighted average of OEM telematics penetration curves and fleet operator outcome-based contracting diffusion. Industry-specific forecast inputs incorporated OBD-III mandate implementation timelines and electric powertrain calibration service emergence patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA enforcement escalation or titanium supply chain disruption scenarios. Deviation in German KBA homologation processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Quality Service Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Driver's License Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Tow Truck Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Americas MAP Market
Automotive Services
Limousine Car Hire or Rental Market