
 Automotive Homologation Services Market | 2026-2036
Automotive Homologation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Homologation Services Market Analysis
China's NEV certification infrastructure is reconfiguring how homologation providers allocate laboratory capacity across Asia. TÜV SÜD AG leverages its Shanghai testing campus to anchor emissions validation programs for domestic OEMs. DEKRA SE competes through specialized cybersecurity homologation protocols aligned with UN R155 requirements. Bureau Veritas SA extends its laboratory network into Thailand and Vietnam to capture outbound Chinese manufacturing relocations.
Automotive homologation services encompass the technical validation, regulatory testing, and documentation processes required to certify vehicles and components for lawful sale in target jurisdictions, involving crashworthiness protocols, electromagnetic compatibility thresholds, and exhaust emission limits measured against standardized drive cycles. Type Approval and Emissions Testing command the largest revenue pools given their mandatory status across all regulated markets, while Simulation Testing grows fastest as OEMs front-load virtual validation to compress physical prototype cycles. Component Certification captures concentrated margin from Tier-1 Suppliers seeking modular approvals that transfer across multiple OEM platforms.
UN ECE regulations, China's GB standards administered by SAMR, and the EU's MDR framework collectively dictate test scope, documentation depth, and market access timelines for homologation service providers. China's dual carbon goals from MEE tighten emissions test stringency, while REACH and RoHS in Europe extend material compliance obligations into component-level certification. Stakeholders must monitor regulatory divergence between UN harmonized standards and emerging national cybersecurity mandates to determine where to build captive testing capacity versus outsourced partnerships.
Market Dynamics
UN ECE regulatory expansion into battery thermal runaway testing and UN R155 cybersecurity mandates is forcing homologation providers to retool laboratory capabilities and retrain engineering teams at unprecedented speed.
Growth Catalysts
- China's GB Standards Expansion:SAMR's tightening of NEV safety protocols requires comprehensive battery abuse testing, driving laboratory capacity investments across Shanghai and Shenzhen.
- EU Battery Regulation:The carbon footprint declaration mandate for EV batteries entering European markets extends homologation scope into upstream supply chain verification.
- South Korean Production Scaling:Domestic EV output concentration near Seoul and Ulsan creates sustained demand for localized electromagnetic compatibility validation services.
Market Restraints
- Capital Equipment Intensity:Crash test sleds and climatic wind tunnels require seven-figure euro investments with decade-long depreciation schedules.
- Regulatory Divergence Risk:China's MIIT maintains parallel certification tracks to UN ECE standards, forcing redundant test protocols for export-bound vehicles.
- Engineering Talent Scarcity:Functional safety assessors qualified to ISO 26262 concentrate in Germany and Japan, limiting provider expansion elsewhere.
Strategic Opportunities
- Thailand Manufacturing Relocation:Chinese OEM assembly transfers to Rayong and Chonburi create demand for ASEAN-focused type-approval services.
- Software-Defined Vehicle Convergence:Over-the-air update validation merges cybersecurity homologation with functional safety assessment, opening integrated service bundles.
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing will require domestic battery testing infrastructure.
Industry Challenges
- Cross-Disciplinary Skill Gaps:Engineers must simultaneously interpret UN ECE protocols, cybersecurity frameworks, and battery electrochemistry, stretching training pipelines.
- Physical-Digital Integration:Correlating virtual crash simulation outputs with sled test results demands new validation methodologies that lack industry standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Homologation Services Market |
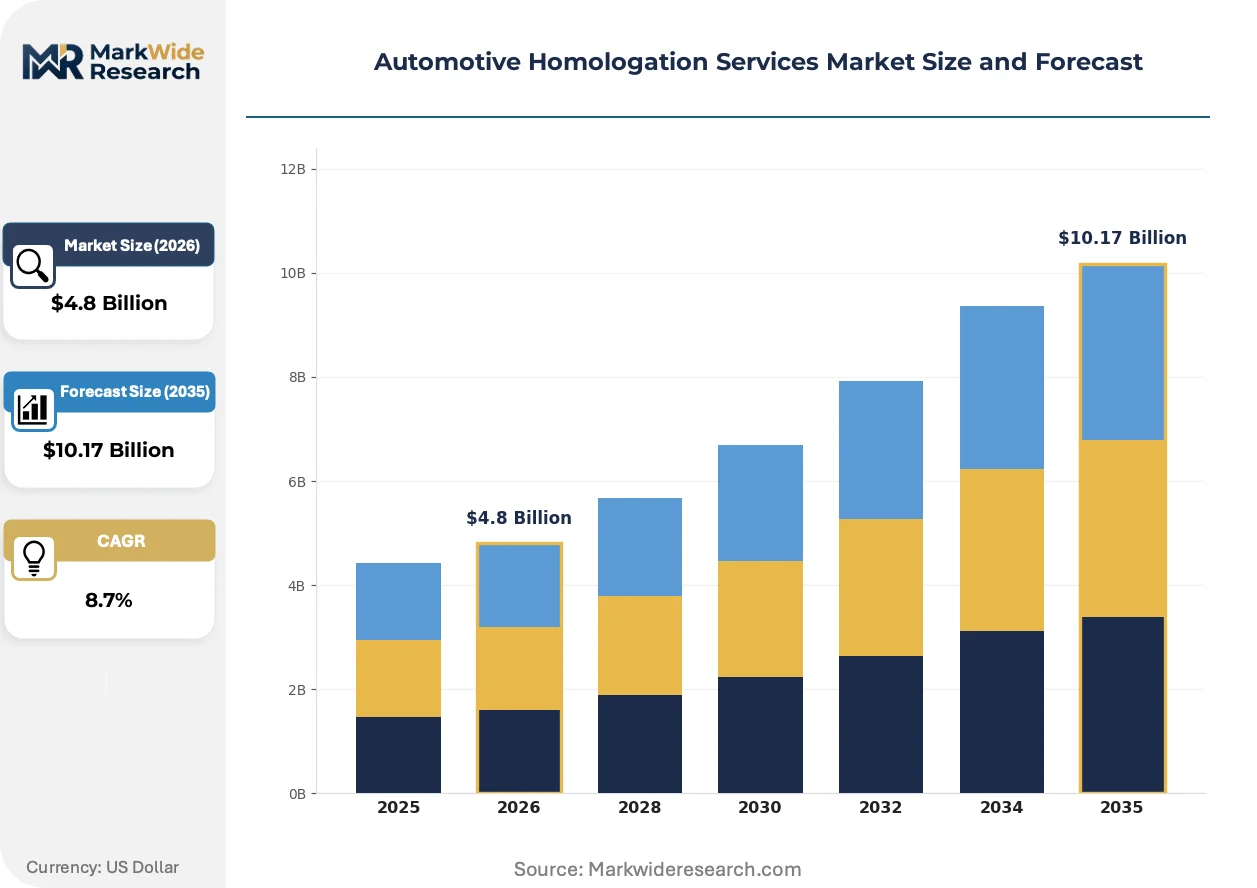
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Type Approval, Component Certification, Emissions Testing, Safety Compliance Testing Method: Laboratory Testing, Dynamic Testing, Simulation Testing, Field Testing Client Type: Manufacturers, Tier-1 Suppliers, Aftermarket Providers, OEMs Market Stage: Pre-Certification, In-Certification, Post-Certification, Continuous Compliance |
| Companies Covered | TÜV SÜD AG, Eurofins Scientific SE, DEKRA SE, Applus+ IDIADA, TÜV Rheinland AG, Bureau Veritas SA, SGS SA, Element Materials Technology Group Ltd., Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Homologation Services Market Emerging Trajectories
Homologation workflows are bifurcating between accelerated virtual validation front-loading and expanded physical testing for novel propulsion architectures. This tension reshapes laboratory design, engineering staffing models, and client engagement structures across the value chain.
Digital twin environments for vehicle crashworthiness assessment are hybridizing physical and virtual validation timelines. Tier-1 suppliers in Germany and Japan now front-load 70 percent of structural load path analysis in simulation before committing to prototype builds. This compression is reallocating capital from physical test cells toward high-performance computing clusters and real-time solver licensing.
The EU's Cyber Resilience Act extends conformity assessment obligations into aftermarket software updates for connected vehicles. Homologation providers must now maintain continuous monitoring capabilities rather than point-in-time certification events. Component suppliers selling into European OEM platforms face the steepest compliance cost increases.
Chinese NEV OEMs are unbundling homologation procurement across specialized boutiques rather than consolidated full-service contracts. Separate vendors now handle GB standards compliance, UN ECE alignment, and export-market adaptation. This fragmentation concentrates margin in niche cybersecurity and battery safety boutiques while pressuring generalist providers.
Automotive Homologation Services Market Segmentation
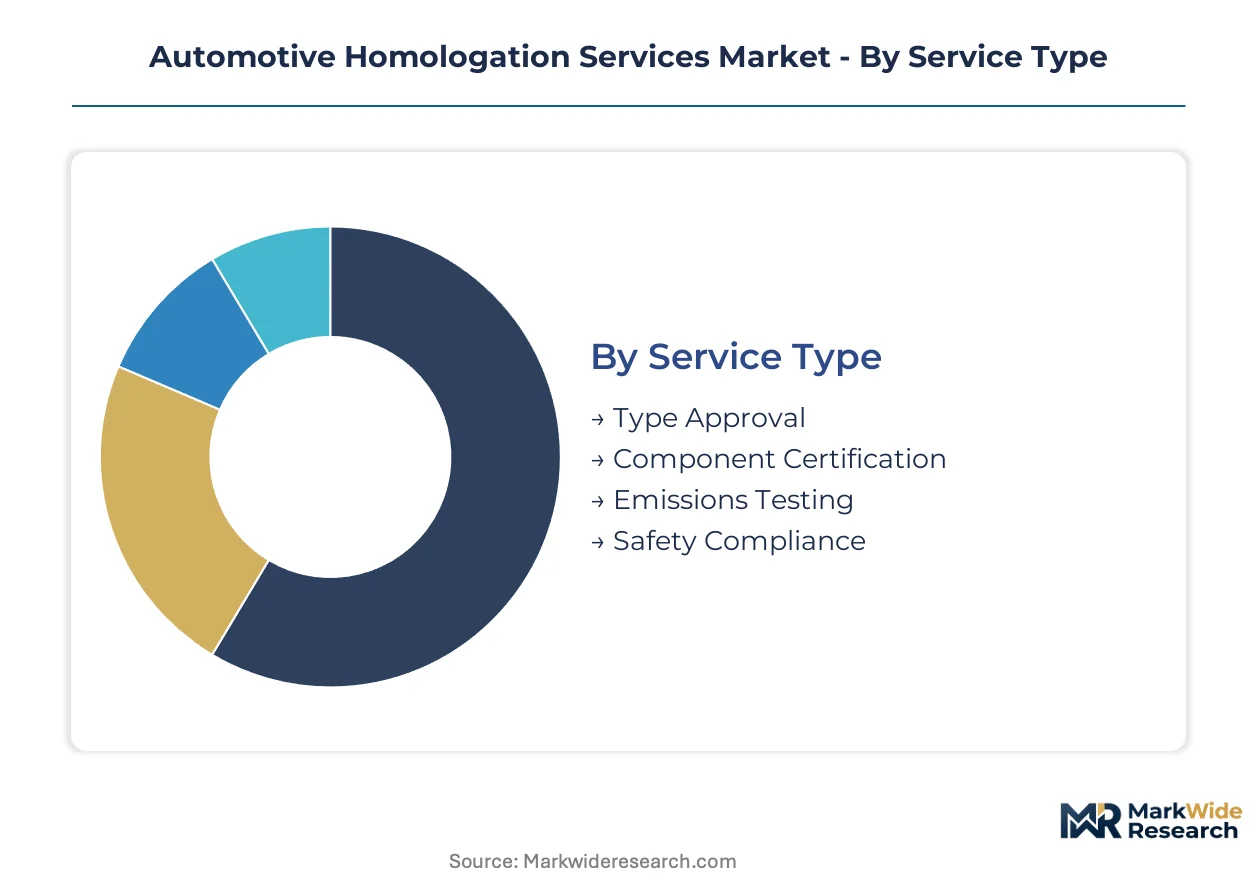
Homologation service procurement varies sharply by where clients sit in the vehicle lifecycle. After-sales compliance obligations now extend certification relationships beyond initial type approval into continuous monitoring regimes.
Service Type:
After-sales-service intensity escalates from one-time approvals toward ongoing compliance mandates, particularly as cybersecurity and battery health monitoring requirements mature.
- Type Approval:Comprehensive vehicle-level certification against UN ECE regulations or national equivalents like China's GB standards administered by SAMR. Demand clusters around Shanghai and Stuttgart as EV OEMs expand export pipelines. Mandatory status across all regulated markets sustains revenue stability despite long sales cycles.
- Component Certification:Modular validation of subsystems—battery packs, ECUs, lighting assemblies—enabling transferable approvals across multiple OEM platforms. Tier-1 suppliers in South Korea and Germany drive volume as they standardize components for cross-platform deployment. Margin concentrates here due to repeat testing of iterative design changes.
- Emissions Testing:Exhaust and evaporative emission validation against standardized drive cycles including WLTP and China's CATC protocols.
- Safety Compliance:Crashworthiness, pedestrian protection, and active safety system verification against evolving UN ECE protocols.
Type Approval holds the largest share; momentum sits with Component Certification.
Testing Method:
Cost tier differentiation separates capital-intensive physical facilities from software-dependent virtual validation, reshaping provider investment priorities.
- Laboratory Testing:Controlled-environment validation including climatic chambers, electromagnetic compatibility anechoic rooms, and battery abuse test cells. Shanghai and Seoul host the densest concentration of accredited capacity as domestic EV production scales. Equipment depreciation schedules stretching beyond a decade lock in incumbent positions.
- Simulation Testing:Virtual validation using finite element analysis and digital twin environments to front-load structural and thermal assessments. German and Japanese Tier-1 suppliers now execute seventy percent of load path analysis in simulation before prototype commitment. This segment climbs the fastest as computing costs decline and solver fidelity improves.
- Dynamic Testing:Track-based validation of vehicle dynamics, braking performance, and durability under real-world loading conditions.
- Field Testing:On-road data collection for real-driving emissions, autonomous system validation, and connected vehicle cybersecurity probing.
Laboratory Testing dominates current revenue; Simulation Testing gains share fastest.
Client Type:
Application focus shifts from complete vehicle validation toward subsystem-level procurement as platform architectures modularize.
- OEMs:Full-vehicle type approval and export market adaptation for passenger car and commercial vehicle manufacturers. Chinese NEV producers unbundle procurement across specialized boutiques rather than consolidated contracts. This fragmentation pressures generalist providers while concentrating margin in niche cybersecurity and battery safety specialists.
- Tier-1 Suppliers:Component-level certification seeking modular approvals transferable across multiple OEM platforms. Bosch, CATL, and Hyundai Mobis drive sustained demand for electromagnetic compatibility and functional safety validation. Volume scales with platform standardization trends.
- Manufacturers:Specialized vehicle producers including bus, truck, and off-highway equipment makers.
- Aftermarket Providers:Compliance for replacement parts, retrofit systems, and accessory integrations.
OEMs anchor volume demand; Tier-1 Suppliers expand fastest.
Market Stage:
Maturity gradients separate established certification workflows from emerging continuous compliance obligations.
- In-Certification:Active testing, documentation compilation, and regulatory submission during vehicle development programs. This stage captures the densest engineering resource allocation and longest client engagement durations. UN ECE regulatory expansion into battery thermal runaway and cybersecurity extends testing timelines.
- Continuous Compliance:Ongoing monitoring, software update validation, and periodic recertification for connected and software-defined vehicles. The EU Cyber Resilience Act mandates aftermarket update assessment, transforming homologation from point-in-time events into persistent service relationships.
- Pre-Certification:Gap analysis, regulatory pathway planning, and test specification development before formal submission.
- Post-Certification:Market surveillance support, defect investigation, and regulatory change impact assessment.
In-Certification generates the largest revenue pool; Continuous Compliance represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes homologation services through integrated full-vehicle validation programs, whereas China fragments procurement across specialized boutiques for battery safety, cybersecurity, and export adaptation. Japan concentrates demand in Tier-1 supplier certification for standardized components. South Korea scales laboratory capacity for domestic EV electromagnetic compatibility. The United States lags in regulatory stringency but accelerates investment as NHTSA tightens autonomous vehicle protocols.
Germany
Stuttgart and Munich anchor Europe's densest cluster of UN ECE type-approval capacity as domestic OEMs expand EV export pipelines. KBA enforcement of UN R155 cybersecurity mandates forces laboratory retooling for continuous compliance validation. TÜV SÜD AG leverages its Munich headquarters to coordinate battery thermal runaway testing programs across European OEM platforms.
China
Shanghai and Shenzhen concentrate SAMR-accredited capacity for GB standards compliance as NEV production scales beyond domestic absorption. MIIT maintains parallel certification tracks to UN ECE standards, forcing redundant test protocols for export-bound vehicles. Domestic OEMs unbundle homologation procurement, concentrating margin in niche cybersecurity boutiques while pressuring generalist providers.
South Korea
Seoul and Ulsan generate sustained demand for localized electromagnetic compatibility validation as domestic EV output concentrates near production hubs. MFDS-aligned functional safety assessment for battery management systems drives laboratory investment. Hyundai Mobis and LG Energy Solution anchor Tier-1 certification volume for standardized components deployable across multiple OEM platforms.
United States
California and Michigan diverge in regulatory exposure as NHTSA accelerates autonomous vehicle protocol development while EPA maintains emissions testing stability. IRA production incentives attract battery manufacturing investment, extending homologation scope into upstream supply chain verification. Detroit-based OEMs rely on outsourced partnerships for cybersecurity validation rather than captive laboratory capacity.
Japan
Nagoya and Tokyo concentrate METI-influenced certification demand for standardized Tier-1 components as platform architectures modularize across Toyota and Honda supply chains. JIS standards alignment with UN ECE protocols reduces redundant testing for export-bound vehicles. Domestic suppliers front-load simulation validation before committing to prototype builds, reallocating capital toward high-performance computing clusters.
Automotive Homologation Services Market Vendor Landscape
Capability concentration sits with specialized boutiques possessing cybersecurity and battery safety credentials; scale advantage sits with full-service networks covering multiple regulatory jurisdictions. The vendor base stratifies between integrated multinationals with decade-long laboratory depreciation schedules and agile specialists capturing fragmented NEV procurement. Three archetypes dominate: UN ECE-aligned European networks, GB standards-focused Chinese campuses, and cybersecurity boutiques. Competitive moves center on ASEAN laboratory expansion and simulation software partnerships.
Among European-anchored networks, TÜV SÜD AG, DEKRA SE, and Bureau Veritas SA exemplify the integrated archetype spanning type-approval, component certification, and emissions testing. These entities occupy positions where UN ECE regulatory expansion forces simultaneous capability investment across battery thermal runaway and cybersecurity domains. Their geographic footprints concentrate laboratory capacity in Germany and China while extending into Thailand and Vietnam to capture manufacturing relocation flows.
| Leading Market Players |
|---|
| TÜV SÜD AG |
| Eurofins Scientific SE |
| DEKRA SE |
| Applus+ IDIADA |
| TÜV Rheinland AG |
| Bureau Veritas SA |
| SGS SA |
| Element Materials Technology Group Ltd. |
| Intertek Group plc |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam maritime freight corridors govern cost pass-through dynamics for homologation equipment imports, concentrating pricing power with German and Chinese laboratory networks while fragmenting margin capture for boutique cybersecurity providers serving export-bound NEV manufacturers.
Pricing Analysis
Price spreads between Stuttgart and Shanghai testing campuses exceed thirty percent for equivalent UN ECE type-approval programs. Project-based pricing dominates comprehensive vehicle certification, while component-level validation shifts toward subscription frameworks for continuous compliance monitoring. Cost compression in emissions testing intensifies as simulation software displaces physical prototype cycles. Tier-1 suppliers exhibit highest price sensitivity due to iterative design change volumes, whereas OEMs absorb premium pricing for accelerated turnaround on export-market adaptation.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates capital equipment procurement risk for climatic wind tunnel and crash sled installations. Laboratory infrastructure draws from German precision engineering, Chinese steel fabrication, and South Korean electromagnetic compatibility chamber specialists. Critical dependencies include high-fidelity sensor arrays, real-time solver licensing, and ISO 17025 accreditation consulting. Single-source vulnerability concentrates in battery abuse test cell manufacturers. Distribution runs through direct OEM procurement for full-vehicle programs and Tier-1 supplier frameworks for modular component certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified assessors for ISO 26262 functional safety and UN R155 cybersecurity protocols remain concentrated in Germany and Japan, creating structural bottlenecks for laboratory expansion elsewhere and compressing margins for generalist providers unable to secure specialized talent.
For Market Incumbents: Entrench cybersecurity and battery safety credentials through captive training academies in Shanghai and Munich, defending against boutique specialists unbundling NEV procurement. Priority investment in ASEAN laboratory capacity captures manufacturing relocation flows from Chinese OEMs. Vertical integration into simulation software partnerships locks in Tier-1 supplier relationships before virtual validation displaces physical testing revenue. For New Entrants and Emerging Players: India's battery testing infrastructure gaps present immediate white-space opportunity as PLI scheme manufacturing scales. Thailand's Rayong-Chonburi corridor lacks SAMR-aligned accreditation capacity for Chinese OEM assembly transfers. Target continuous compliance monitoring services for software-defined vehicles, where EU Cyber Resilience Act mandates transform homologation from point-in-time events into persistent revenue streams. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial testing divisions lacking automotive-specific cybersecurity or battery thermal runaway credentials. Long-term viability hinges on regulatory complexity expansion rather than commoditized emissions testing. Acquisition archetype: mid-cap European networks with UN ECE accreditation but underdeveloped simulation capabilities. Monitor NHTSA autonomous vehicle protocol acceleration as inflection signal for US laboratory investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| UN R155 Cybersecurity Accreditation Investment | DEKRA SE and TÜV SÜD AG capture continuous compliance mandates from EU OEM platforms. |
| ASEAN Laboratory Campus Expansion | Bureau Veritas SA extends Thailand-Vietnam footprint to serve outbound Chinese manufacturing relocations. |
| Simulation Software Partnership | German Tier-1 suppliers front-load seventy percent of structural validation before prototype commitment. |
| Battery Thermal Runaway Test Cell Deployment | SAMR's GB standards expansion forces capacity investments across Shanghai and Shenzhen. |
| Functional Safety Assessor Training Academy | ISO 26262 talent scarcity limits provider expansion beyond Germany and Japan. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, homologation laboratory directors, and SAMR regulatory officials and refined through secondary validation against UN ECE regulatory filings, vehicle production databases, IHS Markit registration data, and customs records for testing equipment imports. Bottom-up triangulation across service type demand and top-down reconciliation against national certification volumes anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include service type, testing method, client archetype, and market stage maturity. Vehicle class, propulsion architecture, and regional production cluster variations informed volume allocation. CAGRs derived from regression against historical certification volumes and regulatory pipeline expansion schedules, with battery safety protocol tightening and cybersecurity mandate rollout as primary forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese state-backed testing networks or accelerated NHTSA rulemaking would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive MRO Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Tow Truck Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Global Car Wash Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Car Subscription Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
Authorized Car Service Center Market