
 United Kingdom Warehousing and Distribution Logistics Market | 2026-2036
United Kingdom Warehousing and Distribution Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Warehousing and Distribution Logistics Market Analytics
Modular fulfillment configurations is hardening as the dominant procurement pattern among UK retailers seeking scalable capacity without long-term lease commitments. CSM Logistics leverages its Midlands hub network to anchor multi-tenant warehouse operations for mid-market manufacturers. Amazon dominates automated last-mile infrastructure through proprietary robotics deployment, while Fullers Logistics specializes in temperature-controlled pharmaceutical storage that meets MHRA compliance thresholds.
Warehousing and distribution logistics encompasses the physical storage, inventory management, and movement of goods through facilities equipped with racking systems exceeding twelve meters in height, climate-controlled zones, and loading docks designed for articulated vehicles up to sixteen-and-a-half meters. The primary commercial purpose centers on reducing order cycle times while minimizing inventory carrying costs for downstream buyers. Third-party logistics providers capture the largest margin pools as retailers outsource fulfillment complexity, though warehouse management systems within the technology segment are expanding fastest as operators replace legacy ERP modules with cloud-native platforms. Automated guided vehicles remain nascent outside grocery and automotive verticals due to capital intensity and integration timelines.
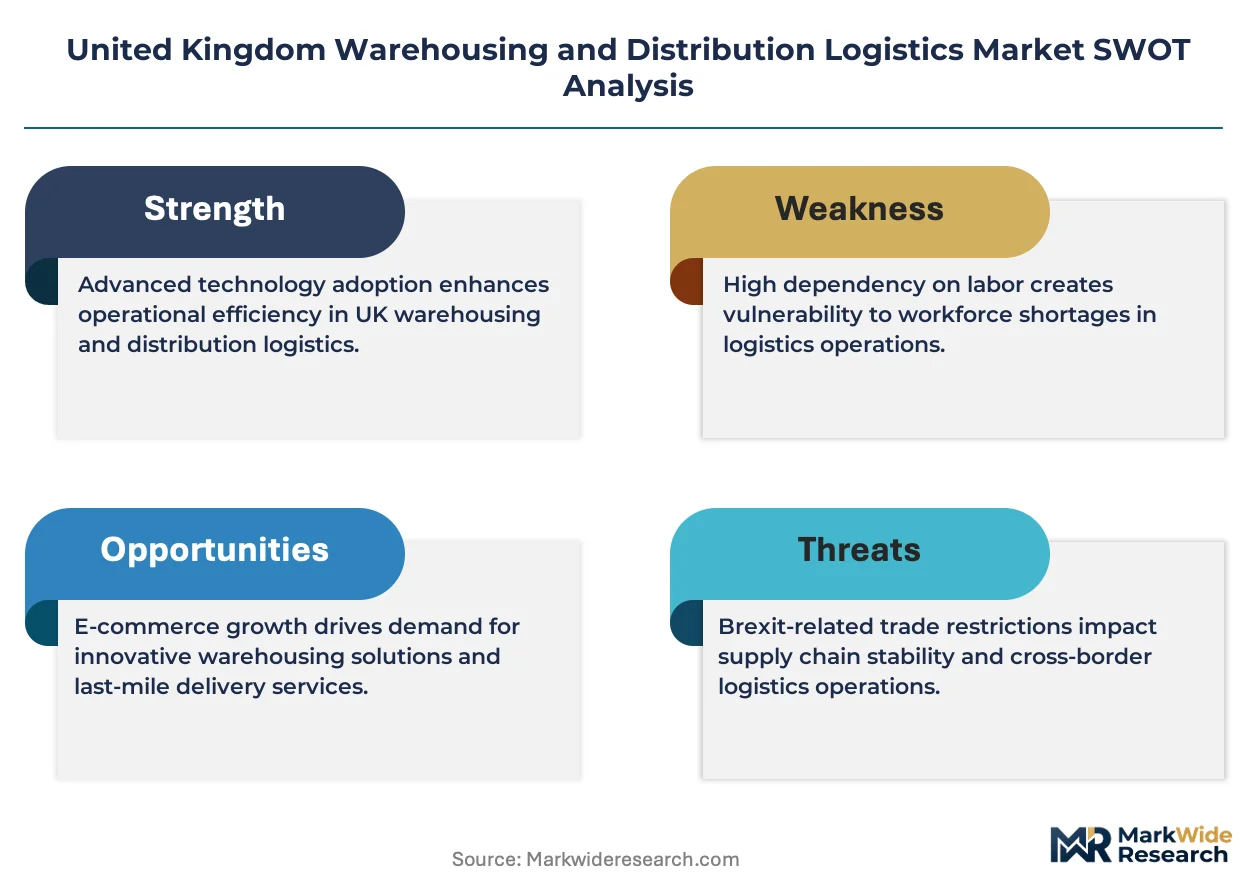
MHRA guidelines for pharmaceutical storage, HSE warehouse safety standards, and Building Regulations Part L energy efficiency requirements collectively shape facility design specifications and operator certification burdens across England, Scotland, and Wales. The UK's post-Brexit customs infrastructure investments are redirecting capital toward bonded warehousing capacity near Dover and Felixstowe. Stakeholders must weigh automation deployment timelines against evolving carbon reporting obligations under SECR regulations before committing to multi-year facility investments.
Market Dynamics
Modular fulfillment configurations are hardening as the dominant procurement pattern among UK retailers seeking scalable capacity without long-term lease commitments. E-commerce order volatility and SECR carbon reporting obligations are forcing operators to prioritize flexibility over fixed asset intensity.
Growth Catalysts
- SECR carbon disclosure mandates:Streamlined Energy and Carbon Reporting requirements are accelerating warehouse electrification investments across England and Wales. Facility operators retrofit LED lighting and solar arrays to meet compliance thresholds.
- Midlands logistics corridor concentration:The East Midlands Gateway and Birmingham distribution cluster absorb the majority of new speculative development. Rail-connected sites command rental premiums above regional averages.
- Automated sortation systems:Parcel handling throughput demands are driving adoption of cross-belt sorters and tilt-tray technologies in grocery and fashion verticals.
Market Restraints
- Steel and concrete input volatility:Warehouse construction costs fluctuate with commodity pricing, compressing developer margins on speculative builds.
- Grid connection queuing:Distribution centers above 50,000 square meters face 18-24 month delays for high-voltage electrical infrastructure in the South East.
- MHRA pharmaceutical certification timelines:Temperature-controlled facilities require 12-18 months for Good Distribution Practice accreditation, freezing speculative development in this subsegment.
Strategic Opportunities
- Northern Powerhouse logistics gap:Manchester and Leeds offer lower land costs than the Midlands with comparable motorway connectivity. Developers target these cities for speculative grade-A stock.
- Last-mile micro-fulfillment convergence:Automated storage and retrieval systems combined with urban dark stores enable 30-minute delivery promises in Greater London.
- Building Regulations Part L revisions:Tightened energy efficiency standards for new commercial buildings create first-mover advantages for operators with net-zero-ready specifications.
Industry Challenges
- WMS integration with legacy ERP:Warehouse management system deployments stall when interfacing with decades-old enterprise resource planning architectures in food manufacturing.
- AGV technician scarcity:Automated guided vehicle maintenance requires mechatronics skills that vocational training pipelines have not scaled to match fleet expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Warehousing and Distribution Logistics Market |
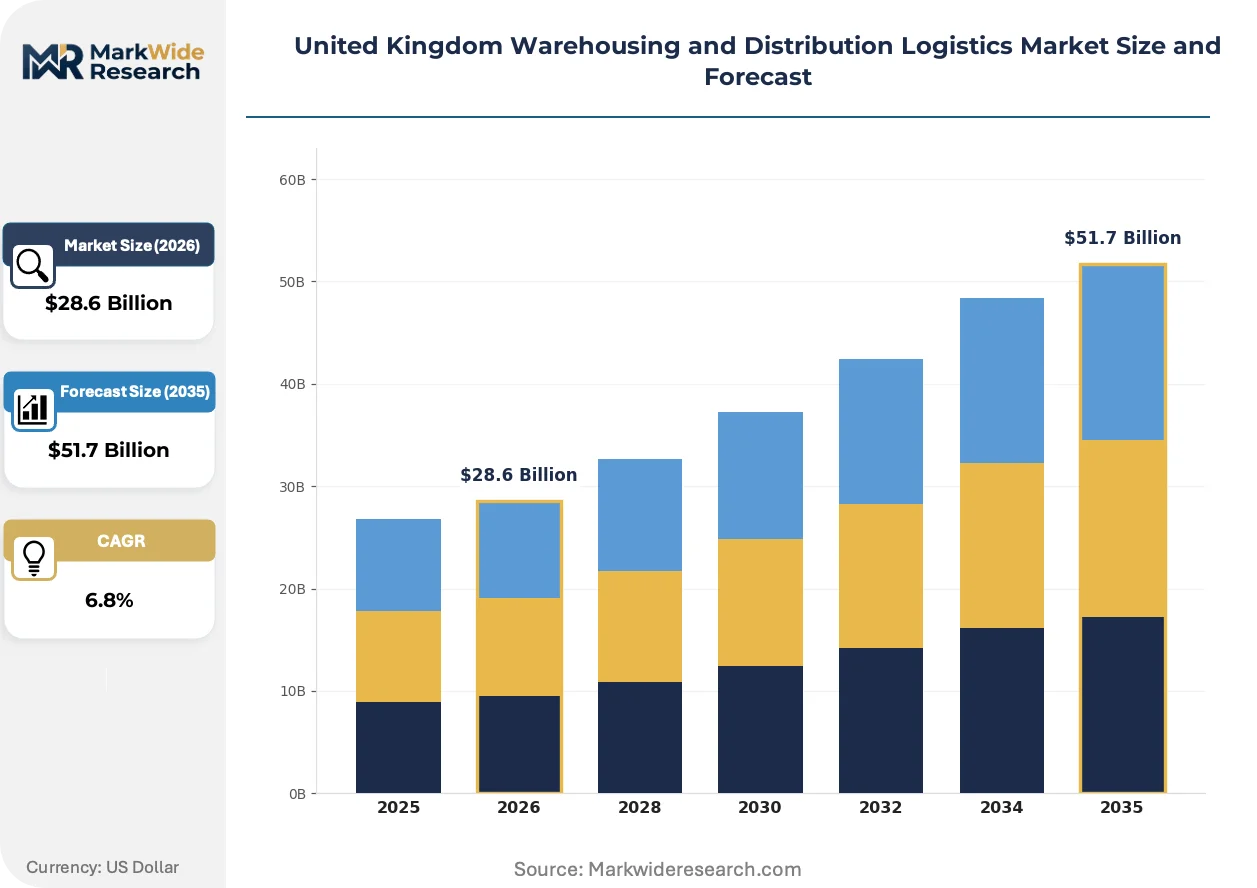
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Third-Party Logistics, Freight Forwarding, Inventory Management, Last-Mile Delivery Technology: Warehouse Management Systems, Robotics, IoT Solutions, Automated Guided Vehicles Customer Type: Retailers, E-commerce Platforms, Manufacturers, Wholesalers End User: Consumer Goods, Electronics, Pharmaceuticals, Automotive |
| Companies Covered | CSM Logistics, Zencargo, Amazon, EUF Group Ltd, KSK Logistics Ltd, Expeditors, Fullers Logistics, Mango International, AIT Worldwide Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Warehousing and Distribution Logistics Market Evolving Landscape
Cloud-native warehouse management platforms are displacing on-premise ERP modules as operators prioritize real-time inventory visibility. Three structural shifts are compressing implementation timelines and reshaping competitive positioning.
Autonomous mobile robotics is decentralizing fulfillment operations by enabling goods-to-person workflows without fixed infrastructure. Mid-market grocery retailers deploy these systems in brownfield warehouses to match Amazon's throughput density. The technology is compressing labor cost differentials between automated and manual facilities.
Building Regulations Part L energy efficiency requirements are mandating solar-ready roofing and heat pump compatibility in new commercial construction. Warehouse developers in the Midlands and South East pre-wire electrical capacity for future battery storage. Pharmaceutical and cold chain operators face the steepest compliance costs given 24-hour climate control demands.
Direct-to-consumer order profiles are fragmenting pallet configurations into single-item picks. Third-party logistics providers serving fashion and electronics verticals reconfigure racking density weekly. This volatility concentrates in the East Midlands Gateway, where speculative developers now specify higher clear heights and narrower aisle widths than traditional bulk storage norms.
United Kingdom Warehousing and Distribution Logistics Market Segmentation
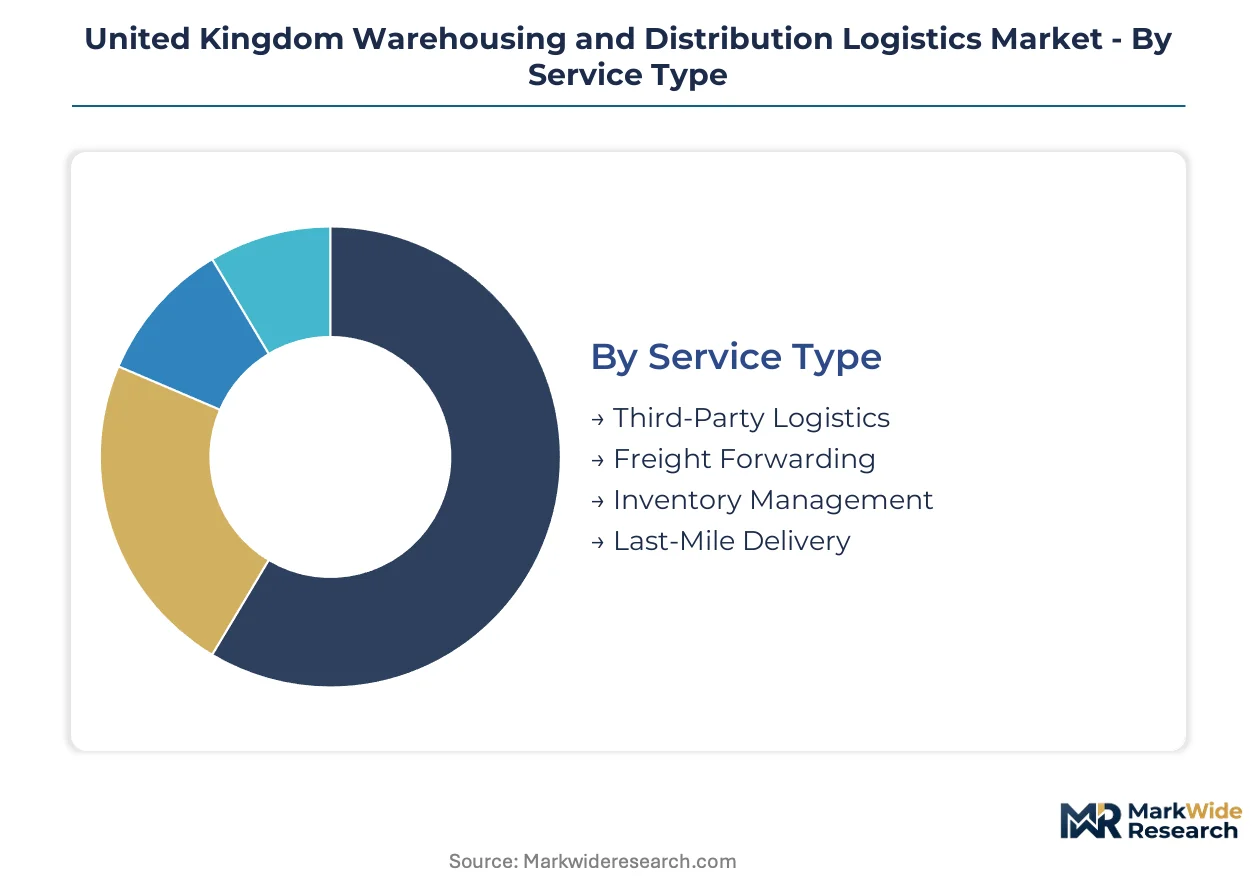
Warehouse operators in the United Kingdom segment their service portfolios around asset ownership models and technology integration depth. Procurement decisions increasingly hinge on whether customers seek captive infrastructure or outsourced flexibility.
Service Type:
Standardized contract structures dominate at the volume tier while bespoke arrangements concentrate among pharmaceutical and automotive verticals requiring specialized handling protocols.
- Third-Party Logistics:Comprehensive outsourcing of warehousing, inventory management, and distribution functions to specialized operators. Demand concentrates among mid-market retailers around the East Midlands Gateway seeking scalable capacity without capital commitment. The segment absorbs the majority of new speculative warehouse development.
- Freight Forwarding:Coordination of international cargo movement through multimodal transport arrangements and customs brokerage. Post-Brexit customs complexity is driving concentration near Dover and Felixstowe where bonded warehousing capacity expands. Operators invest in dedicated customs clearance teams to manage documentation burdens.
- Inventory Management:Stock control, demand forecasting, and replenishment optimization services. E-commerce platforms deploy these solutions to reduce carrying costs across fragmented SKU portfolios.
- Last-Mile Delivery:Final-stage distribution from urban hubs to end consumers. Greater London micro-fulfillment networks adopt automated sortation to meet 30-minute delivery promises.
Leading the category by volume: Third-Party Logistics. Expanding most quickly: Last-Mile Delivery.
Technology:
Capital intensity separates cloud-native deployments from hardware-heavy automation, with integration timelines stretching procurement cycles for complex robotics installations.
- Warehouse Management Systems:Software platforms governing inventory tracking, order fulfillment, and labor allocation. Cloud-native solutions displace legacy ERP modules across England and Wales as operators prioritize real-time visibility. The technology segment expands fastest as brownfield retrofits accelerate.
- Robotics:Autonomous mobile robots and articulated arms executing goods-to-person workflows. Grocery retailers deploy these systems to match Amazon's throughput density in existing facilities. Capital requirements limit penetration outside high-volume verticals.
- IoT Solutions:Sensor networks monitoring environmental conditions, equipment status, and asset location. Pharmaceutical cold chain operators deploy temperature-tracking infrastructure to satisfy MHRA compliance thresholds.
- Automated Guided Vehicles:Fixed-path material handling equipment transporting pallets along predetermined routes. AGV technician scarcity constrains fleet expansion despite labor cost advantages.
Highest deployment velocity: Warehouse Management Systems. Steepest adoption barriers: Automated Guided Vehicles.
Customer Type:
Order volatility patterns differentiate procurement behaviors, with seasonal spikes forcing flexible contract structures among fashion and electronics buyers.
- Retailers:Brick-and-mortar and omnichannel merchants requiring storage and replenishment services. Modular fulfillment configurations dominate procurement as scalable capacity overrides long-term lease commitments.
- E-commerce Platforms:Pure-play digital merchants with direct-to-consumer fulfillment requirements. Order fragmentation into single-item picks drives reconfiguration of racking density weekly in the Midlands.
- Manufacturers:Industrial producers seeking inbound materials management and finished goods distribution. Food manufacturers face WMS integration stalls when interfacing with decades-old ERP architectures.
- Wholesalers:Volume distributors serving downstream retailers with pallet-scale throughput. Bulk storage norms persist despite pressure for case-pick flexibility.
Driving contract innovation: E-commerce Platforms. Most stable demand base: Manufacturers.
End User:
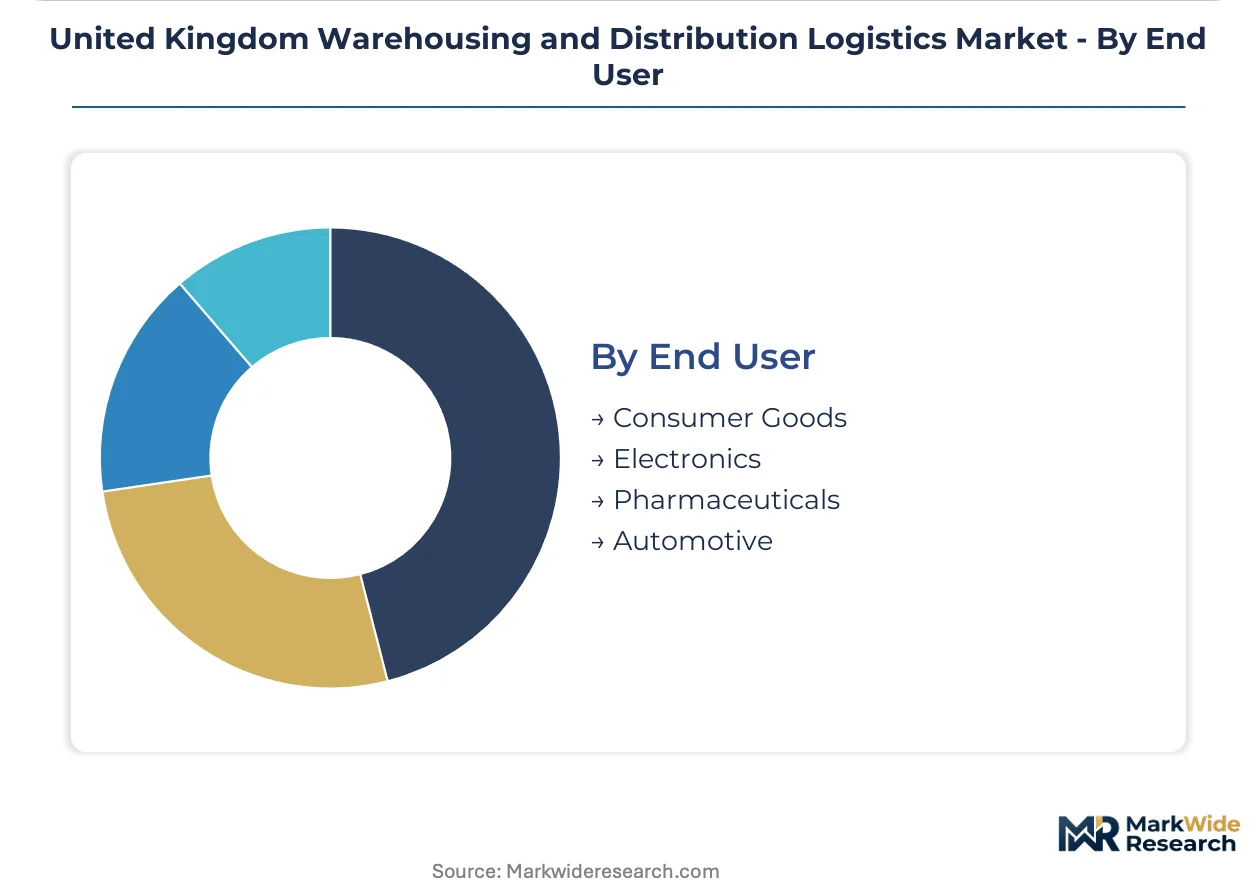
Regulatory stringency and climate control requirements fragment facility specifications across verticals, with pharmaceutical and cold chain operators facing the steepest compliance costs.
- Consumer Goods:Fast-moving packaged products with high inventory turnover and seasonal demand patterns. Fashion verticals concentrate in the East Midlands Gateway where speculative developers specify higher clear heights.
- Electronics:High-value components and finished devices requiring secure storage and anti-static handling. Demand clusters around Birmingham distribution corridors serving manufacturing supply chains.
- Pharmaceuticals:Temperature-sensitive medicines and clinical supplies governed by MHRA Good Distribution Practice. Certification timelines of 12-18 months freeze speculative development in this subsegment.
- Automotive:Just-in-time parts delivery and finished vehicle logistics. OEMs maintain captive warehousing near assembly plants in the West Midlands.
Highest facility specification barriers: Pharmaceuticals. Most standardized requirements: Consumer Goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom outpace domestic warehousing construction, forcing operators to prioritize retrofitting existing stock over greenfield development in constrained sub-markets.
London and the Southeast
E-commerce fulfillment demand from Greater London retailers is saturating available industrial land. The Greater London Authority's industrial land protection policies restrict conversion to residential use. Developers target Thurrock and Dartford for last-mile micro-fulfillment facilities serving same-day delivery promises.
Midlands
The East Midlands Gateway and Birmingham distribution cluster absorb the majority of speculative warehouse development. Streamlined Energy and Carbon Reporting mandates accelerate LED retrofit programs across aging facilities. Rail-connected sites near Castle Donington command rental premiums above regional averages.
North England
Manchester and Leeds offer lower land costs than the Midlands with comparable M62 motorway connectivity. The Northern Powerhouse initiative channels infrastructure investment toward logistics corridors. Developers target Trafford Park and Leeds Valley for grade-A speculative stock.
Scotland
Scottish distribution networks serve northern UK markets with limited cross-border redundancy. Building Standards Scotland energy efficiency regulations parallel England's Part L requirements. The Central Belt between Glasgow and Edinburgh concentrates cold storage investment for seafood and whisky exports.
Wales
South Wales corridor facilities handle Irish Sea freight through Holyhead and Fishguard ports. Welsh Government economic development programs incentivize warehouse employment in former industrial zones. Newport and Cardiff clusters specialize in automotive parts distribution serving English manufacturing plants.
United Kingdom Warehousing and Distribution Logistics Market Competitive Landscape
The competitive structure tilts toward diversified third-party logistics providers with captive real estate portfolios. Mid-market operators compete on flexibility while scale players deploy automation to compress unit costs. Two archetypes dominate: asset-heavy regional networks and technology-enabled freight platforms. Capacity expansion and strategic partnerships constitute the primary competitive moves as operators seek fixed-cost leverage without balance-sheet strain.
Within the diversified logistics tier, CSM Logistics and Fullers Logistics exemplify asset-heavy regional specialization. CSM Logistics anchors multi-tenant warehouse operations through its Midlands hub network. Fullers Logistics occupies a position in temperature-controlled pharmaceutical storage. Amazon represents the scale-driven automation archetype with proprietary robotics deployment across its fulfillment estate.
| Leading Market Players |
|---|
| CSM Logistics |
| Zencargo |
| Amazon |
| EUF Group Ltd |
| KSK Logistics Ltd |
| Expeditors |
| Fullers Logistics |
| Mango International |
| AIT Worldwide Logistics |
| Others |
Value Network & Pricing Analysis
Modular fulfillment procurement preferences among UK retailers are forcing warehouse developers to prioritize flexible lease structures over long-term commitments, compressing developer margins on speculative builds and redirecting capital toward brownfield retrofits with faster return profiles.
Pricing Analysis
Margin tightening in speculative grade-A warehousing reflects steel and concrete input volatility alongside grid connection queuing delays. Three-tier pricing structure across premium rail-connected sites, standard motorway-adjacent facilities, and economy secondary stock dominates procurement negotiations. Price differentiation hinges on SECR compliance readiness and clear height specifications. Cost-down pressure on mid-market operators accelerates as e-commerce platforms consolidate volume commitments. Fashion and electronics verticals exhibit highest price sensitivity due to seasonal demand spikes, while pharmaceutical buyers accept premium rates for MHRA-certified cold chain infrastructure.
Supply Chain Analysis
Steel and concrete supply rests on UK domestic producers supplemented by European imports, while automated sortation equipment draws from German and Japanese manufacturers. Warehouse management system software sources from US cloud-native providers and domestic integrators. Single-source vulnerability concentrates in high-voltage electrical infrastructure where distribution centers above 50,000 square meters face 18-24 month grid connection delays. Distribution runs through Midlands logistics corridor concentration with secondary nodes in Greater London micro-fulfillment networks and Northern Powerhouse development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial land scarcity around the East Midlands Gateway and Birmingham cluster props rental premiums, constraining new speculative supply entry and sustaining pricing power for incumbent operators with captive real estate portfolios.
For Market Incumbents: Deploy automation retrofit programs to match Amazon's throughput density in brownfield facilities. CSM Logistics and Fullers Logistics should deepen captive real estate holdings in the Midlands corridor before Northern Powerhouse infrastructure matures. Grid connection queuing poses the most severe capacity constraint, making early electrical infrastructure commitment the priority defensive move against speculative entrants.
For New Entrants and Emerging Players: Enter via last-mile micro-fulfillment convergence in Greater London's Thurrock and Dartford sub-markets where industrial land protection policies constrain incumbent expansion. Manchester and Leeds offer the most penetrable white-space for grade-A speculative stock given lower land costs and comparable M62 connectivity. Target pharmaceutical temperature-controlled storage as the go-to-market angle, where MHRA certification timelines freeze speculative development and create persistent supply-demand imbalance.
For Investors and Strategic Acquirers: Re-rating potential sits with diversified third-party logistics providers with rail-connected Midlands portfolios given SECR compliance capex requirements favoring scaled operators. Long-term viability frames around electrification readiness and cloud-native WMS deployment capabilities across a five-to-ten year infrastructure replacement cycle. Acquisition target archetype: regional networks with captive real estate and modular contract structures. Watch automated guided vehicle technician training pipeline expansion as the inflection signal for robotics penetration beyond grocery and automotive verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Infrastructure | Pre-emptive grid connection commitments bypass 18-24 month queuing delays for Castle Donington rail-connected sites. |
| Pharmaceutical Cold Chain Certification Investment | MHRA Good Distribution Practice accreditation locks in 12-18 month competitive moats for temperature-controlled operators. |
| Cloud-Native WMS Platform Deployment | Real-time inventory visibility displaces legacy ERP modules across England and Wales brownfield retrofits. |
| Last-Mile Micro-Fulfillment Network Expansion | Automated storage and retrieval systems enable 30-minute delivery promises in Greater London's constrained land environment. |
| SECR-Ready Net-Zero Specification Development | Solar-ready roofing and heat pump compatibility in Midlands speculative builds capture Building Regulations Part L first-mover premiums. |
Research Methodology
Multi-period observation of warehouse construction permits, rental rate indices, and automation deployment announcements anchored the trend analysis, supplemented by interviews with logistics facility developers, third-party logistics operations directors, retail procurement leads, and MHRA compliance officers. Secondary validation drew from UK Building Regulations Part L documentation, Streamlined Energy and Carbon Reporting filings, East Midlands Gateway development authority records, and customs/trade data through Dover and Felixstowe. Bottom-up facility-level capacity assessments triangulated against top-down sector expenditure estimates.
Input-output matrix framing connected e-commerce order volatility patterns to speculative development absorption rates across the projection horizon. Segmentation dimensions modeled encompass service type ownership structures, technology integration depth, customer procurement behavior, and end-use vertical regulatory intensity. CAGRs derived from capacity-weighted average rental growth trajectories and automation capex deployment curves. Forecast inputs incorporated grid connection queue durations and steel price futures volatility bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged commodity price spikes or accelerated SECR enforcement timelines. Forecasts reflect documented assumptions regarding Midlands logistics corridor concentration persistence and post-Brexit customs infrastructure investment continuity. A small set of triggers—AGV technician training scale, Part L revision implementation pace, and Northern Powerhouse transport funding—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Customs Brokerage Market