
 ASEAN Warehousing and Distribution Logistics Market | 2026-2036
ASEAN Warehousing and Distribution Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Warehousing and Distribution Logistics Market Outlook
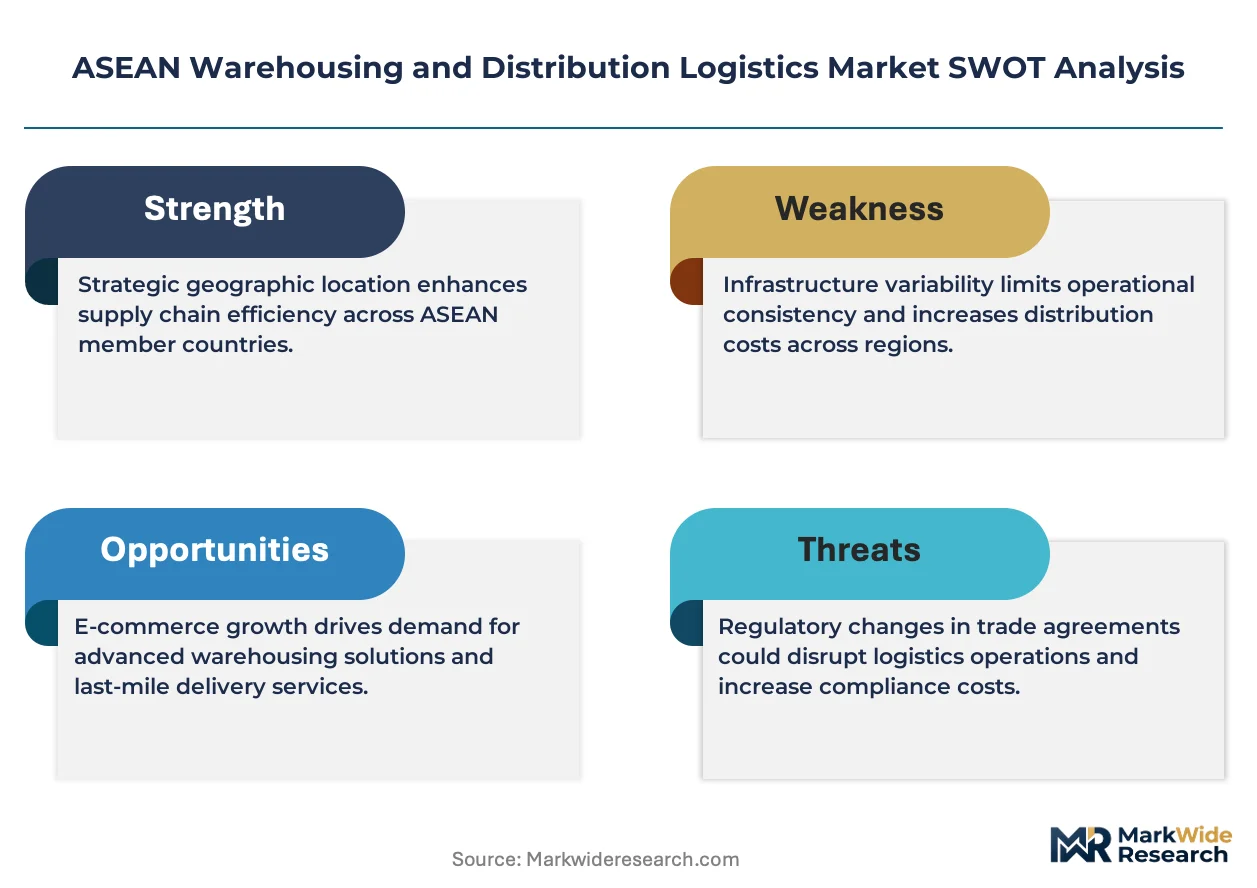
Aluminum racking systems are decoupling warehouse construction costs from steel price volatility across ASEAN industrial zones. Kuehne + Nagel leverages its pharmaceutical cold-chain expertise to dominate specialized storage in Singapore and Thailand. Kerry Logistics anchors regional connectivity through its Greater Mekong Subregion corridor network. WHA Corporation sustains competitive positioning via its captive industrial estate and logistics park development across Eastern Seaboard zones.
ASEAN warehousing and distribution logistics encompasses the physical storage, inventory management, and movement coordination of goods through facilities typically exceeding five thousand square meters with racking heights of twelve meters or more, designed to optimize throughput velocity and order accuracy for multi-channel fulfillment. Contract logistics and value-added services command margin premiums as manufacturers outsource inventory ownership and final-mile preparation to third-party operators. Automation and Warehouse Management Systems represent the fastest-expanding technology dimension, driven by labor cost pressures and same-day delivery commitments from e-commerce platforms.
Thailand's Board of Investment coordinates logistics zone incentives with the Department of Industrial Works facility standards, while Vietnam's Ministry of Transport governs cross-docking compliance through national freight corridor regulations. Indonesia's National Logistics System roadmap mandates integrated distribution center standards that affect market access for foreign operators. Stakeholders must evaluate facility automation roadmaps against divergent national certification requirements before committing capital to multi-country warehouse networks.
Market Dynamics
Cross-border e-commerce fulfillment is compressing order-to-delivery windows across Thailand, Vietnam, and Indonesia, forcing warehouse operators to automate inventory velocity management or lose contract renewals to competitors with integrated Warehouse Management Systems.
Growth Catalysts
- Indonesia's National Logistics System roadmap:Mandates integrated distribution center standards that accelerate foreign operator market entry through unified facility certification requirements.
- Same-day delivery commitments:E-commerce platforms in Bangkok and Ho Chi Minh City are pulling automation investment into temperature-controlled facilities for perishable goods handling.
- Aluminum racking systems:These structures insulate warehouse construction costs from steel price volatility across Eastern Seaboard industrial zones in Thailand.
Market Restraints
- Steel and aluminum input cost volatility:Raw material price swings compress margin predictability for racking and structural component procurement.
- Labor availability constraints:Warehouse automation specialists and cold-chain technicians remain concentrated in Singapore and Bangkok, limiting facility expansion in secondary Vietnamese and Indonesian cities.
- Cross-border customs friction:Divergent ASEAN national freight corridor regulations create compliance delays at Thailand-Vietnam and Indonesia-Malaysia transit points.
Strategic Opportunities
- Philippines logistics gap:Underpenetrated cold-chain infrastructure in Luzon and Visayas regions offers first-mover positioning for temperature-controlled distribution centers.
- Malaysia's national logistics masterplan:Incentivized Warehouse Management System adoption creates captive demand for automation integrators in Port Klang and Johor corridor.
- Cross-docking convergence with IoT tracking:Real-time inventory visibility across Mekong Subregion corridors enables asset-light network expansion without facility ownership.
Industry Challenges
- Automation-legacy system integration:Existing warehouse management platforms in Indonesian and Vietnamese facilities require costly middleware development to interface with robotic picking systems.
- Multi-country certification timelines:Divergent facility standards across Thailand's Board of Investment zones, Vietnam's Ministry of Transport regulations, and Indonesia's national roadmap delay cross-border network standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Warehousing and Distribution Logistics Market |
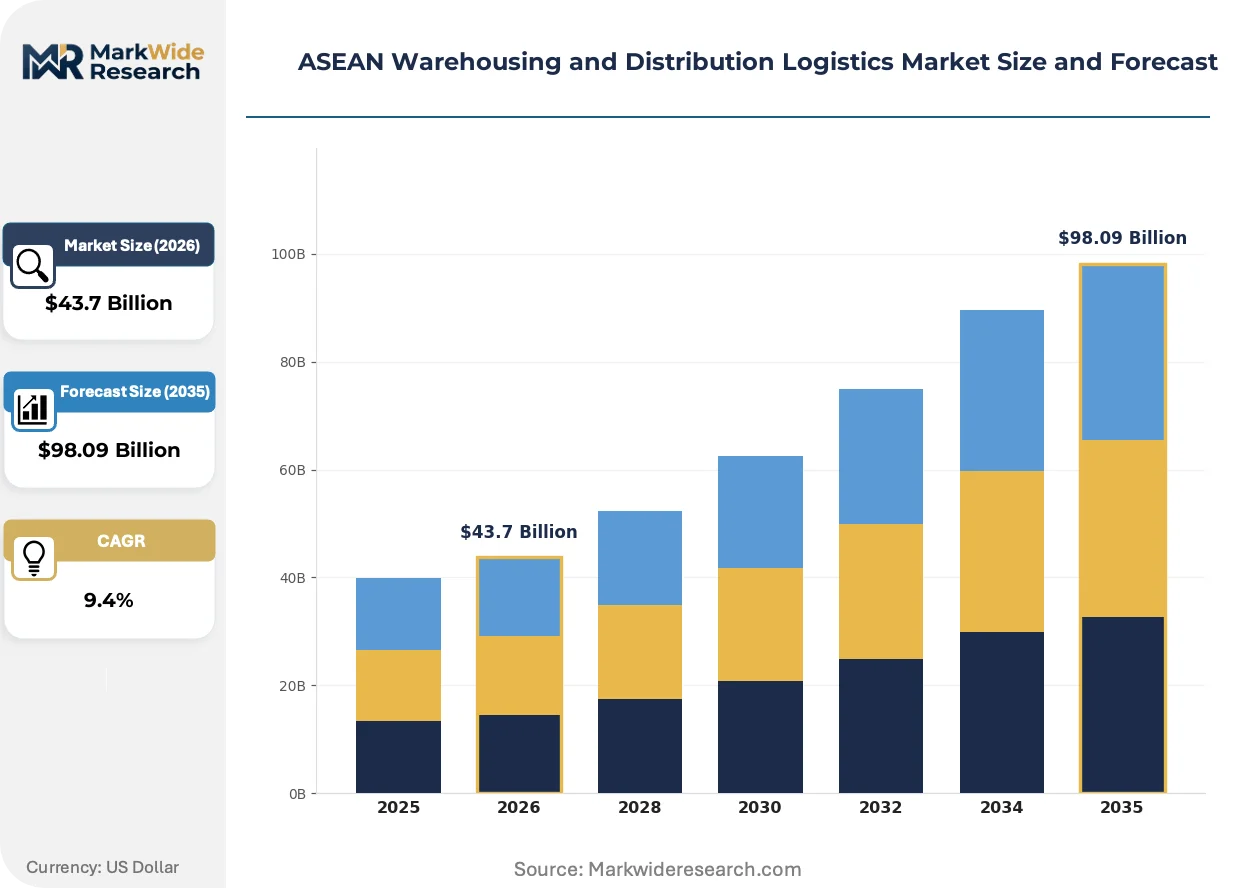
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $98.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Warehousing, Private Warehousing, Contract Logistics, Value-Added Services Technology: Warehouse Management Systems, RFID, Automation, Blockchain End User: Retail Sector, E-commerce, Manufacturing Sector, Food and Beverage Distribution Channel: Direct Shipping, Cross-Docking, Last Mile Delivery, Freight Forwarding |
| Companies Covered | Kuehne + Nagel, Kerry Logistics, DB Schenker, CWT Ltd, WHA Corporation, CEVA Logistics, DHL Supply Chain, Gemadept, Yusen Logistics, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Warehousing and Distribution Logistics Market Strategic Shifts
Automation hardware and software convergence is rewriting capital deployment priorities for ASEAN warehouse operators, with technology choices now determining contract win rates in pharmaceutical and e-commerce verticals.
Autonomous mobile robots for goods-to-person picking are electrifying throughput economics in high-velocity fulfillment centers. Pharmaceutical distributors in Singapore and Thailand are deploying these systems at scale to meet cold-chain validation requirements. The technology is electrifying competitive separation between automated operators and conventional forklift-dependent facilities across Greater Mekong corridors.
Malaysia's national logistics masterplan mandates Warehouse Management System certification for facilities receiving zone-based tax incentives. This regulatory pressure forces technology refresh cycles among incumbent operators in Port Klang and Penang. Cold-chain and pharmaceutical storage segments are responding fastest due to traceability requirements under national pharmaceutical regulator guidelines.
Buyer procurement is consolidating vendor relationships around integrated automation-and-lease bundles rather than discrete equipment purchases. Third-party logistics providers in Jakarta and Bangkok are displacing traditional racking-and-forklift procurement with full-service automation contracts. This pattern is most visible in e-commerce fulfillment verticals where same-day delivery service level agreements require guaranteed throughput commitments.
ASEAN Warehousing and Distribution Logistics Market Segmentation
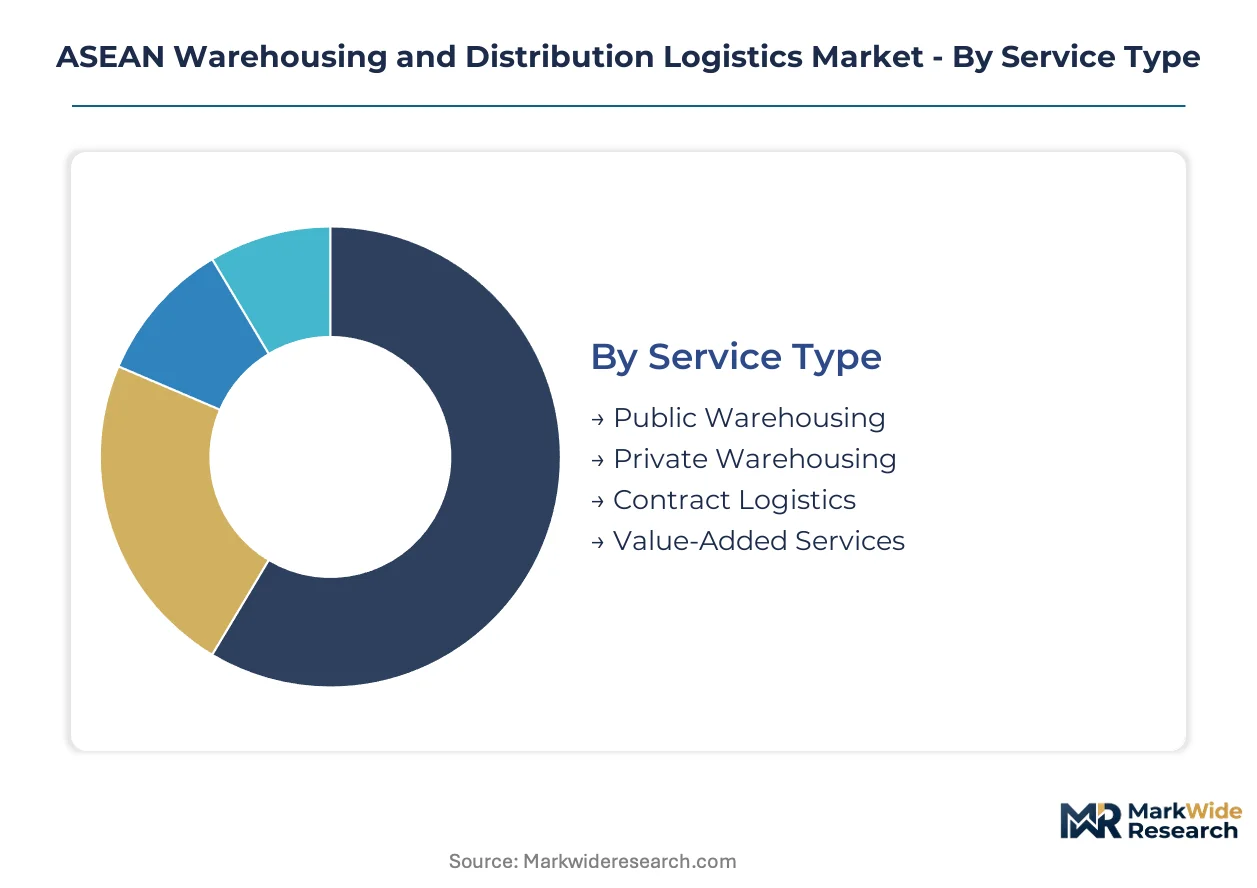
Service configuration and technology integration determine facility investment returns across ASEAN logistics corridors. Segment boundaries blur where contract operators embed WMS platforms and automation hardware into bundled service offerings.
Service Type:
Standalone warehousing operations compete against vertically integrated service bundles that combine physical storage with inventory management and final-mile preparation.
- Public Warehousing:Multi-tenant facilities with shared racking infrastructure serve seasonal demand swings and overflow inventory for manufacturers lacking dedicated distribution assets. Thailand's Eastern Seaboard industrial zones concentrate these facilities near automotive and electronics manufacturing clusters.
- Private Warehousing:Captive facilities owned or long-term leased by single corporations maintain direct control over inventory positioning and security protocols. Demand concentrates among Japanese automotive assemblers in Thailand and Indonesian consumer goods multinationals seeking regulatory compliance under the National Logistics System roadmap.
- Contract Logistics:Third-party operators assume inventory ownership risk and manage inbound-to-outbound flow coordination against service-level agreements.
- Value-Added Services:Packaging, labeling, quality inspection, and kitting operations performed within warehouse walls capture margin premiums beyond pure storage fees.
Contract logistics leads volumes today; value-added services are gaining share fastest.
Technology:
Cost tiers separate legacy operators from competitors deploying integrated automation stacks that command contract premiums.
- Warehouse Management Systems:Software platforms coordinating inventory location, order picking logic, and labor deployment have become baseline requirements for e-commerce fulfillment contracts. Malaysia's national logistics masterplan mandates WMS certification for zone-based tax incentives, accelerating replacement of spreadsheet-dependent operations in Port Klang and Johor facilities.
- Automation:Robotic picking systems, autonomous mobile robots, and automated storage and retrieval systems transform throughput economics in high-velocity facilities. Pharmaceutical distributors in Singapore and Thailand deploy these at scale to meet cold-chain validation requirements that manual operations cannot satisfy.
- RFID:Radio-frequency identification enables real-time inventory tracking without line-of-sight scanning constraints.
- Blockchain:Distributed ledger applications for provenance tracking and smart contract execution remain pilot-stage across ASEAN logistics networks.
Warehouse Management Systems dominate installed base; automation is expanding most quickly.
End User:
Application-specific requirements drive divergent facility specifications across temperature control, security, and throughput dimensions.
- E-commerce:Same-day delivery commitments in Bangkok and Ho Chi Minh City pull investment into urban fulfillment centers with automated sortation and last-mile handoff capabilities. Platform operators consolidate vendor relationships around integrated automation-and-lease bundles rather than discrete equipment procurement.
- Food and Beverage:Temperature-controlled storage and handling protocols dominate facility design for perishable supply chains. Indonesia's archipelago geography and Vietnam's Mekong Delta agricultural output create concentrated demand for cold-chain infrastructure that remains underpenetrated in secondary cities.
- Retail Sector:Omnichannel inventory pooling requires facilities capable of replenishing physical stores while fulfilling direct-to-consumer orders.
- Manufacturing Sector:Just-in-time production dependencies demand cross-docking and sequencing centers positioned within hours of assembly plants.
Manufacturing sector anchors current capacity; e-commerce is climbing the fastest.
Distribution Channel:
Volume concentration and margin profiles vary sharply across channel configurations that determine asset-light versus asset-heavy competitive positioning.
- Cross-Docking:Facilities designed for rapid inventory transfer without long-term storage minimize handling costs for time-sensitive freight. Vietnam's Ministry of Transport governs cross-docking compliance through national freight corridor regulations that affect Mekong Subregion connectivity.
- Last Mile Delivery:Urban micro-fulfillment centers and courier handoff points address final-leg cost compression in dense metropolitan markets. Jakarta and Bangkok operators face land scarcity constraints that favor vertical facility designs and automated sortation over horizontal expansion.
- Direct Shipping:Point-to-point freight movement bypassing intermediate distribution nodes serves bulk commodity flows.
- Freight Forwarding:Intermediary coordination of multi-modal transport and customs clearance adds service layers to physical distribution.
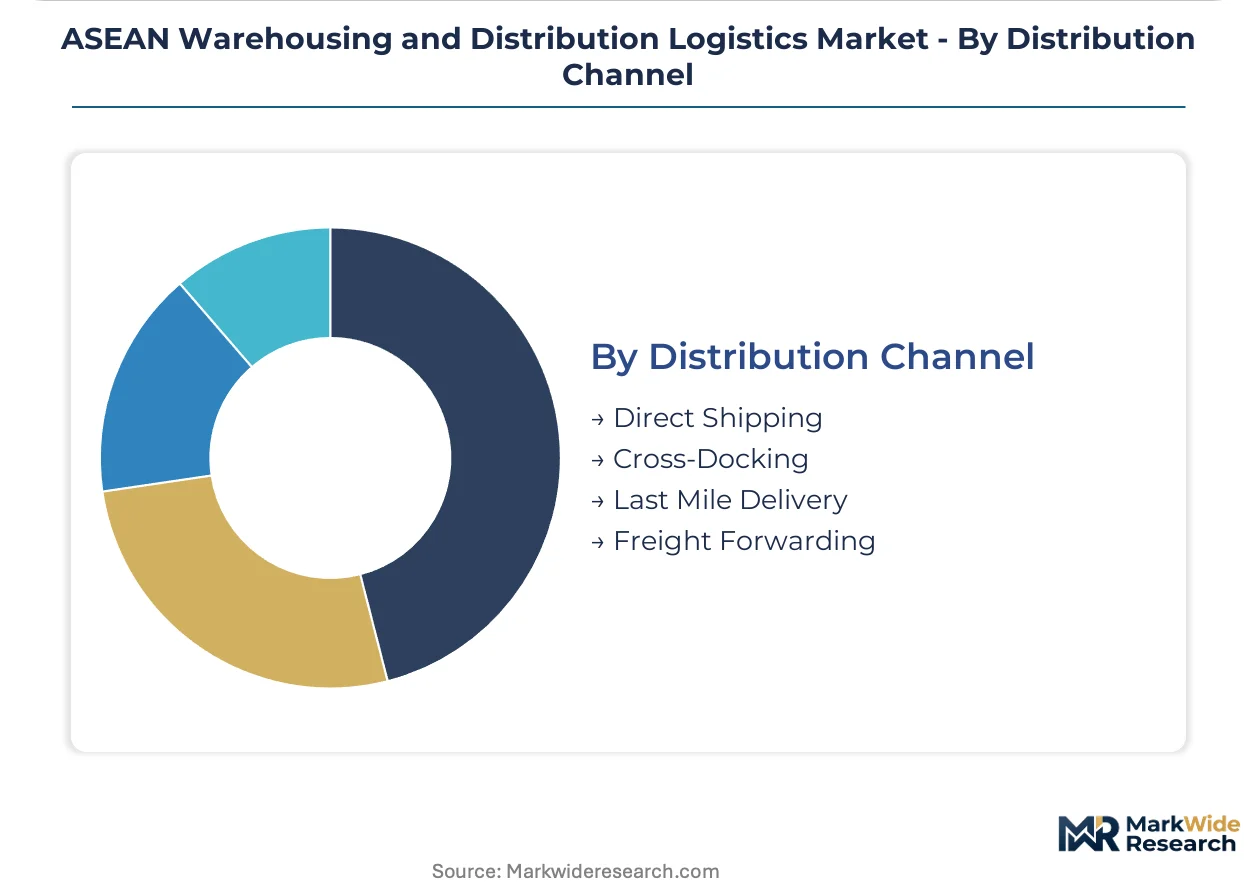
Freight forwarding leads transaction volumes today; last mile delivery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Seaboard industrial corridor anchors ASEAN warehousing capacity expansion through automotive and electronics manufacturing concentration that pulls distribution infrastructure investment into Thailand's Chonburi and Rayong provinces.
Thailand
Automotive assembly plants and electronics manufacturing clusters generate sustained demand for cross-docking facilities and sequencing centers. Thailand's Board of Investment coordinates logistics zone incentives with Department of Industrial Works facility standards that mandate automation readiness. Chonburi and Rayong provinces concentrate new distribution center development near Laem Chabang port and industrial estates.
Vietnam
E-commerce fulfillment networks and Mekong Delta agricultural exports intensify cold-chain infrastructure requirements in Ho Chi Minh City and surrounding provinces. Vietnam's Ministry of Transport governs cross-docking compliance through national freight corridor regulations affecting Mekong Subregion connectivity. Binh Duong and Dong Nai provinces attract distribution investment through proximity to manufacturing zones and Cat Lai port.
Indonesia
Archipelago geography and consumer market scale drive demand for integrated distribution centers serving Jakarta metropolitan area and Surabaya. Indonesia's National Logistics System roadmap mandates facility certification standards that accelerate foreign operator market entry. Bekasi and Karawang industrial zones concentrate warehouse development through land availability and toll road connectivity.
Singapore
Pharmaceutical cold-chain validation requirements and regional headquarters functions sustain premium logistics service demand. Singapore's national pharmaceutical regulator enforces traceability standards that pull automation investment into temperature-controlled facilities. Jurong Island and Changi logistics zones anchor specialized storage for biomedical and aerospace supply chains.
Malaysia
Port Klang container throughput and Johor corridor manufacturing generate contract logistics demand for integrated warehousing and value-added services. Malaysia's national logistics masterplan mandates Warehouse Management System certification for zone-based tax incentives. Shah Alam and Pasir Gudang industrial areas concentrate facility development near Port Klang and Tanjung Pelepas ports.
ASEAN Warehousing and Distribution Logistics Market Competitive Environment
Technology licensing and automation partnerships dominate the current landscape as operators seek to differentiate throughput capabilities without full capital ownership. The market structures around three tiers: global integrated logistics providers with regional headquarters functions, Asian regional specialists with corridor-specific network density, and domestic industrial estate developers with captive logistics park assets. Strategic archetypes include pharmaceutical cold-chain validators, e-commerce fulfillment automation integrators, and industrial zone master developers. Competitive moves concentrate on automation-and-lease bundling and cross-border corridor network expansion.
Among global integrated providers, Kuehne + Nagel and DHL Supply Chain exemplify the pharmaceutical cold-chain validation archetype through Singapore and Thailand facility concentration. Kerry Logistics occupies a position within the Asian regional specialist tier with Greater Mekong Subregion corridor network density. WHA Corporation represents the industrial estate developer archetype through Eastern Seaboard logistics park development. These three company types anchor competitive positioning across automation capability, geographic coverage, and asset ownership models.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Kerry Logistics |
| DB Schenker |
| CWT Ltd |
| WHA Corporation |
| CEVA Logistics |
| DHL Supply Chain |
| Gemadept |
| Yusen Logistics |
| Others |
Value Chain & Pricing Dynamics
Cold-chain automation specialists concentrated in Singapore and Bangkok command wage premiums that compress margin spreads between premium-tier certified facilities and standard warehouse operations across secondary Vietnamese and Indonesian cities. Labor-cost differentials between these talent hubs and emerging markets force pricing-tier stratification that rewards operators with captive technician training pipelines.
Pricing Analysis
Input-cost pass-through from aluminum and steel racking systems drives contract repricing cycles across ASEAN industrial zones. Three-tier pricing structure across pharmaceutical-certified, automation-enabled, and conventional forklift-dependent facilities separates margin tiers by validation level and throughput guarantee. Pricing pressure stems from e-commerce platforms demanding same-day delivery service level agreements without corresponding rate premiums. Small and mid-sized manufacturers exhibit highest price sensitivity, while pharmaceutical distributors accept premium tiers for cold-chain compliance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Japanese automotive assemblers in Thailand's Eastern Seaboard, while distributor networks serve fragmented Indonesian consumer goods manufacturers. Equipment and automation hardware concentrates in China, South Korea, and Japan, with racking systems and robotic components feeding ASEAN facility construction. Raw material dependencies span aluminum extrusions, high-grade steel, and precision sensors for temperature monitoring. Single-source vulnerability from concentrated automation vendor bases in Northeast Asia exposes project timelines to export control disruptions. Distribution runs through industrial estate developers with captive logistics park assets alongside independent third-party procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation-enabled margin expansion defines this market's value-creation trajectory, with Warehouse Management System certification under Malaysia's national logistics masterplan pulling premium-tier pricing into previously commoditized segments.
For Market Incumbents: Deepen automation-and-lease bundling capabilities to defend contract renewal rates against asset-light competitors with IoT-enabled network expansion. Integrate backward into captive aluminum racking fabrication to insulate construction costs from steel price volatility. Prioritize technician training academies in Ho Chi Minh City and Jakarta to reduce dependency on Singapore-Bangkok labor pools. For New Entrants and Emerging Players: Begin with underpenetrated cold-chain infrastructure in the Philippines' Luzon and Visayas regions, where first-mover positioning in temperature-controlled distribution centers avoids entrenched competition. Target pharmaceutical verticals requiring traceability validation that incumbent spreadsheet-dependent operations cannot satisfy. Lead with integrated WMS-automation contracts rather than discrete equipment sales to align with e-commerce procurement consolidation. For Investors and Strategic Acquirers: Asian regional specialists with Greater Mekong Subregion corridor network density are the most active acquirers in this space, consolidating automation capabilities and cross-border permits. Long-term viability hinges on exposure to e-commerce fulfillment automation rather than conventional warehousing. Target acquisition archetypes include industrial estate developers with captive logistics park assets and cold-chain validators with pharmaceutical regulator relationships. Monitor Indonesia's National Logistics System roadmap implementation velocity as inflection indicator for foreign operator market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automation-and-Lease Bundling | Displaces discrete equipment procurement in Jakarta and Bangkok e-commerce fulfillment verticals. |
| Cross-Border Corridor Network Expansion | Kerry Logistics anchors Greater Mekong Subregion connectivity through Vietnam-Thailand-Jakarta linkages. |
| Cold-Chain Infrastructure Buildout | Kuehne + Nagel leverages pharmaceutical expertise to dominate specialized storage in Singapore and Thailand. |
| Warehouse Management System Certification | Malaysia's national logistics masterplan mandates adoption for Port Klang zone-based tax incentives. |
| Industrial Estate and Logistics Park Development | WHA Corporation sustains competitive positioning across Thailand's Eastern Seaboard zones. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics zone operators, automation integrators, cold-chain facility managers, and e-commerce procurement leads with secondary validation from Thailand's Board of Investment incentive disclosures, Vietnam's Ministry of Transport freight corridor regulations, Indonesia's National Logistics System roadmap documents, and customs trade flow data. Bottom-up facility count modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across service type, technology integration level, end-user vertical, and distribution channel dimensions throughout the projection horizon. CAGRs were derived from facility investment pipeline tracking and automation adoption curve analysis. Forecast inputs included e-commerce same-day delivery commitment expansion rates and national logistics masterplan implementation schedules across ASEAN member states.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to Indonesia's facility certification standards and disruptive trade policy shifts affecting Thailand-Vietnam cross-border corridors. Forecasts reflect documented assumptions about labor availability constraints and automation hardware import tariff stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Netherlands Freight and Logistics Market