
 India Direct-To-Consumer (D2C) Logistics Market | 2026-2036
India Direct-To-Consumer (D2C) Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
India Direct-To-Consumer (D2C) Logistics Market Foresight
Biodegradable packaging is expanding as the default material standard across D2C shipments, replacing conventional plastic wraps as brands face EPR mandates and consumer preference shifts. Delhivery leverages its multi-modal network to dominate express deliveries across Tier-2 and Tier-3 pin codes. Shiprocket sustains aggregator economics by consolidating fragmented seller bases onto unified shipping platforms. Ecom Express anchors its position through deep rural penetration and specialized handling for high-value electronics.
India Direct-To-Consumer Logistics encompasses the end-to-end movement of goods from seller inventory to individual residential addresses, incorporating first-mile collection, sortation at automated hubs, and final handoff through gig-worker fleets or dedicated delivery associates. Same-day delivery operates on sub-four-hour fulfillment windows requiring micro-warehouse placement within fifteen kilometers of demand clusters. Last-mile delivery commands the largest operational cost share due to address density challenges and return-trip inefficiencies, while warehousing margin pools deepen as brands adopt bonded storage and value-added kitting services to reduce working capital cycles.
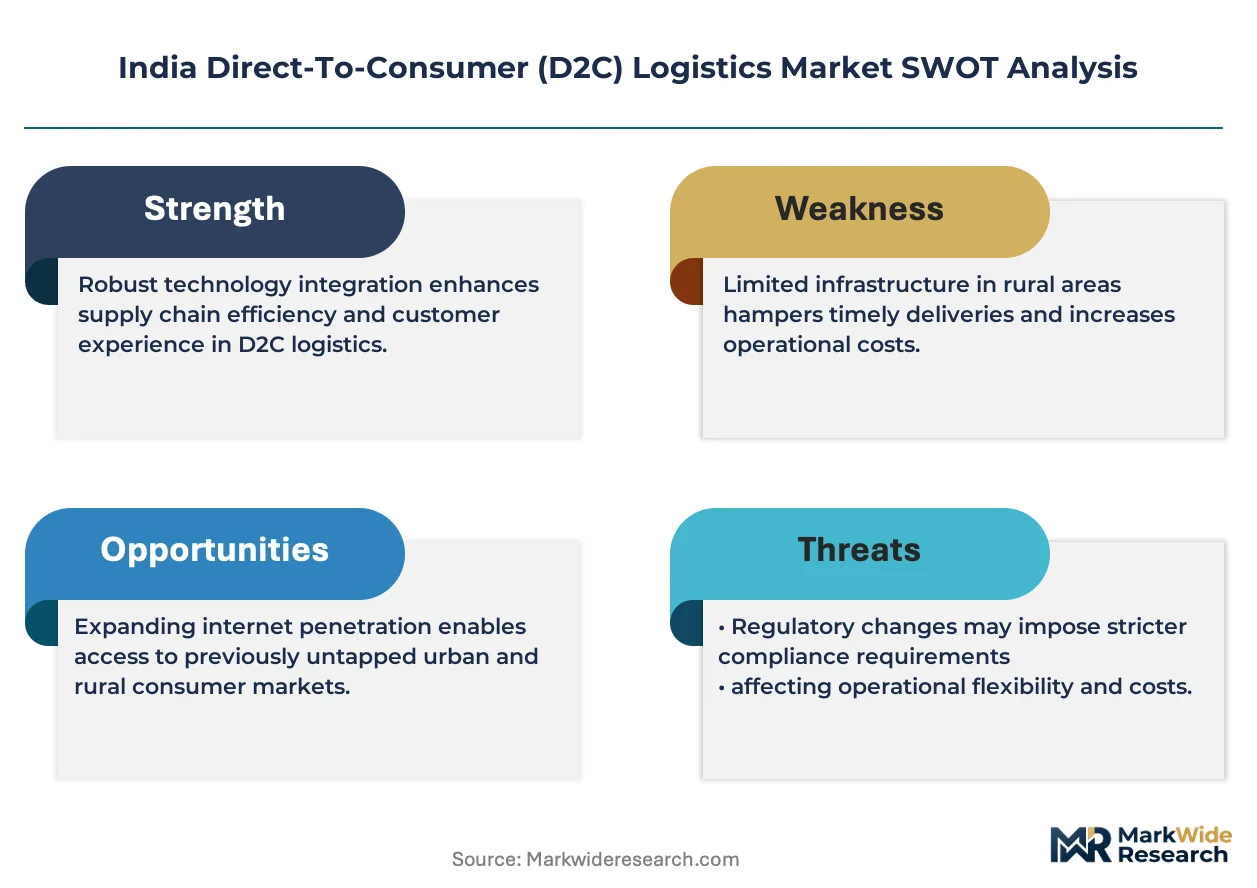
BIS standards for packaging integrity and the CEA's warehouse energy-efficiency guidelines shape infrastructure investment patterns across fulfillment networks. FSSAI regulations govern temperature-controlled last-mile protocols for D2C food and nutraceutical brands, restricting unqualified carriers from perishable lanes. Stakeholders must monitor how CDSCO's evolving e-pharma distribution rules and state-level RTO permit harmonization reshape fleet deployment models and hub licensing requirements.
Market Dynamics
India's D2C logistics sector is being fundamentally restructured by the PLI scheme's warehouse automation mandates, which compel brands to retrofit fulfillment infrastructure for bonded storage and value-added kitting services.
Growth Catalysts
- Textile PLI incentives:The government's production-linked incentive scheme for textiles is accelerating automated sortation hub investments across Maharashtra and Karnataka, compressing order-to-dispatch cycles for fashion brands.
- EPR mandates on packaging:Extended producer responsibility regulations are forcing material substitution toward biodegradable wraps, creating standardized sustainability protocols across carrier networks.
- Metro density clustering:Same-day delivery demand concentrates in Delhi NCR, Mumbai, and Bengaluru, where fifteen-kilometer micro-warehouse placement enables sub-four-hour fulfillment windows.
Market Restraints
- Diesel price volatility:Fuel constitutes the largest variable cost component for last-mile fleets, with price spikes immediately compressing margins on rural delivery routes.
- Address density asymmetry:Low pin-code clustering in Tier-3 towns forces return-trip inefficiencies, elevating per-package delivery costs above urban benchmarks by substantial multiples.
- FSSAI cold-chain exclusion:Temperature-controlled certification requirements bar unqualified carriers from perishable D2C lanes, restricting pool of eligible logistics providers for food and nutraceutical brands.
Strategic Opportunities
- Assam and Northeast penetration:Underdeveloped last-mile infrastructure in these states presents first-mover advantages for carriers establishing dedicated hub-and-spoke networks.
- E-pharma distribution liberalization:CDSCO's evolving telemedicine and online pharmacy rules are opening specialized cold-chain corridors for prescription delivery.
- Drone integration:Convergence of unmanned aerial systems with existing ground fleets is enabling leapfrog solutions for Himalayan and island geographies where road access remains seasonal.
Industry Challenges
- Gig-worker retention:High churn among delivery associates disrupts service consistency, forcing continuous recruitment expenditure and training overhead.
- CEA energy-compliance retrofitting:Warehouse energy-efficiency guidelines require capital-intensive HVAC and lighting upgrades at existing fulfillment centers.
- Return logistics complexity:Apparel-heavy D2C volumes generate elevated reverse-flow shipments, demanding dedicated sortation capacity that sits idle during forward-peak periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Direct-To-Consumer (D2C) Logistics Market |
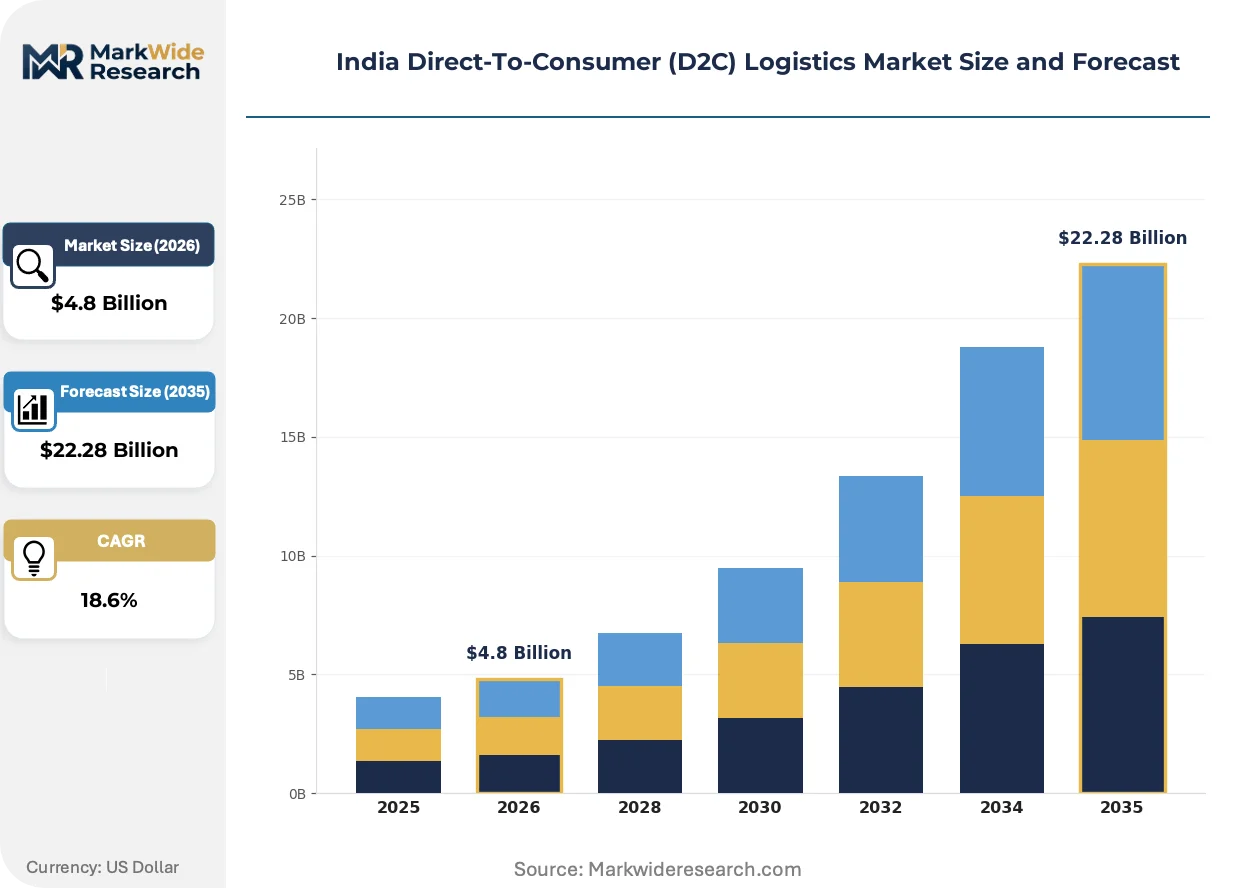
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Scheduled Delivery Shipping Method: Air Freight, Sea Freight, Rail Transport, Road Transport Packaging Type: Boxed Packaging, Flexible Packaging, Bulk Packaging, Palletized Packaging Service Type: Last-Mile Delivery, Warehousing, Fulfillment Services, Reverse Logistics |
| Companies Covered | Delhivery, Shadowfax, XpressBees, DHL, Mahindra Logistics Ltd., Pickrr, Shiprocket, Ecom Express, Zippee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Direct-To-Consumer (D2C) Logistics Market Shifts & Advancements
Automation, regulatory compliance, and buyer behavior are converging to reshape how inventory flows from brand warehouses to residential doorsteps across Indian metros and emerging towns.
Micro-fulfillment centers positioned within dense urban clusters are decentralizing inventory placement away from regional mega-hubs. Fashion and electronics brands are deploying these facilities in Bengaluru's Koramangala and Mumbai's Andheri corridors. This topology collapse is compressing last-mile distances and enabling same-day delivery economics previously viable only in hyperlocal grocery.
BIS packaging integrity standards are mandating drop-test certification and tamper-evident sealing for all D2C shipments. The regulation forces brands to redesign primary and secondary packaging, particularly for glass and liquid products. Electronics and cosmetics verticals are absorbing the highest compliance costs, with many sellers consolidating onto certified third-party logistics providers rather than maintaining in-house quality labs.
Subscription-based replenishment models are displacing one-time purchase behavior in personal care and pet food categories. Direct brand sites and WhatsApp commerce channels are capturing recurring revenue streams that marketplaces previously intermediated. This shift is most pronounced in Pune and Hyderabad, where dual-income households prioritize convenience over price comparison.
India Direct-To-Consumer (D2C) Logistics Market Segmentation
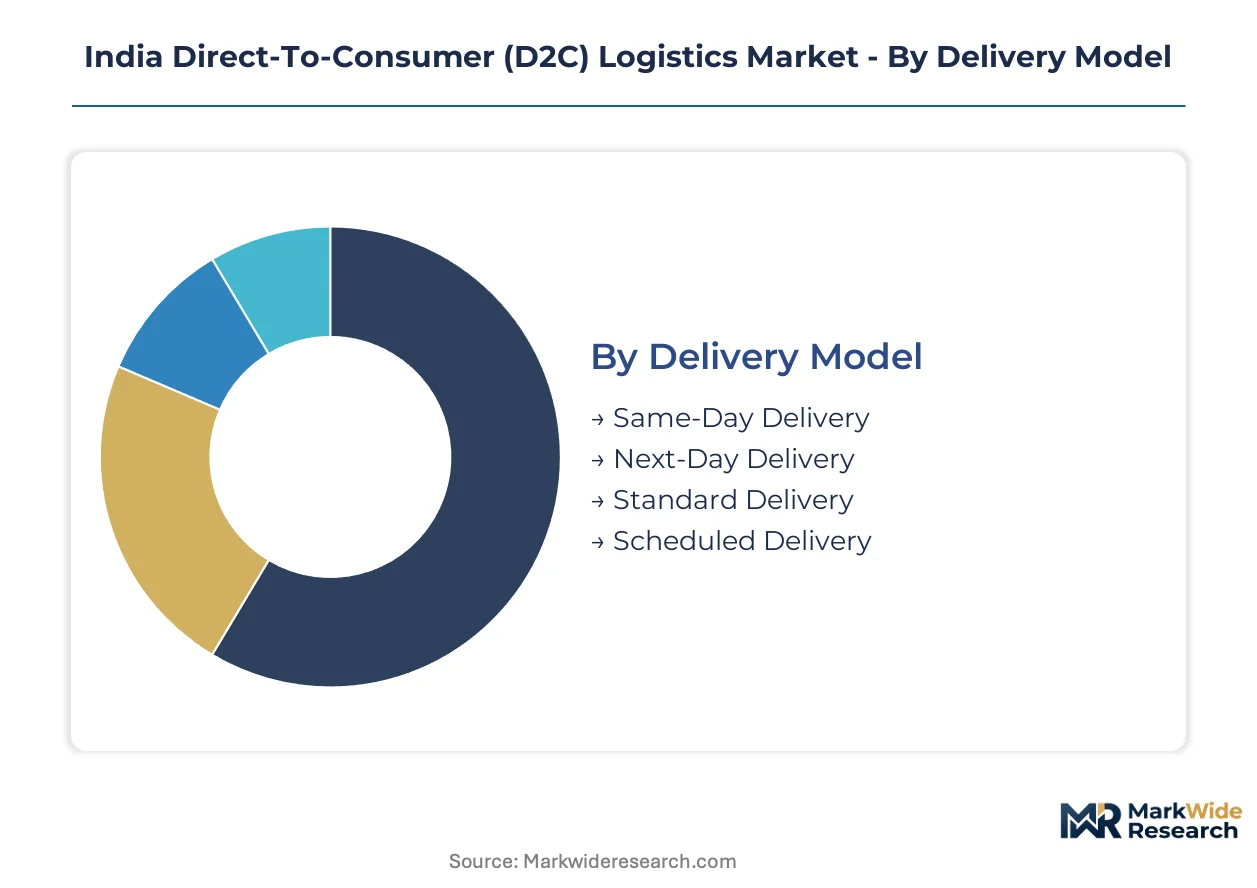
D2C logistics in India fragments across service layers that command distinct margin profiles and capital requirements. Delivery velocity, modal choice, and packaging standards each create separate competitive arenas with unique regulatory exposure and technology intensity.
Delivery Model:
Velocity expectations separate premium-paying urban consumers from price-sensitive mass-market buyers across Maharashtra, Karnataka, and Delhi NCR.
- Same-Day Delivery:Sub-four-hour fulfillment windows demand micro-warehouse placement within fifteen kilometers of demand clusters. Fashion and electronics brands in Mumbai and Bengaluru absorb the highest infrastructure costs for this segment.
- Next-Day Delivery:Overnight sortation at automated hubs enables next-morning handoff without the real estate premium of micro-fulfillment. This tier captures the largest volume share among metro households.
- Standard Delivery:Two-to-four-day windows dominate Tier-2 and Tier-3 penetration where road networks limit express feasibility.
- Scheduled Delivery:Appointment-based handoff suits furniture and large appliances requiring recipient presence; reverse logistics integration reduces failed delivery rates.
Next-day delivery leads volumes today; same-day delivery is gaining share fastest.
Shipping Method:
Modal selection hinges on cargo value density, perishability constraints, and the PLI scheme's bonded storage requirements for textile and electronics exports.
- Road Transport:Dominates domestic D2C with 85% plus share; last-mile fleets and inter-city trucking form the backbone of Delhivery and Ecom Express networks.
- Air Freight:Express parcels and high-value electronics move through Bengaluru and Delhi airport cargo terminals; fuel surcharges compress margins on lightweight shipments.
- Rail Transport:Bulk consolidated loads between regional hubs reduce per-unit costs for non-urgent inventory repositioning.
- Sea Freight:Limited to cross-border D2C and bulk import legs; container availability fluctuations disrupt replenishment cycles for imported brands.
Road transport anchors domestic fulfillment; air freight climbs fastest on electronics and pharma corridors.
Packaging Type:
BIS integrity standards and EPR mandates are forcing material substitution decisions that ripple through cost structures and sustainability positioning.
- Flexible Packaging:Biodegradable wraps and mailers are displacing conventional plastics under FSSAI and BIS pressure; apparel brands drive demand.
- Boxed Packaging:Corrugated containers with tamper-evident sealing dominate electronics and cosmetics; drop-test certification adds compliance overhead.
- Bulk Packaging:Consolidated master cartons reduce per-unit handling costs for subscription replenishment models in personal care.
- Palletized Packaging:Hub-to-hub movements and B2B replenishment legs utilize standard pallet dimensions for forklift efficiency.
Flexible packaging expands most quickly on regulatory tailwinds; boxed formats retain the revenue base.
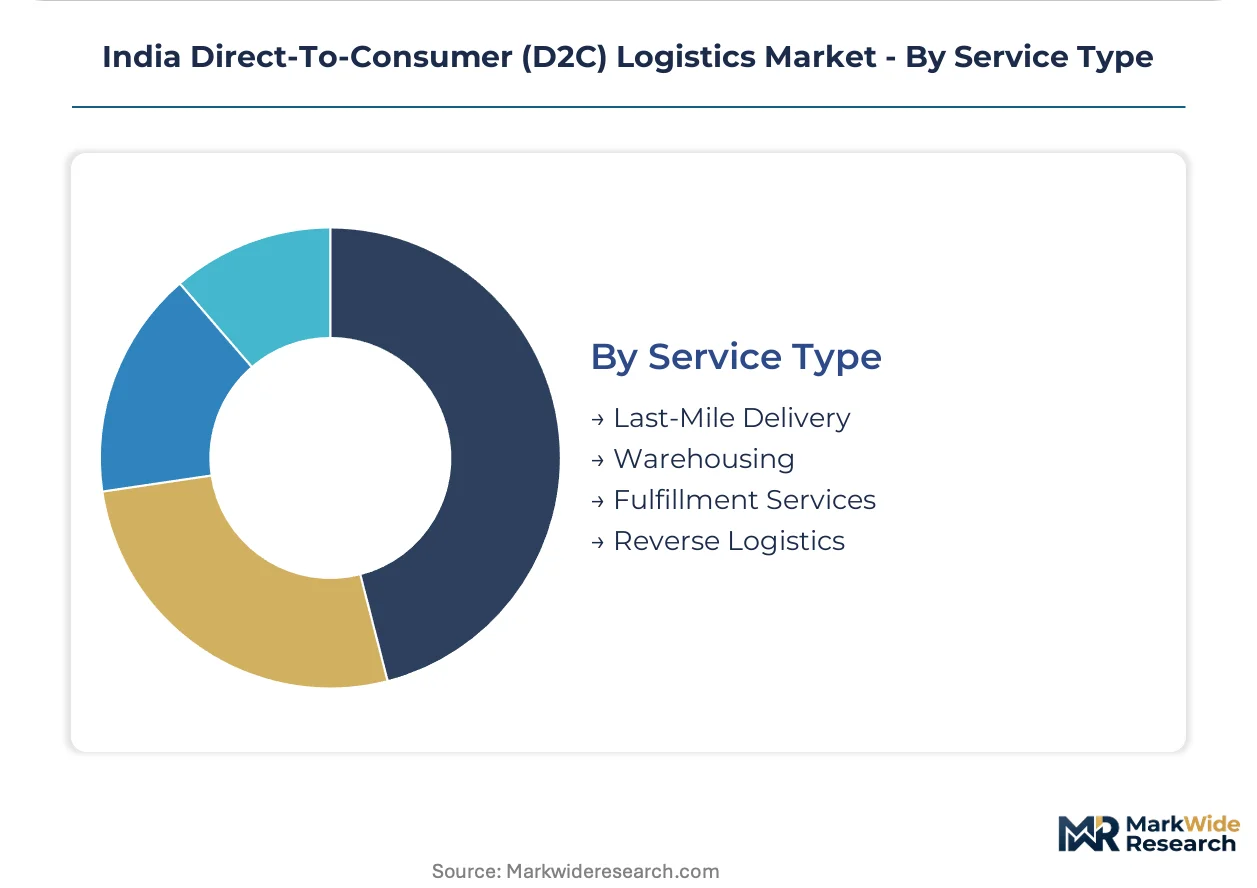
Service Type:
Margin capture shifts from pure transportation toward value-added inventory services that reduce working capital cycles for D2C brands.
- Last-Mile Delivery:Gig-worker fleets and dedicated associates execute final handoff; address density asymmetries between metros and Tier-3 towns create cost divergence.
- Fulfillment Services:Bonded storage, kitting, and gift-wrapped dispatch command premium pricing; PLI textile incentives accelerate automation investment here.
- Warehousing:CEA energy-efficiency guidelines require HVAC and lighting retrofits; climate-controlled zones for electronics and cosmetics deepen margin pools.
- Reverse Logistics:Apparel-heavy return volumes demand dedicated sortation capacity; quality-check and repackaging workflows extend inventory recovery rates.
Last-mile delivery generates the highest revenue share; fulfillment services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors India's D2C logistics density, with Mumbai's Andheri-Kurla corridor hosting the highest concentration of micro-fulfillment centers serving same-day delivery windows for fashion and electronics brands.
Maharashtra
Mumbai and Pune generate the bulk of express delivery volumes, driven by dual-income households prioritizing convenience subscriptions in personal care and pet food. The state's PLI scheme for textiles accelerates automated sortation hub investments around Bhiwandi. Thane's warehouse cluster now hosts bonded storage facilities reducing working capital cycles for apparel exporters.
Karnataka
Bengaluru's Koramangala and Whitefield corridors concentrate micro-warehouse placement for sub-four-hour fulfillment, serving electronics and cosmetics brands. TRAI's digital infrastructure push enables real-time fleet tracking across the state's gig-worker networks. The Electronic City hub processes the highest air-freight volumes for high-value electronics moving through Kempegowda International Airport.
Delhi NCR
Gurgaon and Noida's logistics parks command premium warehousing rents due to fifteen-kilometer proximity to dense residential clusters. FSSAI's cold-chain certification requirements filter carrier eligibility for perishable D2C lanes originating from Ghaziabad food processing units. The region's return logistics complexity exceeds national benchmarks due to apparel-heavy purchase patterns.
Telangana
Hyderabad's pharma corridor attracts specialized cold-chain investment as CDSCO's e-pharma distribution rules liberalize prescription delivery. The state's electronics manufacturing incentives under PLI scheme draw bonded warehouse automation. Shamshabad's cargo terminal anchors air-freight connectivity for temperature-sensitive nutraceutical shipments.
Tamil Nadu
Chennai's Sriperumbudur belt integrates textile PLI beneficiaries with automated fulfillment infrastructure for export-oriented D2C brands. CEA's warehouse energy-efficiency guidelines drive HVAC retrofitting at existing facilities in Ambattur. The Coimbatore tier-2 cluster demonstrates viable same-day economics through denser address clustering than comparable inland cities.
India Direct-To-Consumer (D2C) Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape, with carriers retrofitting fulfillment infrastructure to capture PLI-linked textile and electronics volumes. The market exhibits tiered consolidation: national full-stack operators control express corridors, regional specialists anchor rural penetration, and aggregator platforms consolidate fragmented seller bases. Three archetypes define positioning: asset-heavy network owners, technology-enabled aggregators, and vertical specialists in high-value or perishable categories. M&A activity concentrates on last-mile fleet acquisitions and warehouse automation technology licensing.
Among full-stack network operators, Delhivery exemplifies the asset-heavy archetype through its multi-modal coverage density, while Ecom Express occupies a specialized position in rural electronics handling. Shiprocket represents the aggregator model, consolidating seller fragmentation onto unified shipping platforms without captive infrastructure investment. These three anchors illustrate the strategic divergence between owning physical networks versus orchestrating distributed capacity.
| Leading Market Players |
|---|
| Delhivery |
| Shadowfax |
| XpressBees |
| DHL |
| Mahindra Logistics Ltd. |
| Pickrr |
| Shiprocket |
| Ecom Express |
| Zippee |
| Others |
Supply & Pricing Matrix
Fashion and electronics brands in Mumbai and Bengaluru absorb infrastructure premiums for same-day delivery windows, anchoring a pricing model where velocity tiers separate premium-paying urban households from price-sensitive mass-market buyers across Tier-2 and Tier-3 corridors.
Pricing Analysis
Diesel price volatility passes through immediately to per-package rates on rural routes, compressing carrier margins when fuel spikes hit. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and address density, with metro same-day commanding multiples over Tier-3 standard windows. Cost compression in the economy tier is intensifying because gig-worker churn forces continuous recruitment expenditure. Mass-market buyers in low-density pin codes exhibit highest price sensitivity; subscription-heavy personal care brands in Pune and Hyderabad show lowest.
Supply Chain Analysis
Hub-and-spoke distribution through Bhiwandi, Sriperumbudur, and Electronic City clusters handles bonded storage demand from PLI textile and electronics beneficiaries. Supply concentrates in Maharashtra, Karnataka, and Delhi NCR, with secondary nodes emerging in Telangana and Tamil Nadu. Raw material dependencies include corrugated packaging from domestic paper mills, biodegradable wrap films, and automated sortation equipment. Single-source vulnerability sits with imported conveyor systems and European cold-chain compressors. Distribution runs through Delhivery's multi-modal network, Shiprocket's aggregator platform, and Ecom Express's rural fleet.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's D2C logistics sector functions as a regulatory compounder where BIS packaging integrity mandates and FSSAI cold-chain certifications continuously reshape carrier eligibility and infrastructure investment thresholds.
For Market Incumbents: Deploy warehouse automation retrofits to capture PLI-linked textile and electronics volumes before compliance deadlines harden. Consolidate rural fleet density through dedicated hub-and-spoke networks in Assam and the Northeast, insulating against diesel price volatility through route optimization algorithms. Certification investment in FSSAI temperature-controlled protocols defends position against unqualified entrants barred from perishable lanes. For New Entrants and Emerging Players: Aggregator partnerships with fragmented seller bases on Shopify and WhatsApp commerce channels open immediate volume access without captive infrastructure. Drone-enabled last-mile solutions for Himalayan and island geographies present the most penetrable white-space, leapfrogging road-dependent incumbents where seasonal access limits ground fleets. White-label fulfillment services for subscription personal care brands in Hyderabad and Pune offer a defensible go-to-market anchor. For Investors and Strategic Acquirers: Private equity firms with logistics portfolio companies are the most active acquirers in this space, seeking last-mile fleet assets and warehouse automation technology licensing. Long-term viability hinges on carriers proving rural unit economics at scale while absorbing CEA energy-efficiency retrofit costs. Acquisition targets should demonstrate bonded storage capabilities and FSSAI certification moats. The inflection signal to watch is CDSCO e-pharma distribution liberalization accelerating specialized cold-chain corridor investment.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Fifteen-kilometer warehouse placement in Koramangala and Andheri enables sub-four-hour economics. |
| Biodegradable Packaging Transition | EPR mandates force material substitution ahead of BIS drop-test certification deadlines. |
| Rural Hub-and-Spoke Buildout | Dedicated networks in Assam and Northeast states capture first-mover advantages. |
| Cold-Chain Certification Investment | FSSAI temperature-controlled protocols unlock perishable D2C lanes for nutraceutical brands. |
| Drone Fleet Integration | Unmanned aerial systems address Himalayan and island geographies where roads fail seasonally. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics operations directors, D2C brand supply chain heads, gig-worker fleet managers, and warehouse automation vendors with secondary validation through PLI scheme filings, BIS standards documentation, FSSAI certification registries, and customs bonded warehouse records. Bottom-up carrier volume data and top-down D2C brand fulfillment spend estimates were triangulated to anchor market sizing.
Comparable historical periods across the analysis window established baseline growth trajectories for projection modeling. Segmentation dimensions included delivery velocity tier, shipping method, packaging type, and service layer, with regional regulatory clusters and PLI beneficiary status as industry-specific overlays. CAGRs were derived from trend extrapolation of automated hub investments and same-day delivery penetration curves, incorporating diesel price elasticity and gig-worker wage inflation as forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CDSCO e-pharma rule evolution, state-level RTO permit harmonization, and drone regulatory framework finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Nordics Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transport Market