
 Japan Cold Chain Logistics Market | 2026-2036
Japan Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cold Chain Logistics Market Foresight
The F-Gas Regulation is repositioning the cost-of-entry calculus for refrigerated transport operators across Japan. Mitsubishi Logistics leverages its port-centric warehouse network to dominate temperature-controlled sea freight consolidation. Nichirei Logistics Group anchors its competitive stance through specialized pharmaceutical cold storage facilities nationwide. Sagawa Express differentiates via dense last-mile delivery infrastructure serving Tokyo and Osaka metropolitan zones.
Japan cold chain logistics denotes the integrated system of temperature-controlled storage, handling, and distribution infrastructure maintaining product integrity between 2°C and 8°C for pharmaceuticals and sub-zero thresholds for frozen foods, utilizing vapor-compression refrigeration, insulated vehicle bodies, and real-time monitoring telemetry. The primary commercial purpose centers on preventing thermal degradation of perishable goods across extended supply chains spanning import gateways to retail endpoints. Pharmaceutical cold storage commands premium margin pools due to stringent validation requirements and limited certified facility availability. IoT-enabled solutions represent the fastest-expanding technology dimension as operators deploy sensor networks for regulatory compliance documentation. Road transport occupies the dominant delivery mode position, reflecting Japan's archipelago geography and just-in-time replenishment norms.
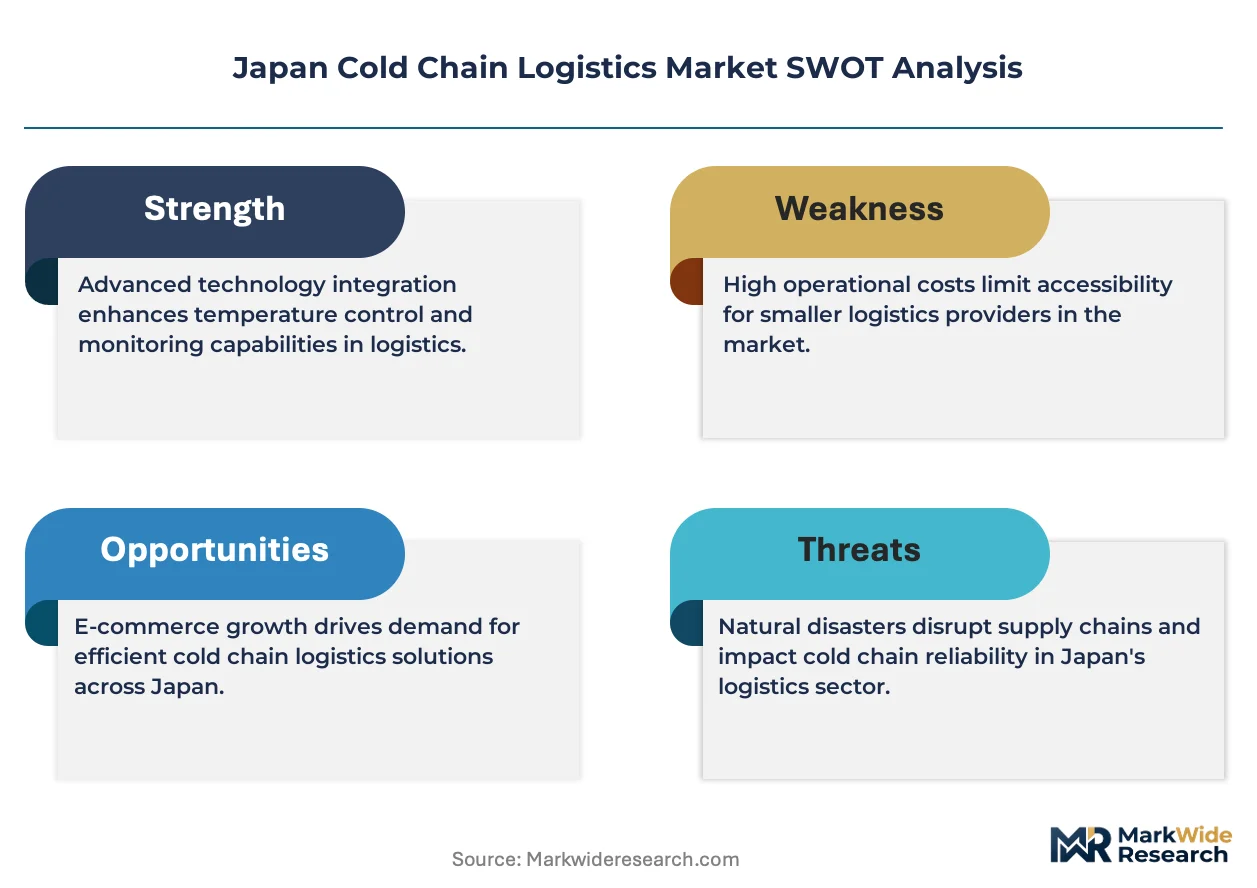
METI enforces energy efficiency benchmarks for commercial refrigeration equipment, directly shaping fleet procurement cycles and facility upgrade timelines. PMDA pharmaceutical storage guidelines mandate continuous temperature documentation, creating compliance-driven demand for validated cold chain infrastructure. JIS standards govern insulation performance and refrigeration unit specifications, establishing baseline product requirements for domestic equipment manufacturers. Stakeholders must monitor evolving refrigerant phase-down schedules and assess capital allocation between facility automation and fleet electrification pathways.
Market Dynamics
METI's refrigerant phase-down mandates are compressing equipment replacement cycles across Japan's cold chain, forcing operators to reallocate capital toward compliant refrigeration systems while pharmaceutical distribution networks expand validated storage capacity.
Growth Catalysts
- Pharmaceutical distribution expansion:Biologics and vaccine storage requirements are pulling investment into certified 2°C to 8°C infrastructure across prefectural medical hubs.
- METI energy efficiency standards:Mandatory performance benchmarks for commercial refrigeration equipment are accelerating fleet turnover and facility modernization timelines.
- IoT sensor deployment:Real-time temperature monitoring telemetry is enabling continuous compliance documentation for PMDA pharmaceutical guidelines.
Market Restraints
- Refrigerant input cost volatility:F-Gas Regulation phase-down schedules are constraining hydrofluorocarbon supply and inflating replacement refrigerant prices.
- Certified facility scarcity:Limited pharmaceutical-grade cold storage availability in secondary prefectures concentrates premium capacity in the Greater Tokyo corridor.
- Electrification capex burden:Battery-electric refrigerated vehicle procurement requires substantial upfront investment against compressed payback periods.
Strategic Opportunities
- Osaka-Kobe port cluster expansion:Underdeveloped temperature-controlled consolidation capacity presents white space for sea-air intermodal services.
- Regenerative medicine logistics:Cell therapy and gene therapy cold chains require ultra-low temperature infrastructure below standard pharmaceutical thresholds.
- Hokkaido agricultural export corridor:Seafood and dairy processors need enhanced pre-cooling and export-grade cold storage to access Asian markets.
Industry Challenges
- Refrigeration technician shortage:Specialized vapor-compression system maintenance skills are scarce as veteran technicians retire without pipeline replacement.
- Legacy telemetry integration:Older warehouse management systems require costly retrofitting to interface with cloud-based temperature monitoring platforms.
- Multi-modal handoff coordination:Port-to-warehouse-to-last-mile temperature continuity demands synchronized scheduling across fragmented carrier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cold Chain Logistics Market |
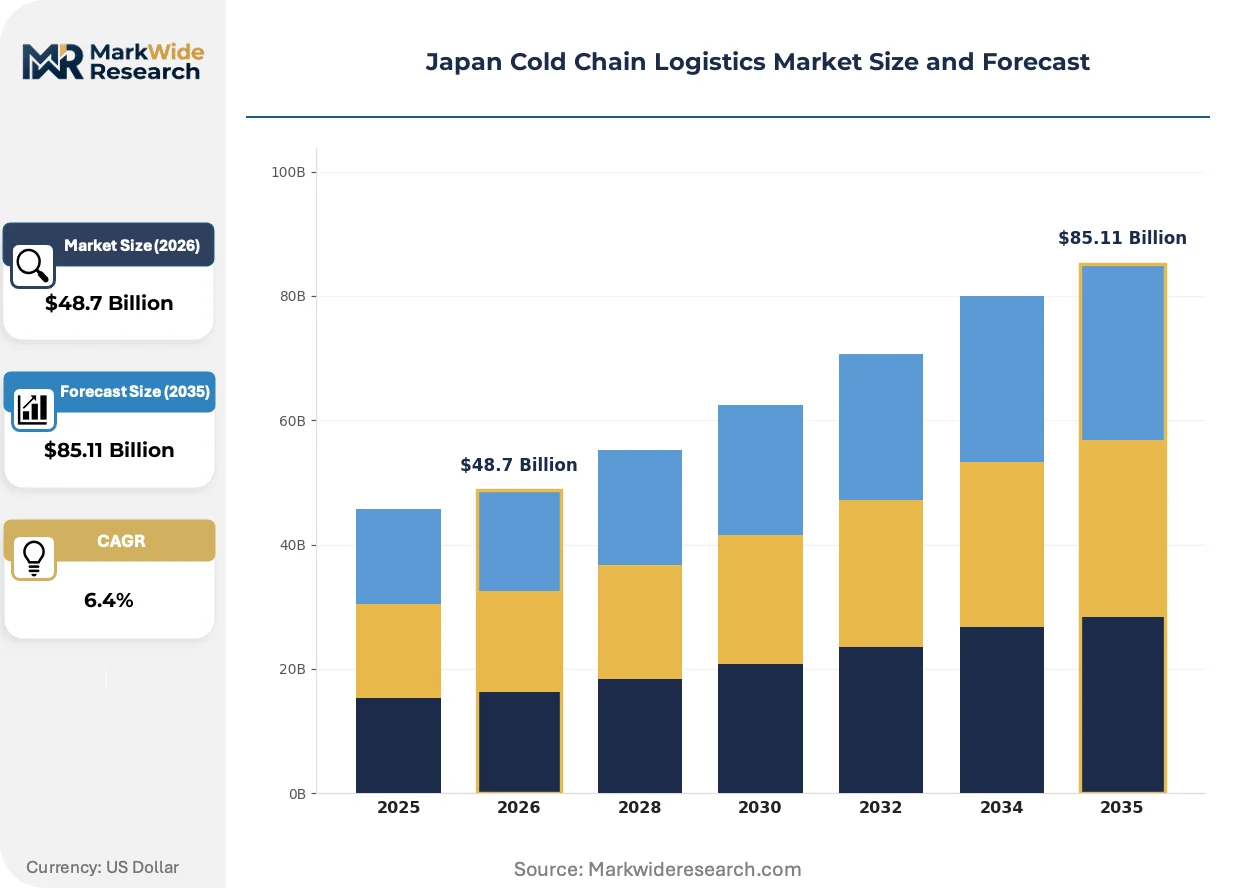
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy Products, Pharmaceuticals Technology: Active Systems, Passive Systems, IoT-Enabled Solutions, Refrigeration Equipment End User: Food Industry, Healthcare Sector, Retail Sector, E-Commerce Delivery Mode: Road Transport, Air Cargo, Sea Freight, Warehousing Solutions |
| Companies Covered | Mitsubishi Logistics, Sagawa Express, Nippon Express, SENKO Co., Ltd., Konoike Transport, Nichirei Logistics Group, Kintetsu World Express, Suzuyo & Co., Yamato Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cold Chain Logistics Market Shifts & Advancements
Digital infrastructure is overtaking mechanical reliability as the primary competitive differentiator in Japan's cold chain, with operators racing to deploy sensor networks and predictive analytics ahead of regulatory documentation requirements.
CO2 transcritical refrigeration systems are overtaking conventional hydrofluorocarbon-based units in large-scale distribution centers. Supermarket chains and third-party logistics providers are adopting these systems at accelerating pace to preempt F-Gas compliance deadlines. This technology is overtaking traditional equipment procurement patterns by embedding energy recovery capabilities that reduce operating expenditure.
PMDA pharmaceutical storage guidelines now mandate continuous temperature documentation with audit-ready data retention. This regulatory shift forces cold storage operators to upgrade telemetry infrastructure and validate electronic record systems. Pharmaceutical distributors face the steepest compliance burden, driving consolidation toward operators with pre-certified facilities.
Consolidation of purchasing power among national pharmacy chains is compressing supplier margins and demanding outcome-based service level agreements. Regional cold storage providers are losing share to integrated logistics platforms offering end-to-end temperature guarantees. This concentration is most visible in Tokyo and Osaka metropolitan zones where hospital group purchasing organizations dominate procurement decisions.
Japan Cold Chain Logistics Market Segmentation
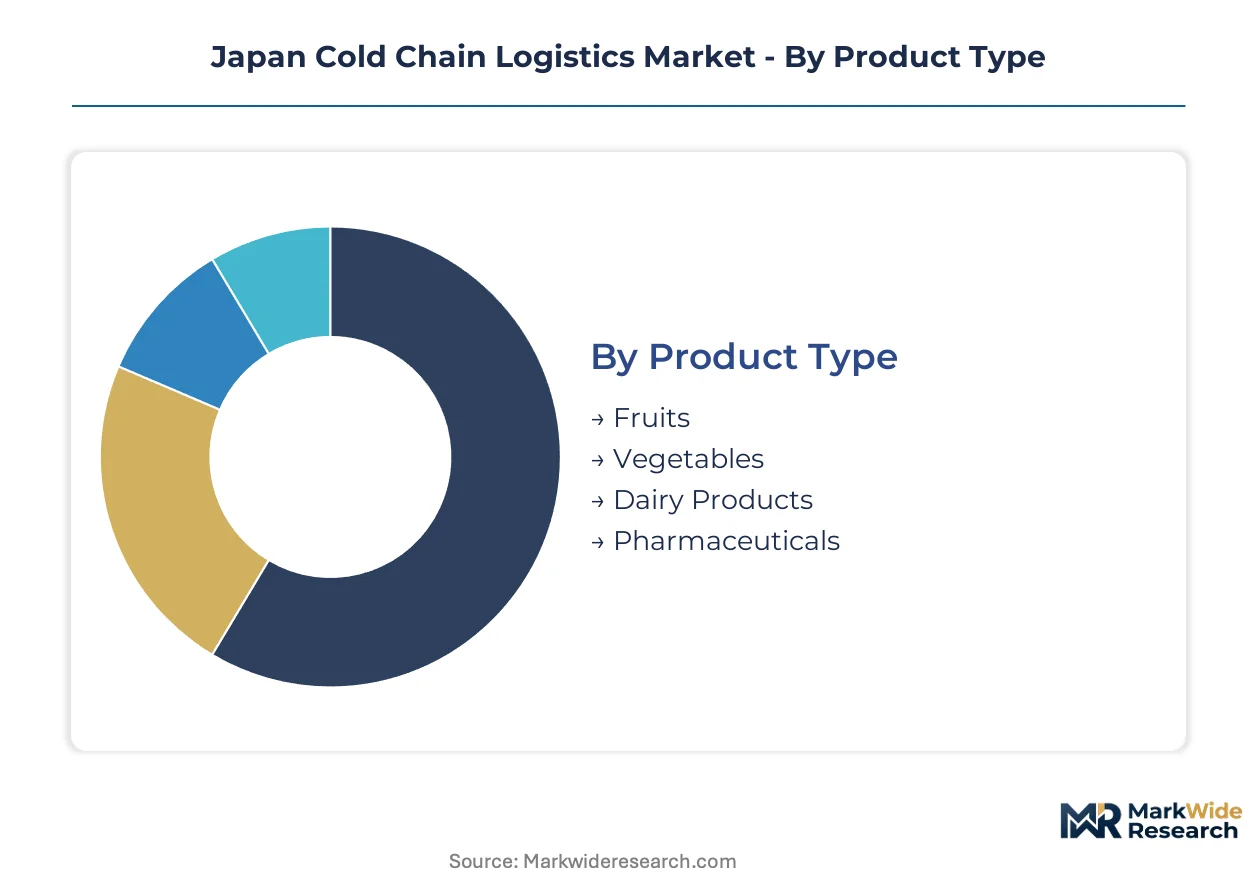
Segmentation in Japan's cold chain logistics market reveals distinct operational requirements across temperature thresholds, regulatory intensity, and infrastructure investment levels. Each category exposes divergent margin structures and capital deployment patterns that shape competitive positioning.
Product Type:
Standardization dominates commodity perishables while pharmaceutical cargo demands validated, certifiable customization.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and cell therapies require continuous 2°C to 8°C monitoring with PMDA-mandated documentation trails. Demand clusters in Greater Tokyo's hospital procurement networks and Osaka's pharmaceutical manufacturing belt, constrained by certified facility scarcity in secondary prefectures.
- Dairy Products:Pasteurized milk, cheese, and ice cream necessitate sub-zero frozen chains alongside chilled distribution for fresh categories. Hokkaido processors drive cold storage expansion near Tomakomai and Kushiro ports for Asian export access.
- Fruits:Premium varieties like Yubari melon and Aomori apples need humidity-controlled pre-cooling and transit.
- Vegetables:Leafy greens and root vegetables utilize standard refrigerated trucking with minimal telemetry.
Leading the category by volume: Fruits and Vegetables combined. Growing fastest: Pharmaceuticals, climbing on biologics distribution expansion.
Technology:
Cost tiers separate legacy mechanical systems from digital-native platforms requiring integration capex.
- IoT-Enabled Solutions:Sensor networks transmit real-time temperature, humidity, and location data to cloud platforms for PMDA compliance documentation. Tokyo-based 3PLs deploy these systems fastest to secure pharmaceutical contracts.
- Refrigeration Equipment:Vapor-compression units, condensers, and evaporators form the mechanical backbone of cold storage facilities and vehicle fleets. METI energy efficiency benchmarks are compressing replacement cycles toward CO2 transcritical systems.
- Active Systems:Powered refrigeration units maintain precise temperature control during transport.
- Passive Systems:Insulated containers with phase-change materials suit short-haul and last-mile delivery.
Refrigeration Equipment anchors current installed base. IoT-Enabled Solutions show steepest expansion trajectory on regulatory documentation mandates.
End User:
Customer type determines service level requirements from basic temperature maintenance to validated chain-of-custody.
- Healthcare Sector:Hospitals, clinics, and pharmaceutical distributors demand end-to-end temperature guarantees with audit-ready records. Consolidation among national pharmacy chains concentrates procurement power in Tokyo and Osaka metropolitan zones.
- E-Commerce:Online grocers and meal-kit services require dense last-mile cold delivery infrastructure with precise arrival windows. Sagawa Express and Yamato Holdings compete on refrigerated same-day coverage in urban corridors.
- Food Industry:Processors and manufacturers utilize bulk cold storage with scheduled distribution rhythms.
- Retail Sector:Supermarket chains operate captive distribution networks or outsource to temperature-controlled 3PLs.
Food Industry generates largest throughput volume. E-Commerce is gaining share fastest on online grocery penetration.
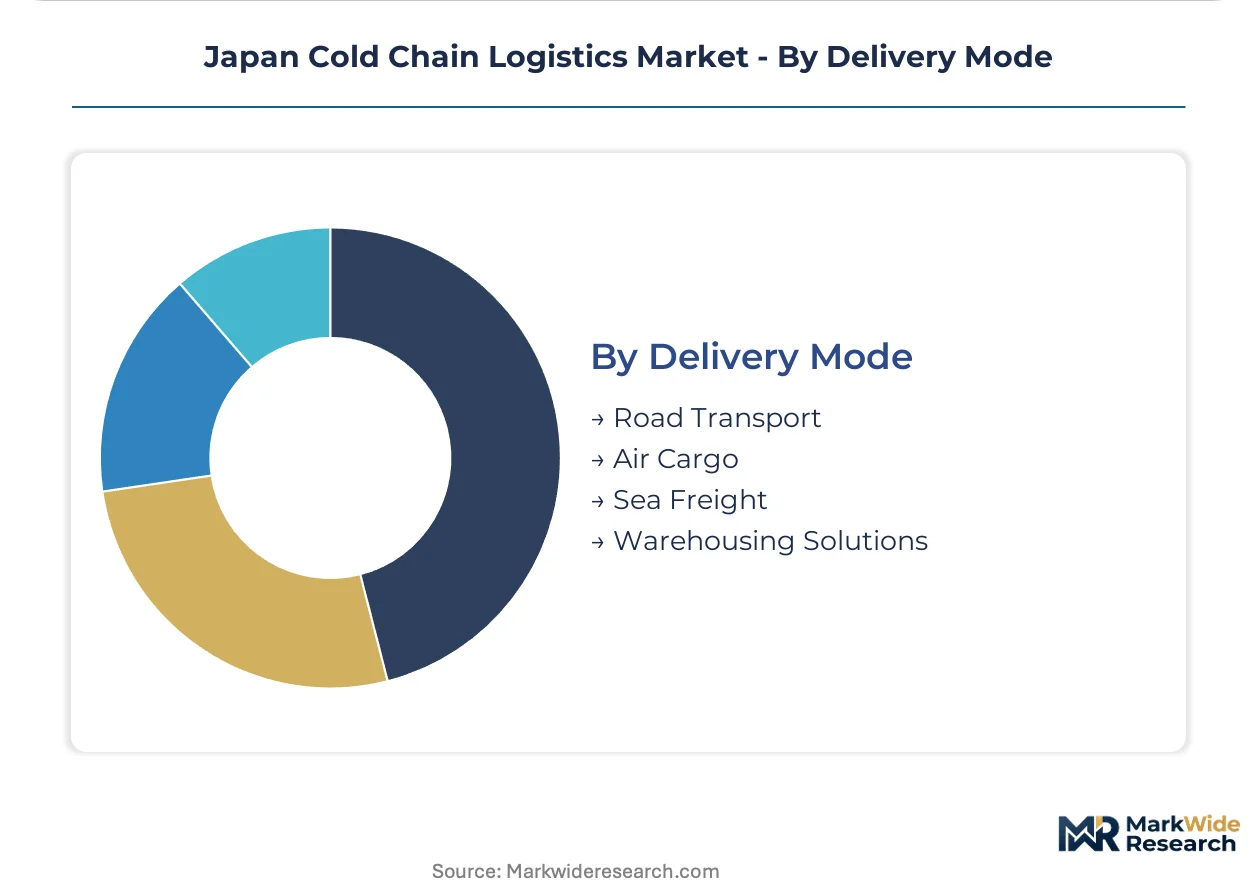
Delivery Mode:
Geography and cargo value dictate modal selection across Japan's archipelago infrastructure.
- Road Transport:Refrigerated trucks and vans execute just-in-time replenishment across Honshu, Shikoku, and Kyushu highway networks. Fleet operators face electrification capex burdens as METI emissions standards tighten.
- Sea Freight:Temperature-controlled container shipping links Hokkaido seafood processors and Kyushu agricultural exporters to Asian markets. Osaka-Kobe port cluster offers underdeveloped consolidation capacity for sea-air intermodal services.
- Air Cargo:High-value pharmaceuticals and fresh produce utilize Narita and Kansai International cold chain facilities.
- Warehousing Solutions:Static cold storage facilities provide inventory buffering and cross-dock consolidation.
Road Transport commands dominant modal share. Sea Freight is expanding most quickly on agricultural export corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Keihin Industrial Zone anchors cold chain concentration through port-linked tax incentives and bonded warehouse status. Prefectural medical procurement networks and METI efficiency mandates reshape infrastructure deployment across Japan's economic corridors.
Kanto/Tokyo
Pharmaceutical distribution networks and e-commerce fulfillment centers drive refrigerated warehouse demand. METI energy efficiency benchmarks accelerate fleet turnover in the Greater Tokyo metropolitan corridor. Narita International Airport cold storage facilities handle high-value pharmaceutical air cargo for hospital group purchasing organizations.
Kansai/Osaka
Seafood processors and pharmaceutical manufacturers pull temperature-controlled consolidation capacity toward the Osaka-Kobe port cluster. PMDA storage guidelines mandate continuous temperature documentation for biologics distribution. Underdeveloped sea-air intermodal infrastructure presents expansion opportunities for temperature-controlled logistics providers.
Chubu/Nagoya
Automotive parts suppliers and food processors utilize just-in-time refrigerated trucking across the Tokai region highway network. JIS insulation standards govern equipment specifications for domestic cold chain infrastructure. Toyota City industrial corridor demands synchronized cold delivery scheduling for precision manufacturing supply chains.
Hokkaido
Seafood and dairy exporters require enhanced pre-cooling infrastructure for Asian market access. Tomakomai and Kushiro ports need expanded export-grade cold storage to handle surging agricultural commodity volumes. Regional processors face capacity constraints meeting international cold chain certification requirements.
Kyushu
Agricultural exporters and semiconductor materials distributors utilize temperature-controlled road and sea freight linkages. Fukuoka metropolitan logistics hubs serve as consolidation points for Asian trade corridors. Limited certified pharmaceutical cold storage concentrates premium capacity in regional medical centers.
Japan Cold Chain Logistics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's cold chain logistics sector. Integrated trading house logistics arms and dedicated temperature-controlled operators split market share along customer complexity lines. Three archetypes dominate: port-centric warehouse networks, pharmaceutical-certified facility operators, and dense last-mile delivery platforms. Consolidation through strategic partnerships and certified facility acquisition accelerates as pharmacy chain purchasing power concentrates.
Within the diversified conglomerate tier, Mitsubishi Logistics exemplifies port-centric consolidation through bonded warehouse networks. Sagawa Express and Nichirei Logistics Group represent contrasting specialization vectors—urban last-mile density versus pharmaceutical-certified infrastructure. These three operators anchor competitive positioning across distinct temperature-controlled service segments.
| Leading Market Players |
|---|
| Mitsubishi Logistics |
| Sagawa Express |
| Nippon Express |
| SENKO Co., Ltd. |
| Konoike Transport |
| Nichirei Logistics Group |
| Kintetsu World Express |
| Suzuyo & Co. |
| Yamato Holdings |
| Others |
Supply & Pricing Matrix
Horizontal consolidation among pharmaceutical-certified warehouse operators anchors both supply positioning and pricing power across Japan's cold chain, as METI refrigerant mandates compress replacement cycles and concentrate premium capacity in the Greater Tokyo corridor.
Pricing Analysis
Short lead-time premiums dominate pharmaceutical cold storage contracts, with certified 2°C to 8°C facilities commanding substantial markups over standard frozen warehousing. Three-tier pricing structure across PMDA-validated, temperature-monitored, and basic refrigerated tiers reflects certification grade and telemetry sophistication. Cost compression in standard frozen warehousing is intensifying because supermarket chains consolidate procurement through national group purchasing organizations. Regional cold storage providers exhibit highest price sensitivity, while biologics distributors accept premium pricing for audit-ready compliance documentation.
Supply Chain Analysis
Refrigerant supply rests on Japanese and Chinese specialty chemical producers, with hydrofluorocarbon phase-down schedules constraining input availability. Insulated vehicle bodies and vapor-compression units draw from domestic equipment manufacturers adhering to JIS standards, while IoT sensor hardware sources from Taiwanese and South Korean electronics suppliers. Single-source vulnerability in certified refrigeration technician labor creates operational risk for facility maintenance. Distribution runs through port-centric warehouse networks consolidating sea-air intermodal cargo before last-mile road transport deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified pharmaceutical cold storage scarcity props pricing across Japan's cold chain, as limited PMDA-validated facility availability concentrates premium capacity in metropolitan medical procurement hubs.
For Market Incumbents: Anticipate METI refrigerant phase-down deadlines by accelerating CO2 transcritical system deployment ahead of compliance mandates. Consolidate certified facility portfolios through targeted acquisitions in underserved prefectural medical markets to defend against integrated logistics platforms encroaching on pharmaceutical contracts. For New Entrants and Emerging Players: Digital-channel routes through IoT-enabled temperature monitoring platforms offer the most penetrable entry vector, bypassing capital-intensive warehouse construction. Target Osaka-Kobe sea-air intermodal consolidation services, where underdeveloped temperature-controlled infrastructure meets surging pharmaceutical export demand. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated trading house logistics arms seeking pharmaceutical certification capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity storage volume. Watch METI refrigerant quota announcements as the critical inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Investment | Validates cold storage facilities for biologics distribution contracts with hospital purchasing organizations. |
| CO2 Transcritical System Deployment | Preempts F-Gas Regulation compliance deadlines while reducing energy operating expenditure. |
| IoT Sensor Network Integration | Enables real-time temperature documentation required by pharmaceutical storage guidelines. |
| Osaka-Kobe Port Expansion | Captures sea-air intermodal cargo currently underserved by temperature-controlled consolidation capacity. |
| Certified Technician Pipeline Development | Addresses specialized vapor-compression maintenance skills scarcity threatening facility uptime. |
Research Methodology
Independent corroboration across cold storage facility operators, pharmaceutical distribution executives, and METI regulatory officials underwrites the qualitative findings. Primary interviews with warehouse operations managers, fleet procurement directors, PMDA compliance officers, and hospital supply chain managers combined with secondary validation from customs trade data, refrigerated transport registration databases, and pharmaceutical logistics SEC filings. Bottom-up facility capacity tallies and top-down pharmaceutical distribution volume estimates provided triangulation anchors.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns and refrigerant phase-down implementation timelines. Segmentation modeling spanned temperature thresholds, certification tiers, delivery modes, and regional medical procurement clusters across the analysis window. CAGRs derived from equipment turnover velocity, pharmaceutical distribution expansion rates, and energy efficiency investment cycles.
Inputs from refrigerated fleet operators and pharmaceutical warehouse providers were available through the study window; gaps in prefectural-level certified facility inventory data introduce uncertainty bands around secondary market estimates. Forecasts reflect documented assumptions regarding METI enforcement timelines and PMDA documentation requirement adoption curves. A small set of regulatory trigger announcements warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Perishable Goods Transportation Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
US Tolling Market