
 Cable Car and Ropeways Market | 2026-2036
Cable Car and Ropeways Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Car and Ropeways Market Intelligence
Steel cable replacement with synthetic fiber composites is realigning product economics across the industry. Doppelmayr/Garaventa Group leverages captive R&D centers in Austria to dominate premium automated installations. POMA Group anchors its position through manufacturing scale in France, competing on funicular systems for steep-grade urban corridors. Nippon Cable Co., Ltd. specializes in earthquake-resistant grip technologies, occupying a defensible niche across Japan's volcanic terrain.
Cable car and ropeway systems are elevated transport mechanisms utilizing continuous haul ropes, grip assemblies, and tensioned support structures to move passengers or freight across variable topography, typically operating at line speeds between 5 and 12 meters per second depending on system classification. Their primary purpose spans recreational access, urban congestion relief, and industrial material handling in terrain where conventional road or rail infrastructure proves economically prohibitive. Double cable configurations command the highest capital allocation in ski resort renewals, while synthetic fiber materials represent the fastest-expanding segment as operators pursue reduced dead load and extended fatigue life. Urban transport end-use applications are attracting new margin pools as municipalities integrate ropeways into multimodal transit networks.
The EU F-Gas Regulation and CE marking directives constrain refrigerant choices and electrical safety certifications for European installations, while Japan's METI enforces seismic performance standards that shape structural design requirements. Switzerland's Federal Office of Transport mandates periodic non-destructive testing protocols that sustain aftermarket service demand across aging alpine infrastructure. Stakeholders must monitor how automated control technology convergence with hybrid drive systems reshapes operator skill requirements and maintenance contract structures.
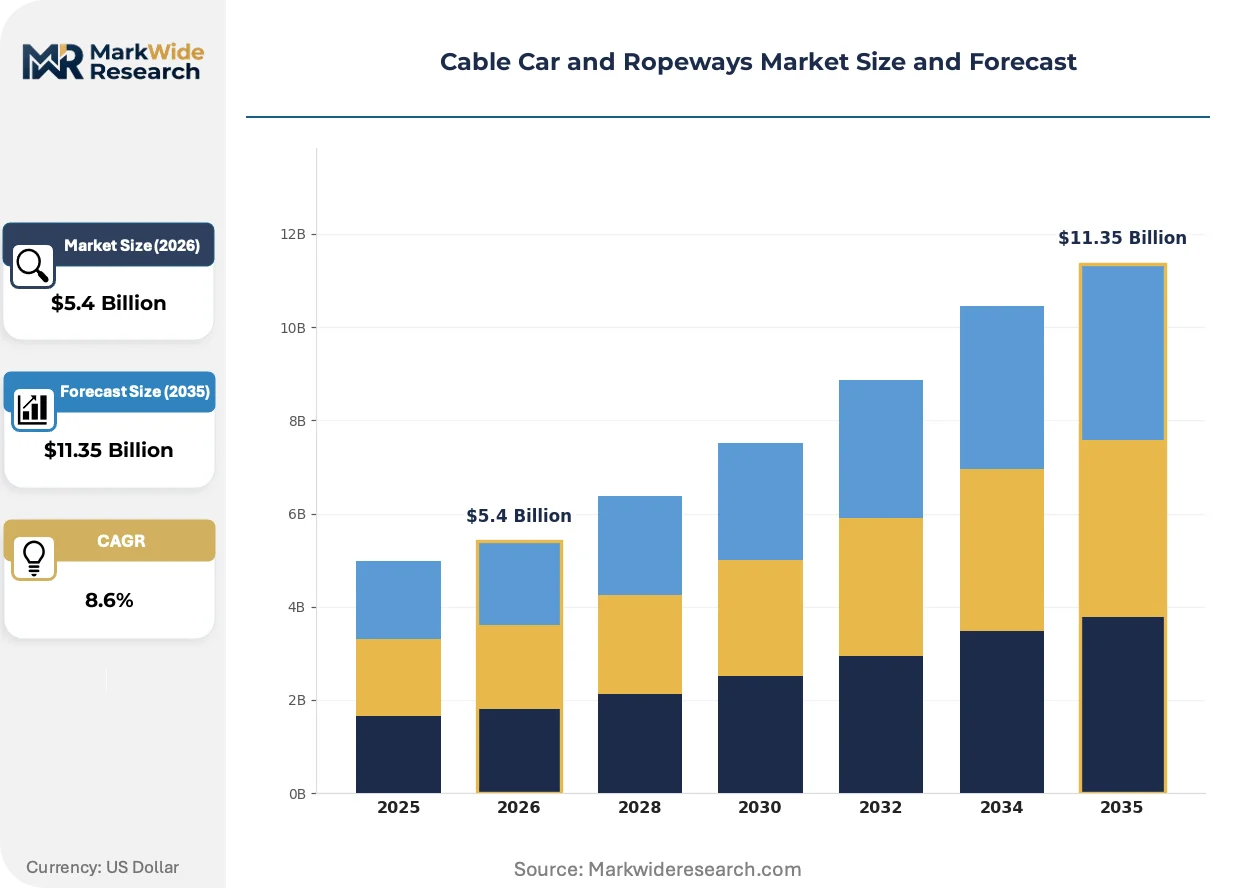
Market Dynamics
Synthetic fiber composite cables are compressing replacement cycles across alpine infrastructure while automated grip systems reconfigure operator labor models. The EU F-Gas Regulation accelerates electric drive adoption, forcing capital reallocation toward electrified haul systems.
Growth Catalysts
- Automated grip technology:Ski resort operators in Switzerland deploy sensor-integrated clamping mechanisms that reduce manual intervention and extend operating hours into marginal weather windows.
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon refrigerants pushes manufacturers toward closed-loop electric drive architectures with lower maintenance overhead.
- Urban congestion corridors:Municipal transit authorities in France and Germany integrate ropeways into multimodal networks where tunneling costs exceed elevated system economics.
Market Restraints
- Steel cable price volatility:Galvanized wire rope costs fluctuate with zinc commodity markets, compressing margins on legacy replacement contracts.
- Austrian supply concentration:Premium automated installation expertise clusters around captive R&D centers in Vorarlberg, creating bottleneck risk for complex projects.
- Seismic certification complexity:Japan's METI structural standards require site-specific engineering that extends deployment timelines for volcanic terrain installations.
Strategic Opportunities
- Indian Himalayan tourism:Underpenetrated mountain corridors in Himachal Pradesh and Uttarakhand present greenfield installation potential as domestic ski infrastructure develops.
- Hybrid-electric convergence:Battery-buffered regenerative drives paired with photovoltaic tension stations enable off-grid operation in remote industrial material handling.
- Swiss non-destructive testing mandates:Federal Office of Transport inspection protocols sustain aftermarket service contracts across aging 1980s infrastructure.
Industry Challenges
- Mechatronics skill scarcity:Automated control systems require technicians trained across mechanical, electrical, and software domains, a combination rarely found in legacy ropeway maintenance workforces.
- CE marking timeline compression:Electrical safety certification for novel drive architectures extends pre-revenue periods, straining development budgets for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Car and Ropeways Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Single Cable, Double Cable, Funicular, Aerial Tramway Material: Steel, Aluminum, Composite, Synthetic Fiber End User: Tourism, Urban Transport, Cargo Transport, Ski Resorts Technology: Automated Control, Hybrid Systems, Electric, Hydraulic |
| Companies Covered | Bartholet Maschinenbau AG, Damodar Ropeways & Infra Ltd., Doppelmayr/Garaventa Group, Vergokan, MND Group, Leitner Ropeways, Nippon Cable Co., Ltd., STM Teleferik, POMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Car and Ropeways Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory energy mandates are converging to transform system architecture. Three developments are compressing traditional design paradigms and opening new application vectors.
Carbon fiber-reinforced polymer haul ropes are unifying strength-to-weight performance with corrosion immunity. Alpine operators in Switzerland and Austria adopt these composites for span-critical installations where dead load reduction permits longer unsupported crossings. The technology is unifying previously separate engineering disciplines—structural, mechanical, and aerodynamic—into integrated cable system design.
The EU F-Gas Regulation's refrigerant phase-down is forcing heat management redesigns across European installations. Electric drive motors replace hydraulic cooling systems dependent on regulated gases. French and German manufacturers accelerate permanent magnet motor development to maintain CE marking compliance without thermal management complexity.
Service contract unbundling is fragmenting traditional procurement relationships. Ski resort operators in Japan separate grip assembly maintenance from full-system overhaul agreements, creating spot-market competition for specialized technical labor. This pattern concentrates in aging infrastructure corridors where component-level expertise commands premium pricing over bundled vendor relationships.
Cable Car and Ropeways Market Segmentation
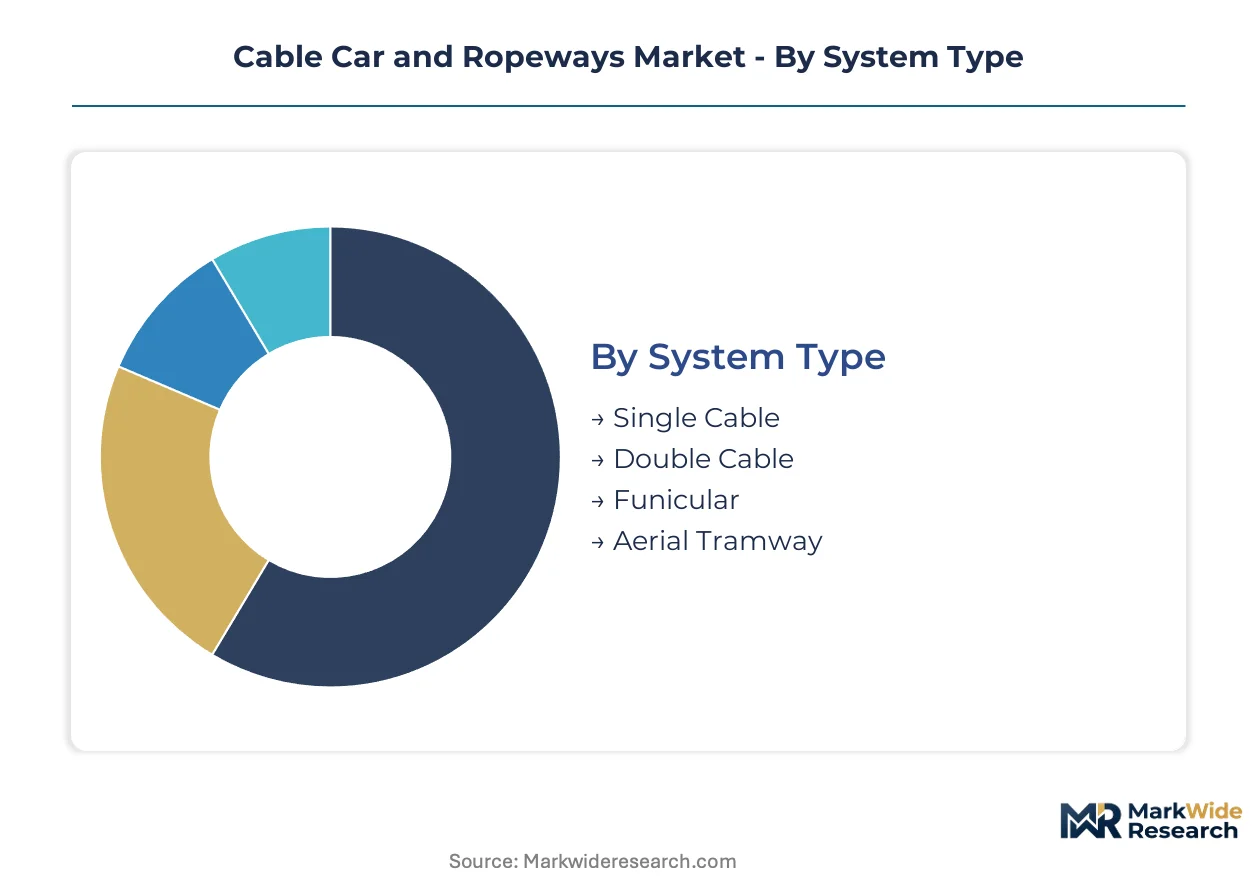
Cable car and ropeway systems fragment across four distinct dimensions that govern capital allocation, operational complexity, and regulatory exposure. System architecture and material composition determine upfront investment and lifecycle economics, while end-use application and drive technology shape revenue stability and compliance burden.
System Type:
Double cable configurations command premium capital allocation in alpine renewals, while single cable systems dominate volume deployments across cost-sensitive corridors.
- Double Cable:Parallel haul and track rope configurations support heavier cabins across extreme spans. Swiss and Austrian ski operators specify these systems for terrain where unsupported crossings exceed 800 meters. Automated grip mechanisms reduce labor intensity at high-altitude terminals.
- Single Cable:Continuous loop systems with detachable grips serve lower-capacity routes. French urban transit authorities deploy these for commuter corridors where tunneling economics fail. The EU F-Gas Regulation accelerates electric drive retrofits on legacy installations.
- Funicular:Counterbalanced rail-guided systems operate on steep fixed gradients. Italian lake district municipalities favor these for historic center access where aerial clearance is restricted.
- Aerial Tramway:Fixed-grip shuttles with bidirectional cabin pairs cross wide valleys. Japanese volcanic terrain installations require METI seismic certification that extends engineering timelines.
Mature deployment sits with Double Cable. Newer deployment is concentrated in Single Cable.
Material:
Steel maintains installed base dominance while synthetic fiber composites capture replacement cycle momentum across fatigue-critical applications.
- Steel:Galvanized wire rope with zinc-aluminum coating delivers proven fatigue resistance. Alpine infrastructure from the 1980s relies on these materials, sustaining aftermarket inspection demand under Swiss Federal Office of Transport mandates.
- Synthetic Fiber:Ultra-high molecular weight polyethylene and aramid composites reduce dead load by 60-80% versus steel. Austrian manufacturers specify these for span-critical installations where aerodynamic stability matters. The technology is climbing the fastest as operators pursue extended replacement intervals.
- Composite:Carbon fiber-reinforced polymer hybrid ropes unify corrosion immunity with structural performance. German engineering firms prototype these for offshore wind service applications.
- Aluminum:Lightweight structural elements in tower fabrication reduce transport costs to remote sites. Norwegian fjord-crossing projects specify aluminum alloy pylons for helicopter-assisted assembly.
Steel dominates replacement contracting. Synthetic Fiber leads new specification.
End User:
Ski resort operators drive premium system renewals while urban transit authorities expand the addressable market through congestion pricing corridors.
- Ski Resorts:Seasonal demand concentration requires weather-resilient automated systems. Swiss operators invest in sensor-integrated grip technology to extend operating hours into marginal conditions.
- Urban Transport:Municipal integration into multimodal networks creates new margin pools. French cities deploy ropeways across river corridors where bridge construction is politically constrained.
- Tourism:Heritage site access and scenic routes generate stable off-peak revenue. Indian Himalayan states in Himachal Pradesh and Uttarakhand present greenfield installation potential.
- Cargo Transport:Industrial material handling across mining and forestry terrain operates on lower margins. Battery-buffered regenerative drives enable off-grid deployment in remote extraction sites.
Revenue concentration sits with Ski Resorts. Volume expansion is concentrated in Urban Transport.
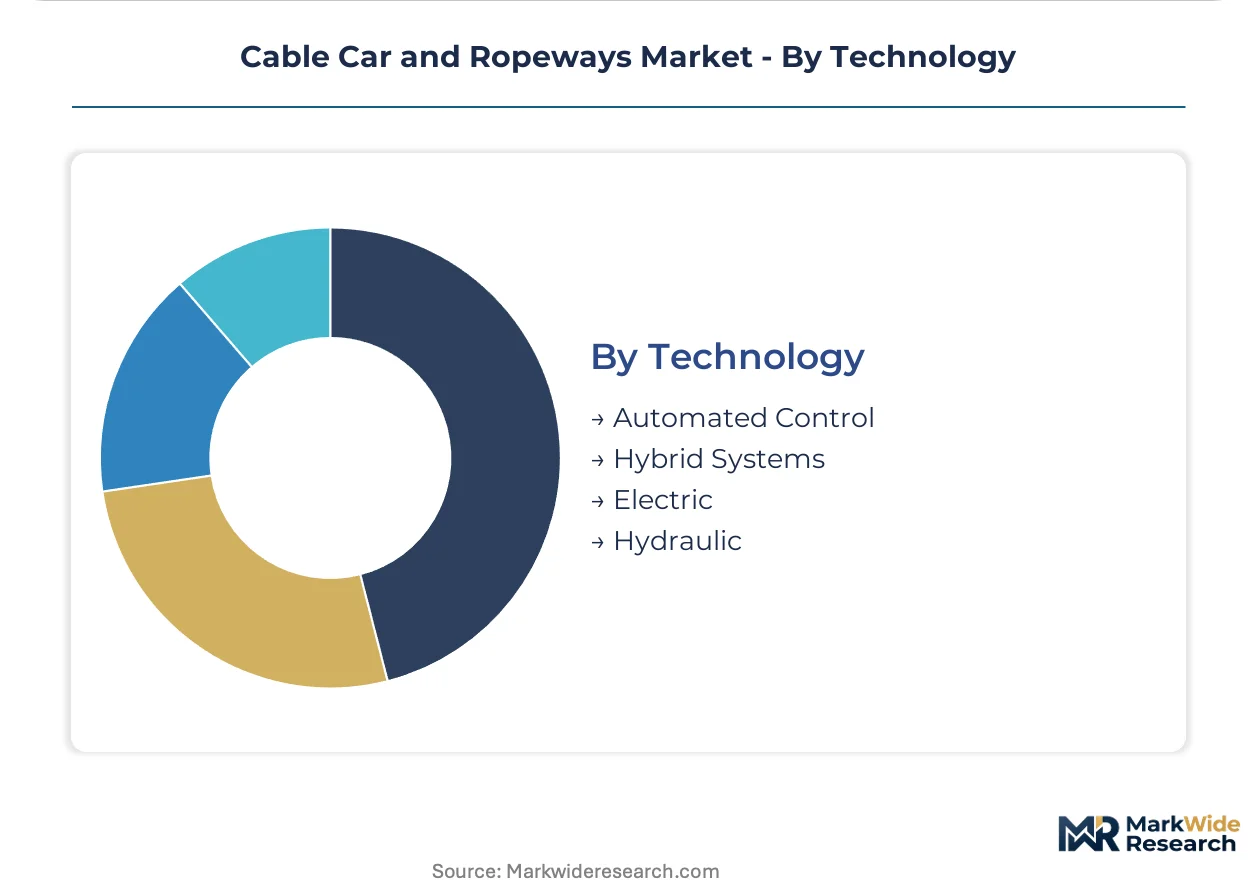
Technology:
Electric drive architectures displace hydraulic systems as the EU F-Gas Regulation phases down refrigerant-dependent cooling circuits.
- Electric:Permanent magnet synchronous motors eliminate hydraulic thermal management. German and French manufacturers accelerate development to maintain CE marking compliance without regulated gases.
- Automated Control:Sensor-integrated clamping and tension monitoring reduce manual intervention. Japanese operators unbundle grip assembly maintenance from full-system contracts, creating spot-market competition for specialized technicians.
- Hybrid Systems:Battery-buffered regenerative braking paired with photovoltaic tension stations supports off-grid operation. Remote industrial corridors in Scandinavia pilot these configurations.
- Hydraulic:Legacy drive systems dependent on hydrofluorocarbon refrigerants face accelerated obsolescence. Replacement cycles compress as operators anticipate regulatory enforcement.
Installed base sits with Hydraulic. Specification momentum is concentrated in Electric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's mountain tourism corridors concentrate premium automated installations, while India's Himalayan states attract greenfield investment under special tourism zone incentives. The EU F-Gas Regulation and Japan's METI seismic standards reshape capital deployment across three continents.
Switzerland
Alpine ski resort operators drive fleet replacements with sensor-integrated grip systems. The Federal Office of Transport mandates periodic non-destructive testing protocols that sustain aftermarket service demand. Zermatt and St. Moritz clusters host concentrated R&D partnerships for automated clamping mechanisms.
France
Municipal transit authorities integrate ropeways into multimodal networks across river corridors. The EU F-Gas Regulation accelerates electric drive retrofits on legacy hydraulic installations. Grenoble and Lyon urban clusters deploy funicular systems for steep-grade historic center access.
Japan
Volcanic terrain installations require METI seismic certification that extends engineering timelines. Nippon Cable Co., Ltd. anchors domestic supply through earthquake-resistant grip technologies. Hakone and Nikko tourism corridors concentrate specialized maintenance expertise.
India
Domestic ski infrastructure development in Himachal Pradesh and Uttarakhand presents greenfield installation potential. State tourism boards offer capital subsidies under Himalayan circuit development programs. Manali and Auli clusters attract preliminary feasibility studies for urban congestion relief projects.
Austria
Premium automated installation expertise clusters around captive R&D centers in Vorarlberg. CE marking directives constrain electrical safety certification timelines for novel drive architectures. Innsbruck and Salzburg alpine zones concentrate double cable system specifications for extreme span crossings.
Cable Car and Ropeways Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated system architects commanding premium positioning in automated alpine installations while regional fabricators compete on urban transit retrofit economics. The vendor base organizes around three strategic archetypes: European engineering houses with captive R&D infrastructure, Asian specialists in terrain-specific adaptations, and emerging-market contractors serving cost-sensitive corridor development. Consolidation pressure concentrates in the premium tier where automated grip technology requires unified mechanical-electrical-software capabilities. Competitive moves center on backward integration into synthetic fiber composite supply and geographic licensing partnerships for seismic-certified system architectures.
Among European engineering houses, Doppelmayr/Garaventa Group and POMA Group exemplify divergent scale strategies, with the former anchoring premium automated installations through Austrian R&D concentration and the latter competing on funicular manufacturing scale for urban corridors. Nippon Cable Co., Ltd. occupies a defensible position within the terrain-specialist archetype, representing Japanese seismic engineering adaptation. These three entities collectively illustrate how regulatory geography—EU F-Gas compliance, CE marking, and METI certification—shapes competitive boundary definition more than raw manufacturing capacity.
| Leading Market Players |
|---|
| Bartholet Maschinenbau AG |
| Damodar Ropeways & Infra Ltd. |
| Doppelmayr/Garaventa Group |
| Vergokan |
| MND Group |
| Leitner Ropeways |
| Nippon Cable Co., Ltd. |
| STM Teleferik |
| POMA Group |
| Others |
Cost & Logistics Intelligence
Ski resort operator procurement of automated grip systems with EU F-Gas-compliant electric drives is forcing supply-side reconfiguration toward Austrian R&D centers and French manufacturing scale, compressing margins on legacy hydraulic retrofits while elevating premiums for seismic-certified Japanese engineering.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent alpine installations from scheduled urban corridor deployments, with Swiss Federal Office of Transport-mandated inspection contracts commanding premium rates for certified technicians. Three-tier pricing structure across premium automated, standard electric, and economy hydraulic tiers reflects certification grade and after-sales bundling intensity. Cost compression in economy hydraulic tiers is intensifying because of refrigerant phase-down compliance deadlines. Urban transit authorities in France exhibit highest price sensitivity due to municipal budget cycles, while Japanese volcanic terrain operators show lowest sensitivity given METI certification scarcity.
Supply Chain Analysis
India's domestic-content mandates under Himalayan circuit development programs are reshaping sourcing toward local tower fabrication partnerships for greenfield installations in Himachal Pradesh and Uttarakhand. Supply concentrates in Austria for premium automated systems, France for funicular manufacturing scale, and Japan for seismic-resistant grip technologies. Raw material dependencies encompass galvanized steel wire rope, ultra-high molecular weight polyethylene composites, and permanent magnet motor components. Single-source vulnerability clusters around Austrian captive R&D centers for sensor-integrated clamping mechanisms. Distribution runs through direct OEM contracting for alpine renewals and municipal procurement frameworks for urban transit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable car and ropeway market sits in a technology-transition phase as electric drive architectures displace hydraulic systems dependent on phased-down refrigerants.
For Market Incumbents: To counter mechatronics skill scarcity threatening automated system deployment timelines, Doppelmayr/Garaventa Group and POMA Group should deepen backward integration into synthetic fiber composite supply chains while establishing captive training academies for cross-domain technician certification. CE marking timeline compression for novel drive architectures demands pre-emptive regulatory engagement to defend installation contract win rates. For New Entrants and Emerging Players: Enter via Indian Himalayan tourism corridors where state capital subsidies under special tourism zone incentives reduce upfront barrier to greenfield installation feasibility. Target cargo transport applications in remote Scandinavian industrial sites where battery-buffered regenerative drives enable off-grid value propositions absent from incumbent portfolios. Partner with regional helicopter logistics operators for aluminum pylon assembly in Norwegian fjord-crossing terrain. For Investors and Strategic Acquirers: The window for entry favors terrain-specialist engineering firms with METI seismic certification or hybrid-electric system prototypes ahead of EU F-Gas enforcement acceleration. Long-term viability hinges on regulatory geography capture rather than manufacturing scale alone. Monitor Swiss Federal Office of Transport inspection contract unbundling patterns as signal for aftermarket service margin fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Supply | Austrian manufacturers secure captive UHMWPE composite sources for span-critical alpine installations. |
| Electric Drive Architecture Transition | French and German OEMs maintain CE marking compliance through permanent magnet motor development. |
| Seismic Certification Partnership | Japanese engineering adaptation opens volcanic terrain corridors under METI structural standards. |
| Urban Transit Corridor Integration | Municipal ropeway deployment across French river corridors bypasses bridge construction politics. |
| Aftermarket Service Unbundling | Component-level maintenance contracts in Japan concentrate specialized technical labor premiums. |
Research Approach
Independent corroboration across ski resort operator procurement directors, municipal transit authority engineers, and alpine infrastructure maintenance heads underwrites the qualitative findings, validated against EU F-Gas regulatory filings, Swiss Federal Office of Transport inspection protocols, and Japanese METI seismic certification databases. Bottom-up installation contract analysis triangulates with top-down regional tourism infrastructure investment tracking.
Comparable-period anchoring to alpine fleet replacement cycles and urban congestion pricing adoption timelines structures the projection horizon across system type, material composition, end-use application, and drive technology segmentation dimensions. CAGRs derive from unit economics modeling of electric versus hydraulic drive lifecycle costs, incorporating synthetic fiber composite penetration curves and automated control adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity zinc price volatility for steel cable inputs and regulatory enforcement timing for refrigerant-dependent hydraulic obsolescence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Perishable Goods Transportation Market