
 United Kingdom Road Freight Transport Market | 2026-2036
United Kingdom Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Road Freight Transport Market Analytics
The UK net-zero HGV transition programme is realigning capital allocation across the sector. Culina Group leverages its temperature-controlled network to sustain refrigerated market share in food logistics. Turners (Soham) Ltd. anchors its position through bulk agricultural and aggregate haulage across East Anglia. Wincanton PLC differentiates via integrated warehousing and dedicated contract logistics for retail clients.
United Kingdom road freight transport encompasses the commercial movement of goods by heavy goods vehicles on public road networks, typically operating at gross vehicle weights from 3.5 tonnes to 44 tonnes with diesel, hybrid, or emerging battery-electric powertrains. The sector functions as the dominant domestic logistics mode, handling manufactured goods, raw materials, and perishable commodities between production sites, distribution centres, and end consumers. Full truckload services dominate volume throughput on major trunk routes, while less than truckload operations capture fragmented SME demand with higher yield per pallet. Reefer trucks command premium positioning within the vehicle type matrix due to pharmaceutical and fresh food cold-chain requirements. The above 15 tons load capacity bracket concentrates long-haul efficiency gains, though urban access restrictions are compressing its growth trajectory in metropolitan zones.
The Driver and Vehicle Standards Agency enforces operator licensing and tachograph compliance, directly constraining fleet utilisation rates and driver availability. The Department for Transport's Future of Freight strategy and Vehicle Excise Duty reforms for zero-emission trucks are restructuring total cost of ownership calculations for procurement teams. The Health and Safety Executive governs load securing and warehouse interface protocols, shaping liability frameworks across the delivery model spectrum. Stakeholders must monitor the interplay between charging infrastructure deployment pace and battery-electric truck range capabilities before committing to fleet replacement cycles.
Market Dynamics
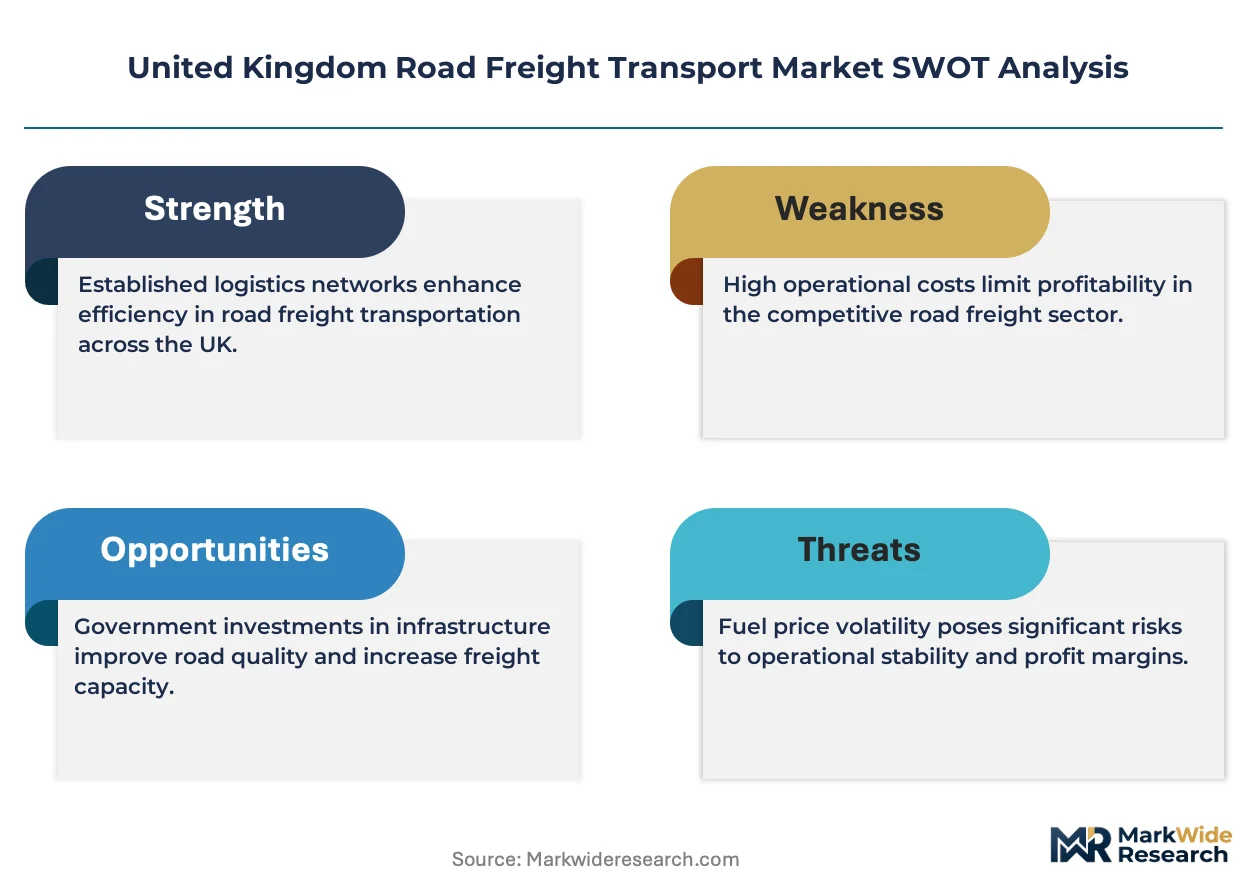
The Department for Transport's zero-emission HGV mandate is compressing diesel fleet residual values while forcing premature replacement cycles across England's logistics corridors. Capital allocation now hinges on charging infrastructure deployment pace versus battery-electric range capabilities.
Growth Catalysts
- E-commerce fulfillment density:Dedicated freight demand concentrates around the East Midlands Gateway and Birmingham logistics cluster as online retail penetration deepens last-mile requirements.
- Vehicle Excise Duty reform:Zero-emission truck incentives under the Department for Transport's decarbonisation strategy are restructuring total cost of ownership calculations for procurement teams.
- Reefer premium positioning:Pharmaceutical and fresh food cold-chain requirements command sustained yield premiums across temperature-controlled vehicle categories.
Market Restraints
- Battery-electric range limitation:Current lithium-ion energy density constrains above-15-ton long-haul operations beyond 300-kilometer radii from charging depots.
- Driver availability compression:DVSA operator licensing and tachograph compliance regimes directly constrain fleet utilisation rates across the sector.
- Charging infrastructure lag:Grid connection queues and substation upgrade timelines delay depot electrification for multi-vehicle fleets.
Strategic Opportunities
- Midlands hub specialisation:The East Midlands Gateway and surrounding distribution corridors offer consolidation potential for regional less-than-truckload networks.
- Integrated warehousing convergence:Dedicated contract logistics combined with captive transport assets are displacing pure-play haulage relationships in retail verticals.
- CSRD-aligned fleet reporting:Corporate sustainability reporting requirements create service differentiation for operators with verified emissions transparency.
Industry Challenges
- Tachograph compliance complexity:DVSA enforcement of driver hours regulations demands real-time telematics integration with legacy fleet management systems.
- Load securing certification:Health and Safety Executive protocols govern warehouse interface protocols, shaping liability frameworks across delivery models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Road Freight Transport Market |
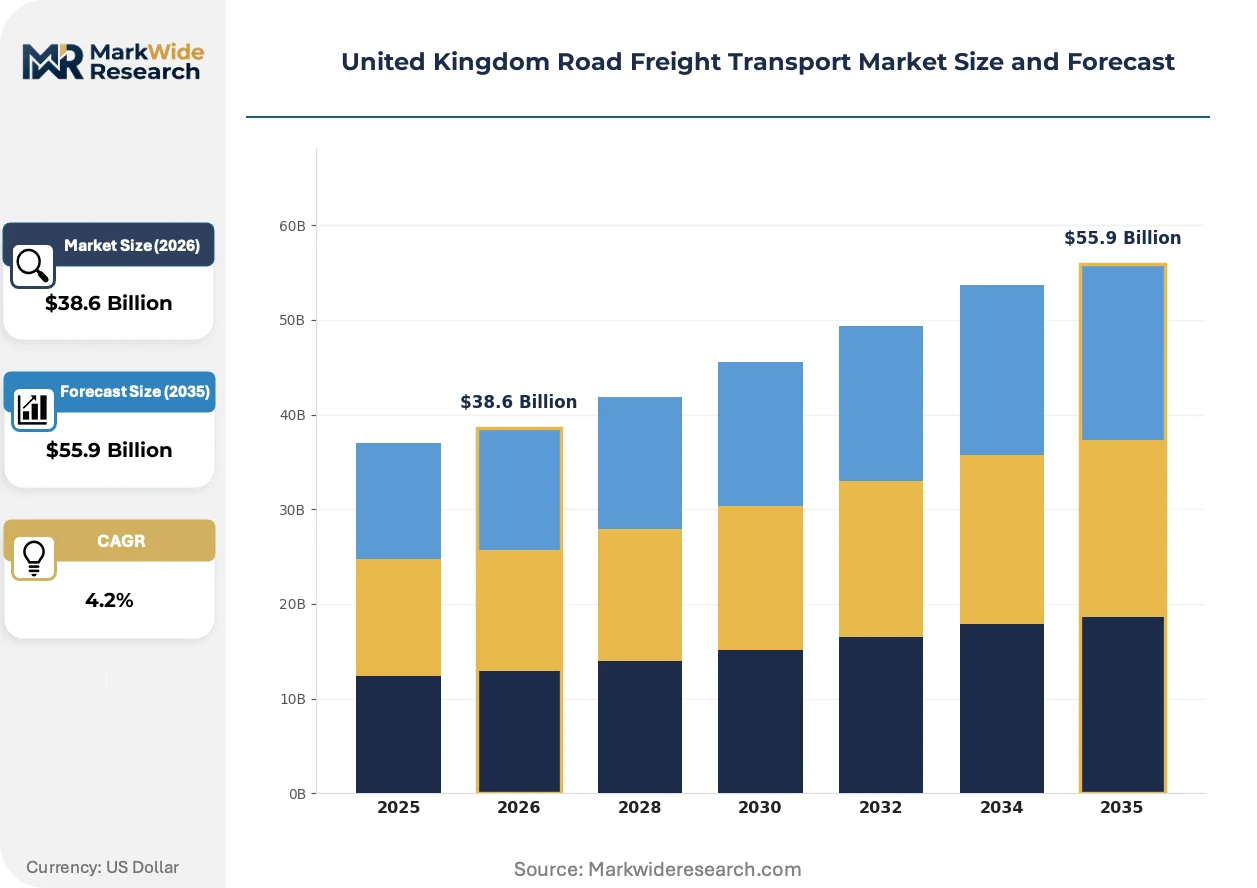
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Dedicated Freight, Expedited Transport Vehicle Type: Reefer Trucks, Flatbed Trucks, Tanker Trucks, Box Trucks Load Capacity: Below 3 Tons, 3-7 Tons, 7-15 Tons, Above 15 Tons Delivery Model: Door-to-Door, Distribution Center, Cross-Docking, Hub-and-Spoke |
| Companies Covered | Culina Group, Turners (Soham) Ltd., Wincanton PLC, DSV A/S, DHL Group, Gregory Distribution Ltd., DACHSER, Howard Tenens, Kinaxia Logistics Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Road Freight Transport Market Evolving Landscape
Telematics and predictive maintenance systems are compressing vehicle downtime while reshaping how operators monetise fleet data. Three converging developments define this transition.
Battery-electric drivetrains is consolidating around 350-450 kWh pack configurations for regional distribution duty cycles. Food retailers and pharmaceutical distributors are piloting refrigerated electric units despite payload trade-offs. This consolidation is compressing diesel residual values and accelerating defleeting decisions among mid-size operators.
DVSA enforcement protocols now mandate remote tachograph data access for roadside compliance checks. The Driver and Vehicle Standards Agency's digital-first inspection regime is forcing telematics upgrades across pre-2019 vehicle parc. Above-15-ton fleets operating cross-border into Scotland and Wales face harmonised enforcement intensity.
Shippers now unbundle transport from warehousing contracts, awarding dedicated freight lanes through mini-bids rather than multi-year logistics partnerships. This disintermediation concentrates volume with asset-backed operators possessing integrated yard management capabilities. FMCG verticals in England's Midlands corridor exhibit the most pronounced procurement model fragmentation.
United Kingdom Road Freight Transport Market Segmentation

Service configuration dictates fleet investment cycles and driver utilisation economics across England's logistics corridors. Vehicle specification and load capacity choices determine access to premium freight lanes and regulatory compliance burdens.
Service Type:
Shipper procurement preferences separate high-volume contract relationships from fragmented spot-market transactions.
- Full Truckload:Single-origin shipments occupy entire vehicle capacity on dedicated routes between manufacturing sites and distribution centres. Major retail consolidation flows through the East Midlands Gateway corridor, where FMCG shippers prioritise load security and transit time certainty over per-pallet economics.
- Less Than Truckload:Multi-consignor cargo consolidation demands sophisticated hub-and-spoke terminal networks with precise sortation capabilities. SME manufacturing clusters across the West Midlands generate fragmented demand that yields higher revenue per pallet kilometre than bulk movements.
- Dedicated Freight:Captive fleet arrangements serve pharmaceutical and automotive verticals requiring temperature integrity or just-in-sequence delivery.
- Expedited Transport:Time-critical shipments command premium positioning for aerospace components and medical supplies.
Volume sits with Full Truckload; growth tilts toward Dedicated Freight.
Vehicle Type:
Thermal management capabilities and load security specifications create tiered procurement economics for fleet operators.
- Reefer Trucks:Insulated cargo compartments with integrated refrigeration units maintain temperature bands between -25°C and +25°C for pharmaceutical and fresh food chains. Cold-chain compliance requirements in England's supermarket distribution networks sustain yield premiums despite higher capital and fuel costs.
- Flatbed Trucks:Open-deck configurations accommodate outsized construction materials and agricultural machinery with flexible load securing arrangements. Infrastructure project pipelines around Birmingham and Manchester drive irregular demand spikes.
- Tanker Trucks:Pressure-vessel designs handle liquid bulk commodities including petroleum derivatives and food-grade oils.
- Box Trucks:Enclosed dry-van bodies protect general merchandise from weather exposure during multi-drop urban delivery cycles.
Reefer Trucks capture the steepest expansion trajectory; Box Trucks retain volume dominance.
Load Capacity:
Weight classification determines route eligibility, driver licensing requirements, and charging infrastructure compatibility under decarbonisation mandates.
- Above 15 Tons:Maximum gross combination weights up to 44 tonnes enable long-haul efficiency on England's motorway network. DVSA operator licensing constraints and battery-electric range limitations compress deployment flexibility for regional operators.
- Below 3 Tons:Light commercial vehicles navigate urban low-emission zones without HGV driver certification requirements. Last-mile e-commerce fulfillment in London and Manchester concentrates demand for compact electric van conversions.
- 3-7 Tons:Medium-duty rigid trucks bridge urban access and suburban distribution requirements.
- 7-15 Tons:Heavy rigid configurations serve regional pallet networks with reduced regulatory burden versus articulated combinations.
Above 15 Tons retains volume concentration; Below 3 Tons is gaining share fastest.
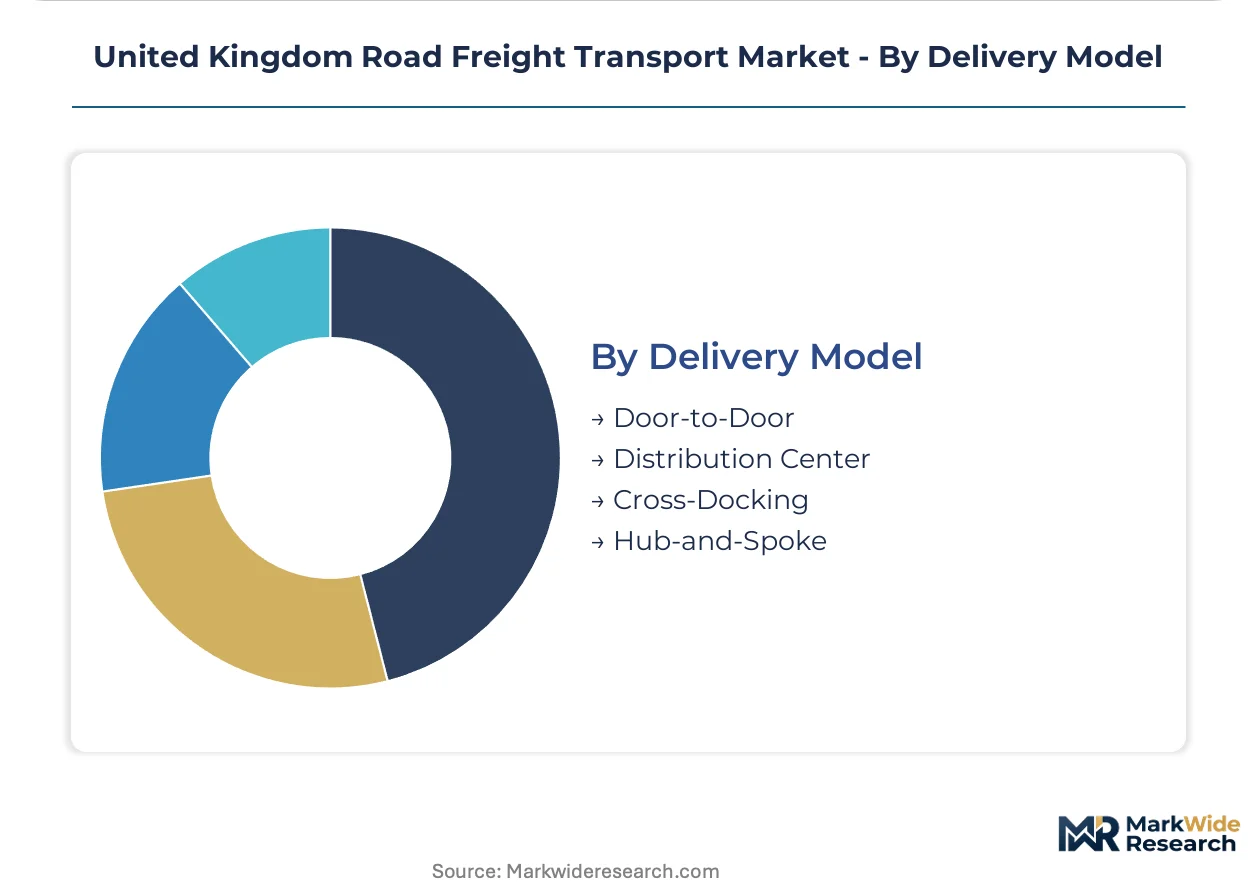
Delivery Model:
Network topology choices reflect inventory positioning strategies and customer service level agreements.
- Hub-and-Spoke:Centralised sortation facilities aggregate flows from multiple origins before line-haul dispatch to regional terminals. The East Midlands Gateway superhub anchors national parcel and pallet networks with rail-connected intermodal capacity.
- Door-to-Door:Direct origin-to-destination movements eliminate intermediate handling for high-value or time-sensitive commodities. Aerospace suppliers around Bristol and pharmaceutical manufacturers in Cambridge specify this model.
- Distribution Center:Consolidated inbound flows to retail replenishment centres enable cross-docking efficiency.
- Cross-Docking:Minimal dwell-time transfer operations match inbound supplier vehicles with outbound delivery routes.
Hub-and-Spoke commands volume; Door-to-Door shows the fastest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East Midlands Gateway superhub anchors England's logistics gravity, with the Birmingham logistics cluster and Greater Manchester distribution networks forming the dominant freight corridors for cross-border movements into Scotland and Wales.
England
E-commerce fulfillment density concentrates around the East Midlands Gateway and Birmingham logistics cluster, driving dedicated freight demand across the Midlands distribution hub. The Department for Transport's zero-emission HGV mandate under the decarbonisation strategy is restructuring fleet procurement priorities for operators serving England's motorway network. Pharmaceutical and fresh food cold-chain requirements sustain premium positioning for reefer trucks operating from Cambridge to Bristol.
Scotland
North Sea oil services and whisky exports generate specialized bulk and temperature-controlled movements from Aberdeen and Speyside through Carlisle border crossings. Transport Scotland's freight investment programs prioritize rail-road intermodal connections at Grangemouth and Mossend. The Central Belt corridor between Glasgow and Edinburgh captures urban last-mile consolidation for retail distribution.
Wales
Port of Holyhead ro-ro traffic and South Wales steel movements create irregular heavy-haul demand across the A55 and M4 corridors. Welsh Government transport decarbonisation targets accelerate depot electrification planning for fleets serving the Wrexham industrial estate. The Swansea Bay logistics zone attracts regional distribution center investment from English retailers.
Northern Ireland
Belfast Harbour and Larne port freight flows depend on Irish Sea ro-ro connections with Liverpool and Heysham under post-Brexit customs protocols. The Department for Infrastructure's freight strategy addresses cross-border movements to the Republic of Ireland through the A1 corridor. Manufacturing clusters around Craigavon and Londonderry generate just-in-sequence automotive component movements.
United Kingdom Road Freight Transport Market Competitive Landscape
The competitive structure tilts toward integrated contract logistics operators with captive transport assets. Mid-size regional hauliers retain share in bulk agricultural and temperature-controlled verticals through specialized equipment fleets. Three archetypes dominate: asset-heavy dedicated contract logistics providers, pure-play haulage operators with niche equipment specialization, and pan-European freight forwarders with UK road brokerage capabilities. Consolidation through fleet acquisition and strategic warehousing partnerships represents the primary competitive dynamic.
Among UK-based operators, Culina Group exemplifies the temperature-controlled network archetype, Turners (Soham) Ltd. occupies a position within bulk agricultural and aggregate haulage specialization, and Wincanton PLC represents the integrated warehousing and dedicated contract logistics model. These three companies anchor distinct strategic positions without overlapping service configurations.
| Leading Market Players |
|---|
| Culina Group |
| Turners (Soham) Ltd. |
| Wincanton PLC |
| DSV A/S |
| DHL Group |
| Gregory Distribution Ltd. |
| DACHSER |
| Howard Tenens |
| Kinaxia Logistics Limited |
| Others |
Value Network & Pricing Analysis
The Department for Transport's zero-emission HGV mandate gates both qualified supply and premium-tier pricing access, as fleet operators with depot electrification capabilities command rate premiums while diesel-dependent carriers face margin compression across England's logistics corridors.
Pricing Analysis
Outcome-based contracts anchored to pallet throughput and on-time-in-full performance dominate procurement between FMCG shippers and dedicated fleet operators. Price differentiation separates CSRD-aligned operators with verified emissions transparency from standard-tier providers lacking sustainability certification. Pricing pressure stems from battery-electric capital costs and charging infrastructure investments compressing operating margins for mid-size hauliers. SME manufacturing clusters exhibit highest price sensitivity, while pharmaceutical distributors accept premium positioning for temperature integrity guarantees.
Supply Chain Analysis
Driver availability constraints across England's East Midlands and West Midlands manufacturing belts compress fleet utilisation rates and extend lead times for contracted capacity. Vehicle chassis production draws from Germany, Poland, and Turkey, while lithium-ion battery packs source from South Korea and China. Single-source vulnerability concentrates in electric drivetrain components where alternative qualified suppliers remain limited. Distribution runs through the East Midlands Gateway superhub with rail-connected intermodal capacity anchoring national pallet networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK road freight transport market is becoming a vertical-integration race, as operators pursue captive warehousing assets to displace pure-play haulage relationships and capture margin from end-to-end logistics contracts.
For Market Incumbents: Hedge diesel residual value exposure through accelerated defleeting timelines ahead of zero-emission mandate enforcement. Secure long-term depot leaseholds with grid upgrade commitments to lock in charging infrastructure access before connection queue delays worsen. Battery-electric range limitations threaten above-15-ton long-haul operations; backward integration into regional hub networks mitigates this constraint.
For New Entrants and Emerging Players: Enter via temperature-controlled verticals where pharmaceutical and fresh food cold-chain requirements sustain yield premiums despite higher capital barriers. Target the East Midlands Gateway corridor for dedicated freight lane contracts with e-commerce fulfillment operators seeking alternatives to integrated incumbents. Lead with CSRD-aligned emissions reporting as a procurement differentiator against legacy fleet operators.
For Investors and Strategic Acquirers: DVSA enforcement protocol tightening is the leading indicator that telematics-capable fleets will command acquisition premiums over pre-2019 vehicle parc. Long-term viability favors asset-backed operators with integrated warehousing and captive transport assets over pure-play haulage models. Monitor charging infrastructure deployment pace versus battery-electric range capability convergence as the inflection signal for fleet replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Depot Electrification Programme | Grid-connected charging infrastructure secures zero-emission fleet operating rights under Department for Transport mandates. |
| Integrated Warendering Acquisition | Captive distribution centre assets displace third-party haulage relationships in FMCG vertical procurement. |
| Telematics Platform Deployment | Real-time tachograph compliance satisfies DVSA digital-first inspection protocols across pre-2019 vehicle parc. |
| Reefer Fleet Specialisation | Temperature-controlled capabilities capture pharmaceutical and fresh food premium yield segments. |
| CSRD Reporting Certification | Verified emissions transparency differentiates operators in corporate shipper sustainability procurement. |
Research Methodology
Multi-period observation of fleet utilisation rates, depot electrification timelines, and driver hour compliance patterns anchored the trend analysis, supplemented by interviews with fleet operations directors, transport procurement managers at FMCG and pharmaceutical shippers, DVSA enforcement officials, and charging infrastructure developers. Secondary validation drew from Department for Transport freight statistics, DVSA operator licensing databases, Vehicle Excise Duty reform documentation, and Health and Safety Executive load securing protocols. Bottom-up fleet capacity modeling and top-down logistics spend estimates were triangulated against cross-referenced primary and secondary sources.
Segment-weighting approaches applied service type, vehicle configuration, and load capacity classifications across the projection horizon. Full Truckload, Less Than Truckload, Dedicated Freight, and Expedited Transport categories were modeled separately with distinct driver utilisation and fuel cost assumptions. Above-15-ton, 7-15-ton, 3-7-ton, and Below-3-ton brackets captured divergent regulatory compliance burdens and electrification feasibility profiles. CAGRs were derived from trend extrapolation of fleet replacement cycles, e-commerce fulfillment density growth, and zero-emission mandate compliance trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated zero-emission mandate enforcement or prolonged charging infrastructure deployment delays. Forecasts reflect documented assumptions regarding battery-electric range improvement curves, driver availability recovery, and grid connection queue resolution timelines. Material deviation in DVSA enforcement intensity or Vehicle Excise Duty reform implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Railcar Unloader Market