
 Reverse Logistics Market | 2026-2036
Reverse Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Logistics Market Intelligence
Aftermarket service revenue is fragmenting across repair networks, refurbishment centers, and parts recovery operations as brands seek margin retention from returned goods. XPO Logistics leverages its North American warehouse footprint to capture high-value electronics returns. DSV anchors European remanufacturing flows through specialized pharmaceutical and automotive reverse corridors. FedEx competes on speed-to-credit, positioning its returns platform as a customer retention tool for omnichannel retailers.
Reverse logistics encompasses the collection, inspection, sorting, and disposition of post-consumer products back into supply chains through repair, resale, or material recovery pathways, requiring barcode-level traceability and condition grading protocols. Returns management and remanufacturing command the largest service-type revenue pools, while recycling margins compress under commodity price volatility. Third-party logistics providers capture outsourced solutions growth as shippers shed fixed-cost infrastructure, though integrated logistics retains appeal among high-volume automotive and electronics end users seeking control over proprietary component recovery.
The EPA oversees e-waste handling standards in the United States, while the EU Green Deal and REACH framework mandate material disclosure and circular economy targets that reshape product design and collection obligations across Europe. China's MEE enforces dual carbon goals that tighten scrap import rules and push domestic remanufacturing investment. Stakeholders must decide whether to build captive reverse capacity or partner with specialized providers as regulatory compliance costs diverge by geography and product category.
Market Dynamics
The EU Green Deal and Extended Producer Responsibility mandates are forcing manufacturers to internalize end-of-life costs, converting reverse logistics from a cost center into a regulated compliance function with dedicated infrastructure investments.
Growth Catalysts
- E-commerce returns volume:Online retail expansion in Germany, the United States, and China generates massive product flows requiring inspection, grading, and disposition at scale.
- REACH framework compliance:European chemical disclosure rules compel electronics and automotive OEMs to track material composition through recovery channels for circular economy reporting.
- Battery remanufacturing:Electric vehicle end-of-life protocols in China and the EU create specialized reverse corridors for lithium-ion cell recovery and second-life applications.
Market Restraints
- Commodity price volatility:Scrap metal and plastic pricing swings compress recycling margins, making material recovery operations economically unpredictable quarter-to-quarter.
- Transportation cost concentration:Fuel and last-mile delivery expenses in North American rural zones disproportionately erode returns processing economics.
- Data sanitization complexity:GDPR and state-level privacy laws impose strict device-wipe protocols that slow electronics refurbishment throughput and increase labor intensity.
Strategic Opportunities
- India aftermarket expansion:The country's nascent organized reverse supply chain offers first-mover advantage for refurbishment networks serving price-sensitive consumer electronics demand.
- Pharmaceutical cold-chain returns:Temperature-controlled biologics recovery represents a high-margin white space with specialized handling requirements and limited competition.
- AI-powered condition grading:Computer vision and machine learning convergence enables automated quality assessment, reducing inspection labor and accelerating resale velocity.
Industry Challenges
- Warehouse management system integration:Legacy ERP platforms lack native reverse-flow modules, forcing expensive custom middleware development for barcode-level traceability.
- Certified refurbishment technician shortage:Electronics repair skills gaps in key markets delay scaling of authorized remanufacturing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Logistics Market |
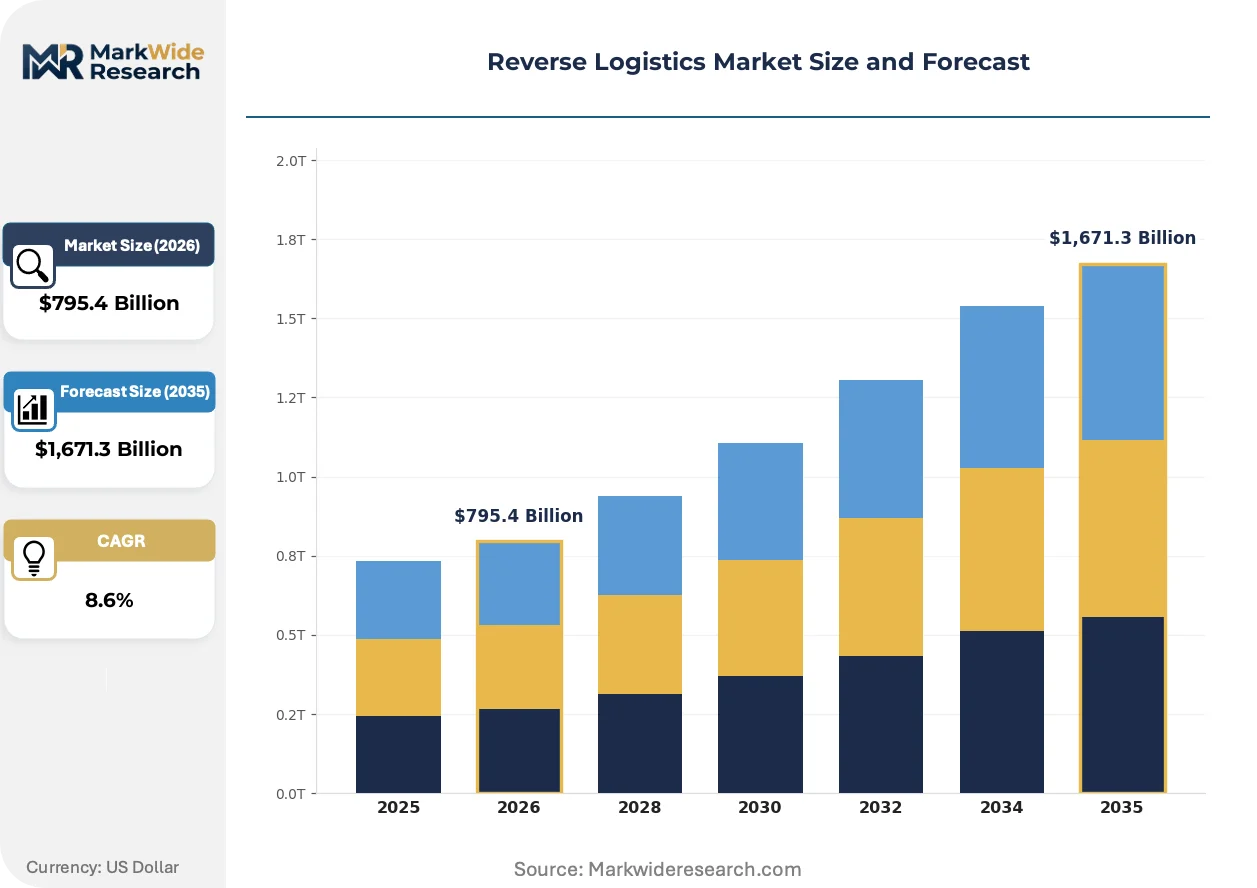
| Market Size in 2026 | $795.4 Billion |
| Market Size in 2035 | $1,671.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Returns Management, Remanufacturing, Recycling, Repair Services End User: E-commerce, Retail, Electronics, Automotive Logistics Model: Integrated Logistics, Third-Party Logistics, In-House Logistics, Outsourced Solutions Product Type: Consumer Electronics, Apparel, Industrial Equipment, Furniture |
| Companies Covered | XPO Logistics, DSV, UPS, DB Schenker, Kuehne + Nagel, FedEx, CH Robinson, CEVA Logistics, DHL Supply Chain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Logistics Market Strategic Shifts & Innovations
Digital traceability infrastructure and automated disposition systems are redefining competitive advantage in returns processing. Three developments merit particular attention.
Blockchain-enabled provenance tracking is migrating from pilot programs to operational deployment at scale. Electronics OEMs in Germany and the United States are adopting distributed ledger systems to document component origin through multiple life cycles. This technology is migrating from compliance documentation toward dynamic pricing engines that adjust resale values based on verified usage history and refurbishment touchpoints.
The EPA's e-waste handling standards are tightening data destruction and material recovery protocols for federal contractors. These rules now require chain-of-custody documentation from collection through final disposition. Enterprise IT asset disposition vendors serving government and healthcare verticals face the steepest compliance ramps.
Retailers are unbundling returns handling from core logistics contracts, creating standalone procurement categories with discrete SLA structures. Omnichannel merchants in the United Kingdom and France now source inspection, grading, and resale as separate service lines rather than bundled fulfillment add-ons. This shift concentrates purchasing power among specialized 3PLs with dedicated refurbishment infrastructure.
Reverse Logistics Market Segmentation
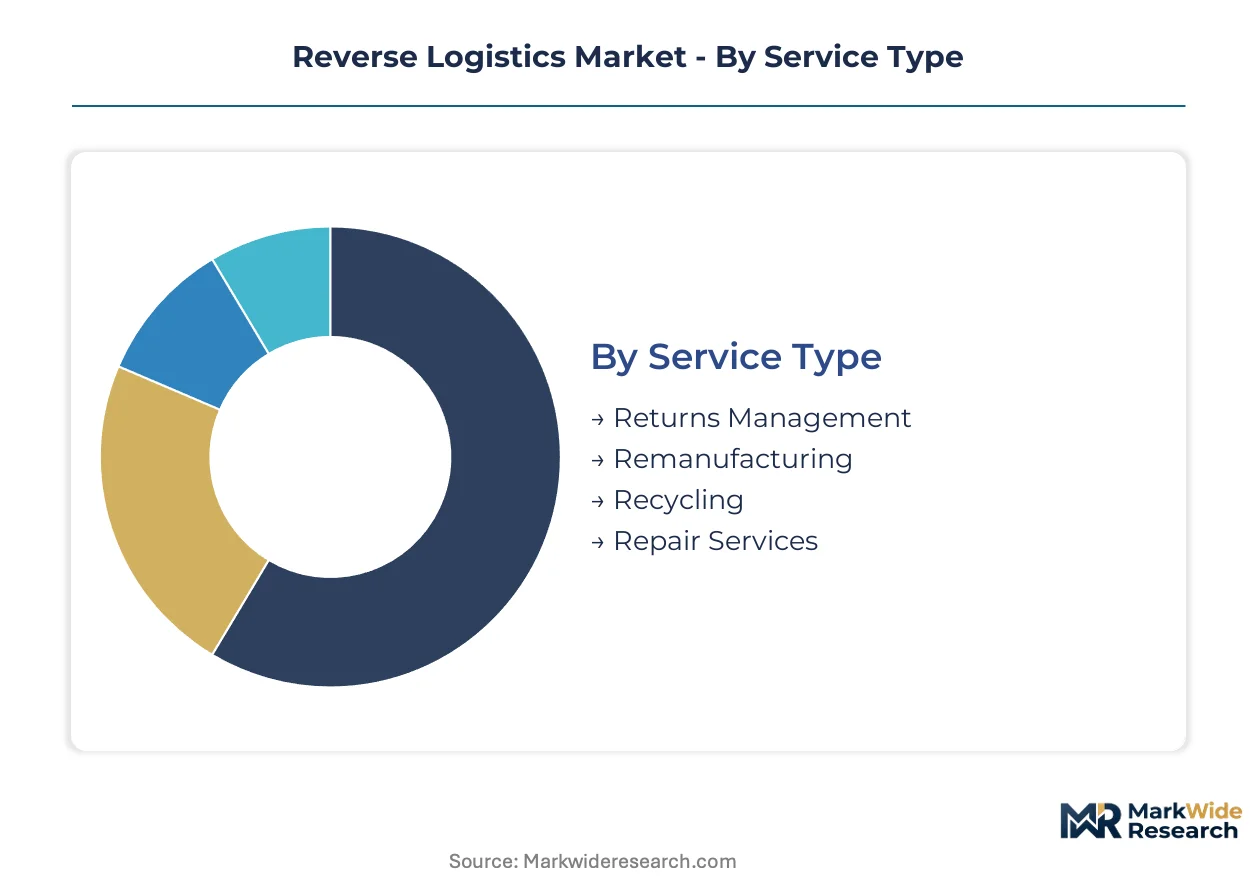
Reverse logistics operators configure service portfolios around four distinct segmentation axes. Each dimension shapes capital deployment, margin structure, and regulatory exposure differently across the value chain.
Service Type:
Cost tier determines infrastructure intensity and margin profile across reverse service lines.
- Returns Management:Encompasses collection, inspection, sorting, and disposition workflows with barcode-level traceability requirements. E-commerce platforms in Germany and the United States drive volume concentration as omnichannel merchants unbundle returns handling from core logistics contracts.
- Remanufacturing:Involves component recovery, refurbishment, and quality recertification to OEM specifications. Automotive and electronics OEMs in China and the European Union anchor demand as Extended Producer Responsibility mandates internalize end-of-life costs.
- Recycling:Material recovery operations for scrap metal, plastics, and rare earth elements. Commodity price volatility compresses margins unpredictably.
- Repair Services:Warranty fulfillment and aftermarket maintenance networks. Certified technician shortages constrain scaling in key markets.
Returns Management holds installed capacity. Remanufacturing is rotating up the share rankings.
End User:
Application-specific handling protocols create divergent service requirements and compliance footprints.
- E-commerce:High-velocity returns processing with automated grading and rapid credit issuance. Volume concentrates in the United States, Germany, and China as platform expansion outpaces physical retail infrastructure.
- Retail:Omnichannel integration of store-based returns with centralized disposition. Margin retention from resale channels drives investment in refurbishment capability.
- Electronics:Data sanitization under GDPR and state-level privacy laws imposes strict device-wipe protocols. EPA e-waste standards tighten chain-of-custody documentation for federal contractors.
- Automotive:Battery remanufacturing corridors for lithium-ion recovery and second-life applications. China's MEE dual carbon goals and EU Green Deal protocols reshape investment patterns.
Electronics commands the steepest compliance ramps. E-commerce is expanding most quickly as a demand source.
Logistics Model:
Customer type and volume scale determine captive versus outsourced configuration decisions.
- Integrated Logistics:End-to-end control over proprietary component recovery favored by high-volume automotive and electronics end users. Capital intensity limits adoption to largest shippers.
- Third-Party Logistics:Specialized providers capture outsourced solutions growth as shippers shed fixed-cost infrastructure. XPO Logistics and DSV anchor North American and European networks respectively.
- In-House Logistics:Captive reverse capacity built around confidential product designs and core component security. Prevalent among pharmaceutical and defense verticals.
- Outsourced Solutions:Discrete SLA structures for inspection, grading, and resale as standalone procurement categories. Retailers in the United Kingdom and France now source these separately from bundled fulfillment.
Third-Party Logistics holds installed capacity. Outsourced Solutions is climbing the fastest as unbundling accelerates.
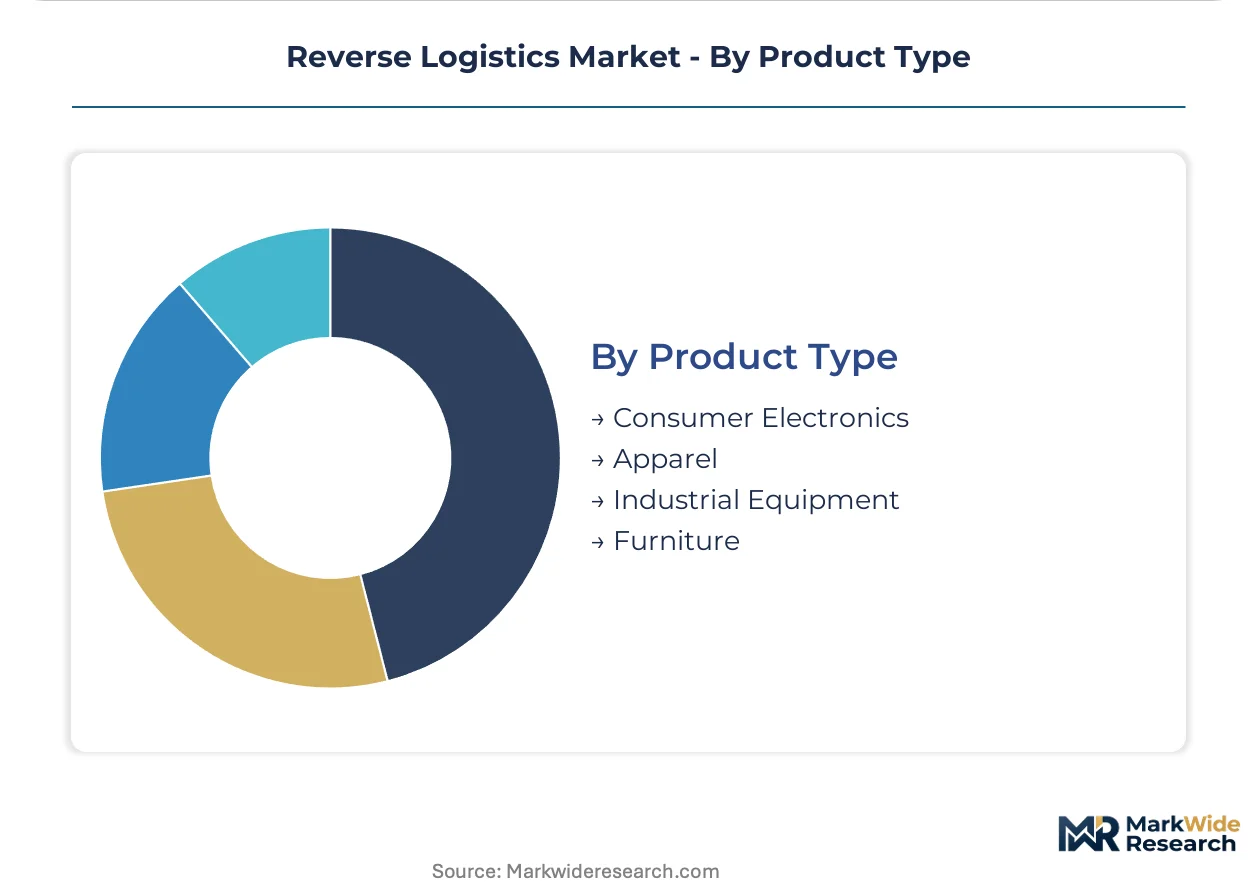
Product Type:
Physical characteristics and value density shape transportation economics and refurbishment viability.
- Consumer Electronics:Smartphone, laptop, and tablet returns with high resale velocity potential. Condition grading automation via computer vision reduces inspection labor intensity.
- Apparel:Seasonal return spikes with lower per-unit value requiring rapid disposition to secondary markets. Last-mile cost concentration in rural zones erodes processing economics.
- Industrial Equipment:Heavy-asset recovery with remanufacturing value concentrated in precision components. Extended producer responsibility frameworks in the EU drive circular economy investment.
- Furniture:Bulky returns with high transportation cost-to-value ratios limiting economically viable recovery options. Disposal fees increasingly internalized under regulatory pressure.
Consumer Electronics holds installed capacity. Industrial Equipment is gaining share fastest as circular economy mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany treats reverse logistics as a regulated compliance function under Extended Producer Responsibility, while the United States and China prioritize speed-to-credit and battery recovery economics respectively. This consumption-mix differential shapes infrastructure investment patterns across major markets.
United States
E-commerce returns volume concentrates in California and Texas distribution corridors, with omnichannel retailers unbundling inspection and grading services. EPA e-waste handling standards tighten chain-of-custody documentation for federal contractors. Chicago anchors third-party logistics capacity expansion as XPO Logistics scales high-value electronics processing.
Germany
Automotive OEMs drive remanufacturing demand as EU Green Deal mandates internalize end-of-life costs for lithium-ion battery recovery. REACH framework compliance compels material disclosure tracking through circular economy reporting channels. The Rhine-Ruhr corridor hosts specialized pharmaceutical reverse corridors serving European remanufacturing flows.
China
Electric vehicle end-of-life protocols generate specialized reverse corridors for battery cell recovery and second-life applications. MEE enforces dual carbon goals that tighten scrap import rules and push domestic remanufacturing investment. Shenzhen and Shanghai build dedicated reverse supply chain infrastructure for consumer electronics refurbishment.
India
Price-sensitive consumer electronics demand creates first-mover opportunities for organized refurbishment networks in nascent aftermarket channels. Central pollution control directives push state-level e-waste collection obligations without federal harmonization. Maharashtra and Karnataka concentrate early infrastructure deployment around Mumbai and Bangalore tech corridors.
United Kingdom
Omnichannel merchants source inspection, grading, and resale as separate procurement categories with discrete SLA structures. GDPR device-wipe protocols slow electronics refurbishment throughput and increase labor intensity. London and the Southeast concentrate unbundled returns handling contracts as retailers separate logistics from core fulfillment.
Reverse Logistics Market Key Industry Players
Capability concentration sits with specialized remanufacturing providers; scale advantage sits with integrated logistics networks spanning multiple continents. The market structures around three tiers: asset-heavy warehouse operators, specialized pharmaceutical and automotive corridor managers, and technology-enabled returns platforms. Strategic moves cluster on geographic corridor anchoring and unbundled service line expansion.
Within the integrated logistics tier, XPO Logistics and DSV occupy positions that exemplify divergent regional strategies. XPO leverages North American warehouse footprint concentration for high-value electronics returns. DSV anchors European pharmaceutical and automotive reverse corridors. FedEx sits within the speed-focused tier, positioning returns platforms as customer retention tools for omnichannel retailers.
| Leading Market Players |
|---|
| XPO Logistics |
| DSV |
| UPS |
| DB Schenker |
| Kuehne + Nagel |
| FedEx |
| CH Robinson |
| CEVA Logistics |
| DHL Supply Chain |
| Others |
Cost & Logistics Intelligence
The Rhine-Ruhr corridor anchors European remanufacturing capacity, where specialized pharmaceutical and automotive reverse logistics infrastructure concentrates pricing power among corridor-dominant operators serving REACH-mandated material disclosure workflows.
Pricing Analysis
Long-term offtake contracts dominate high-volume automotive and electronics OEM relationships, while spot pricing governs commodity recycling flows vulnerable to scrap metal volatility. Three-tier pricing structure across premium, standard, and economy levels separates certified remanufacturing from basic refurbishment and material recovery tiers. Cost compression in recycling operations is intensifying because commodity price swings erode quarterly margins unpredictably. E-commerce platforms exhibit the highest price sensitivity, prioritizing speed-to-credit over refurbishment depth, while pharmaceutical cold-chain returns buyers accept premium pricing for specialized handling.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard among third-party logistics providers competing for retailer unbundled procurement contracts. Reverse logistics capacity concentrates in Germany, China, and the United States, with specialized corridor development in Shenzhen for consumer electronics and Chicago for high-value returns processing. Operations draw from lithium-ion battery feedstocks, post-consumer electronics scrap, and automotive component cores as primary inputs. Single-source vulnerability runs through concentrated battery remanufacturing corridors in China. Distribution runs through hub-and-spoke warehouse networks with last-mile collection density determining rural zone economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse logistics sits in early-cycle expansion as Extended Producer Responsibility mandates convert compliance costs into dedicated infrastructure investment across the European Union and China.
For Market Incumbents: Pre-empt specialized corridor consolidation by anchoring pharmaceutical and automotive reverse capacity in the Rhine-Ruhr and Shenzhen clusters before regional competitors lock in long-term OEM contracts. XPO Logistics and DSV demonstrate the defensive value of geographic footprint concentration. Certification investment in REACH and EPA e-waste standards builds switching costs against emerging 3PL challengers.
For New Entrants and Emerging Players: Establish a beachhead in India's nascent organized refurbishment networks serving price-sensitive consumer electronics demand in Maharashtra and Karnataka tech corridors. Pharmaceutical cold-chain returns represent the most penetrable white space, with limited incumbent specialization and high-margin temperature-controlled handling requirements. Lead with AI-powered condition grading as a differentiated go-to-market angle to reduce inspection labor intensity against legacy operators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy warehouse operators with integrated refurbishment infrastructure over pure-play technology platforms lacking physical disposition capability. Long-term viability hinges on regulatory compliance depth rather than software-only solutions. Acquisition targets should demonstrate corridor dominance in battery remanufacturing or pharmaceutical reverse flows. Watch EPA e-waste standard tightening and EU Green Deal enforcement intensity as inflection indicators for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Corridor Anchoring in Battery Recovery | Electric vehicle end-of-life protocols in China and the EU create captive lithium-ion cell recovery demand. |
| AI-Powered Condition Grading Deployment | Computer vision automation reduces inspection labor and accelerates resale velocity for electronics returns. |
| Unbundled Service Line Expansion | Retailers in the United Kingdom and France now source inspection, grading, and resale as discrete procurement categories. |
| REACH Compliance Infrastructure Investment | European chemical disclosure rules compel material tracking through circular economy reporting channels. |
| Pharmaceutical Cold-Chain Returns Capability | Temperature-controlled biologics recovery represents high-margin white space with specialized handling requirements. |
Research Approach
A spread of perspectives from 3PL operations directors, OEM sustainability officers, refurbishment center managers, and regulatory compliance leads converged on the working assumptions driving segmentation and growth estimates. Primary fieldwork combined structured interviews with secondary validation through EPA e-waste handling standards documentation, EU Green Deal regulatory filings, MEE dual carbon goal enforcement notices, and customs data on scrap metal trade flows. Bottom-up service line sizing and top-down market triangulation cross-checked volume assumptions across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling returns volume generation against installed processing capacity across service type, end user, logistics model, and product type dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating e-commerce expansion rates, regulatory mandate phase-in schedules, and remanufacturing technology adoption curves. Forecast inputs included battery end-of-life vehicle stock projections and electronics refurbishment automation penetration assumptions.
Sensitivities concentrate around commodity price volatility in recycling operations, regulatory enforcement intensity divergence across geographies, and e-commerce returns volume growth deceleration. Forecasts reflect documented assumptions on mandate implementation timelines and technology adoption rates. Macroeconomic contraction, regulatory rollback, or breakthroughs in product durability extending replacement cycles would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market