
 ASEAN Cold Chain Logistics Market | 2026-2036
ASEAN Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Cold Chain Logistics Market Outlook
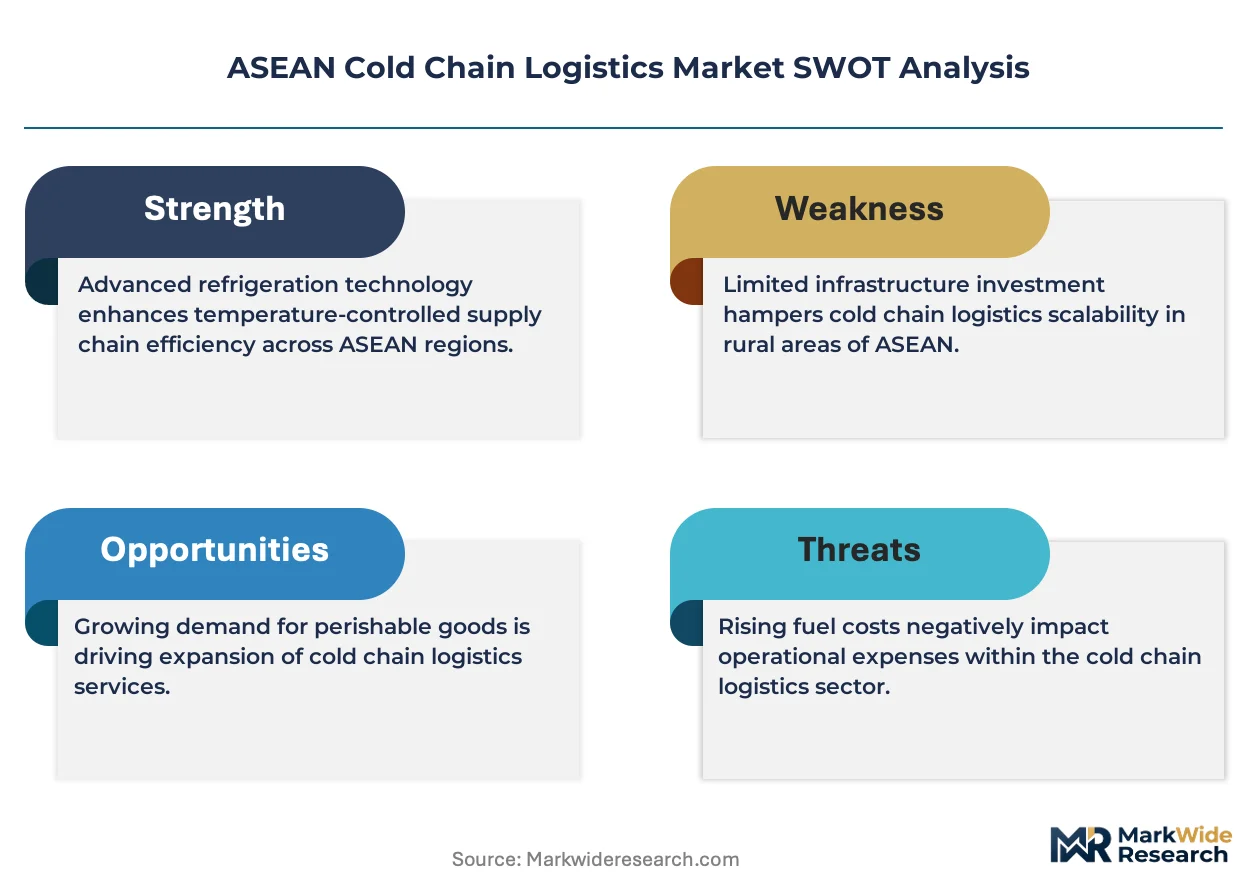
Phase-change materials are rebalancing insulation economics in refrigerated transport across Southeast Asia. DHL International GmbH leverages its multi-country hub network to sustain temperature-controlled pharmaceutical flows between Singapore, Thailand, and Vietnam. Tiong Nam Logistics Holdings Berhad anchors domestic Malaysian cold storage with extensive warehouse automation in Selangor and Johor. JWD Group differentiates through specialized frozen seafood logistics serving Thai export processors at Laem Chabang port.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—maintaining ranges from deep frozen at minus 25 degrees Celsius to chilled at 2 to 8 degrees Celsius through refrigerated vehicles, insulated containers, and climate-managed warehouses—designed to preserve perishable goods from production through final delivery. Transportation services dominate service type revenue as cross-border ASEAN fruit and seafood exports require continuous refrigeration across multiple customs checkpoints. IoT Solutions within the technology segment represent the fastest-expanding category as real-time temperature monitoring and predictive alerts reduce spoilage liability for pharmaceutical shipments. Food & Beverage end users command the largest volume share, though Pharmaceuticals generates superior per-unit margins due to stringent Good Distribution Practice compliance requirements.
Thailand's FDA enforces pharmaceutical cold chain standards that mandate continuous temperature documentation for vaccine distribution, while Singapore's SFA and HSA jointly regulate food safety and medical product storage conditions through integrated licensing frameworks. Vietnam's Ministry of Agriculture and Rural Development operates decentralized cold chain certification for seafood export facilities seeking EU and Japanese market access. Stakeholders must evaluate where regulatory divergence between ASEAN member states creates compliance fragmentation versus harmonization opportunities for regional network design.
Market Dynamics
Pharmaceutical cold chain compliance mandates are forcing logistics providers across Southeast Asia to retrofit warehouse networks with continuous temperature monitoring infrastructure. Thailand's FDA documentation requirements for vaccine distribution are cascading into cross-border shipment protocols, compressing operational margins while elevating technical barriers to market entry.
Growth Catalysts
- Thailand's Board of Investment incentives:Tax holidays for cold storage automation equipment are accelerating warehouse robotics deployment in Bangkok and Eastern Economic Corridor zones.
- EU-Japan seafood certification alignment:Vietnam's Ministry of Agriculture decentralized cold chain certification is enabling Mekong Delta processors to access premium export markets with verified temperature documentation.
- Phase-change material insulation:Advanced thermal buffering compounds are reducing diesel consumption in refrigerated transport fleets operating across ASEAN highway corridors.
Market Restraints
- Diesel price volatility:Refrigerated transport fleets depend on fossil fuel inputs that fluctuate with Singapore refined product benchmarks, compressing per-route profitability.
- Cross-border customs fragmentation:Non-harmonized sanitary inspection protocols at Thailand-Cambodia and Vietnam-Laos checkpoints create temperature excursion risks during extended border delays.
- Limited domestic reefer manufacturing:ASEAN cold chain operators rely on imported refrigerated vehicle chassis from Japanese and European suppliers, constraining fleet expansion timelines.
Strategic Opportunities
- Cambodia and Laos agricultural corridors:Underdeveloped cold storage density in these Mekong sub-markets creates first-mover advantages for pre-cooling infrastructure near harvest zones.
- IoT-predictive maintenance convergence:Real-time sensor networks combined with machine learning algorithms enable fleet operators to prevent refrigeration unit failures before cargo spoilage occurs.
- Singapore's integrated licensing frameworks:Joint SFA-HSA regulations for food and pharmaceutical storage are creating template compliance architectures exportable to neighboring markets.
Industry Challenges
- Refrigeration technician scarcity:Specialized maintenance skills for transport refrigeration units and warehouse climate systems remain concentrated in Thailand and Malaysia, limiting operational scaling in frontier markets.
- Multi-jurisdiction GDP certification:Pharmaceutical distributors must maintain parallel Good Distribution Practice documentation standards across Thailand FDA, Singapore HSA, and Vietnam Ministry of Health regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Cold Chain Logistics Market |
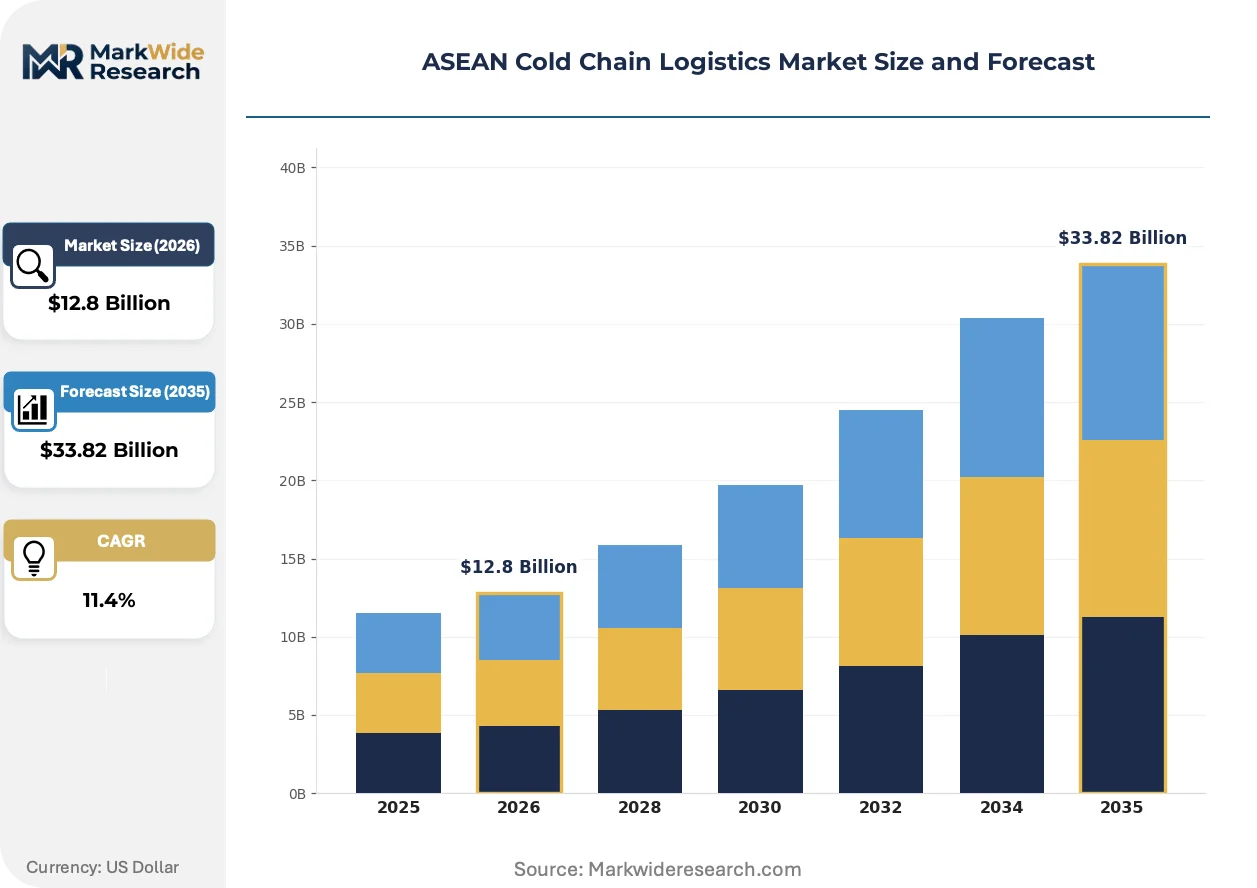
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Monitoring, Packaging Technology: Refrigeration, Insulation, Tracking Systems, IoT Solutions End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Distribution Channel: Direct, Retail, Wholesale, E-commerce |
| Companies Covered | DHL International GmbH, Tiong Nam Logistics Holdings Berhad, JWD Group, Yusen Logistics Co., Ltd., DSV A/S, Nippon Express, Yamato Logistics (HK) Ltd., Konoike Cool Logistics (Thailand) Co., Ltd., Thai Max Co. Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Cold Chain Logistics Market Strategic Shifts
Digital traceability infrastructure is displacing paper-based temperature logs across ASEAN pharmaceutical corridors. Real-time data streams are becoming contractual requirements between logistics providers and biologics manufacturers.
Phase-change material thermal buffering is expanding into long-haul refrigerated transport across the Thai-Malaysian peninsula. Seafood exporters operating from Songkhla and Penang ports are adopting composite insulation panels embedded with paraffin-based compounds. These materials stabilize cargo temperatures during multi-day voyages to Middle Eastern and European destinations, reducing generator runtime and fuel expenditure.
Thailand's FDA continuous temperature documentation mandate for vaccine distribution is forcing third-party logistics providers to deploy redundant sensor networks. Warehouses storing pharmaceutical products must now maintain blockchain-verified temperature records accessible to regulators within four hours. Malaysian operators serving cross-border Thai pharmaceutical flows are investing in parallel compliance infrastructure to maintain market access.
Biologics manufacturers are consolidating procurement relationships around logistics providers with integrated pharmaceutical licensing across multiple ASEAN jurisdictions. Small and mid-sized cold chain operators lacking Singapore HSA or Thailand FDA certifications are losing contract renewals to regional network specialists. This concentration dynamic is most visible in Singapore's Tuas biomedical cluster, where multinational pharmaceutical firms are reducing vendor counts from twelve to four preferred logistics partners.
ASEAN Cold Chain Logistics Market Segmentation
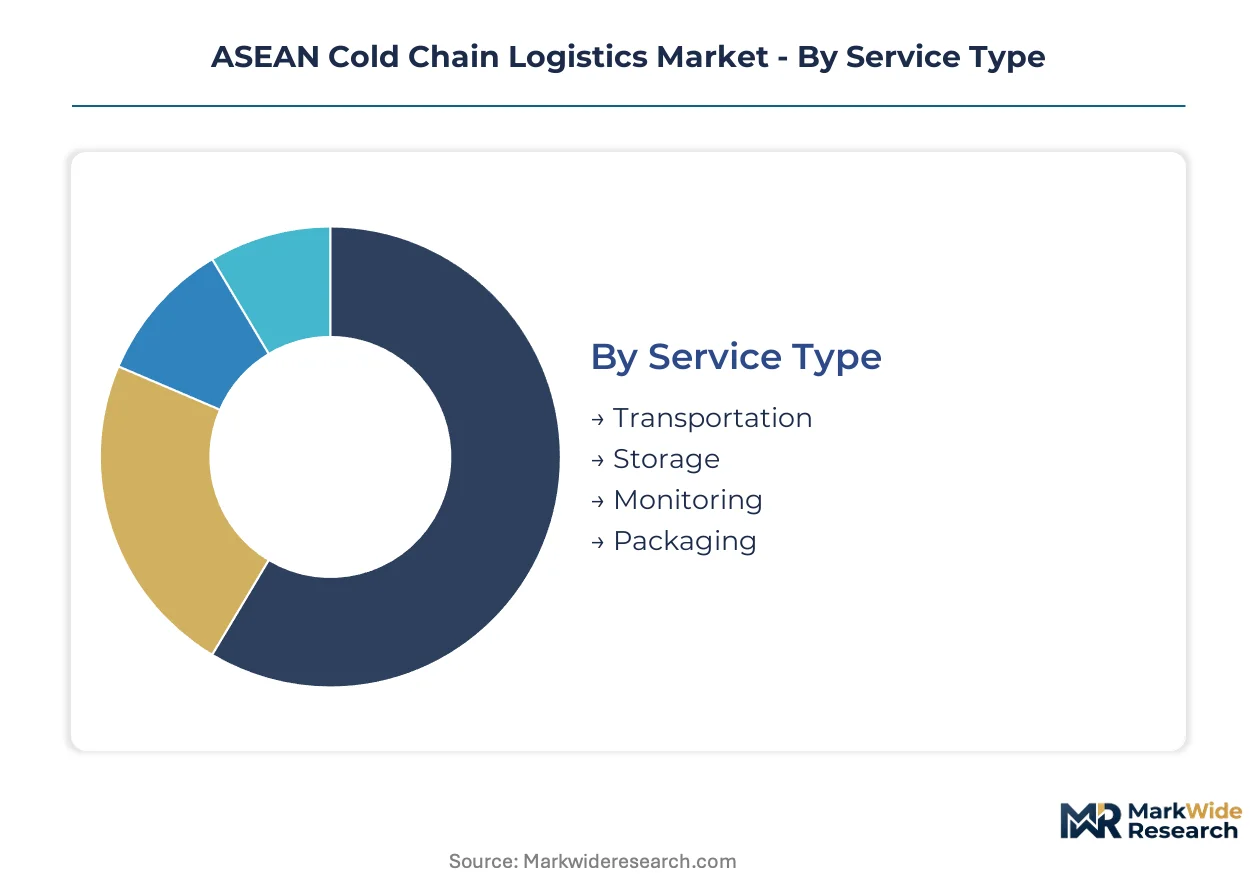
ASEAN cold chain logistics operators configure service portfolios around cargo sensitivity tiers and cross-border regulatory complexity. Segmentation choices determine capital allocation between warehouse automation, fleet refrigeration specifications, and compliance documentation systems.
Service Type:
Standardization dominates high-volume transportation contracts while storage services require customization for pharmaceutical GDP certification or seafood export pre-cooling.
- Transportation:Refrigerated vehicle fleets maintain continuous temperature ranges from deep frozen at minus 25 degrees Celsius to chilled at 2 to 8 degrees Celsius across Thai-Malaysian highway corridors and Vietnam-Cambodia border crossings. Cross-border fruit and seafood exports drive fleet utilization, though diesel price volatility tied to Singapore refined product benchmarks compresses per-route profitability.
- Storage:Climate-managed warehouses deploy automated racking systems and redundant cooling infrastructure to satisfy Thailand FDA continuous temperature documentation mandates for vaccine distribution. Thailand's Board of Investment tax holidays for cold storage automation equipment are accelerating robotics deployment in Bangkok and Eastern Economic Corridor zones.
- Monitoring:Real-time sensor networks track cargo conditions through multiple customs checkpoints, generating blockchain-verified records accessible to regulators within four hours.
- Packaging:Phase-change material insulation and composite thermal buffering compounds reduce generator runtime in long-haul refrigerated transport.
Most installed capacity flows through Transportation. Expansion is steepest in Storage.
Technology:
Refrigeration hardware absorbs the majority of capital expenditure while IoT software layers command expanding maintenance budgets and recurring revenue streams.
- Refrigeration:Transport refrigeration units and warehouse climate systems depend on specialized maintenance skills concentrated in Thailand and Malaysia, limiting operational scaling in frontier markets. Fleet operators source chassis primarily from Japanese and European suppliers due to limited domestic reefer manufacturing across ASEAN.
- IoT Solutions:Real-time temperature monitoring combined with machine learning algorithms enables predictive maintenance that prevents cargo spoilage before refrigeration unit failures occur. Biologics manufacturers now mandate digital traceability infrastructure as contractual requirements, displacing paper-based temperature logs.
- Insulation:Paraffin-based phase-change materials embedded in composite panels stabilize cargo temperatures during multi-day voyages from Songkhla and Penang ports to Middle Eastern and European destinations.
- Tracking Systems:GPS-integrated location services coordinate handoffs between multimodal transport legs across Singapore, Thailand, and Vietnam hub networks.
Refrigeration claims the largest share of technology spending. IoT Solutions are climbing the fastest as predictive analytics reduce spoilage liability.
End User:
Food and beverage volume concentration contrasts with pharmaceutical margin premiums driven by stringent compliance documentation requirements.
- Food & Beverage:Seafood and tropical fruit processors in Vietnam's Mekong Delta agricultural export corridor require expanded freezing and pre-cooling facilities to access EU and Japanese markets with verified temperature documentation. EU-Japan seafood certification alignment through Vietnam's Ministry of Agriculture decentralized cold chain certification enables premium market access.
- Pharmaceuticals:Vaccine and biologics distribution networks demand continuous temperature documentation under Thailand FDA, Singapore HSA, and Vietnam Ministry of Health parallel Good Distribution Practice regimes. Small and mid-sized operators lacking multi-jurisdiction certifications are losing contract renewals to regional network specialists.
- Electronics:Semiconductor and component shipments require humidity-controlled transport corridors between Malaysian manufacturing zones and Singapore distribution hubs.
- Cosmetics:Temperature-sensitive formulations drive demand for climate-managed warehousing in urban consumption centers.
Food & Beverage dominates cargo volume. Pharmaceuticals generates superior per-unit margins.
Distribution Channel:
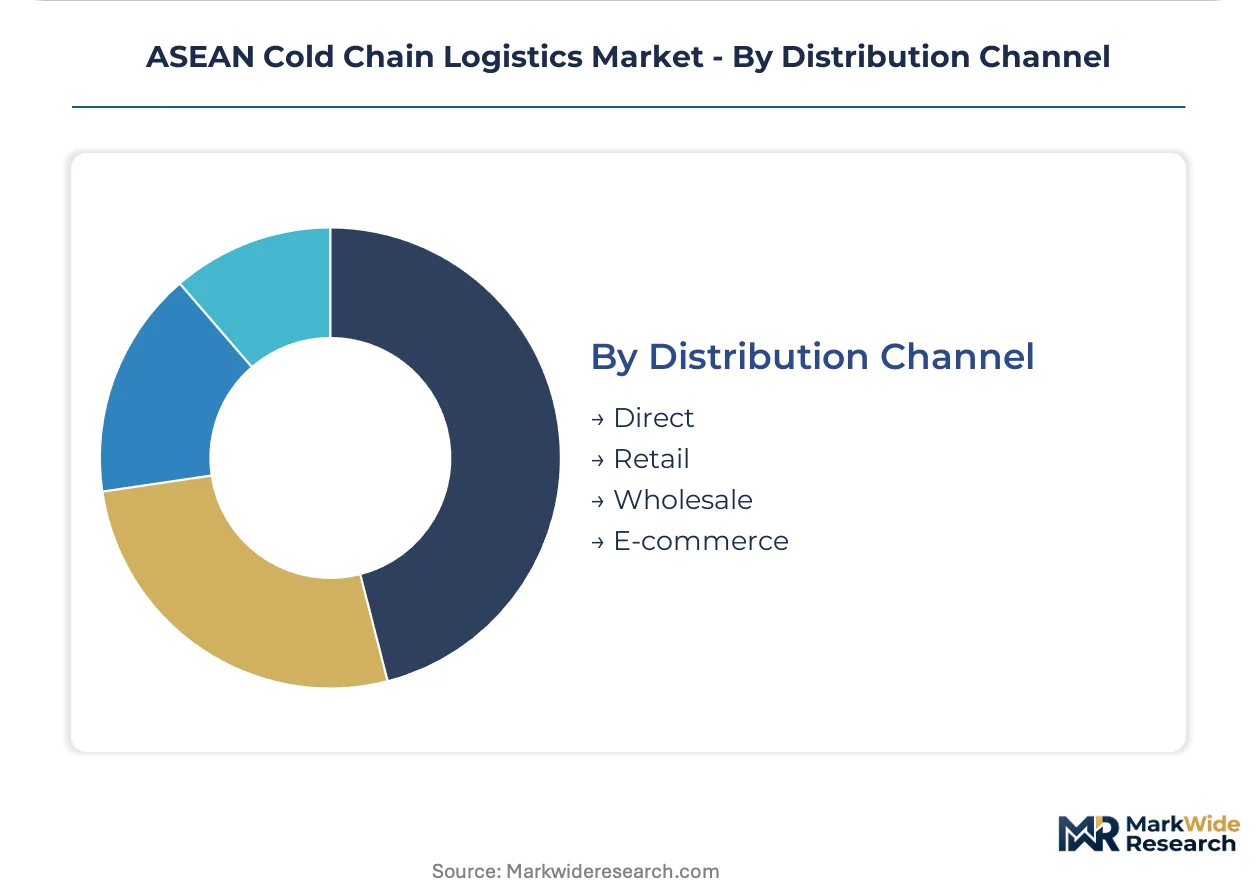
Direct channel relationships with multinational pharmaceutical firms are consolidating around fewer preferred logistics partners, while wholesale networks fragment across agricultural procurement intermediaries.
- Direct:Biologics manufacturers in Singapore's Tuas biomedical cluster are reducing vendor counts from twelve to four preferred logistics partners with integrated pharmaceutical licensing across multiple ASEAN jurisdictions. Direct procurement relationships command premium pricing for guaranteed compliance documentation.
- Wholesale:Agricultural cooperatives and seafood export processors aggregate harvest volumes for consolidation at Laem Chabang port and Mekong Delta cold storage facilities.
- Retail:Supermarket chains and food service distributors operate captive cold storage for last-mile delivery in Bangkok, Kuala Lumpur, and Ho Chi Minh City metropolitan areas.
- E-commerce:Online grocery platforms are driving demand for urban micro-fulfillment centers with rapid temperature-controlled picking and delivery capabilities.
Direct channels capture the highest-value pharmaceutical flows. E-commerce is gaining share fastest in urban last-mile delivery infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Tuas biomedical cluster anchors pharmaceutical cold chain infrastructure across Southeast Asia, commanding premium compliance standards that cascade through regional networks. Temperature-controlled logistics capacity concentrates in Thailand, Vietnam, Malaysia, and Indonesia, with emerging corridors in Cambodia and Laos attracting first-mover warehouse investments.
Thailand
Bangkok's Eastern Economic Corridor drives automated cold storage expansion for vaccine distribution networks. Thailand's FDA mandates continuous temperature documentation with blockchain-verified records accessible within four hours. Laem Chabang port anchors specialized frozen seafood logistics serving export processors with climate-controlled container staging.
Vietnam
Mekong Delta agricultural corridors demand expanded pre-cooling infrastructure for tropical fruit and seafood exports to EU and Japanese markets. Vietnam's Ministry of Agriculture operates decentralized cold chain certification enabling verified temperature documentation for premium market access. Ho Chi Minh City metropolitan cold storage clusters are integrating urban micro-fulfillment for e-commerce grocery platforms.
Singapore
Tuas biomedical manufacturing zones concentrate biologics production requiring integrated pharmaceutical licensing across multiple ASEAN jurisdictions. Singapore's SFA and HSA jointly regulate food safety and medical product storage through template compliance architectures exportable to neighboring markets. The city-state's multi-country hub network sustains temperature-controlled pharmaceutical flows to Thailand and Vietnam.
Malaysia
Selangor and Johor warehouse automation clusters anchor domestic cold storage capacity with extensive robotics deployment. Malaysian operators serving cross-border Thai pharmaceutical flows invest in parallel Thailand FDA compliance infrastructure to maintain market access. Penang port seafood exporters adopt phase-change material insulation for multi-day voyages to Middle Eastern destinations.
Indonesia
Java's urban consumption centers drive demand for climate-managed warehousing in Jakarta and Surabaya metropolitan areas. The national pharmaceutical regulator enforces evolving Good Distribution Practice standards for vaccine distribution networks. Batam and Bintan logistics zones are developing transshipment cold storage for cross-border ASEAN fruit flows.
ASEAN Cold Chain Logistics Market Competitive Environment
Global majors compete with regional champions across compliance certification depth, with multinational logistics networks leveraging multi-country hub infrastructure against specialized local operators. The vendor base stratifies into three tiers: integrated pharmaceutical specialists maintaining parallel FDA-HSA-Ministry of Health certifications, domestic cold storage operators with warehouse automation advantages, and port-centric seafood logistics providers. Competitive moves center on M&A consolidation for certification breadth and automated capacity expansion in Eastern Economic Corridor and Mekong Delta zones.
Among German-based global logistics networks, DHL International GmbH exemplifies the integrated pharmaceutical specialist archetype with multi-country temperature-controlled infrastructure. Japanese logistics operators including Yusen Logistics Co., Ltd. and Nippon Express occupy positions emphasizing precision temperature management for cross-border ASEAN corridors. Regional champions such as Tiong Nam Logistics Holdings Berhad and JWD Group represent domestic automation leaders and port-centric seafood specialists respectively, anchoring market presence through geographic density and specialized cold chain expertise.
| Leading Market Players |
|---|
| DHL International GmbH |
| Tiong Nam Logistics Holdings Berhad |
| JWD Group |
| Yusen Logistics Co., Ltd. |
| DSV A/S |
| Nippon Express |
| Yamato Logistics (HK) Ltd. |
| Konoike Cool Logistics (Thailand) Co., Ltd. |
| Thai Max Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Diesel fuel costs cascade through refrigerated transport pricing tiers across ASEAN highway corridors, compressing margins for fleet operators while elevating premiums for pharmaceutical-certified cold storage capacity in Bangkok and Singapore. Cross-border fruit and seafood exporters absorb fuel volatility through spot-rate contracts, whereas vaccine distributors lock in multi-year agreements with GDP-certified logistics providers to secure compliance documentation.
Pricing Analysis
Input-cost pass-through from Singapore refined product benchmarks shapes three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical GDP certification commands premium tier positioning, while Mekong Delta seafood exporters operate in price-sensitive standard tiers. Pricing pressure stems from diesel volatility and Japanese/European reefer chassis import costs. Small agricultural cooperatives exhibit highest price sensitivity; multinational biologics manufacturers prioritize compliance over cost.
Supply Chain Analysis
Direct-to-pharma channels handle hyperscale vaccine distribution through Singapore's Tuas biomedical cluster, while wholesale networks fragment across Mekong Delta agricultural procurement intermediaries. Supply concentrates in Thailand, Vietnam, and Malaysia for warehouse automation and fleet operations. Fleet expansion draws from imported Japanese and European refrigerated vehicle chassis, paraffin-based phase-change materials, and IoT sensor networks. Single-source vulnerability in reefer chassis imports creates supply chain risk. Distribution runs through multi-country hub networks anchored by Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN cold chain logistics functions as a stable compounder, with pharmaceutical compliance mandates creating durable pricing power for certified operators across the region.
For Market Incumbents: Anchor market position through parallel Thailand FDA and Singapore HSA certification investments that small competitors cannot replicate. Expand automated cold storage capacity in Bangkok's Eastern Economic Corridor to capture vaccine distribution volume. Biologics manufacturer vendor consolidation from twelve to four preferred partners threatens mid-tier operators lacking multi-jurisdiction licensing. For New Entrants and Emerging Players: Begin with Cambodia and Laos agricultural corridors where cold storage density remains underdeveloped and first-mover pre-cooling infrastructure near harvest zones commands premium positioning. Target Mekong Delta seafood processors seeking EU-Japan certification alignment through Vietnam's Ministry of Agriculture decentralized programs. Partner with established Thai or Malaysian operators for cross-border pharmaceutical compliance documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction GDP certification scarcity separates scalable regional networks from fragmented local operators. Five-to-ten year viability favors integrated pharmaceutical specialists with automated warehouse robotics and redundant sensor networks. Target acquisition profile encompasses mid-sized Thai or Vietnamese operators with Eastern Economic Corridor or Mekong Delta geographic density lacking certification breadth. Monitor biologics manufacturer vendor count reduction as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction GDP Certification Investment | Thailand FDA, Singapore HSA, and Vietnam Ministry of Health parallel licensing unlocks biologics manufacturer procurement consolidation. |
| Warehouse Automation Scale-Up | Robotics deployment in Bangkok Eastern Economic Corridor zones captures Thailand Board of Investment tax holiday benefits. |
| Phase-Change Material Fleet Retrofit | Paraffin-based thermal buffering reduces diesel consumption for Penang and Songkhla port seafood exporters on Middle East routes. |
| IoT-Predictive Maintenance Integration | Real-time sensor networks with machine learning algorithms prevent refrigeration unit failures before cargo spoilage occurs. |
| Cross-Border Compliance Infrastructure | Blockchain-verified temperature documentation systems satisfy Thailand FDA four-hour regulatory access mandates. |
Study Parameters
Direct dialogue with cold chain operations directors, pharmaceutical logistics procurement managers, Thailand FDA regulatory affairs officers, and Vietnam Ministry of Agriculture certification inspectors grounded qualitative findings. Secondary validation drew from ASEAN customs trade databases, refrigerated transport fleet registration records, pharmaceutical distribution licensing registries, and Board of Investment incentive disclosure filings. Bottom-up service provider capacity assessments triangulated against top-down end-user demand segmentation across food, pharmaceutical, and electronics verticals.
Bottom-up modeling aggregated individual country-level cold storage capacity and refrigerated fleet counts by technology tier and certification status. Top-down verification cross-checked against pharmaceutical distribution value flows and agricultural export volumes through Laem Chabang, Penang, and Mekong Delta corridors. Segmentation dimensions encompassed service type, technology layer, end-user industry, and distribution channel complexity. CAGRs derived from historical capacity expansion rates and regulatory mandate implementation timelines. Forecast inputs incorporated diesel price trajectory assumptions and IoT sensor network adoption curves.
Several conditions sit outside the modeled scope, including abrupt ASEAN customs harmonization breakthroughs, domestic reefer chassis manufacturing emergence, and pandemic-scale vaccine distribution surge events. Forecasts reflect base-case assumptions regarding regulatory enforcement continuity and fuel price band stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
Romania Road Freight Transport Market