
 United States Customs Brokerage Market | 2026-2036
United States Customs Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Customs Brokerage Market Analytics
Expedited clearance tier certification is unwinding competitive dynamics among established providers. C.H. Robinson leverages its digital freight platform to automate tariff classification across high-volume SKUs. Expeditors International sustains premium positioning through captive customs brokerage integrated with its forwarding network. FedEx Logistics anchors volume leadership by embedding brokerage within its last-mile delivery infrastructure.
United States customs brokerage encompasses licensed intermediary services that manage tariff classification, duty calculation, and regulatory filing on behalf of importers and exporters, operating under strict bonding requirements and power-of-attorney frameworks. The practice demands real-time harmonized system code accuracy, country-of-origin verification, and continuous regulatory monitoring to prevent port delays and penalty exposure. Service type segmentation shows customs clearance commanding the largest revenue pool while automated delivery models represent the fastest expansion vector. Client type dynamics reveal freight forwarders as the most concentrated demand channel, though direct manufacturer relationships yield superior margin retention. Industry vertical segmentation demonstrates e-commerce outpacing traditional retail in brokerage volume growth.
CBP's Section 321 enforcement modernization, FDA's foreign supplier verification programs, and EPA's import compliance mandates collectively elevate documentation precision requirements. These frameworks compel brokers to invest in classification databases and audit trails that preempt shipment holds. Stakeholders must weigh technology infrastructure commitments against the compliance cost burden that smaller importers increasingly cannot absorb internally.
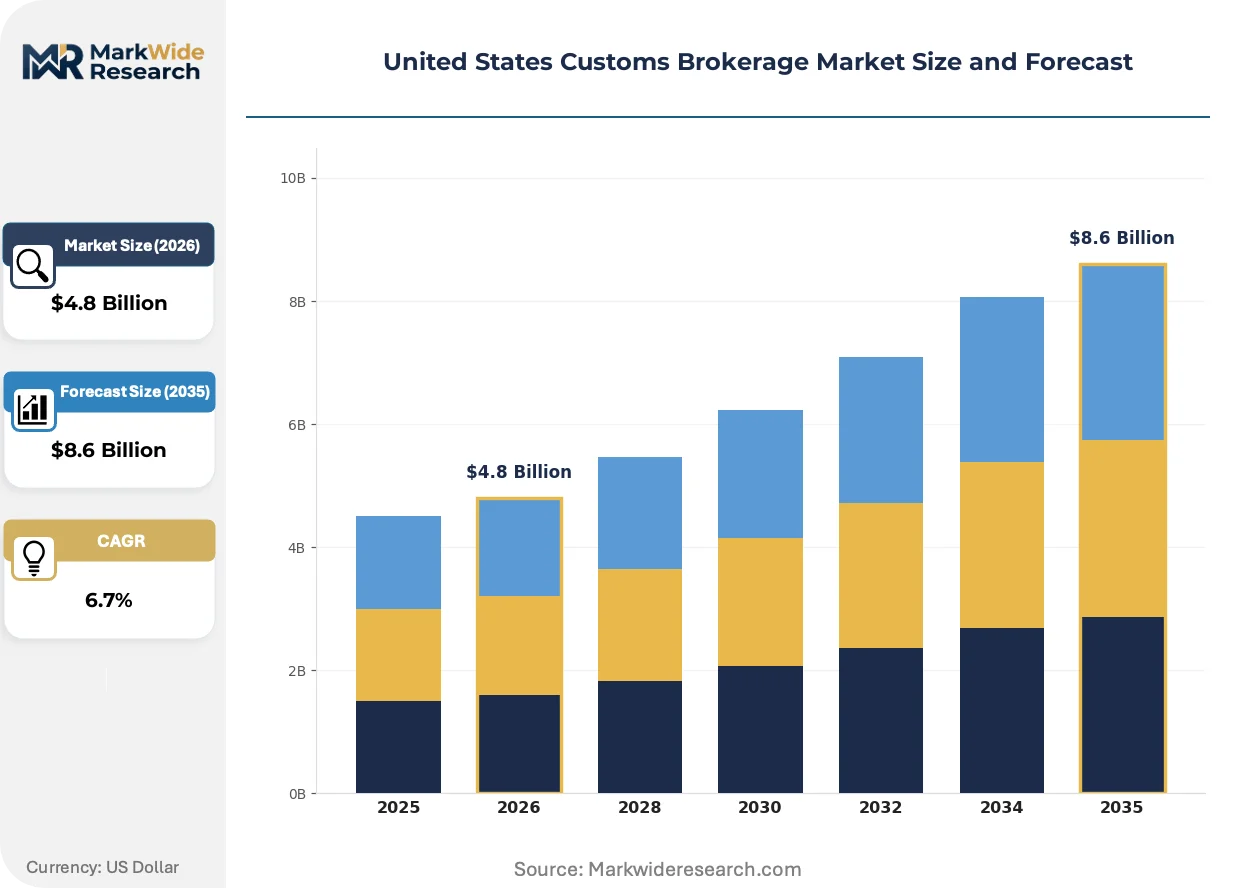
Market Dynamics
Post-de minimis enforcement is compressing clearance timelines for low-value e-commerce shipments, forcing importers to externalize compliance functions previously managed in-house. The FDA and CBP's synchronized scrutiny on Section 321 entries is restructuring how brokerage capacity distributes across port corridors.
Growth Catalysts
- E-commerce import surge:Direct-to-consumer retailers are flooding California and Texas ports with fragmented SKU volumes that demand automated tariff classification systems.
- Section 321 enforcement modernization:CBP's tightened data requirements on shipments below $800 valuation are compelling mid-market importers to retain licensed brokers rather than self-file.
- Foreign Supplier Verification Programs:FDA mandates for food and cosmetic imports are expanding broker roles beyond clearance into pre-arrival documentation auditing.
Market Restraints
- Licensed broker scarcity:The pipeline of CBP-licensed customs brokers is thinning relative to shipment volume growth, particularly in specialized FDA-regulated categories.
- Bonding cost escalation:Continuous bond minimums and single transaction bond pricing are rising, squeezing smaller freight forwarders that lack balance sheet depth.
- Harmonized System volatility:Annual tariff schedule revisions and country-of-origin rule changes force perpetual retraining investments that fixed-fee arrangements cannot absorb.
Strategic Opportunities
- Midwest manufacturing corridor expansion:Reshoring initiatives in Ohio and Michigan are creating first-mover advantages for brokers establishing inland clearance nodes away from coastal congestion.
- Environmental compliance integration:EPA import mandates on chemical substances are opening adjacent service lines where brokers bundle hazardous materials documentation with standard clearance.
- API-first platform architectures:Real-time CBP systems integration is enabling subscription-based brokerage models that displace per-shipment pricing for high-volume importers.
Industry Challenges
- Harmonized System code expertise gaps:Accurate classification of evolving product categories—particularly electronics and composite materials—requires specialized knowledge that training programs struggle to replenish.
- Legacy ERP integration friction:Brokerage management systems must interface with importer inventory platforms that span decades of technical debt, delaying automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Customs Brokerage Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customs Clearance, Regulatory Compliance, Consultancy, Documentation Client Type: Importers, Exporters, Freight Forwarders, Manufacturers Delivery Model: Online Platforms, In-Person Services, Hybrid Solutions, Automated Systems Industry Vertical: E-Commerce, Retail, Manufacturing, Automotive |
| Companies Covered | FedEx Logistics, UPS Supply Chain Solutions, Expeditors International, C.H. Robinson, Livingston International, A.N. Deringer, Kuehne+Nagel, BDP International, DHL Global Forwarding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Customs Brokerage Market Evolving Landscape
Automation is penetrating documentation workflows that brokers previously handled through manual review, compressing clearance timelines while elevating precision requirements. The competitive frontier is shifting toward predictive compliance rather than reactive exception management.
Machine learning classification engines are miniaturizing the expertise once concentrated in senior broker teams, enabling real-time harmonized system code suggestions across millions of SKUs. E-commerce platforms and direct importers are deploying these tools at enterprise scale. This capability compression is flattening the premium that traditional brokers commanded for complex classification work.
FDA's foreign supplier verification program enforcement is tightening pre-arrival documentation standards for food and cosmetic imports, extending broker liability upstream into supplier qualification. The industrial consequence is mandatory audit trail architectures that integrate with CBP's Automated Commercial Environment. Small and mid-sized importers in the beauty and nutritional supplement verticals are absorbing the steepest compliance cost increases.
Shipper procurement patterns are consolidating around integrated forwarding-brokerage bundles that eliminate multi-vendor coordination overhead. Direct manufacturer relationships are displacing freight forwarder intermediation for high-volume accounts seeking margin retention. This channel compression is most visible among California-based electronics importers managing complex Asia-Pacific supply chains.
United States Customs Brokerage Market Segmentation
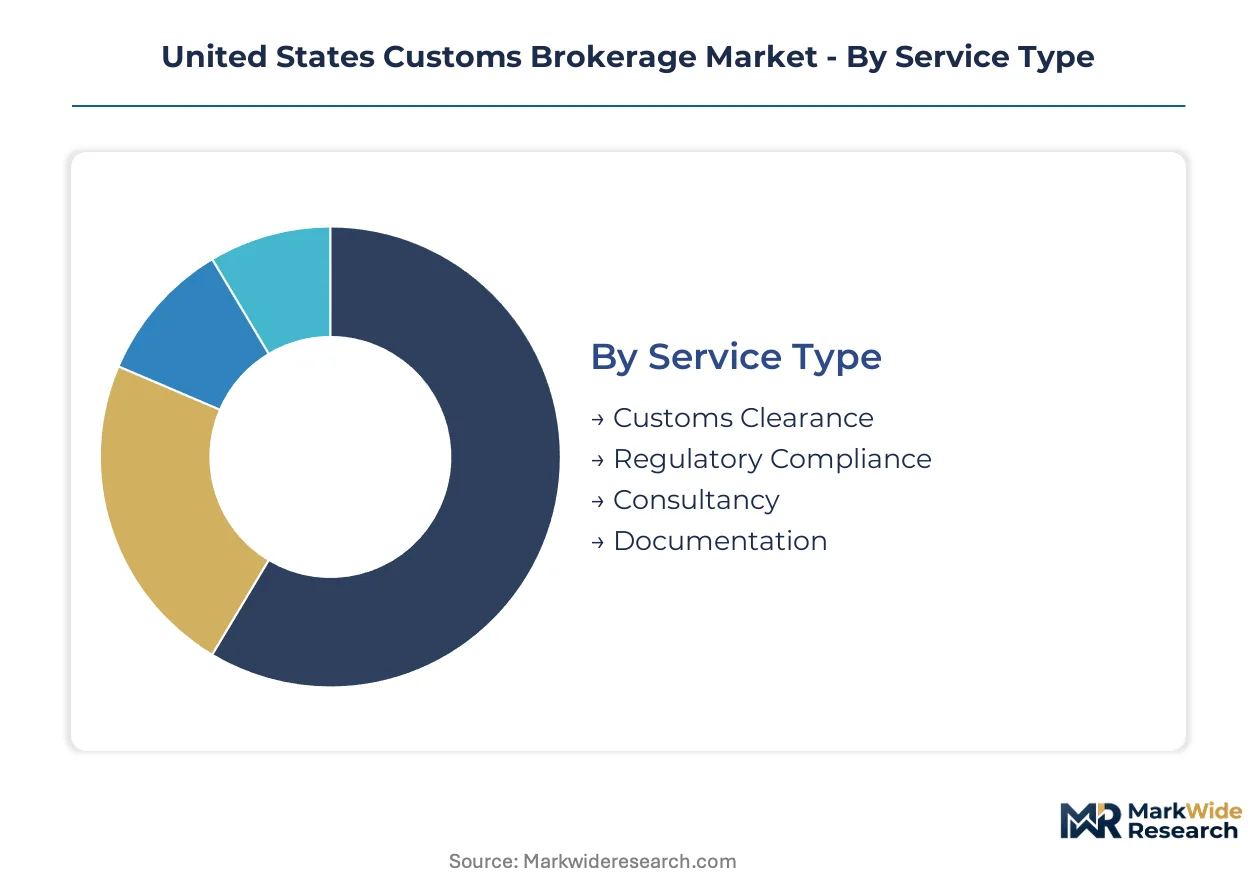
Segmentation in United States customs brokerage reveals how service delivery, client relationships, and technology deployment interlock. Each dimension exposes distinct margin structures and automation readiness that shape competitive positioning.
Service Type:
Domestic import clearance dominates volume, while export-facing and advisory services concentrate in coastal advisory hubs serving multinational accounts.
- Customs Clearance:Core filing and release management for CBP entry processing. California and Texas port corridors absorb the heaviest volume as e-commerce fragmentation strains traditional capacity.
- Regulatory Compliance:FDA, EPA, and USDA pre-arrival documentation auditing. Demand concentrates among food, cosmetic, and chemical importers facing tightened foreign supplier verification mandates.
- Consultancy:Advisory on tariff engineering and origin determination. High-value engagements cluster around footwear and electronics manufacturers navigating annual harmonized system revisions.
- Documentation:Certificate of origin, commercial invoice, and packing list preparation. Smaller freight forwarders outsource this function to manage bonding cost pressures.
Customs clearance commands the established base. The steepest expansion runs through regulatory compliance as FDA and EPA mandates deepen broker liability upstream.
Client Type:
Cost tier stratification separates enterprise accounts with captive brokerage relationships from mid-market players seeking variable-cost alternatives.
- Freight Forwarders:Intermediary channel aggregating fragmented shipper demand. Forwarders in Los Angeles and Miami corridors face margin compression as direct manufacturer relationships displace their brokerage sourcing.
- Importers:Direct retailers and distributors managing their own clearance. E-commerce direct-to-consumer brands in California are externalizing compliance functions previously managed in-house.
- Manufacturers:Industrial producers with integrated supply chain control. Reshoring initiatives in Ohio and Michigan are creating first-mover opportunities for inland brokerage nodes.
- Exporters:Domestic producers seeking destination-country clearance support. Volume concentrates among agricultural and automotive shipments to Canada and Mexico.
Freight forwarders retain the volume anchor. Manufacturers are gaining share fastest as direct relationships displace intermediary channels.
Delivery Model:
Application maturity separates legacy in-person services from API-first architectures reshaping high-volume account procurement.
- Automated Systems:Machine learning classification engines and real-time CBP integration. E-commerce platforms deploy these at enterprise scale across millions of SKUs.
- Hybrid Solutions:Blended digital and human review for complex entries. Mid-market importers favor this model for FDA-regulated shipments requiring exception handling.
- Online Platforms:Self-service portals for standard documentation and tracking. Smaller importers adopt these to manage fixed-cost compliance burdens.
- In-Person Services:Traditional broker-client relationships with physical document handling. Retains importance for high-value automotive and aerospace shipments requiring white-glove coordination.
In-person services hold the legacy installed base. Automated systems are climbing the fastest as real-time integration enables subscription pricing displacement.
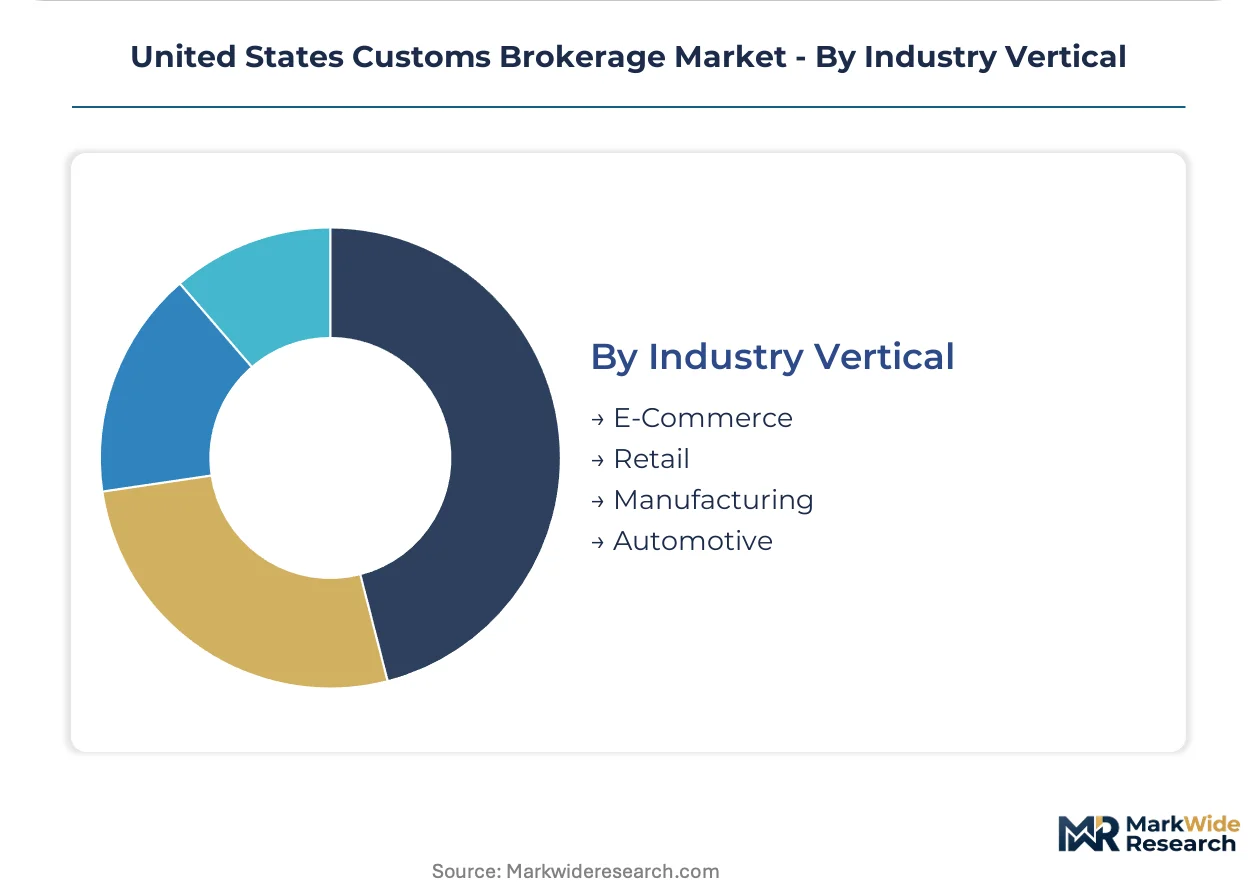
Industry Vertical:
Supply concentration aligns with port geography, with e-commerce and retail clustering in California while manufacturing and automotive distribute across inland corridors.
- E-Commerce:Direct-to-consumer import volumes with fragmented SKU profiles. California-based electronics and apparel importers drive demand for automated classification at scale.
- Manufacturing:Industrial input and capital equipment clearance. Midwest reshoring corridors in Michigan and Ohio are expanding broker presence away from coastal congestion.
- Retail:Traditional brick-and-mortar import programs with seasonal concentration. Department store chains maintain established broker relationships for predictable clearance windows.
- Automotive:Just-in-time parts and finished vehicle entry processing. Texas and Michigan corridors specialize in OEM supply chain integration with expedited release protocols.
Retail maintains the incumbent revenue position. E-commerce is expanding most quickly as post-de minimis enforcement compresses clearance timelines for low-value shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brokerage capacity clusters along coastal port corridors where e-commerce fragmentation strains traditional clearance infrastructure. California and Texas absorb the heaviest shipment volumes, while inland manufacturing hubs emerge as alternative nodes. Regional specialization reflects distinct regulatory enforcement patterns and industrial customer bases.
California
Los Angeles and Long Beach port complexes process the nation's highest customs entry volumes, driven by direct-to-consumer electronics and apparel imports. FDA's foreign supplier verification program enforcement concentrates here, compelling brokers to maintain dedicated food and cosmetic compliance teams. Silicon Valley e-commerce platforms deploy automated classification engines at enterprise scale across millions of fragmented SKUs.
Texas
Houston and Laredo corridors specialize in automotive just-in-time parts and energy sector equipment requiring expedited release protocols. CBP's Section 321 modernization tightens data requirements on cross-border e-commerce shipments entering through El Paso and Brownsville. Dallas-Fort Worth anchors inland distribution networks serving reshoring manufacturers relocating from coastal congestion.
New York-New Jersey
The Port of New York and New Jersey handles diversified consumer goods and pharmaceutical imports with stringent FDA documentation requirements. EPA import mandates on chemical substances drive demand for bundled hazardous materials clearance services. Brooklyn and Newark logistics clusters attract mid-market freight forwarders seeking alternatives to saturated West Coast capacity.
Illinois
Chicago's inland port infrastructure supports Midwest manufacturing reshoring initiatives in automotive and industrial machinery. CBP's centralized examination station network here reduces dwell times for Ohio and Michigan supply chains. O'Hare cargo terminals process high-value electronics requiring white-glove brokerage coordination with aerospace manufacturers.
Florida
Miami serves as the primary entry point for Latin American perishables and luxury goods subject to USDA and FDA parallel inspection regimes. Port Everglades and Jacksonville attract cruise line supply chains and yacht manufacturing components needing specialized clearance. Tampa and Orlando corridors expand for Central American textile imports facing tightened country-of-origin verification.
United States Customs Brokerage Market Competitive Landscape
Concentration sits with integrated logistics conglomerates that embed brokerage within broader forwarding and delivery infrastructure. The market structure shows tiered differentiation between premium service providers and volume-driven platforms. Two strategic archetypes dominate: captive brokerage networks owned by express carriers, and independent specialists competing on regulatory expertise. Competitive moves center on API-first platform architectures and geographic expansion into inland manufacturing corridors.
Within the integrated logistics tier, FedEx Logistics, UPS Supply Chain Solutions, and Expeditors International exemplify distinct positioning approaches. FedEx Logistics anchors volume leadership through embedded brokerage within last-mile delivery infrastructure. UPS Supply Chain Solutions occupies a position bridging express networks with customs compliance automation. Expeditors International represents premium positioning through captive brokerage integrated with forwarding operations. These three entities collectively demonstrate how scale and specialization create defensible competitive positions.
| Leading Market Players |
|---|
| FedEx Logistics |
| UPS Supply Chain Solutions |
| Expeditors International |
| C.H. Robinson |
| Livingston International |
| A.N. Deringer |
| Kuehne+Nagel |
| BDP International |
| DHL Global Forwarding |
| Others |
Value Network & Pricing Analysis
API-first platform architectures replacing legacy per-shipment pricing are redistributing brokerage capacity toward inland manufacturing corridors while compressing margins for traditional port-based providers dependent on transactional fee structures.
Pricing Analysis
CBP's Section 321 enforcement modernization dictates the pricing tier structure across the customs brokerage landscape. Three-tier pricing structure across premium, standard, and economy levels separates expedited clearance with dedicated account management from automated self-service portals. Price differentiation rests on certification grade for FDA-regulated categories and volume scale for e-commerce platform integrations. Cost compression in the standard tier is intensifying because machine learning classification engines miniaturize expertise once concentrated in senior broker teams. Mid-market freight forwarders exhibit the highest price sensitivity due to bonding cost escalation, while multinational manufacturers with captive brokerage relationships demonstrate the least.
Supply Chain Analysis
China and Vietnam anchor apparel and electronics manufacturing feeding California and Texas port corridors. Raw material dependencies span semiconductor components, textile inputs, and lithium-ion battery cells. Single-source vulnerability concentrates in harmonized system code expertise for evolving product categories. Distribution runs through integrated forwarding-brokerage bundles that eliminate multi-vendor coordination overhead for high-volume importers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
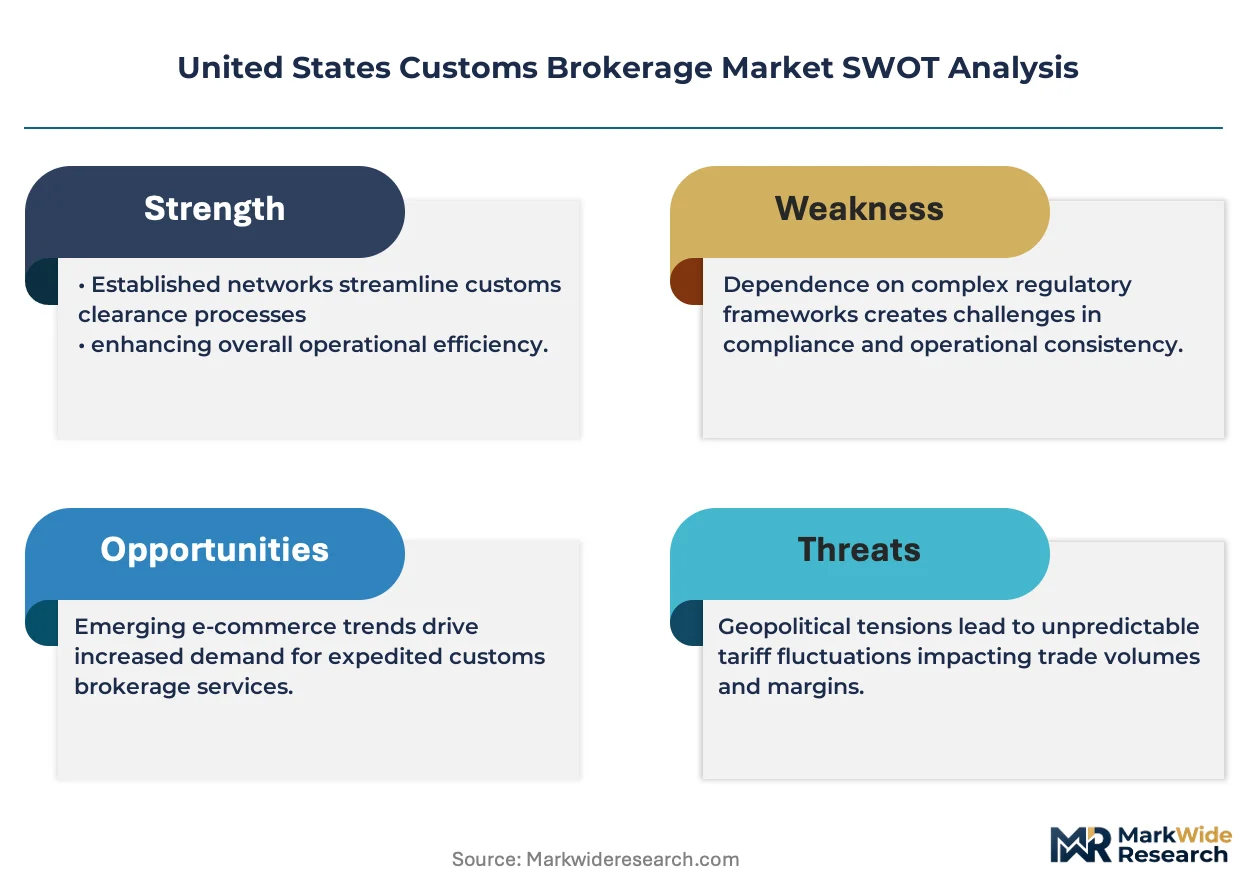
Incumbent customs brokers face substitution pressure from automated classification engines that flatten premiums for complex tariff work previously protected by specialized knowledge scarcity.
For Market Incumbents: Secure captive relationships with reshoring manufacturers in Ohio and Michigan by establishing inland clearance nodes away from coastal congestion. Deepen vertical integration into regulatory compliance auditing to preempt FDA foreign supplier verification program mandates from disintermediating broker roles. Machine learning classification tools represent the core substitution threat requiring proprietary data asset development. For New Entrants and Emerging Players: CTPAT certification fast-track enables brokerage positioning for mid-market e-commerce importers externalizing compliance functions previously managed in-house. Target the beauty and nutritional supplement verticals absorbing the steepest compliance cost increases from tightened documentation standards. Deploy subscription-based API-first architectures to displace per-shipment pricing for high-volume accounts seeking margin retention. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed freight forwarders in Los Angeles and Miami corridors facing margin compression from direct manufacturer relationship displacement. Long-term viability hinges on technology infrastructure commitments that smaller competitors cannot absorb internally. Watch for CBP bond minimum adjustments as an inflection indicator for balance sheet pressure on sub-scale providers.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Real-time CBP integration enables subscription pricing displacement for high-volume importers. |
| Inland Clearance Node Expansion | Midwest reshoring corridors in Ohio and Michigan create first-mover positioning advantages. |
| FDA Compliance Integration | Pre-arrival documentation auditing bundles extend broker liability upstream into supplier qualification. |
| Machine Learning Classification Investment | Automated harmonized system code suggestions compress clearance timelines across fragmented SKU volumes. |
| Continuous Bond Capacity Scaling | Balance sheet depth separates tier-one providers from freight forwarders facing bonding cost escalation. |
Research Methodology
Operator-level perspectives from licensed customs brokers, freight forwarder operations directors, e-commerce supply chain managers, and CBP regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through CBP enforcement bulletins, FDA foreign supplier verification program guidance, EPA import compliance mandates, and trade customs data. Bottom-up shipment volume modeling triangulated against top-down market sizing across service type, client type, delivery model, and industry vertical segmentation dimensions.
Sensitivity analysis tested forecast outputs against regulatory enforcement intensity variations and technology adoption curve assumptions across the analysis window. Segmentation dimensions modeled include service delivery tier, client relationship structure, automation readiness, and geographic port corridor concentration. CAGRs derived from shipment volume trajectories, bonding cost inflation patterns, and e-commerce import fragmentation trends. Forecast inputs incorporated CBP Section 321 modernization timelines and FDA pre-arrival documentation standard evolution.
Underlying assumptions cover regulatory enforcement continuity and technology platform migration rates, with deviation risk concentrated in harmonized system schedule volatility and licensed broker pipeline constraints. Forecasts reflect these documented conditions with acknowledged sensitivity to CBP policy shifts. Recalibration cycles align with material shifts in de minimis enforcement thresholds and foreign supplier verification program expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Latin America Inland Waterway Transport Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Multimodal Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
US Tolling Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
FMCG Logistics Market